
 Global Orange Market | 2026-2036
Global Orange Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orange Market Outlook
GlobalGAP certification is unwinding competitive access for smaller growers who cannot absorb audit costs. Citrosuco leverages its São Paulo crushing capacity to anchor global not-from-concentrate supply chains. Wonderful Citrus LLC controls branded fresh orange shelf space across US retail channels. Sucocitrico Cutrale Ltd. dominates Brazilian concentrate exports through vertically integrated grove-to-port operations.
Oranges constitute the fruit of Citrus sinensis, a hesperidium characterized by leathery flavedo, segmented juice vesicles containing citric acid and ascorbic acid, and commercial propagation via budded rootstock. Fresh oranges retain the largest value pool in retail channels, though orange concentrate sustains higher volume throughput in industrial procurement. Online retailers represent the fastest-growing distribution channel, while Tetra Paks displace glass bottles in juice packaging due to logistics efficiency and shelf stability.
EU REACH and F-Gas Regulation constrain post-harvest chemical treatments and refrigeration systems across European import corridors. FDA and USDA grading standards govern US market access, with phytosanitary protocols tightening under APHIS oversight. Stakeholders must monitor divergence between EU Green Deal agricultural targets and Mercosur trade negotiation outcomes to calibrate long-term sourcing geography.
Market Dynamics
EU F-Gas Regulation phase-down mandates are forcing cold-chain equipment replacement across citrus transport corridors, while Brazilian concentrate processors expand crushing capacity to capture NFC juice demand from European retailers.
Growth Catalysts
- Not-from-concentrate juice preference:European retail buyers are redirecting procurement toward NFC products, pulling Brazilian processors to reconfigure extraction lines and cold-press infrastructure.
- REACH compliance as market access filter:Post-harvest chemical treatments approved under EU REACH protocols now determine which export corridors remain viable for non-EU growers.
- Tetra Pak logistics efficiency:Shelf-stable aseptic packaging is displacing glass bottles in juice distribution, cutting freight costs and breakage rates for long-haul supply chains.
Market Restraints
- Input cost volatility in refrigeration gases:HFC phase-down timelines under EU F-Gas Regulation are compressing equipment replacement cycles and raising cold-chain capex for transport operators.
- São Paulo supply concentration:Brazilian grove-to-port infrastructure dominance creates single-point vulnerability for global concentrate volume, with frost and citrus greening disease risks concentrated in this corridor.
- Fresh segment perishability ceiling:The biological shelf-life of unprocessed oranges imposes hard limits on geographic reach for fresh retail channels, constraining premium capture outside production zones.
Strategic Opportunities
- Indian retail modernization:Organized grocery expansion and cold-chain infrastructure buildout in India creates underpenetrated demand for imported fresh oranges and premium juice concentrates.
- EU Green Deal agricultural targets:Carbon footprint disclosure requirements and sustainable sourcing mandates are creating preference premiums for certified low-emission citrus supply chains.
- Online direct-to-consumer channels:E-commerce fulfillment networks are enabling subscription-based fresh orange and juice delivery models that bypass traditional wholesale distribution markups.
Industry Challenges
- GlobalGAP audit cost absorption:Smaller growers face exclusion from premium retail channels as certification compliance costs escalate beyond their balance-sheet capacity.
- APHIS phytosanitary timeline compression:USDA inspection and clearance protocols for imported citrus are tightening, extending port dwell times and complicating just-in-time delivery commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orange Market |
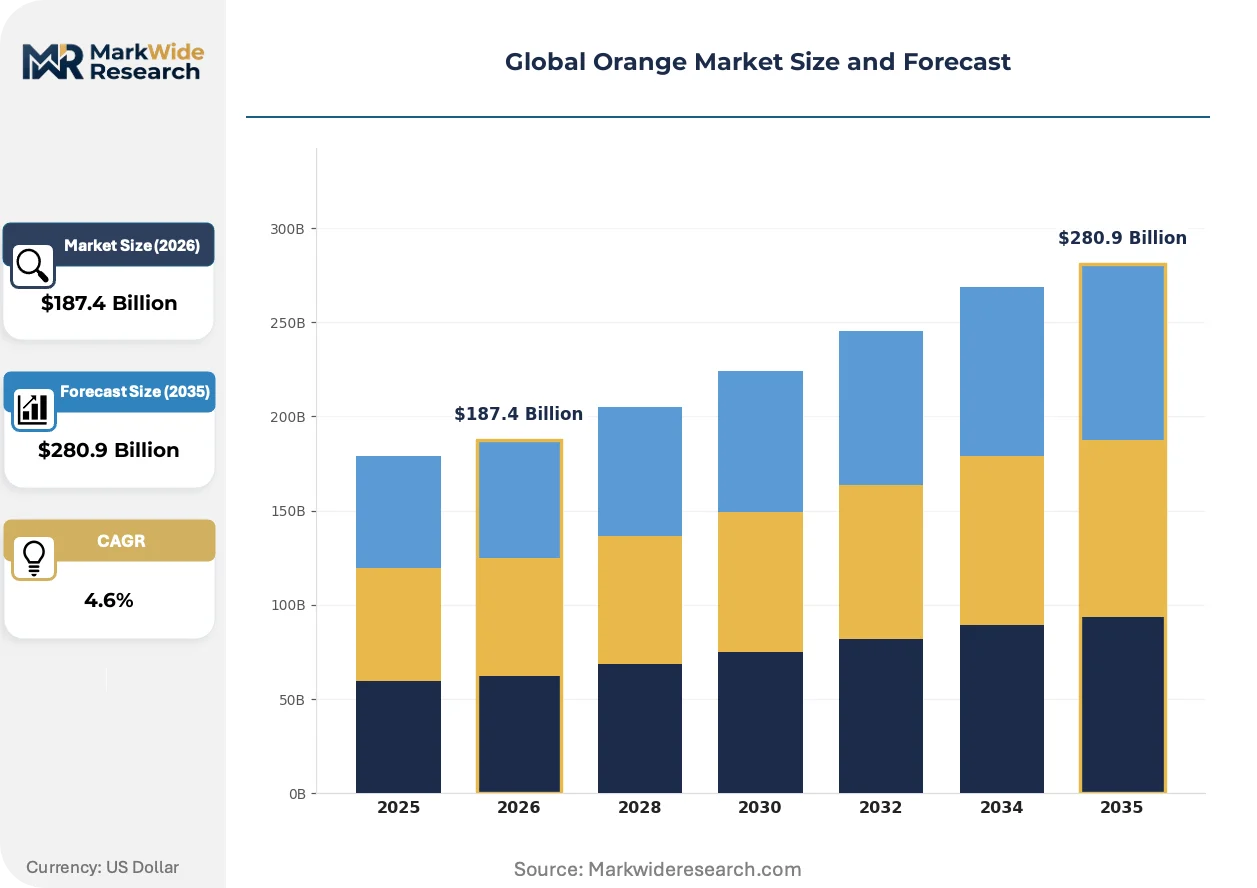
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $280.9 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Oranges, Dried Oranges, Orange Juice, Orange Concentrate Distribution Channel: Supermarkets, Online Retailers, Wholesalers, Farmers Markets End Use: Household, Food Industry, Beverage, Personal Care Packaging Type: Plastic Bags, Cardboard Boxes, Glass Bottles, Tetra Paks |
| Companies Covered | Citrosuco, Sunkist Growers Inc., Wonderful Citrus LLC, Citrus World Inc., Sucocitrico Cutrale Ltd., Dole Food Company Inc., Fresh Del Monte Produce Inc., Sun Pacific Inc., Berje Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orange Market Strategic Shifts
Processing technology and packaging formats are splitting the orange market into divergent supply chains optimized for either fresh retail immediacy or industrial concentrate scale.
High-pressure processing for NFC juice is bifurcating the premium juice segment from heat-pasteurized commodity volumes. Cold-press extraction lines at Brazilian facilities are scaling output to serve European supermarket private-label programs. This thermal-nonthermal divide is compressing margins for mid-tier pasteurized products while creating parallel certification and cold-chain requirements.
EU F-Gas Regulation mandates are accelerating HFC refrigerant replacement in citrus transport containers and storage facilities. Equipment retrofits and new unit purchases are absorbing capital that might otherwise expand processing capacity. Brazilian exporters and Spanish distributors are most exposed, as their Atlantic crossing routes require extended refrigeration cycles.
Retail buyers are consolidating procurement decisions into centralized category-management functions, displacing fragmented regional purchasing. Major European supermarket chains now specify sustainability credentials and origin traceability as mandatory bid criteria. This concentration is most visible in Germany and the Netherlands, where buying cooperatives command volume leverage over Brazilian and Spanish suppliers.
Global Orange Market Segmentation
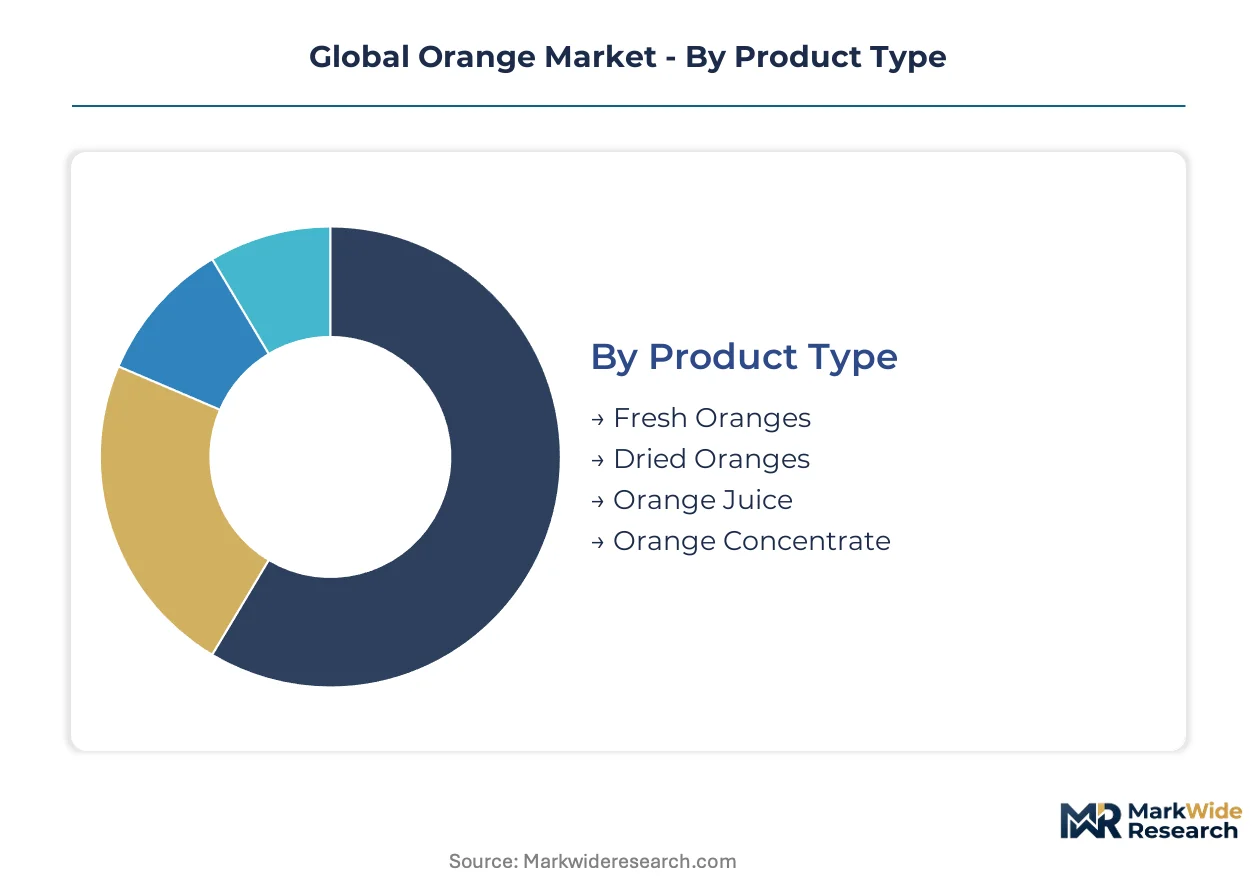
Orange market segmentation reveals divergent regulatory and logistical requirements across product formats. Fresh fruit faces phytosanitary complexity while processed products navigate packaging sustainability mandates. Each segment demands distinct cold-chain infrastructure and certification protocols.
Product Type:
EU REACH and FDA grading standards create divergent compliance burdens across processed versus unprocessed formats, with concentrate exports facing additive disclosure requirements that fresh whole fruit avoids.
- Fresh Oranges:Whole Citrus sinensis fruit sold in flavedo-intact form requires controlled-atmosphere transport and USDA APHIS phytosanitary clearance for US entry. Brazilian São Paulo groves and Spanish Valencia corridors dominate procurement for European retail, with frost risk and citrus greening disease constraining supply reliability.
- Orange Juice:Extracted and pasteurized liquid product splits between not-from-concentrate premium tiers and reconstituted commodity volumes. European supermarket private-label programs are pulling Brazilian processors toward cold-press extraction infrastructure, with NFC preference climbing fastest in Germany and Netherlands buying cooperatives.
- Dried Oranges:Dehydrated slice and peel segments for culinary and decorative applications.
- Orange Concentrate:Evaporated soluble solids for industrial beverage formulation and reconstitution.
Established volume favors Orange Concentrate; emerging adoption favors Orange Juice.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain infrastructure from low-touch direct sales, with compliance overhead determining viable participation.
- Supermarkets:Centralized category management functions now mandate GlobalGAP certification and origin traceability as bid prerequisites. German and Dutch retail cooperatives leverage consolidated procurement to extract sustainability credentials from Brazilian and Spanish suppliers, squeezing margin for uncertified growers.
- Online Retailers:Direct-to-consumer fulfillment networks enable subscription-based fresh delivery models that bypass wholesale markups. This channel climbs fastest where cold-chain infrastructure gaps persist in traditional retail, particularly in Indian urban markets.
- Wholesalers:Volume aggregation for food service and industrial buyers with lower certification thresholds.
- Farmers Markets:Localized direct producer-to-consumer sales with minimal regulatory overlay.
Supermarkets command procurement consolidation; Online Retailers gain share fastest in underpenetrated cold-chain corridors.
End Use:
Application maturity separates commodity ingredient demand from emerging premium positioning in non-food categories.
- Household:Direct consumer purchase for fresh consumption and home juicing, concentrated in retail channels with quality grading visibility.
- Food Industry:Ingredient supply for confectionery, bakery, and prepared foods with specification-driven procurement.
- Beverage:Industrial juice and concentrate offtake for formulation and private-label bottling.
- Personal Care:Essential oil and extract demand for cosmetics and fragrance applications, with EU REACH chemical registration requirements constraining supplier qualification.
Beverage anchors volume throughput; Personal Care expands most quickly on premium extract positioning.
Packaging Type:
Logistics efficiency and shelf stability requirements are displacing traditional formats across transport modes.
- Tetra Paks:Aseptic carton systems enable ambient distribution with extended shelf life, cutting freight cost and breakage versus glass. European retail buyers specify this format for private-label juice programs, with EU F-Gas Regulation cold-chain constraints reinforcing preference for shelf-stable alternatives.
- Plastic Bags:Lightweight flexible packaging for fresh fruit retail display and bulk handling.
- Cardboard Boxes:Standardized corrugated containment for wholesale fresh fruit movement.
- Glass Bottles:Premium positioning format for chilled juice with higher transport cost and breakage exposure.
Glass Bottles retain premium positioning; Tetra Paks gain share fastest on logistics efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down mandates are accelerating equipment replacement across cold-chain corridors, while Brazilian export tax incentives and Indian PLI scheme subsidies for food processing infrastructure reshape procurement geography.
Brazil
São Paulo state groves supply the majority of global orange concentrate volume, with Citrosuco and Sucocitrico Cutrale Ltd. operating vertically integrated grove-to-port networks. ANVISA phytosanitary protocols govern export certification, while frost risk and citrus greening disease concentrate supply vulnerability in the southeastern corridor.
United States
California and Florida groves serve fresh retail channels, with Wonderful Citrus LLC and Sunkist Growers Inc. controlling branded shelf space. FDA grading standards and USDA APHIS inspection protocols tighten port clearance timelines, while Tetra Pak adoption accelerates in private-label juice programs across retail cooperatives.
Spain
Valencia province anchors European fresh orange supply, with Citrus World Inc. and regional cooperatives supplying German and Dutch supermarket chains. EU REACH chemical registration constrains post-harvest treatment options, while F-Gas Regulation mandates force cold-chain equipment retrofits across Mediterranean export corridors.
India
Maharashtra and Telangana organized grocery expansion creates underpenetrated demand for imported fresh oranges and premium concentrates. FSSAI food safety standards and DGFT import tariff structures determine market access, while PLI scheme subsidies for cold-chain infrastructure buildout enable subscription-based direct-to-consumer delivery models in Mumbai and Hyderabad.
China
Jiangxi and Hunan provinces dominate domestic fresh consumption, with NMPA food additive regulations and GB standards governing juice import quality. MIIT cold-chain development targets and dual carbon goals accelerate HFC refrigerant phase-out in citrus transport containers, reshaping equipment procurement for Brazilian and Spanish exporters.
Global Orange Market Competitive Environment
Player mix skews toward vertically integrated grove operators and branded retail specialists. Market structure concentrates around Brazilian crush capacity and US retail channel control, with mid-tier processors facing margin compression from NFC preference shifts and certification cost escalation. Strategic archetypes include captive supply chain operators, branded fresh fruit marketers, and commodity concentrate exporters. Dominant competitive moves center on cold-press extraction infrastructure expansion and sustainability credential acquisition for EU supermarket private-label qualification.
Within the vertically integrated tier, Citrosuco and Sucocitrico Cutrale Ltd. occupy positions anchoring global not-from-concentrate and concentrate supply chains respectively. Among US-based branded marketers, Wonderful Citrus LLC exemplifies retail channel control through supermarket shelf-space dominance, while Sunkist Growers Inc. represents cooperative aggregation models for fresh fruit distribution. These three companies illustrate the geographic bifurcation between Brazilian industrial scale and US retail proximity.
| Leading Market Players |
|---|
| Citrosuco |
| Sunkist Growers Inc. |
| Wonderful Citrus LLC |
| Citrus World Inc. |
| Sucocitrico Cutrale Ltd. |
| Dole Food Company Inc. |
| Fresh Del Monte Produce Inc. |
| Sun Pacific Inc. |
| Berje Inc. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance costs gate both cold-chain equipment qualification and transport pricing tiers simultaneously, forcing exporters to absorb retrofit expenses or cede shelf-stable formats to competitors. Certification under REACH and GlobalGAP protocols creates parallel entry barriers that stratify procurement access across European retail channels.
Pricing Analysis
Certification level creates the primary spread between premium NFC juice and commodity concentrate tiers, with GlobalGAP-audited groves commanding contract premiums from German and Dutch supermarket cooperatives. Three-tier pricing structure across premium, standard, and economy levels reflects cold-press infrastructure investment, origin traceability, and shelf-stable packaging format. Cost compression in mid-tier pasteurized products is intensifying because European buyers are consolidating procurement into centralized category managers. Food service wholesalers exhibit highest price sensitivity, while private-label retail programs demonstrate lowest sensitivity due to origin-story premiums.
Supply Chain Analysis
Brazil and Spain anchor global orange supply, with São Paulo state groves feeding concentrate crushers and Valencia province corridors serving fresh retail channels. Raw material flows draw from budded rootstock propagation, citrus greening-resistant cultivars, and aseptic packaging substrates. Single-source vulnerability concentrates in Brazilian southeastern corridors where frost and disease risks threaten volume continuity. Distribution runs through vertically integrated grove-to-port networks for concentrate, and controlled-atmosphere container routes for fresh fruit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with EU REACH and F-Gas compliance timelines creating switching costs that lock in incumbent supplier relationships.
For Market Incumbents: Shield crushing capacity utilization by accelerating cold-press extraction line expansion before NFC preference hardens procurement standards. Consolidate backward integration into budded rootstock nurseries to secure cultivar supply against citrus greening disease spread. Channel control through direct supermarket cooperative relationships offers the strongest defensive lever against Spanish and Indian sourcing alternatives.
For New Entrants and Emerging Players: GlobalGAP fast-track certification programs unlock white-space access in Indian organized grocery expansion, where cold-chain infrastructure gaps persist in Mumbai and Hyderabad metro corridors. Subscription-based direct-to-consumer fulfillment models bypass wholesale markups in underpenetrated urban markets. Target sustainability credential acquisition as the primary go-to-market angle for EU Green Deal procurement mandates.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-press extraction infrastructure as Brazilian processors reconfigure lines for NFC output. Long-term viability favors vertically integrated grove operators with captive port access over toll-processing dependent competitors. Acquisition targets should display ANVISA export certification and São Paulo state grove concentration. Watch EU-Mercosur trade negotiation outcomes as the critical inflection signal for sourcing geography reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extraction Scale-Up | Brazilian processors capture NFC preference from German supermarket cooperatives. |
| GlobalGAP Certification Investment | Audited groves unlock private-label procurement from Dutch retail buying groups. |
| Backward Integration into Rootstock | Captive cultivar supply buffers against citrus greening disease vulnerability. |
| Tetra Pak Format Conversion | Shelf-stable packaging cuts freight costs for Atlantic crossing routes. |
| Direct-to-Consumer Channel Launch | Subscription models bypass wholesale markups in Indian urban corridors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs export data, EU regulatory filings, and supermarket procurement disclosures. Interviews with Brazilian crushing facility managers, Spanish cooperative export directors, German category buyers, and Indian cold-chain logistics operators informed supply structure validation. Secondary sources include ANVISA phytosanitary records, DGFT import tariff schedules, and FSSAI food safety compliance databases. Bottom-up volume modeling triangulates against top-down trade flow analysis.
Segmentation dimensions span product type, distribution channel, end use, and packaging format across the projection horizon. CAGRs derive from trend extrapolation of NFC adoption curves, cold-chain infrastructure buildout rates, and regulatory compliance cost trajectories. Industry-specific inputs incorporate citrus greening disease spread models and EU F-Gas equipment replacement timelines.
Underlying assumptions cover sustained Mercosur trade access, stable frost incidence in São Paulo state, and continued EU Green Deal enforcement, with deviation risk concentrated in phytosanitary protocol tightening and refrigerant phase-down acceleration. Recalibration cycles align with material shifts in EU-Mercosur negotiation outcomes and ANVISA export certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Dates Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market
Fruits and Vegetables
Freeze Dried Bananas Market