
 Sugared Egg Yolk Market | 2026-2036
Sugared Egg Yolk Market Size, Share, and Industry Trends Forecast 2026-2036
Sugared Egg Yolk Market Analytics
Specialized food-processing labor availability is collapsing across industrial baking corridors in Western Europe, forcing manufacturers to source pre-formulated egg ingredients rather than train in-house pasteurization teams. Rembrandt Enterprises leverages its captive flock operations across the American Midwest to sustain supply continuity for sugared yolk buyers. OVOBEST Eiprodukte GmbH & Co. KG anchors European procurement networks through its German processing base, while Michael Foods competes on liquid-yolk formulation breadth for quick-service restaurant chains.
Sugared egg yolk comprises pasteurized hen egg yolk blended with sucrose or glucose syrup, typically standardized to 40-50% sugar content and spray-dried or drum-dried into shelf-stable powder or semi-liquid concentrate for industrial food production. Powdered yolk dominates current revenue pools due to extended ambient stability and reduced cold-chain dependency, though liquid yolk formats are gaining traction among artisanal bakeries seeking cleaner-label emulsification. The application split tilts heavily toward confectionery and baking, where sugared yolk supplies Maillard-reactive proteins and natural emulsifiers that synthetic alternatives struggle to replicate at equivalent cost.
FDA oversight of egg product pasteurization under the Egg Products Inspection Act shapes US market entry requirements, while the EU's EFSA and national regulators such as Germany's BVL enforce Salmonella-negative certification for cross-border egg derivative trade. China's SAMR and GB standards for processed egg products are tightening microbial limits, redirecting export-oriented capacity toward domestic compliance investments. Stakeholders must weigh regional regulatory divergence against the operational complexity of maintaining multiple pasteurization protocols and documentation systems.
Market Dynamics
Specialized food-processing labor availability is collapsing across industrial baking corridors in Western Europe, forcing manufacturers to source pre-formulated egg ingredients rather than train in-house pasteurization teams. This structural workforce compression is redirecting procurement toward consolidated suppliers with captive flock operations and certified processing infrastructure.
Growth Catalysts
- EU Food Additives Regulation:Tightening purity thresholds for processed egg derivatives are disqualifying marginal producers and concentrating volume among certified processors with Salmonella-negative certification protocols.
- Artisanal bakery channel:Premium patisserie consumption in France anchors regional volume expansion as traditional applications resist synthetic emulsifier substitution.
- Drum-drying technology:Improved thermal processing efficiency is extending ambient stability windows for sugared yolk concentrates without cold-chain dependency.
Market Restraints
- Feed input volatility:Corn and soybean meal prices directly compress processor margins, with captive flock operators holding cost advantages over toll processors.
- Supply concentration risk:German processing infrastructure dominates EU cross-border trade, creating single-point vulnerability for continental procurement networks.
- Plant-based emulsifier substitution:Lecithin and hydrocolloid blends are capturing clean-label positioning in mass-market confectionery applications.
Strategic Opportunities
- China domestic compliance investments:SAMR tightening of GB microbial standards is redirecting export-oriented capacity toward domestic premium positioning.
- Quick-service restaurant chains:Liquid yolk formulation breadth for industrial baking applications remains underpenetrated versus powder dominance.
- Clean-label emulsification:Maillard-reactive protein positioning is supplanting synthetic additive claims in premium European patisserie marketing.
Industry Challenges
- Pasteurization protocol fragmentation:Maintaining FDA Egg Products Inspection Act compliance alongside EFSA and BVL certification creates documentation system complexity.
- In-house production capability gaps:Industrial baking corridors lack trained thermal processing specialists, forcing reliance on external pre-formulated supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugared Egg Yolk Market |
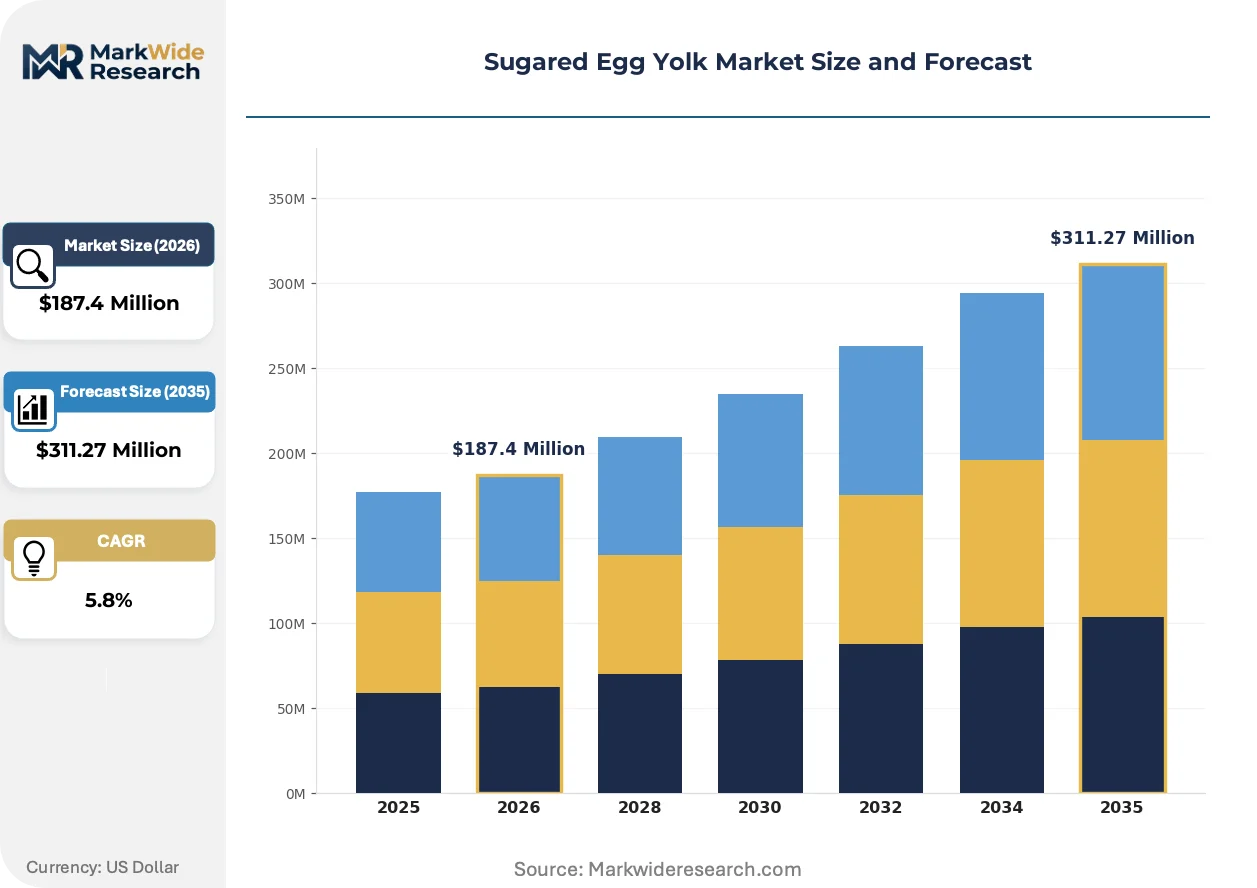
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Yolk, Liquid Yolk, Granulated Yolk, Pasteurized Yolk Application: Baking, Confectionery, Sauces, Dressings End User: Household, Bakeries, Restaurants, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Rembrandt Enterprises, SKM Best Eggs, Dalian Hanovo Foods Co., Ltd., Zeagold Foods, Frutex Australia Pty Ltd., OVOBEST Eiprodukte GmbH & Co. KG, Ballas Egg Products Corporation, Crystal Lakes LLC, Michael Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugared Egg Yolk Market Evolving Landscape
Processing technology and regulatory compliance architecture are actively reshaping competitive positioning in sugared egg yolk supply. Three developments are restructuring how value is captured across the value chain.
Low-temperature spray-drying systems with nitrogen blanketing are supplanting conventional drum-drying for high-value confectionery applications. Premium chocolate manufacturers in Belgium and Switzerland are adopting these systems to preserve volatile flavor compounds and reduce thermal degradation of lipid fractions. The technology is compressing acceptable supplier lists to processors with capital-intensive equipment footprints.
REACH chemical safety documentation requirements are extending to food-contact processing equipment and cleaning agents used in egg derivative facilities. German processors under BVL oversight are retrofitting production lines to eliminate quaternary ammonium compound residues. The confectionery segment is absorbing compliance costs through supplier qualification delays and extended audit cycles.
Bakeries are consolidating procurement relationships around full-service ingredient suppliers with integrated technical support. Industrial baking corridors in northern France are replacing spot-market egg yolk purchases with annual volume contracts bundling formulation consulting and regulatory documentation. This concentration is most visible among mid-scale patisserie chains seeking to outsource pasteurization liability while retaining product differentiation claims.
Sugared Egg Yolk Market Segmentation
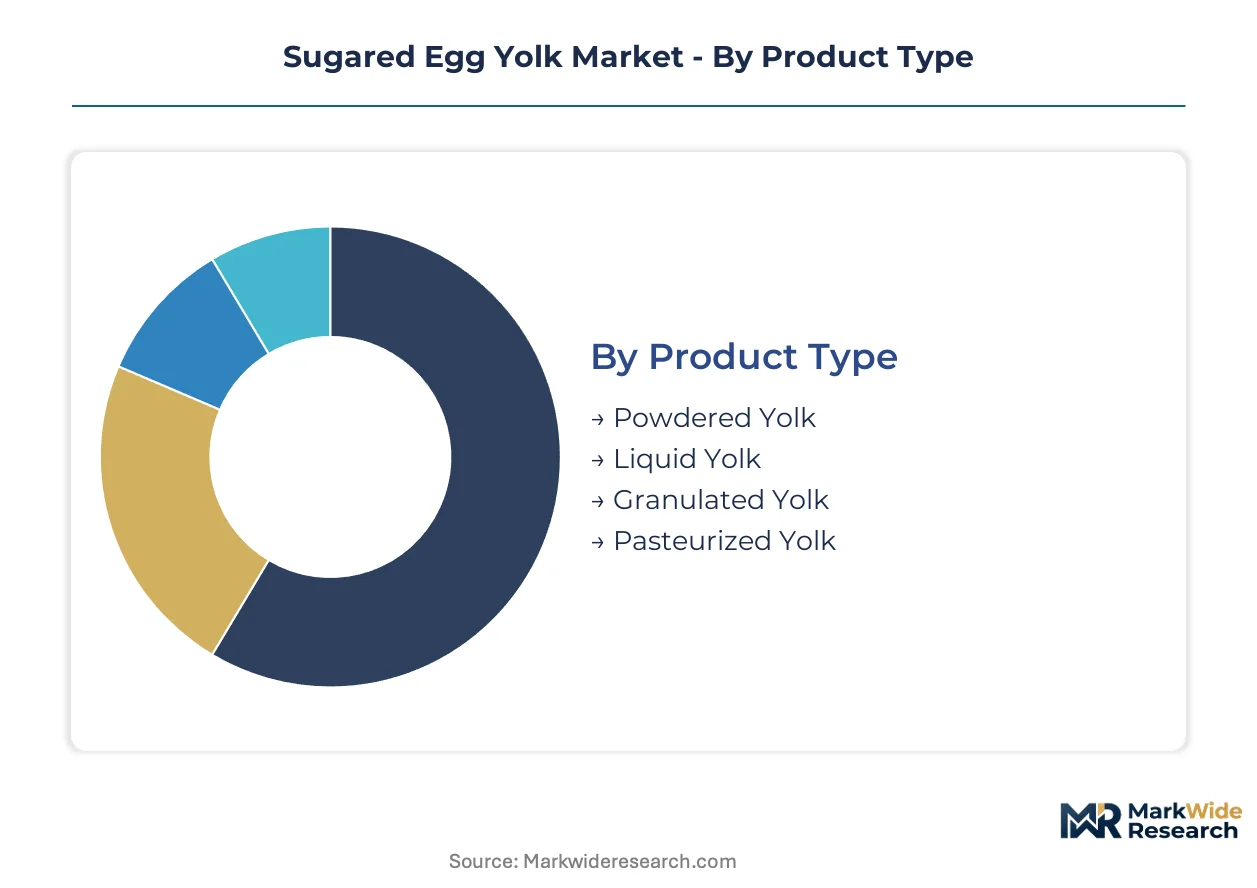
Sugared egg yolk procurement patterns diverge sharply between industrial-scale food manufacturers and artisanal end-users, with format selection, packaging requirements, and technical support needs driving fundamentally different channel economics across each segment boundary.
Product Type:
Powdered yolk flows predominantly through bulk direct sales to food manufacturers seeking extended shelf stability, while liquid formats concentrate in specialty stores serving artisanal bakeries with shorter production cycles.
- Powdered Yolk:Spray-dried or drum-dried concentrate standardized to 40-50% sucrose content delivers ambient stability exceeding 18 months without cold-chain dependency. Industrial confectionery producers in Belgium and Switzerland anchor volume demand, with nitrogen-blanketed low-temperature systems now qualifying supplier lists for premium chocolate applications.
- Liquid Yolk:Pasteurized semi-liquid concentrate requires refrigerated distribution but offers superior emulsification performance in cold-process applications. French patisserie chains are consolidating annual volume contracts around this format to outsource pasteurization liability while retaining Maillard-reactive protein claims.
- Granulated Yolk:Intermediate moisture granules dissolve faster than powder in high-shear mixing environments.
- Pasteurized Yolk:Minimal-processing variant retains native lipid structure for flavor-sensitive sauce applications.
Powdered yolk dominates installed base. Liquid yolk is where expansion concentrates.
Application:
Cost tier stratification separates commodity-scale baking from premium confectionery, with formulation consulting bundled only at the upper price bands.
- Baking:Industrial bread and pastry operations consume standardized powder for cost-efficient emulsification. Northern France's mid-scale patisserie chains are replacing spot-market purchases with technical-support contracts covering formulation optimization.
- Confectionery:Premium chocolate and praline manufacturing demands low-thermal-degradation processing to preserve volatile flavor compounds. REACH documentation requirements for food-contact equipment are extending supplier qualification cycles.
- Sauces:Mayonnaise and hollandaise bases favor liquid yolk for immediate functional performance.
- Dressings:Shelf-stable emulsified products blend powdered yolk with modified starches.
Baking commands volume share. Confectionery captures margin expansion.
End User:
Customer type determines packaging scale and regulatory documentation intensity, with food manufacturers demanding batch-level Salmonella-negative certification that household channels ignore.
- Food Manufacturers:Multi-tonne annual contracts with integrated technical support and EFSA-compliant documentation. German processing infrastructure anchors EU cross-border supply.
- Bakeries:Mid-volume procurement shifting from spot markets to annual contracts bundling formulation consulting.
- Restaurants:Small-batch liquid yolk through specialty distributors with refrigerated last-mile delivery.
- Household:Retail-format granulated products through supermarkets with minimal technical support.
Food manufacturers concentrate procurement volume. Bakeries are climbing the fastest.
Distribution Channel:
Supply concentration risk manifests in channel selection, with direct sales bypassing German processing infrastructure dependency for qualified buyers.
- Direct Sales:Annual volume contracts with captive-flock processors eliminate intermediary margins. Rembrandt Enterprises leverages Midwest flock operations for supply continuity.
- Specialty Stores:Technical consultation and smaller pack sizes for artisanal bakeries resisting synthetic emulsifier substitution.
- Supermarkets:Standardized granulated formats for household and small restaurant segments.
- Online Retail:Emerging channel for sample procurement and technical documentation access.
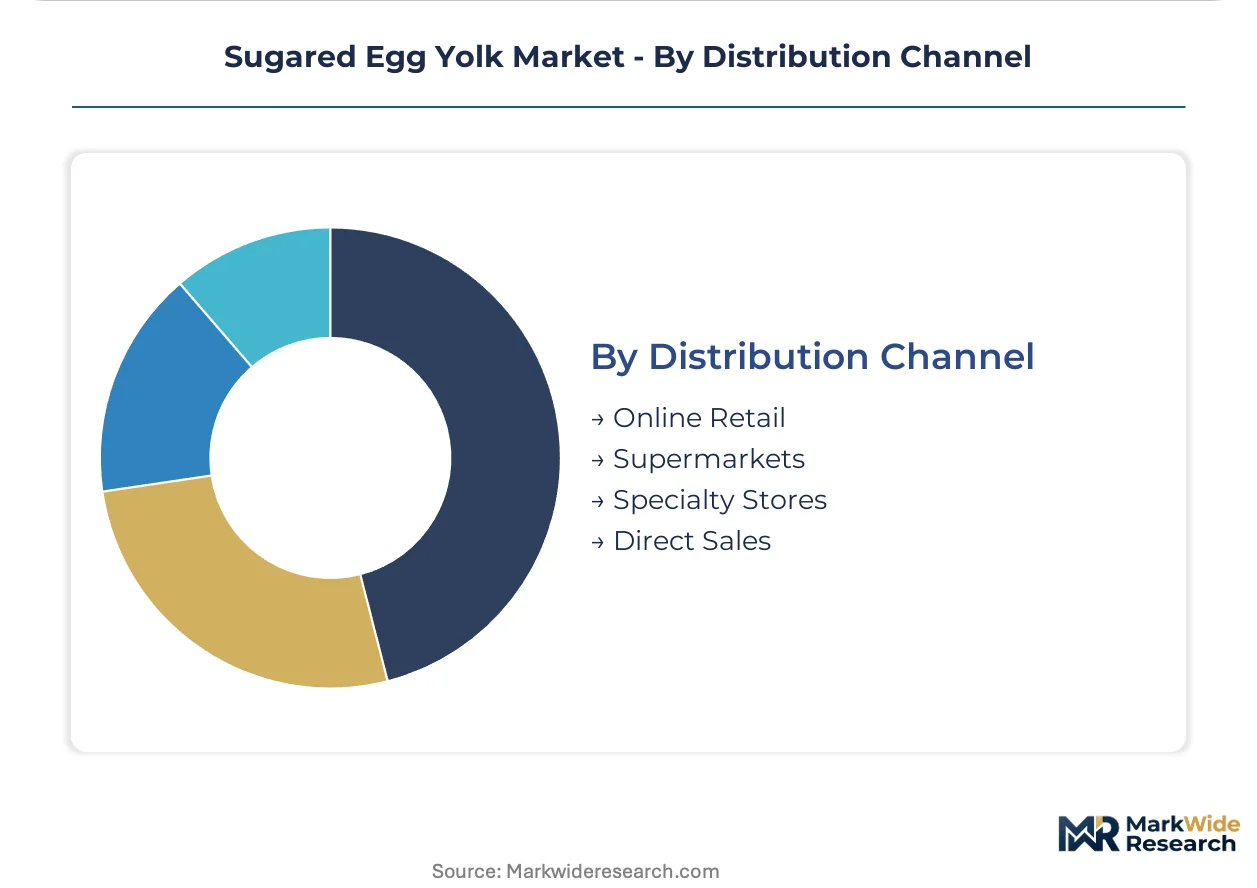
Direct sales dominate value capture. Specialty stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes sugared egg yolk predominantly through artisanal patisserie channels, while the United States and China route larger volumes through industrial food manufacturing corridors with divergent regulatory compliance burdens.
France
Traditional patisserie consumption anchors European demand, with Île-de-France and Auvergne-Rhône-Alpes hosting concentrated clusters of premium bakeries. ANSM enforces strict Salmonella-negative certification under EU Food Additives Regulation purity thresholds. Lyon-based patisserie chains are consolidating annual procurement contracts to outsource pasteurization liability.
Germany
Industrial processing infrastructure dominates cross-border supply, with BVL oversight creating certification bottlenecks for non-compliant imports. REACH documentation requirements now extend to food-contact equipment in egg derivative facilities. Lower Saxony processing plants are retrofitting production lines to eliminate quaternary ammonium compound residues.
United States
Quick-service restaurant chains drive liquid yolk formulation demand for industrial baking applications. FDA Egg Products Inspection Act pasteurization protocols shape market entry requirements for domestic and imported products. Midwest captive flock operations sustain supply continuity for sugared yolk buyers across the Great Lakes corridor.
China
Domestic compliance investments redirect export-oriented capacity toward premium positioning as SAMR tightens GB microbial standards for processed egg products. Yangtze River Delta food manufacturers are absorbing higher certification costs to access tier-one urban markets. Shanghai-based distributors are consolidating procurement relationships around full-service ingredient suppliers.
Belgium
Premium chocolate manufacturing demands low-thermal-degradation processing to preserve volatile flavor compounds in sugared yolk concentrates. EFSA cross-border certification enables seamless supply integration with French and German industrial users. Antwerp-area confectionery producers are adopting nitrogen-blanketed spray-drying systems to qualify for high-value supplier lists.
Sugared Egg Yolk Market Competitive Landscape
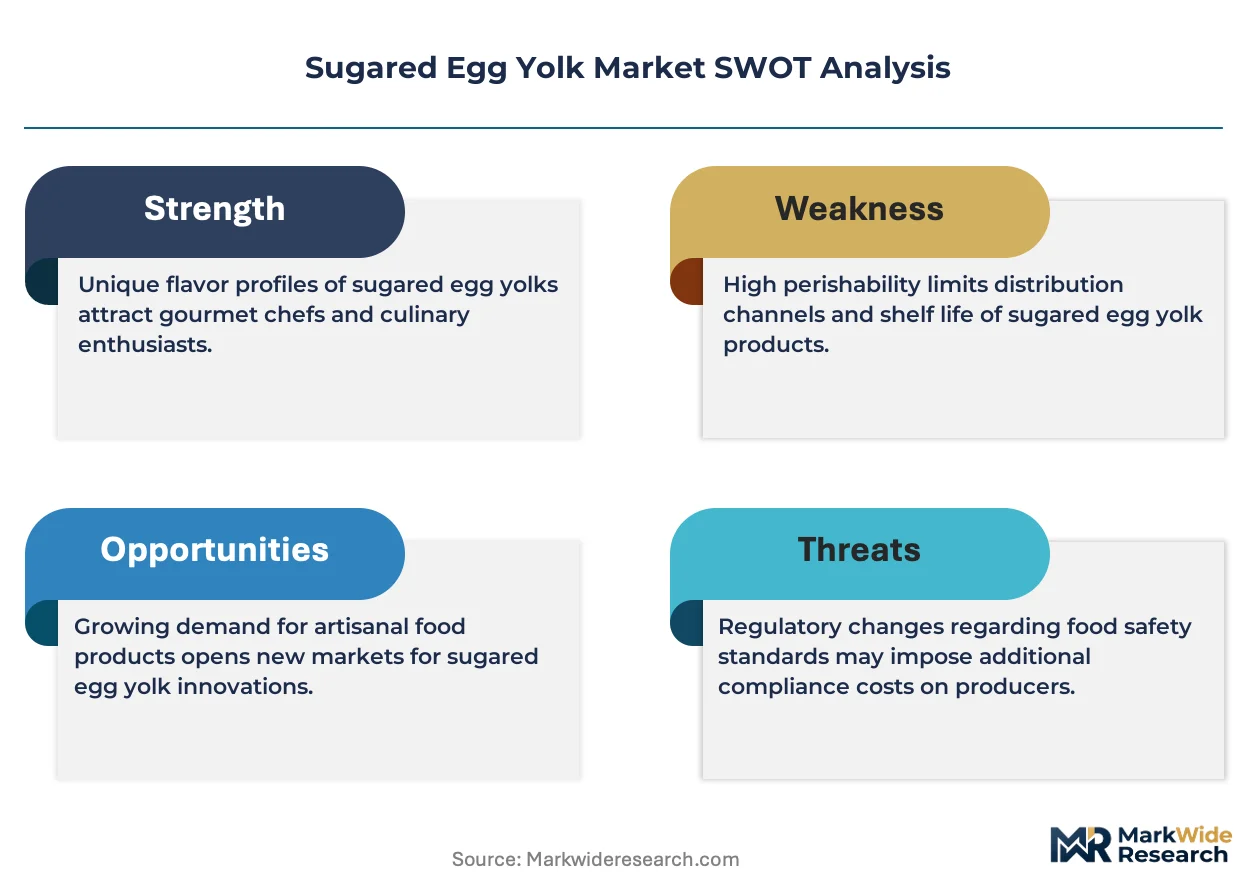
A small set of integrated leaders sits above a broader specialist tier, with captive flock operators holding cost advantages over toll processors amid feed input volatility. The structure concentrates procurement volume among certified processors with multi-regional compliance infrastructure. Three archetypes dominate: Midwest-based captive flock integrators, German processing anchors with EU cross-border networks, and liquid-yolk formulation specialists serving quick-service channels. Competitive moves center on backward integration into upstream flock control and annual volume contract bundling with technical support services.
Among captive flock integrators, Rembrandt Enterprises exemplifies the Midwest-based archetype with supply continuity advantages. German processing leadership is anchored by OVOBEST Eiprodukte GmbH & Co. KG, representing the EU certification-heavy tier. Michael Foods occupies a position on the liquid-yolk formulation vector for industrial baking applications. These three names illustrate how geographic origin and corporate structure align with divergent strategic positioning across powder versus liquid format dominance.
| Leading Market Players |
|---|
| Rembrandt Enterprises |
| SKM Best Eggs |
| Dalian Hanovo Foods Co., Ltd. |
| Zeagold Foods |
| Frutex Australia Pty Ltd. |
| OVOBEST Eiprodukte GmbH & Co. KG |
| Ballas Egg Products Corporation |
| Crystal Lakes LLC |
| Michael Foods |
| Others |
Value Network & Pricing Analysis
Plant-based lecithin substitution in mass-market confectionery is simultaneously fragmenting demand geography and compressing pricing power for commodity-grade sugared yolk processors. This displacement dynamic concentrates premium pricing among nitrogen-blanketed low-temperature processors in Belgium and Switzerland while forcing standard-grade suppliers into volume-based contract competition.
Pricing Analysis
Long-term offtake contracts dominate procurement between industrial food manufacturers and captive flock operators, with annual volume agreements bundling technical support and regulatory documentation commanding 15-20% premiums over spot-market powder transactions. Price differentiation hinges on Salmonella-negative certification tier and cold-chain delivery capability, with artisanal bakery channels showing lowest price sensitivity due to pasteurization liability outsourcing needs. Cost compression in standard-grade powder is intensifying because corn and soybean feed input volatility squeezes toll processor margins. Quick-service restaurant chains exhibit highest price sensitivity, driving liquid yolk suppliers toward formulation breadth competition.
Supply Chain Analysis
Inventory lead times stretch 8-12 weeks for nitrogen-blanketed low-temperature spray-dried product due to equipment utilization bottlenecks at Belgian and Swiss confectionery-grade facilities. Supply concentrates in Germany for EU cross-border powder distribution, the American Midwest for captive flock liquid yolk, and China's Yangtze River Delta for domestic premium positioning. Raw material flows draw from corn and soybean meal markets, specialized egg collection logistics, and food-grade sucrose supply chains. Single-source vulnerability concentrates in German processing infrastructure for continental European procurement. Distribution runs through direct sales relationships for industrial volumes and specialty stores for artisanal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained thermal processing specialists have become the scarcest capability layer in this market, with industrial baking corridors unable to staff in-house pasteurization teams and forced into pre-formulated ingredient dependency. This skill gap is restructuring competitive advantage around certified processor networks rather than manufacturing scale alone.
For Market Incumbents: Fortify backward integration into captive flock operations to neutralize feed input volatility that disproportionately harms toll processors. Deepen annual contract bundling with formulation consulting and regulatory documentation services to lock in artisanal bakery channels resisting synthetic emulsifier substitution. Plant-based lecithin capture of clean-label positioning in mass-market confectionery demands premium-tier differentiation through nitrogen-blanketed processing certification.
For New Entrants and Emerging Players: SAMR fast-track certification for GB microbial standards offers entry into China's domestic premium tier as export-oriented capacity redirects toward compliance investments. Liquid yolk formulation breadth for quick-service restaurant chains remains underpenetrated versus powder dominance, presenting the most penetrable white-space target. Technical support bundling with refrigerated last-mile delivery capability provides differentiated go-to-market positioning against established powder suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward captive flock integrators with multi-regional compliance infrastructure spanning FDA, EFSA, and SAMR certification protocols. Long-term viability over the next decade rests on upstream supply control rather than downstream formulation services alone. Watch for drum-drying technology retrofit announcements as inflection indicators of margin compression vulnerability among legacy processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Flock Expansion | Midwest and Lower Saxony operations secure feed cost advantages against toll processors. |
| Nitrogen-Blanketed Processing Retrofit | Belgian and Swiss facilities qualify for premium chocolate manufacturer supplier lists. |
| SAMR Compliance Investment | Yangtze River Delta processors access tier-one urban markets under tightened GB standards. |
| Annual Volume Contract Bundling | French patisserie chains outsource pasteurization liability while retaining differentiation claims. |
| Liquid Yolk Formulation Development | Quick-service restaurant chains gain cold-process emulsification performance advantages. |
Research Methodology
Initial hypotheses were tested against primary input from egg processing plant managers, artisanal bakery procurement leads, confectionery R&D directors, and quick-service restaurant supply chain officers and refined through secondary validation. Primary fieldwork combined structured interviews with regulatory affairs specialists at BVL and FDA oversight bodies alongside channel partner discussions with specialty ingredient distributors. Secondary sources included customs and trade flow data for processed egg derivatives, EU Food Additives Regulation filings, SEC 10-K disclosures from integrated food processors, and EFSA guidance documentation. Bottom-up volume modeling triangulated against top-down expenditure analysis across the analysis window.
Variance decomposition across product format, application tier, and end-user scale shaped the analytical framework for projection modeling. Segmentation dimensions covered powder versus liquid versus granulated formats, baking versus confectionery versus sauce applications, and food manufacturer versus bakery versus restaurant end-user categories. CAGRs were derived from fitted growth curves anchored to observed procurement pattern shifts and regulatory compliance investment cycles. Industry-specific forecast inputs incorporated captive flock capacity utilization rates and artisanal bakery channel contract consolidation velocity.
Underlying assumptions cover sustained feed input volatility, regulatory divergence persistence, and plant-based emulsifier substitution pace, with deviation risk concentrated in SAMR enforcement intensity and EU purity threshold implementation timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Soy Protein Market
Ingredients
Jojoba Oil Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Psyllium Products Market
Ingredients
Ice Cream Ingredients Market
Ingredients
Bouillon Cubes Market
Ingredients
Carrot Fiber Market
Ingredients
Dry Molasses Products Market
Ingredients
Hen Egg White Protein Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Soy Flour Market
Ingredients
Germany Gelatin Market
Ingredients
Soy Protein Isolate Market
Ingredients
White Wheat Malt Market