
 Clinical Trial Packaging Market | 2026-2036
Clinical Trial Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Packaging Market Intelligence
The European Union's Clinical Trial Regulation (CTR) is broadening the scope of packaging requirements for multi-country studies. This shifts complexity onto packaging providers who must manage harmonized labeling and distribution across borders. Catalent specializes in cold-chain solutions for the growing biologics pipeline. PCI Pharma Services leverages its integrated supply chain services to support large-scale global trials, while the Almac Group sustains its market position through comprehensive trial supply management.
Clinical trial packaging encompasses primary and secondary containment systems for investigational medicinal products. These materials must ensure product stability and patient blinding, often using multi-language booklet labels and tamper-evident features. While bottles remain a standard format, blister packs are increasingly preferred for their unit-dose accuracy and patient adherence benefits. Phase III trials represent the largest application segment, consuming significant packaging volumes due to extended study durations and large patient cohorts.
Regulatory oversight from bodies like the US FDA, the EMA in Europe, and China's NMPA is stringent, mandating compliance with Good Manufacturing Practices (GMP). These regulations, including serialization requirements under the US DSCSA, dictate material choices and quality assurance protocols. Consequently, packaging suppliers must decide on the level of investment in digital tracking and temperature monitoring technologies. This choice will determine their competitiveness in handling complex, multi-regional trials.
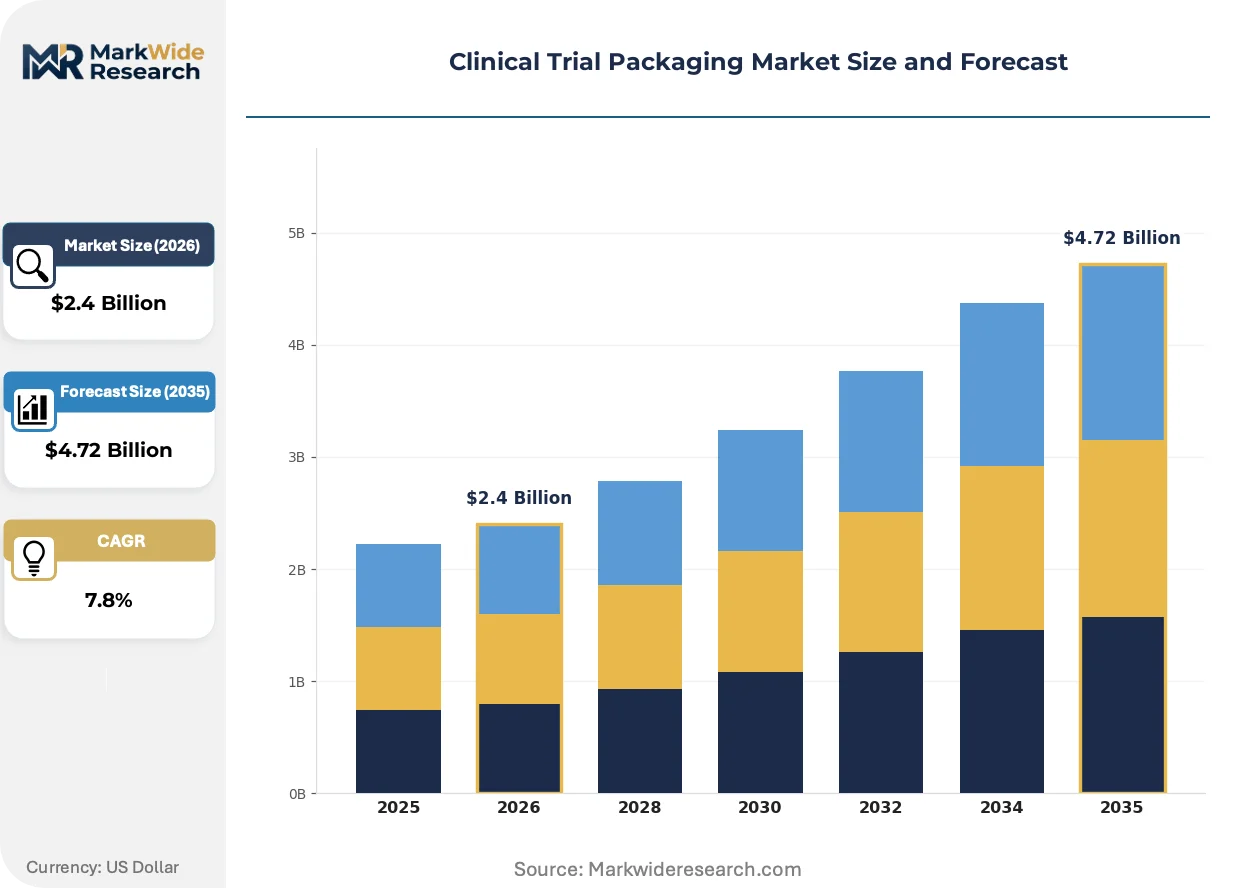
Market Dynamics
The central tension in the clinical trial packaging market is the conflict between global trial harmonization, driven by regulations like the EU's CTR, and the need for region-specific compliance, such as discrete serialization and labeling rules in different countries.
Growth Catalysts
- Expansion of Biologics and Cell Therapy Trials:The growing pipeline of temperature-sensitive biologics, cell therapies, and gene therapies necessitates advanced cold-chain packaging, including insulated shippers and real-time temperature monitoring, to ensure product integrity from the manufacturing site to the patient.
- Serialization Mandates:Regulatory frameworks, including the US Drug Supply Chain Security Act (DSCSA), mandate unit-level serialization for traceability. This requirement is a direct catalyst for investment in smart packaging technologies and integrated digital platforms.
- Surge in Chinese Clinical Trials:A significant increase in new clinical trial initiations within China, encouraged by the NMPA's regulatory reforms, is creating concentrated demand for GMP-compliant primary and secondary packaging services within the Asia-Pacific region.
Market Restraints
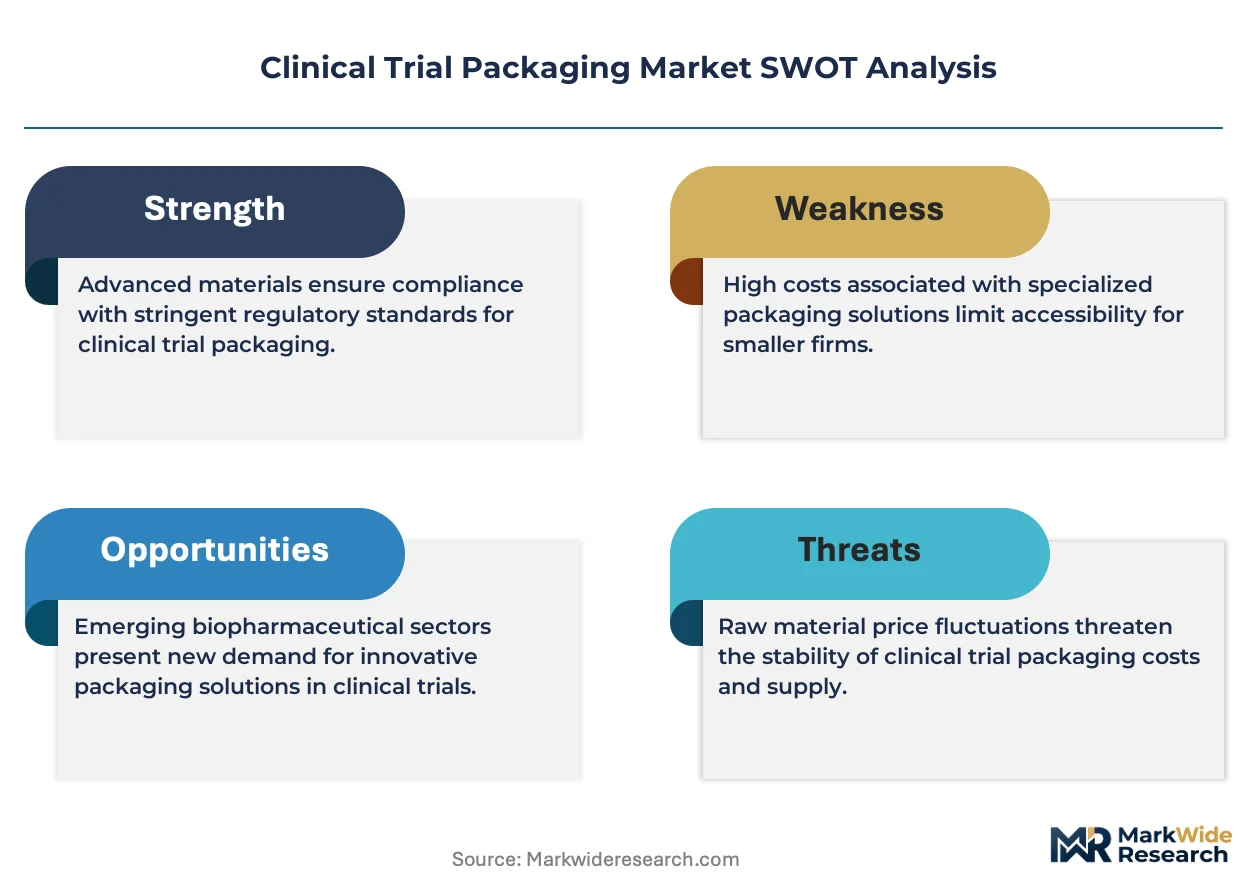
- High Cost of Cold-Chain Materials:The specialized materials and validation processes required for qualified cold-chain shippers and phase-change materials create a high cost base. This expense can be a significant barrier, particularly for smaller biotechnology firms or academic-led studies.
- Complexities of EU CTR Harmonization:While intended to simplify, the European Union's Clinical Trial Regulation (CTR) imposes complex requirements for harmonized labeling across multiple member states. This shifts significant logistical and compliance burdens onto packaging providers managing multi-country trials.
- Limited GMP-Compliant Capacity:A scarcity of contract manufacturing organizations (CMOs) with available, GMP-certified capacity for specialized packaging formats, such as multi-panel booklet labels or child-resistant blister packs for global trials, creates production bottlenecks.
Strategic Opportunities
- Smart Packaging for Adherence Monitoring:Integrating NFC or RFID tags into blister packs and bottles offers a pathway to monitor patient adherence in real time. This data provides significant value to trial sponsors seeking to improve data quality and intervention effectiveness.
- Integrated Trial Supply Management Services:Sponsors are increasingly seeking single-source partners who can manage the entire supply chain, from packaging and labeling to global distribution and returns management. This creates an opportunity for providers to offer end-to-end service bundles.
- Expansion into Emerging Trial Hubs:Beyond established markets, there is an opportunity to build packaging and logistics infrastructure in growing clinical research hubs. Countries like Brazil and South Korea are becoming more active in hosting global trials, creating localized demand.
Industry Challenges
- Harmonization of Multi-Language Labeling:Managing the design, approval, and application of booklet labels that accommodate numerous languages for global Phase III trials is a major operational challenge. Errors or delays in this process can halt patient recruitment across multiple sites.
- Capital Investment in Digital Technologies:Implementing and validating digital systems for serialization, temperature tracking, and supply chain visibility requires substantial upfront capital expenditure. The return on this investment depends on securing contracts for complex, high-value trials.
- Scarcity of Specialized Talent:The industry faces a shortage of personnel with dual expertise in pharmaceutical packaging regulations and advanced logistics, particularly for cold-chain and cell therapy supply chains. This talent gap can constrain a provider's ability to scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Packaging Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottle, Blister Pack, Vial, Syringe, Sachet Application: Phase I Trials, Phase II Trials, Phase III Trials, Bioavailability Studies, Bioequivalence Studies End User: CROs, Pharmaceutical Companies, Biotechnology Firms, Clinical Research Laboratories, Contract Packaging Organizations Packaging Material: Glass, Plastic, Aluminum, Paperboard, Foil |
| Companies Covered | PCI Pharma Services, Catalent, Bilcare Limited, WestRock Company, Schreiner MediPharm, Fisher Clinical Services, Almac Group, Piramal Pharma Solutions, WuXi AppTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Packaging Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from packaging as a passive container to an active component of the clinical trial ecosystem. This shift is driven by the need to manage more complex therapies, enhance data integrity, and meet stringent global regulatory standards.
Adaptive packaging design is gaining traction for use in decentralized and complex clinical trials. This technology involves pre-validated components that can be assembled and labeled on demand. Pharmaceutical sponsors running multi-arm or adaptive protocol studies are the primary adopters, seeking to minimize waste and delays. This approach is modularizing the clinical supply chain, enabling just-in-time kitting and distribution closer to clinical sites or directly to patients.
Sustainability frameworks, particularly those influenced by the EU Green Deal, are impacting material selection for clinical trial packaging. This regulatory pressure is compelling a shift away from traditional single-use plastics and toward materials with higher recyclability or a lower carbon footprint. Packaging suppliers are the most affected, as they must now invest in R&D to find alternatives that meet strict GMP and product stability requirements for both primary and secondary containers.
A clear behavioral shift is occurring away from large-volume orders toward smaller, highly customized packaging runs. This change is directly tied to the rise of trials for orphan drugs, cell therapies, and personalized medicines, which involve small patient cohorts. This model disrupts traditional high-volume contract manufacturing, creating an advantage for agile suppliers with rapid changeover capabilities. The trend is most visible within oncology and rare disease trials.
Clinical Trial Packaging Market Segmentation
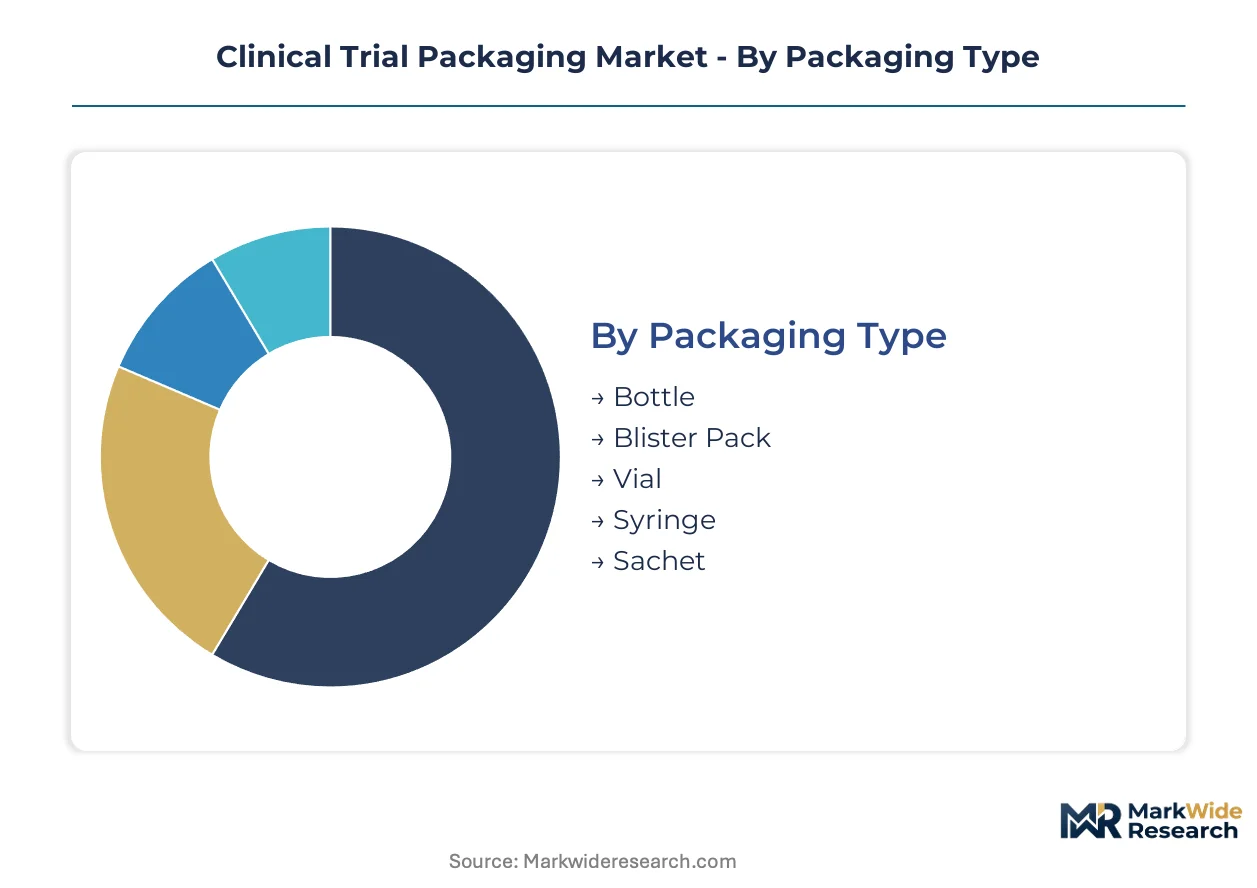
Segmentation within the clinical trial packaging market reveals how diverse product requirements, application scopes, and end-user demands shape supply-side offerings. Understanding these categories is critical for providers to align their capabilities with specific client needs and regulatory mandates.
Packaging Type:
The customization-vs-standardization spectrum defines packaging type choices within clinical trials, balancing cost-efficiency with specific product and patient requirements.
- Blister Pack:Blister packs consist of a thermoformed plastic cavity and a lidding material, typically foil, providing unit-dose accuracy and enhanced patient adherence. Demand is concentrating in Europe due to stringent patient adherence monitoring requirements under the EMA.
- Bottle:Bottles, typically made of plastic or glass, serve as a standard primary containment for solid oral dosage forms and liquid formulations. Demand remains strong across all trial phases, driven by their established use and cost-effectiveness for large volume studies.
- Vial:Vials are small glass or plastic containers primarily used for injectable drugs, often requiring sterile filling and specialized closures.
- Syringe:Pre-filled syringes offer convenience and dose accuracy for injectable therapies, particularly in decentralized clinical trials.
- Sachet:Sachets are flexible, single-dose pouches suitable for powders, granules, or viscous liquids, offering portability and ease of use.
Most installed capacity flows through bottles. Expansion is steepest in blister packs.
Application:
Application segmentation reflects the varying scale and regulatory rigor across different clinical trial phases and study types.
- Phase III Trials:Phase III trials involve large patient cohorts and extended study durations, requiring substantial volumes of primary and secondary packaging. Demand is strongest in China due to a surge in new trial initiations encouraged by the NMPA.
- Phase I Trials:Phase I trials involve small patient cohorts testing drug safety and dosage, necessitating highly customized, often low-volume packaging solutions. Demand for packaging in these early phases is increasing with the rise of orphan drugs and personalized medicines.
- Phase II Trials:Phase II trials assess drug efficacy and side effects in a larger group than Phase I, requiring moderate packaging volumes and robust blinding features.
- Bioavailability Studies:These studies evaluate the rate and extent to which the active drug ingredient is absorbed from a drug product.
- Bioequivalence Studies:Bioequivalence studies compare the bioavailability of different formulations of the same drug, often requiring precise dose packaging.
Growth in this category primarily stems from Phase III Trials, while Bioavailability Studies maintains a stable base.
End User:
End-user segmentation highlights the diverse service models and operational scales of organizations engaging in clinical research.
- Pharmaceutical Companies:Pharmaceutical companies represent established entities with broad R&D pipelines, necessitating comprehensive packaging solutions for global studies. Demand for their trials drives significant innovation in cold-chain logistics due to a growing biologics pipeline.
- Biotechnology Firms:Biotechnology firms often focus on novel biologics and cell therapies, requiring specialized cold-chain packaging and flexible, smaller-batch services. Demand is accelerating for their complex, temperature-sensitive products.
- CROs:Contract Research Organizations manage trials for sponsors, requiring packaging partners capable of integrated supply chain services across multiple projects.
- Clinical Research Laboratories:These laboratories conduct specific analyses within trials, often requiring specialized kits and sample collection packaging.
- Contract Packaging Organizations:CPOs specialize in packaging services, offering expertise and capacity to various clinical trial stakeholders.
The largest spend originates from Pharmaceutical Companies, with Biotechnology Firms showing accelerated engagement.
Packaging Material:
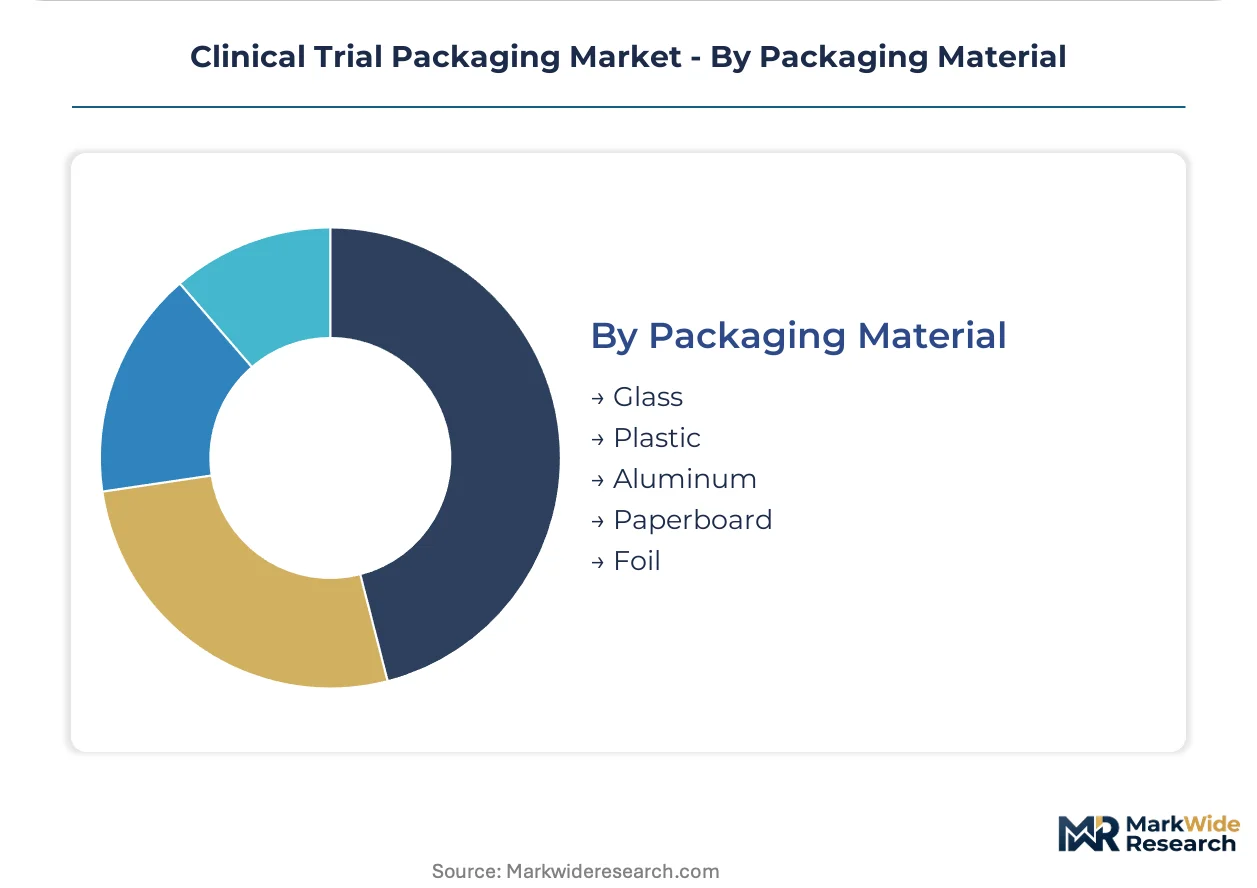
Material properties dictate suitability for product stability and regulatory compliance, influencing packaging material selection.
- Plastic:Plastic materials, including PET and HDPE, offer versatility and cost-effectiveness for various primary and secondary packaging formats. Demand is high across all trial phases due to their adaptability for both solid and liquid formulations.
- Glass:Glass provides excellent barrier properties and chemical inertness, making it ideal for sensitive injectable formulations and long-term stability studies. Demand is concentrated in biologics and sterile products where material integrity is paramount.
- Aluminum:Aluminum is used for its barrier properties against moisture, light, and oxygen, commonly found in blister foils and flexible packaging.
- Paperboard:Paperboard is frequently used for secondary packaging, providing structural integrity and surfaces for multi-language labeling.
- Foil:Foils, often aluminum-based, serve as critical lidding materials for blister packs and pouches, offering superior barrier protection.
Traditional material choices like Glass continue to dominate, but innovation is concentrated in Paperboard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The clinical trial packaging industry initially scaled in regions with established pharmaceutical manufacturing and advanced clinical research infrastructure. These foundational areas continue to drive innovation in complex packaging solutions. Significant demand now emerges from countries actively expanding their biotechnology sectors and trial capabilities.
United States
Demand for clinical trial packaging is driven by a robust pipeline of novel biologics and cell therapies from large pharmaceutical companies. The US FDA's stringent Good Manufacturing Practices (GMP) and the Drug Supply Chain Security Act (DSCSA) mandate advanced serialization and quality controls. Boston and San Francisco Bay Area biotechnology hubs concentrate research, requiring specialized cold-chain and adaptive packaging.
China
A surge in new clinical trial initiations, encouraged by regulatory reforms from the NMPA, generates substantial demand for GMP-compliant primary and secondary packaging. China's dual carbon goals influence material selection towards more sustainable options within packaging. Shanghai's pharmaceutical industry cluster is rapidly expanding its capacity for local and global trial support.
Germany
The country's strong pharmaceutical R&D sector and extensive network of contract research organizations require sophisticated packaging for multi-country European studies. The European Medicines Agency (EMA) regulations and the EU Green Deal compel packaging providers to invest in harmonized labeling and sustainable materials. Frankfurt and Munich remain central to European clinical logistics, managing complex distribution networks.
Japan
Demand for specialized clinical trial packaging stems from a focus on personalized medicines and advanced therapies. Japan's PMDA enforces strict quality standards for investigational medicinal products, influencing packaging design and material choices. The Tokyo metropolitan area, with its numerous pharmaceutical companies, drives requirements for high-precision packaging and cold-chain solutions.
United Kingdom
The UK's advanced biotechnology sector and strong academic research institutions generate demand for agile and customized packaging solutions. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees trial packaging compliance, particularly for complex biologics. The "Golden Triangle" of London, Oxford, and Cambridge forms a research cluster, requiring innovative packaging for early-phase and rare disease trials.
Clinical Trial Packaging Market Key Industry Players
The competitive structure tilts toward specialized contract packaging organizations and integrated clinical supply chain providers. The market exhibits a tiered structure, with large-scale global players offering comprehensive services alongside niche providers focusing on specific therapeutic areas or packaging formats. Strategic archetypes include full-service supply chain integrators, cold-chain specialists, and regional packaging experts. Dominant competitive moves involve capacity expansion in specialized areas and strategic partnerships for global reach.
Among the full-service supply chain integrators, PCI Pharma Services and Catalent exemplify the trend towards comprehensive global trial support, managing complex logistics from packaging to distribution. These providers offer extensive capabilities for both primary and secondary packaging, including specialized cold-chain requirements. The Almac Group occupies a strong position through its extensive trial supply management services, catering to multi-regional studies with robust blinding and labeling solutions. These entities anchor industry capabilities in handling the increasing complexity of biologics and cell therapies, providing integrated solutions across various trial phases.
| Leading Market Players |
|---|
| PCI Pharma Services |
| Catalent |
| Bilcare Limited |
| WestRock Company |
| Schreiner MediPharm |
| Fisher Clinical Services |
| Almac Group |
| Piramal Pharma Solutions |
| WuXi AppTec |
| Others |
Cost & Logistics Intelligence
Adaptive packaging design is modularizing the clinical supply chain, simultaneously reshaping cost economics by minimizing waste and influencing supply concentration through just-in-time kitting. This innovation supports flexible production runs for specialized therapies.
Pricing Analysis
The split between bundled and unbundled services significantly influences pricing in the clinical trial packaging market. Project-based contracting dominates for complex, multi-regional trials, reflecting the high customization required. Price differentiation stems from the customization level for specialized formats like multi-panel booklet labels and the certification level for GMP-compliant facilities. Pricing softness reflects increased competition for standard packaging solutions. Biotechnology firms exhibit lower price sensitivity for novel therapies, while established pharmaceutical companies seek cost efficiencies for large-volume Phase III trials.
Supply Chain Analysis
GMP certification and regulatory qualification gate entry into the clinical trial packaging supply chain, favoring established providers. China, the United States, and Germany concentrate significant GMP-compliant packaging capacity for investigational products. The supply chain draws from specialized cold-chain materials and pharmaceutical-grade plastics as critical inputs. Single-source vulnerability for advanced temperature monitoring devices creates a structural risk. Distribution runs through integrated logistics providers and contract research organizations, ensuring global reach for multi-country studies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clinical trial packaging market acts as a regulatory compounder, driven by the EU's Clinical Trial Regulation (CTR) which mandates harmonized labeling across member states. This regulation pushes demand for advanced, compliant packaging solutions.
For Market Incumbents: Anticipate increased demand for specialized cold-chain solutions stemming from the growing biologics pipeline and cell therapies. Reinforce capacity in regions like the Asia-Pacific to address the surge in Chinese trial initiations. Invest in digital tracking technologies to counter the threat of serialization complexity and maintain market leadership. Deepen vertical integration into specialized packaging materials to mitigate supply chain risks and ensure quality control. For New Entrants and Emerging Players: Channel partners like Contract Research Organizations (CROs) offer a pathway to penetrate the market by providing integrated supply chain services. Target the underpenetrated segment of small-batch, highly customized packaging for orphan drugs and personalized medicines. Focus on agile production capabilities and rapid changeover times for these specialized runs. A go-to-market angle emphasizing flexible, just-in-time kitting solutions can effectively differentiate offerings. For Investors and Strategic Acquirers: Valuations sit cheapest among regional packaging specialists lacking global distribution networks. The market offers long-term viability, driven by sustained pharmaceutical R&D spending and evolving regulatory mandates. Target agile contract packaging organizations with strong GMP compliance and specialized cold-chain expertise. A signal to watch is the increasing adoption of smart packaging technologies, indicating readiness for complex, decentralized trials.| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Smart Packaging Technologies | Enhances patient adherence monitoring and meets stringent serialization requirements from the US DSCSA. |
| Expand Cold-Chain Logistics Capacity | Supports the growing pipeline of temperature-sensitive biologics and cell therapies. |
| Pursue Global GMP Certifications | Enables participation in multi-country studies governed by regulations like the EU CTR. |
| Form Partnerships with CROs | Provides integrated supply chain solutions for sponsors seeking single-source partners. |
| Develop Sustainable Packaging Alternatives | Addresses regulatory pressures from the EU Green Deal and evolving material selection preferences. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and proprietary databases — were reconciled to construct this market analysis. Conversations with regulatory affairs leads, supply chain managers, R&D executives, and procurement officers provided qualitative insights. Secondary validation drew from sources including FDA filings, EMA submissions, and ClinicalTrials.gov data. This approach ensured robust bottom-up and top-down triangulation for market sizing.
Data-stream reconciliation integrated qualitative insights and quantitative metrics to develop the forecast framework across the analysis window. Segmentation dimensions modeled included packaging type, application, end user, packaging material, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns and projected future adoption curves. Key forecast inputs included biologics pipeline expansion and global serialization mandate timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts, material innovation, and geopolitical events. All forecasts reflect documented assumptions about market evolution. A model refresh is warranted upon material change in global clinical trial initiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market