
 Anti-Counterfeit Pharmaceutical Packaging Market | 2026-2036
Anti-Counterfeit Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Counterfeit Pharmaceutical Packaging Market Analysis
A capital-intensity divergence between integrated authentication providers and component specialists is reorganizing competitive tiers in anti-counterfeit pharmaceutical packaging. 3M Company leverages its materials science depth to dominate tamper-evident film substrates across North American pharma corridors. SICPA Holding SA anchors global security ink supply through captive pigment chemistry operations. Authentix competes in track-and-trace software layers, differentiating through government-linked credentialing contracts rather than hardware scale.
Anti-counterfeit pharmaceutical packaging encompasses tamper-evident and authentication-enabled materials engineered with overt, covert, and forensic features such as holographic diffraction patterns, taggant-laden substrates, and machine-readable serialized codes to verify product integrity throughout distribution. Its primary purpose is to prevent falsified medicines from entering legitimate supply chains while enabling regulatory traceability and consumer verification. Serialization technology is capturing disproportionate investment as regulatory deadlines force pharma manufacturers to deploy unit-level coding infrastructure. RFID Tags represent the fastest-growing product category where item-level tracking in cold-chain biologics creates premium margin pools. Security Inks remain a mature, high-volume segment where AlpVision SA and Atlantic Zeiser GmbH occupy specialized niches in microtext and thermochromic formulations.
The US FDA enforces the Drug Supply Chain Security Act, mandating interoperable electronic tracking that directly shapes serialization hardware procurement timelines for pharmaceutical manufacturers. The EU EMA coordinates with national regulators under the Falsified Medicines Directive, requiring safety features and verification systems that standardize authentication formats across member states. India's CDSCO is aligning with WHO prequalification standards, pushing domestic exporters toward ISO-compliant traceability platforms. Stakeholders must monitor whether emerging economies adopt full serialization mandates or maintain partial authentication requirements, as this divergence will determine where capital flows for label and hologram capacity expansion.
Market Dynamics
Serialization mandates across the US Drug Supply Chain Security Act and EU Falsified Medicines Directive are forcing pharmaceutical manufacturers to rebuild packaging infrastructure around unit-level traceability rather than batch-level authentication.
Growth Catalysts
- Regulatory serialization deadlines:The US FDA's DSCSA enforcement timeline and the EU EMA's safety feature requirements are compelling pharmaceutical manufacturers to deploy machine-readable codes on every saleable unit.
- Cold-chain biologics expansion:Temperature-sensitive biologics manufacturers are adopting RFID-enabled packaging to maintain chain-of-custody visibility through distribution networks.
- Export compliance pressure:Indian and Chinese pharmaceutical exporters are upgrading authentication capabilities to meet WHO prequalification standards for regulated markets.
Market Restraints
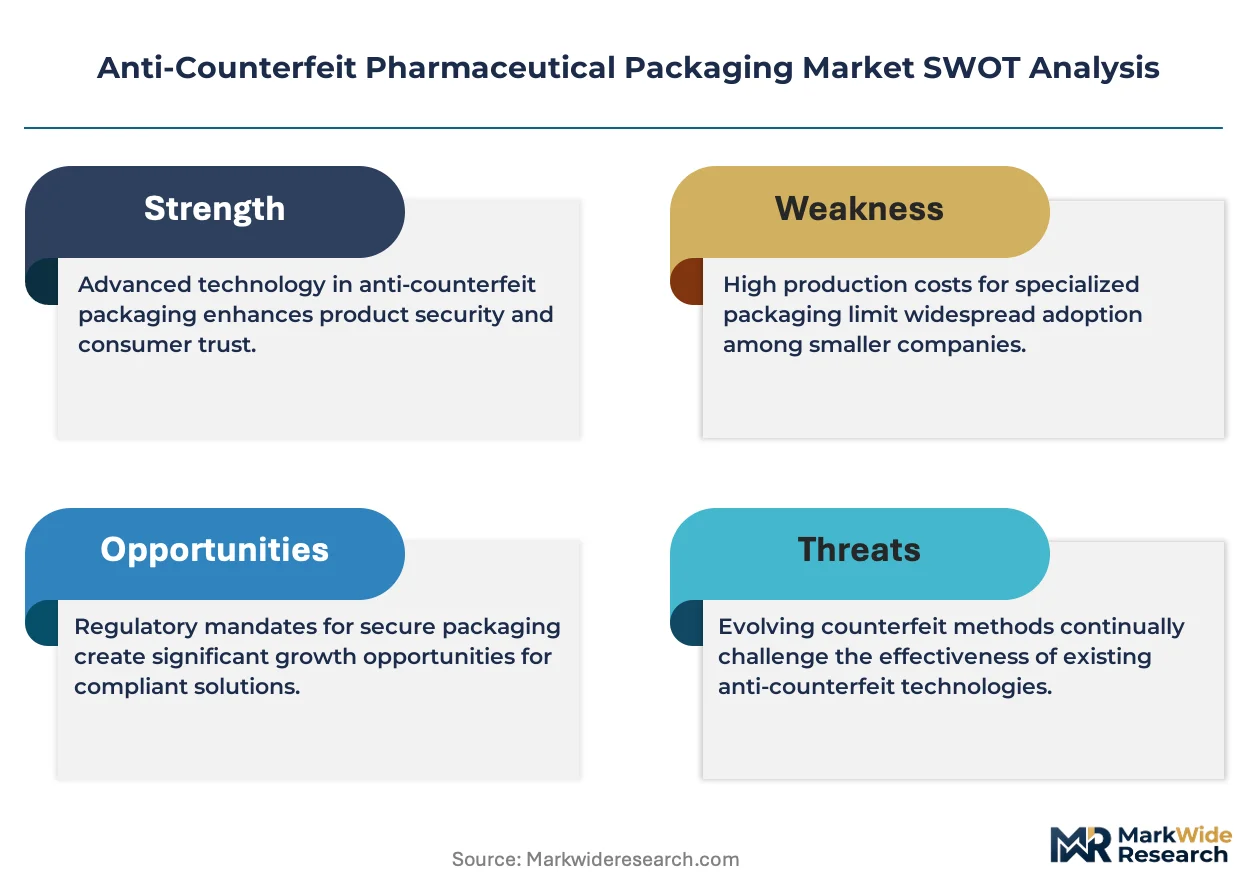
- Specialized substrate cost volatility:Tamper-evident films and holographic substrates depend on petrochemical-derived polymers and rare-earth optical coatings subject to supply fluctuations.
- Security ink supply concentration:Captive pigment chemistry operations in Switzerland and France control critical security ink formulations, creating single-source dependencies for authentication providers.
- Interoperability friction:Divergent national serialization data formats between the US FDA's EPCIS standards and EU EMA's EMVS protocols force redundant system investments.
Strategic Opportunities
- Brazilian regulatory alignment:ANVISA's advancing traceability roadmap for pharmaceuticals creates first-mover positioning for serialization integrators serving Latin American export corridors.
- Blockchain-IoT convergence:Distributed ledger verification layered with NFC-enabled consumer authentication is opening direct-to-patient verification channels bypassing pharmacy intermediaries.
- Saudi Arabia's localization push:SFDA mandates for domestic pharmaceutical packaging capabilities are attracting authentication technology transfers to the Gulf Cooperation Council.
Industry Challenges
- Serialized data architecture talent scarcity:Pharmaceutical manufacturers lack internal expertise in EPCIS event repositories and master data alignment across contract manufacturing networks.
- Legacy packaging line retrofit complexity:Existing bottle-filling and blister-packaging equipment requires mechanical and software modifications to accommodate vision systems and print applicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Counterfeit Pharmaceutical Packaging Market |
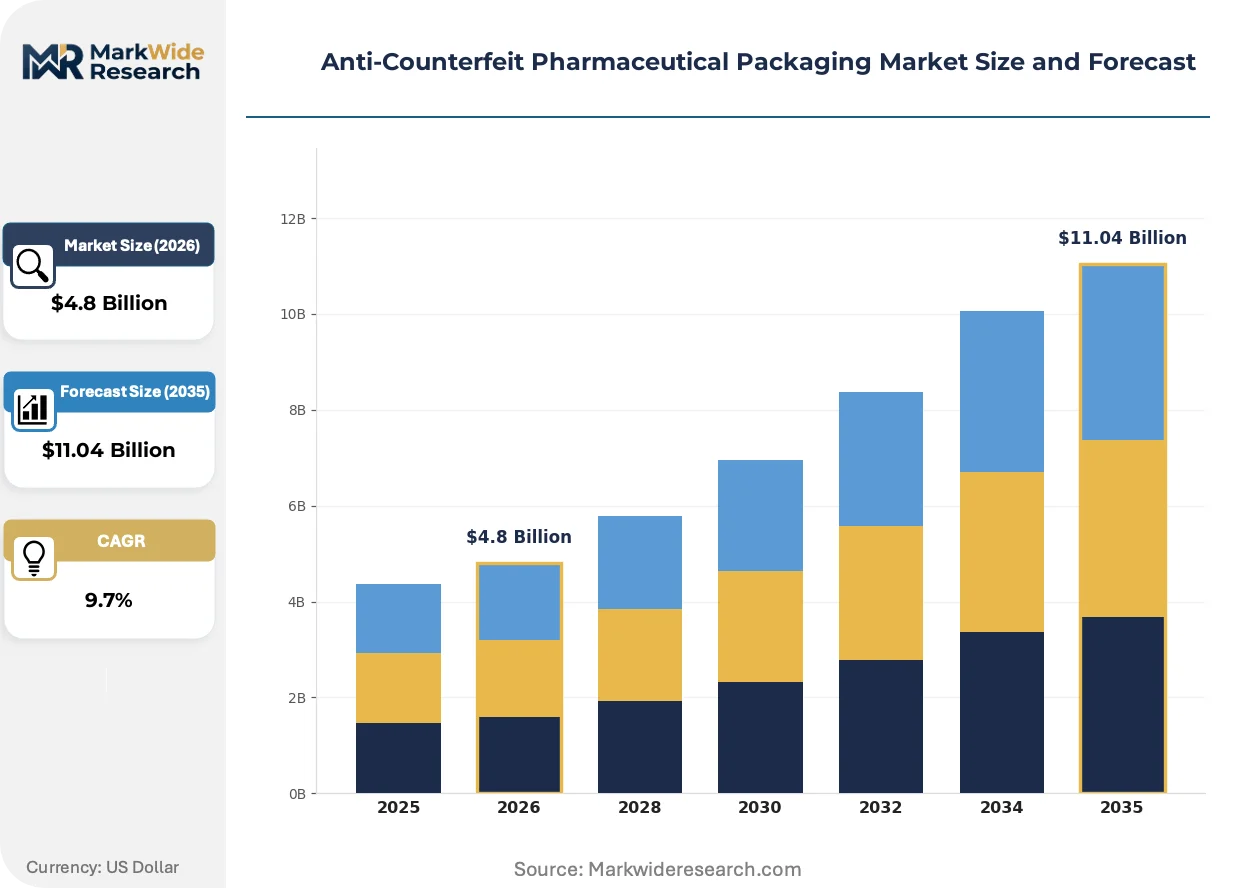
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Holograms, Security Inks, RFID Tags Technology: Digital Watermarking, Serialization, Track & Trace, Biometric Authentication Application: Prescription Drugs, OTC Products, Vaccines, Biotechnology End User: Pharmaceutical Manufacturers, Distributors, Retailers, Hospitals |
| Companies Covered | Zebra Technologies Corp., SATO Holdings Corporation, 3M Company, Authentix, AlpVision SA, Avery Dennison Corporation, SICPA Holding SA, Atlantic Zeiser GmbH, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Counterfeit Pharmaceutical Packaging Market Emerging Trajectories
Digital authentication layers are overtaking physical security features as the primary defense against pharmaceutical counterfeiting, compressing the value capture from holograms and specialty inks toward software-enabled verification ecosystems.
Machine-readable serialization codes with embedded cryptographic signatures are supplanting overt holographic authentication for high-value biologics. Oncology and rare disease drug manufacturers are deploying these codes at unit-level across vial and prefilled syringe formats. The shift is compressing margins for conventional hologram suppliers while expanding recurring revenue pools for track-and-trace software platforms.
The EU EMA's delegated regulation under the Falsified Medicines Directive mandates standardized 2D data matrix codes with unique identifiers across all prescription medicines. This framework forces authentication providers to abandon proprietary code formats in favor of interoperable EU-wide verification systems. Generic drug manufacturers with pan-European distribution networks face the steepest compliance costs and are consolidating supplier relationships to reduce validation overhead.
Direct purchasing of authentication-enabled packaging by pharmaceutical brand owners is displacing traditional converter-mediated procurement. Large molecule drug developers in Massachusetts and California are contracting directly with substrate and software vendors to secure supply continuity and accelerate regulatory filing timelines. This pattern is most pronounced in US biotech clusters where speed-to-market for novel therapies overrides cost optimization in packaging sourcing decisions.
Anti-Counterfeit Pharmaceutical Packaging Market Segmentation
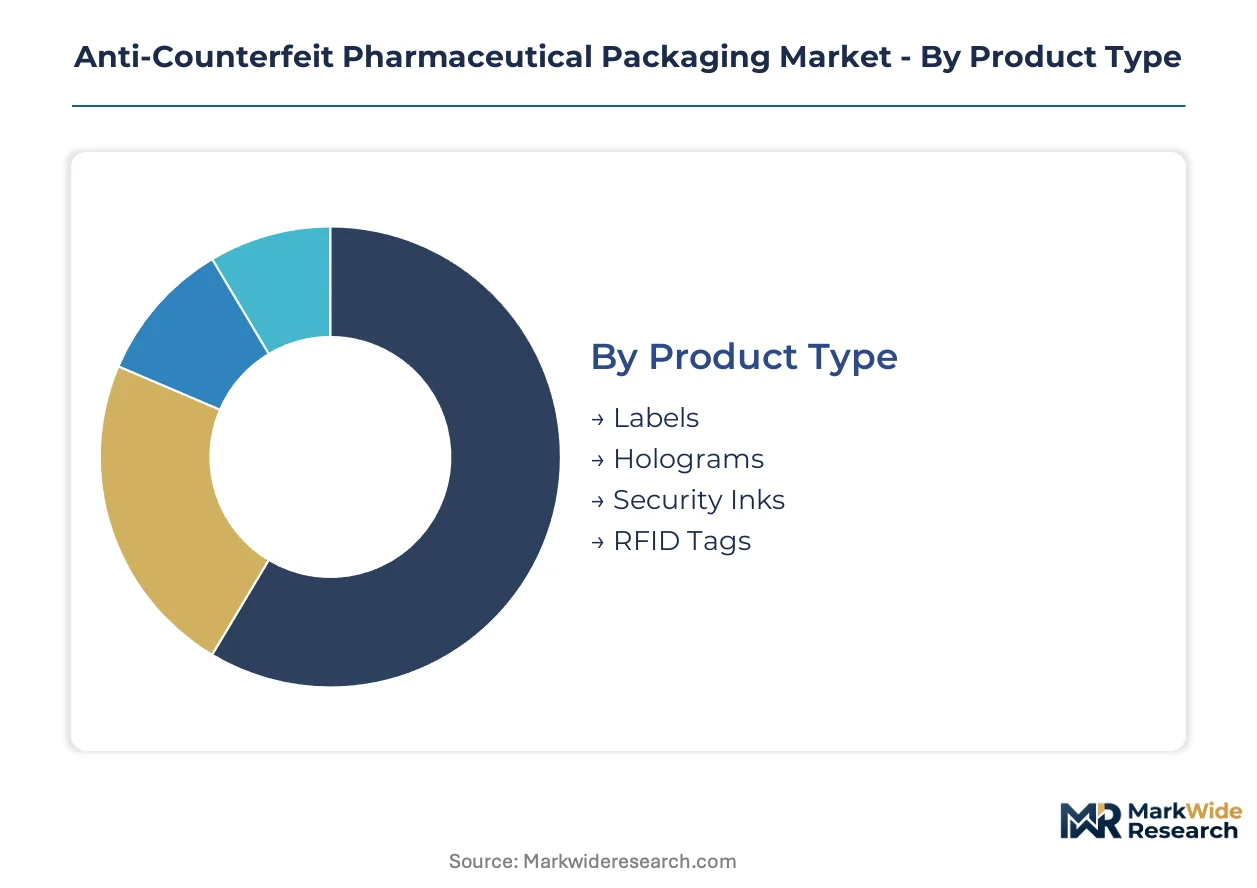
Pharmaceutical packaging authentication segments align with distinct regulatory compliance layers. Serialization mandates and cold-chain traceability requirements fragment procurement priorities across product categories, forcing manufacturers to balance legacy authentication investments against emerging digital verification platforms.
Product Type:
Regulatory differentiation between unit-level coding mandates and batch-level authentication requirements splits procurement strategies across substrate categories. The US FDA's DSCSA and EU EMA's Falsified Medicines Directive enforce divergent technical specifications that reshape supplier selection criteria.
- Labels:Pressure-sensitive substrates with integrated 2D data matrix and human-readable lot codes dominate prescription drug compliance. North American oncology manufacturers prioritize tamper-evident destructible facestocks for vial applications where cold-chain handling demands adhesive stability across temperature excursions.
- RFID Tags:UHF and NFC-enabled inlays embedded in blister lidding and folding carton structures enable item-level tracking without line-of-sight scanning. Biologics distributors in Massachusetts and California corridors deploy these for temperature-sensitive shipments where chain-of-custody documentation carries regulatory weight.
- Holograms:Diffractive optically variable devices provide overt consumer verification through kinetic and multi-channel effects. Indian exporters utilize these for WHO prequalification compliance in regulated destination markets.
- Security Inks:Taggant-laden and thermochromic formulations deliver covert machine-readable authentication. Swiss and French captive pigment operations supply these to European security printers under long-term contractual arrangements.
Established volume favors Labels; emerging adoption favors RFID Tags.
Technology:
Cost tier differentiation separates enterprise-scale serialization deployments from modular track-and-trace implementations serving mid-cap pharmaceutical manufacturers. Capital intensity and internal IT capability determine technology selection across customer segments.
- Serialization:Line-level coding infrastructure integrating vision systems, print applicators, and aggregation software constitutes the largest capital deployment category. Generic drug manufacturers with pan-European distribution networks consolidate supplier relationships to reduce validation overhead across multiple national EMVS connections.
- Track & Trace:Event repository platforms capturing EPCIS-compliant transaction data enable supply chain visibility without full serialization hardware retrofits. Distributors leverage these for compliance in markets with phased implementation timelines.
- Digital Watermarking:Imperceptible image signatures embedded in primary packaging graphics permit smartphone-based consumer verification. OTC brand owners pilot these for direct-to-patient engagement bypassing pharmacy intermediaries.
- Biometric Authentication:Fingerprint and iris recognition systems for high-value controlled substance dispensing remain confined to institutional pharmacy settings with dedicated infrastructure budgets.
Enterprise budgets concentrate on Serialization; pilot investments flow toward Digital Watermarking.
Application:
Application segmentation reflects margin structure variation across therapeutic categories, with biologics commanding premium authentication spending per unit compared to commoditized small-molecule generics.
- Biotechnology:Cell and gene therapy products require cryogenic-compatible authentication features surviving ultra-low temperature storage. Massachusetts and California biotech clusters contract directly with substrate vendors to secure supply continuity for novel therapy launches.
- Vaccines:Multi-dose vial and prefilled syringe formats demand tamper-evident closure systems with integrated serialization for international immunization programs. Gavi and UNICEF procurement specifications drive supplier qualification standards.
- Prescription Drugs:Chronic disease maintenance therapies in oral solid dosage forms constitute the highest unit volume segment with standardized 2D data matrix requirements under EU and US mandates.
- OTC Products:Consumer-facing authentication features prioritize brand protection over regulatory compliance, with holographic seals and scratch-off verification codes common in analgesic and cough-cold categories.
Regulatory pressure concentrates on Prescription Drugs; margin expansion favors Biotechnology.
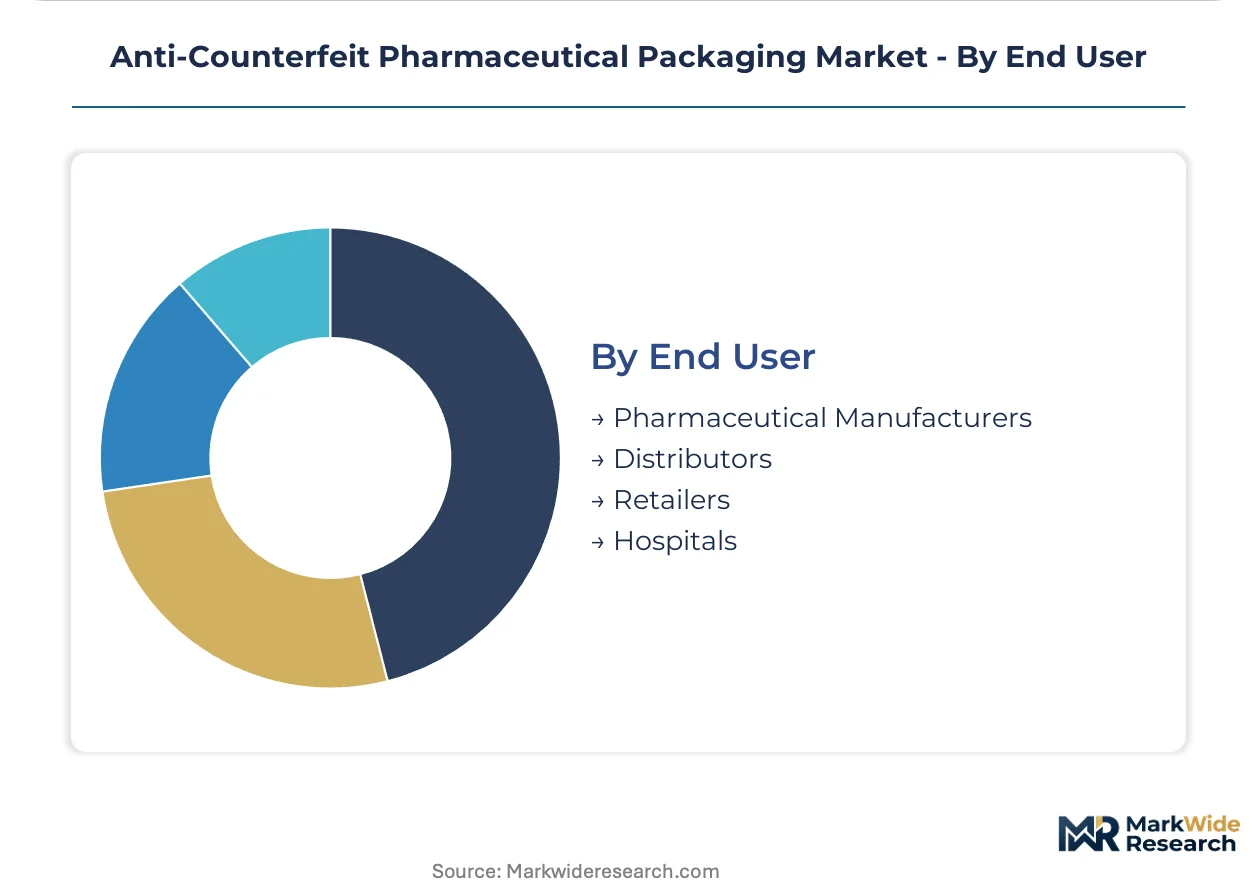
End User:
Customer type segmentation reveals procurement authority migration from traditional converter channels toward direct pharmaceutical brand owner engagement, particularly in high-velocity therapy development settings.
- Pharmaceutical Manufacturers:Brand owners and contract development organizations specify authentication requirements in regulatory filing packages. Large molecule developers in US biotech corridors override cost optimization to accelerate speed-to-market timelines.
- Distributors:Wholesale and specialty pharmacy distributors deploy verification systems for inbound receipt authentication and outbound shipment documentation. Three-tier pricing structures separate enterprise platform deployments from modular API-based integrations.
- Retailers:Chain pharmacies and mass merchandisers implement consumer-facing verification applications for brand differentiation in competitive OTC segments.
- Hospitals:Institutional procurement of authentication-enabled unit-dose packaging supports medication safety protocols and diversion control programs.
Specification authority rests with Pharmaceutical Manufacturers; implementation scale favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Switzerland and Germany command premium authentication spending per unit, while Indian and Chinese exporters compete on label and hologram volume at compressed margins. This pricing-power asymmetry shapes where capital deploys across the value chain.
United States
The FDA's DSCSA enforcement timeline drives serialization hardware procurement across Massachusetts and California biotech corridors. Brand owners contract directly with substrate vendors to accelerate regulatory filings for novel therapies. Cold-chain biologics distributors in these clusters deploy RFID-enabled packaging for chain-of-custody documentation.
Germany
Generic drug manufacturers with pan-European distribution networks consolidate supplier relationships to reduce EMVS validation overhead. The EMA's delegated regulation under the Falsified Medicines Directive forces abandonment of proprietary code formats. North Rhine-Westphalia hosts contract packaging operations serving EU-wide serialization mandates.
India
Domestic exporters upgrade hologram and label capabilities to meet WHO prequalification standards for regulated destination markets. CDSCO alignment with international traceability protocols pushes manufacturers toward ISO-compliant platforms. Gujarat and Maharashtra pharmaceutical clusters drive capacity expansion in authentication-enabled packaging.
China
High-volume production centers serve export demand while local manufacturers navigate evolving NMPA traceability requirements. The country's dual carbon goals pressure petrochemical-derived substrate suppliers to reformulate optical coatings. Yangtze River Delta packaging converters integrate serialization systems for biologics export contracts.
Switzerland
Captive pigment chemistry operations in Swiss manufacturing centers control critical security ink formulations for European authentication providers. Swissmedic coordination with EMA standards shapes regional compliance specifications. Basel-area pharmaceutical headquarters influence global packaging specification authority for multinational drug developers.
Anti-Counterfeit Pharmaceutical Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across hardware, software, and materials segments. The market structure concentrates around integrated authentication providers with captive chemistry operations and component specialists serving modular procurement needs. Three archetypes dominate: materials science conglomerates with substrate depth, security ink specialists with captive pigment operations, and track-and-trace software platforms with government credentialing relationships. Competitive moves center on direct contracting with pharmaceutical brand owners and consolidation of supplier relationships to reduce validation overhead.
Among materials science conglomerates, 3M Company exemplifies substrate-scale positioning through tamper-evident film dominance. SICPA Holding SA represents the security ink archetype with captive chemistry operations anchoring European supply. Authentix occupies the software-layer position, differentiating through track-and-trace platform deployments rather than hardware manufacturing scale.
| Leading Market Players |
|---|
| Zebra Technologies Corp. |
| SATO Holdings Corporation |
| 3M Company |
| Authentix |
| AlpVision SA |
| Avery Dennison Corporation |
| SICPA Holding SA |
| Atlantic Zeiser GmbH |
| CCL Industries |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Swiss and French captive pigment chemistry facilities anchors pricing power for security ink formulations, compressing margins for authentication providers lacking backward integration into optical coating production while elevating price floors for holographic substrates dependent on rare-earth supply.
Pricing Analysis
The customization-premium spread between configured-to-order serialization platforms and standard label substrates structures procurement decisions across pharmaceutical manufacturer tiers. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-scale track-and-trace deployments from modular verification systems, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard hologram and security ink tiers is intensifying because Indian and Chinese exporters are expanding label capacity for WHO prequalification compliance. Generic drug manufacturers with pan-European distribution networks exhibit highest price sensitivity, while Massachusetts and California biotech clusters prioritize supply continuity over unit cost optimization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for petrochemical-derived tamper-evident films and optical coating precursors. Geographic supply concentrates in Switzerland, France, and Germany for security ink formulations, with India and China driving volume expansion in hologram and label substrates. Raw material dependencies rest on rare-earth optical coatings, taggant-laden polymer substrates, and specialized adhesive chemistries. Single-source vulnerability from captive pigment operations in Swiss manufacturing centers creates structural risk for European authentication providers. Distribution runs through direct contracting channels between pharmaceutical brand owners and substrate vendors, displacing traditional converter-mediated procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Track-and-trace software platforms with government credentialing relationships represent a service-attach opportunity, as recurring-revenue subscription layers for EPCIS event repositories and EMVS connectivity expand faster than hardware sales of print applicators and vision systems.
For Market Incumbents: Consolidate supplier relationships across pan-European generic drug manufacturers to reduce EMVS validation overhead, while deepening backward integration into captive pigment chemistry to defend margin position against emerging Indian and Chinese label specialists. Regulatory serialization deadlines under FDA DSCSA enforcement create urgency for pharmaceutical manufacturers to consolidate vendor relationships, making channel control the priority lever for incumbents with existing government credentialing contracts. For New Entrants and Emerging Players: FDA 510(k) fast-track and EU notified body pre-certification pathways accelerate market access for serialization integrators targeting mid-cap biotechnology manufacturers in Massachusetts and California corridors. White-space targets include Brazilian ANVISA traceability alignment for Latin American export corridors and blockchain-IoT convergence layers for direct-to-patient verification. The most penetrable segment is cold-chain biologics distributors lacking internal EPCIS expertise, with pilot-to-production scaling as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among track-and-trace software platforms with government credentialing relationships, positioning these archetypes for superior cash-flow quality across the analysis window. Long-term viability favors authentication providers with hybrid hardware-software offerings serving regulatory compliance mandates rather than commodity label converters. Acquisition targets should demonstrate EMVS or EPCIS platform deployments with pharmaceutical manufacturer reference accounts. The signal to watch is ANVISA traceability roadmap advancement, which would trigger capital deployment toward Latin American serialization integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Fast-Track | FDA DSCSA and EU EMA pre-certification accelerates pharmaceutical manufacturer procurement timelines for novel therapy launches. |
| Backward Integration into Pigment Chemistry | Captive optical coating production secures supply continuity for security ink formulations against rare-earth price volatility. |
| Direct-to-Patient Verification Platform | Blockchain-IoT convergence layers bypass pharmacy intermediaries for OTC brand protection and consumer engagement. |
| Latin American Serialization Expansion | ANVISA traceability alignment positions integrators for Brazilian pharmaceutical export corridor growth. |
| Cold-Chain Biologics Authentication | Cryogenic-compatible RFID inlays enable chain-of-custody documentation for temperature-sensitive cell and gene therapies. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA DSCSA guidance documents, EMA falsified medicines delegated regulations, and WHO prequalification standards, combining interviews with pharmaceutical packaging procurement directors, regulatory affairs leads at biologics manufacturers, serialization platform engineers, and security ink formulation chemists with customs trade data and SEC 10-K filings from listed authentication providers. Bottom-up unit-level coding deployment estimates triangulate against top-down pharmaceutical packaging expenditure projections.
Segmentation dimensions modeled include product type, technology layer, therapeutic application, and end-user procurement authority, with dosage form and regional regulatory cluster as additional pharmaceutical-specific variables. CAGRs derive from regression analysis of historical serialization hardware procurement against regulatory deadline proximity, incorporating cold-chain biologics expansion rates and export compliance pressure from Indian and Chinese manufacturers across the projection horizon.
Underlying assumptions cover sustained FDA DSCSA enforcement timelines and EU EMA safety feature mandate adherence, with deviation risk concentrated in emerging economy adoption of full versus partial serialization requirements and petrochemical-derived substrate cost volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Nutraceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Vaccine Shippers Market