
 Glass Medicine Bottles Market | 2026-2036
Glass Medicine Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Medicine Bottles Market Foresight
ISO 15378 certification for primary packaging materials is redrawing competitive boundaries in pharmaceutical glass manufacturing. Gerresheimer AG leverages captive mold-making capabilities and vertical integration into tubular glass converting to sustain cost leadership across European and North American supply agreements. Schott AG anchors high-value borosilicate capacity for injectable and biologic applications, while SGD Pharma competes through specialized amber glass formulations targeting light-sensitive oncology compounds.
Glass medicine bottles are rigid primary containers fabricated from soda-lime, borosilicate, or treated flint glass, engineered to meet chemical durability standards USP <660> and EP 3.2.1 for pharmaceutical contact materials. They protect liquid pharmaceuticals, injectable solutions, and solid oral dosages from moisture ingress, oxygen permeation, and ultraviolet degradation through controlled wall thickness and hydrolytic resistance. Amber glass bottles command premium positioning due to mandatory light protection for photosensitive APIs, while borosilicate variants capture the fastest growth trajectory driven by biologic drug expansion and escalating thermal shock requirements for autoclave sterilization. Pharmaceutical manufacturers represent the dominant end-user channel, though research laboratories concentrate disproportionate margin capture through small-batch, high-specification custom formats.
FDA's Current Good Manufacturing Practice regulations and the EU's Medical Device Regulation (MDR) impose extractables and leachables testing protocols that elevate compliance costs for non-specialized converters. The European Pharmacopoeia and USP glass classification systems directly determine market access tiers, with Type I borosilicate and Type II treated soda-lime commanding differentiated pricing bands. Stakeholders must monitor evolving pharmacopeial harmonization negotiations and dual-sourcing qualification timelines as supply security rises in strategic priority.
Market Dynamics
ISO 15378 certification requirements are compressing supplier qualification timelines while biopharmaceutical serialization mandates from FDA and EMA force contract manufacturers to dual-source borosilicate capacity, restructuring procurement relationships across the value chain.
Growth Catalysts
- EMA serialization mandates:Track-and-trace requirements for pharmaceutical packaging are compelling biologics manufacturers to upgrade primary container specifications, expanding addressable demand for Type I borosilicate bottles.
- Injectable biologics expansion:Monoclonal antibody and cell therapy pipelines are accelerating thermal shock resistance requirements that favor borosilicate over soda-lime alternatives in autoclave sterilization cycles.
- Rhine-Main cluster concentration:Germany's pharmaceutical manufacturing corridor anchors European demand through Gerresheimer and Schott conversion facilities serving Merck KGaA and Boehringer Ingelheim supply agreements.
Market Restraints
- Borosilicate supply concentration:Schott AG and Corning control approximately 70% of global pharmaceutical-grade borosilicate tubing supply, creating single-source vulnerability for converters without backward integration.
- Energy cost volatility:Glass melting furnaces consume natural gas at rates exceeding 5 GJ per ton of finished product, exposing margin structures to European TTF benchmark fluctuations.
- Plastic vial substitution:Cyclic olefin polymer (COP) and cyclic olefin copolymer (COC) materials are capturing parenteral applications where break resistance outweighs oxygen barrier requirements.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru are qualifying European glass suppliers for USFDA-inspected facilities, opening import substitution channels.
- Cell and gene therapy packaging:Cryogenic storage requirements for CAR-T therapies and mRNA vaccines are creating specifications for ultra-low temperature resistant borosilicate formats.
- EU Green Deal alignment:Carbon border adjustment mechanisms and recycled content mandates are favoring glass over petroleum-derived alternatives in sustainability scoring for pharmaceutical procurement.
Industry Challenges
- ISO 15378 auditor scarcity:Qualified certification bodies for pharmaceutical packaging quality management systems are concentrated in Western Europe, extending qualification timelines for Asian and Latin American converters.
- Extractables and leachables testing backlog:USP <1664> and EP 3.2.1 analytical protocols require 12-18 month stability studies, delaying new product introductions for specialized oncology formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Medicine Bottles Market |
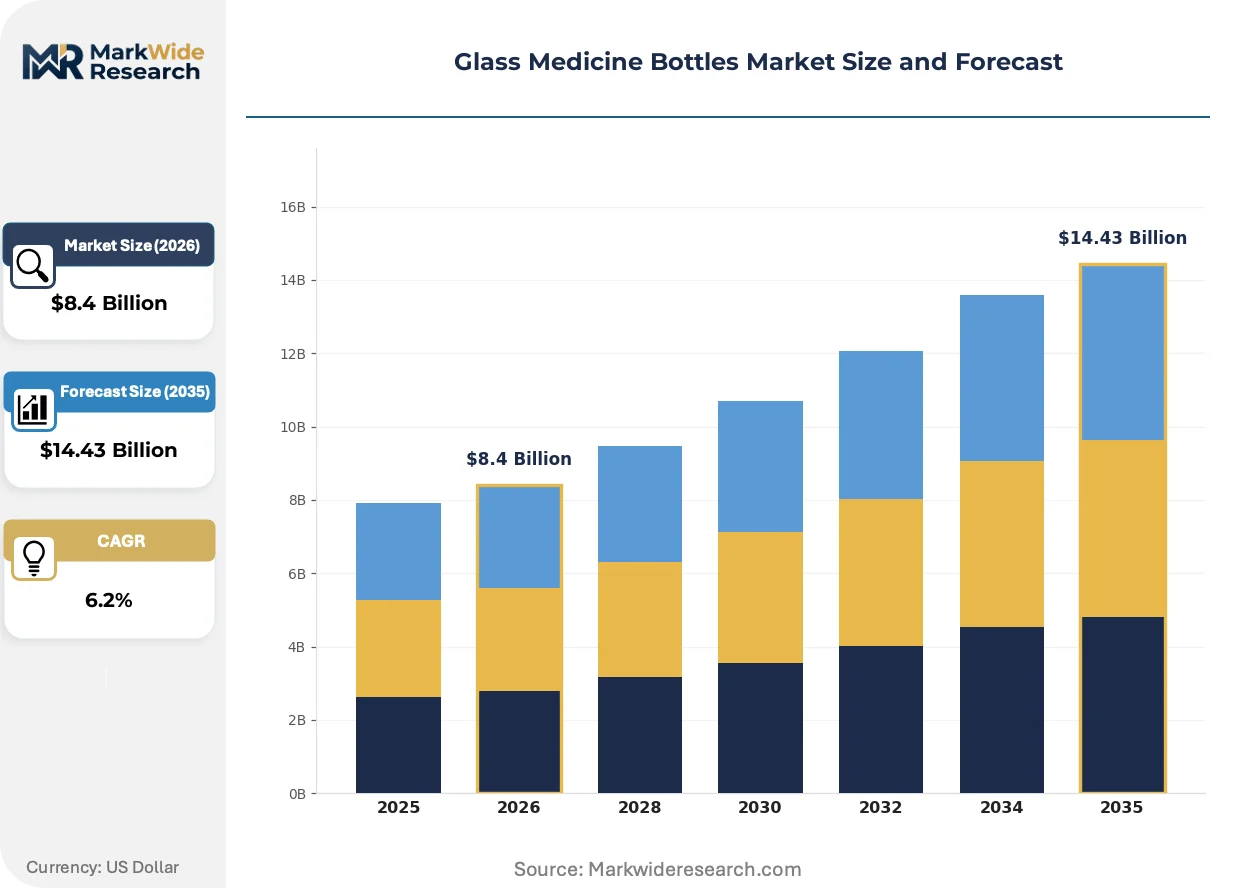
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amber Glass Bottles, Clear Glass Bottles, Flint Glass Bottles, Colored Glass Bottles, Borosilicate Glass Bottles Application: Liquid Pharmaceuticals, Injectable Solutions, Capsules & Tablets, Topical Ointments, Herbal Preparations End User: Hospitals, Pharmaceutical Manufacturers, Research Laboratories, Pharmacies, Clinics Packaging Type: Screw Caps, Dropper Caps, Child-Resistant Caps, Flip-Top Caps, Tamper-Evident Seals |
| Companies Covered | Gerresheimer AG, Schott AG, O-I Glass, Inc., SGD Pharma, Corning Incorporated, Bormioli Pharma, Stevanato Group, Nipro Corporation, West Pharmaceutical Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Medicine Bottles Market Shifts & Advancements
Digital printing and anti-counterfeiting technologies are converging with primary packaging specifications, while pharmacopeial harmonization negotiations between USP and EP are compressing regional format fragmentation.
Near-infrared spectroscopy and machine vision inspection systems are bifurcating quality assurance protocols across the industry. High-volume parenteral manufacturers are adopting 100% automated defect detection at line speeds exceeding 600 bottles per minute. This technology compression is eliminating manual inspection roles while raising capital barriers for mid-scale converters.
FDA's Drug Supply Chain Security Act (DSCSA) and EMA's Falsified Medicines Directive are mandating unit-level serialization on primary containers by 2025. Pharmaceutical manufacturers are embedding 2D data matrix codes directly into glass surfaces through laser etching or ceramic ink deposition. Injectable and biologic segments are absorbing the highest compliance costs, with contract packagers qualifying multi-format serialization lines.
Biopharmaceutical procurement teams are consolidating supplier panels from 8-12 vendors to 3-4 strategic partners, prioritizing ISO 15378-certified converters with captive mold-making capabilities. This concentration is visible most acutely in North American and Western European markets, where dual-sourcing requirements still permit reduced vendor counts if geographic redundancy exists.
Glass Medicine Bottles Market Segmentation
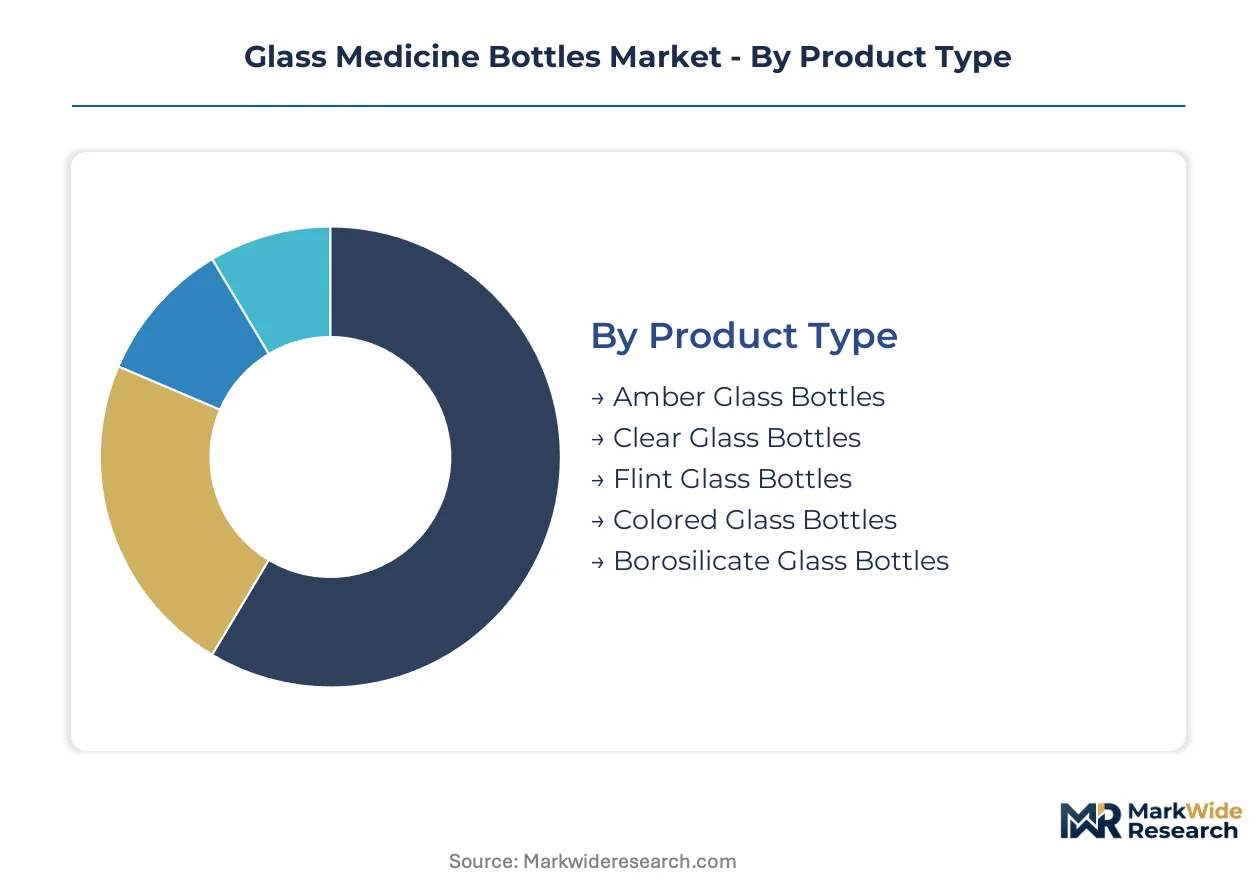
Pharmaceutical glass segmentation reflects divergent compliance burdens across pharmacopeial classifications. USP Type I borosilicate and Type II treated soda-lime specifications create tiered qualification pathways that reshape procurement patterns for biologics manufacturers.
Product Type:
USP and EP glass classifications impose extractables testing protocols that stratify manufacturing economics across material grades.
- Borosilicate Glass Bottles:Engineered from aluminum oxide-boron trioxide-silica matrices delivering hydrolytic resistance USP <660> Type I compliance. Injectable biologics manufacturers in Germany's Rhine-Main corridor specify these formats for autoclave sterilization cycles exceeding 121°C. Thermal shock resistance requirements for monoclonal antibody packaging are displacing soda-lime alternatives in high-value parenteral applications.
- Amber Glass Bottles:Iron oxide-doped formulations blocking ultraviolet transmission below 450nm wavelength. Oncology compound manufacturers mandate these containers for photosensitive APIs requiring light protection under ICH Q1B stability guidelines. FDA extractables protocols for amber variants extend qualification timelines versus clear alternatives.
- Clear Glass Bottles:Soda-lime compositions meeting EP 3.2.1 Type III standards for non-critical oral dosages.
- Flint Glass Bottles:High-clarity treated soda-lime formats for liquid pharmaceuticals where visual inspection is required.
- Colored Glass Bottles:Cobalt or chromium oxide variants serving specialty cosmetic-pharmaceutical crossovers.
Established volume favors amber glass; emerging adoption favors borosilicate formats.
Application:
End-use specifications cascade from sterilization modality and API sensitivity requirements.
- Injectable Solutions:Parenteral applications demand Type I borosilicate compliance with particle contamination limits USP <788>. EMA serialization mandates for biologics track-and-trace are restructuring primary container specifications across European contract manufacturing organizations. Autoclave sterilization protocols favor thermal shock-resistant formats over polymer alternatives.
- Liquid Pharmaceuticals:Oral solutions and suspensions utilize Type II treated soda-lime or Type III soda-lime depending on pH stability requirements. Cough syrups and pediatric formulations concentrate procurement volumes through pharmaceutical manufacturers in India and Germany.
- Capsules & Tablets:Solid oral dosages utilize wider-neck amber or clear glass with desiccant integration.
- Topical Ointments:Wide-mouth configurations with metal or plastic closures for semisolid preparations.
- Herbal Preparations:Traditional medicine segments in regulated and semi-regulated markets.
Injectable applications absorb premium pricing; liquid pharmaceuticals anchor volume scale.
End User:
Customer procurement sophistication determines specification stringency and qualification overhead.
- Pharmaceutical Manufacturers:Integrated drug developers and contract manufacturing organizations drive ISO 15378-certified procurement with dual-sourcing requirements. FDA and EMA serialization mandates are compressing supplier panels from multi-vendor arrangements to strategic partnerships with backward-integrated converters.
- Research Laboratories:Small-batch, high-specification custom formats for clinical trial materials and stability studies command disproportionate margin capture despite lower absolute volumes.
- Hospitals:Institutional procurement of unit-dose and bulk parenteral containers.
- Pharmacies:Compounding operations requiring USP <797> sterile preparation compliance.
- Clinics:Point-of-care medication dispensing with simplified logistics requirements.
Pharmaceutical manufacturers concentrate specification authority; research laboratories capture margin premiums.
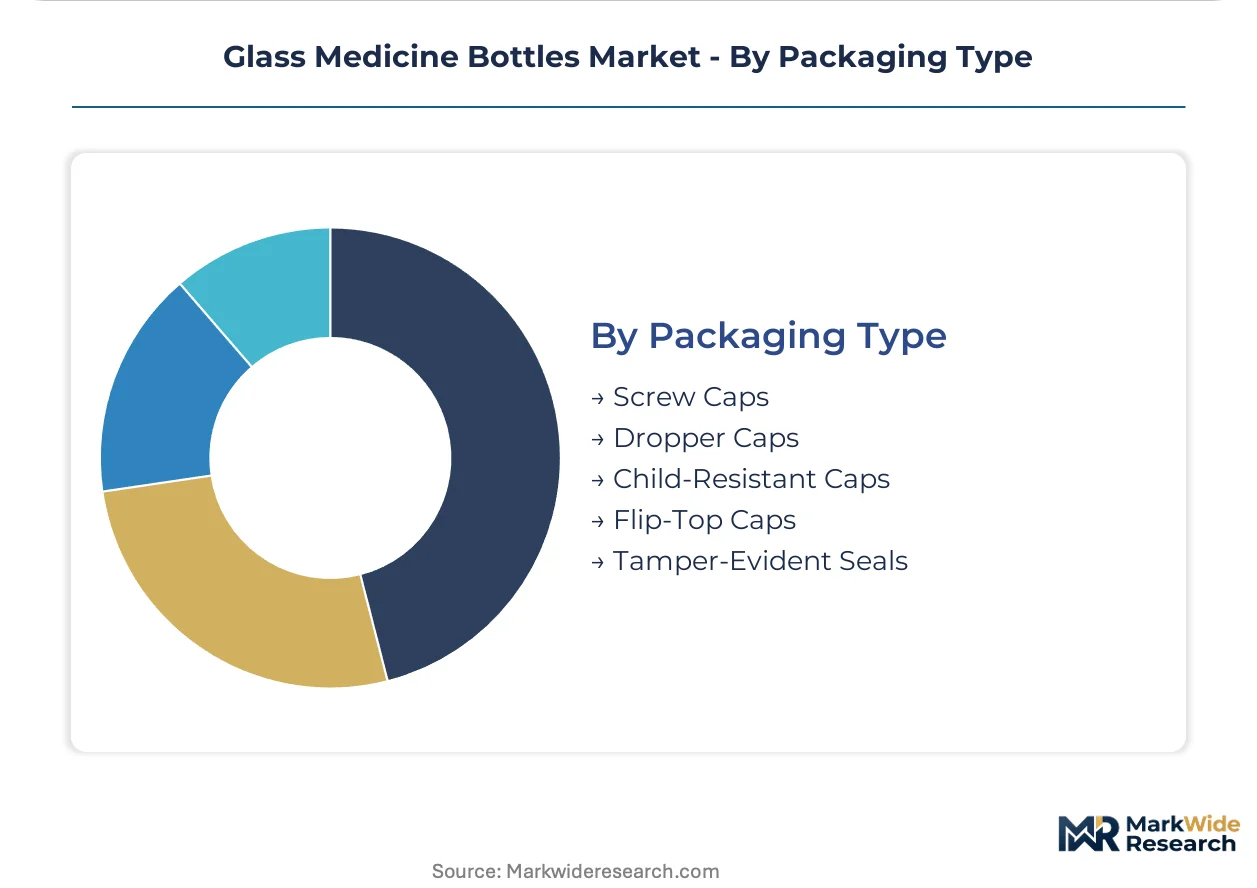
Packaging Type:
Closure system selection intertwines with child safety mandates and tamper-evidence regulations.
- Child-Resistant Caps:Push-and-turn or squeeze-and-turn mechanisms meeting US 16 CFR 1700 and ISO 8317 protocols for oral prescription medications. Poison Prevention Packaging Act compliance is mandatory for household-use pharmaceuticals in the United States.
- Tamper-Evident Seals:Induction-sealed or shrink-banded systems satisfying FDA Food, Drug, and Cosmetic Act Section 801 requirements. Biologics manufacturers embed these features into primary container specifications for supply chain security.
- Screw Caps:Standard continuous thread closures for non-restricted medications.
- Dropper Caps:Pipette-integrated systems for ophthalmic and pediatric liquid formulations.
- Flip-Top Caps:Hinged dispensing closures for over-the-counter convenience applications.
Regulatory mandates favor child-resistant systems; convenience positioning favors flip-top formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates and EMA track-and-trace requirements are restructuring procurement patterns across pharmaceutical manufacturing clusters. Germany's Rhine-Main corridor anchors European borosilicate demand, while India's CDMO expansion and US biologics growth reshape import substitution dynamics.
Germany
The Rhine-Main pharmaceutical corridor generates concentrated demand for Type I borosilicate bottles serving Merck KGaA and Boehringer Ingelheim supply agreements. EMA serialization mandates under the Falsified Medicines Directive compel dual-sourcing qualification for contract manufacturers. Gerresheimer and Schott operate major conversion facilities in the region, supplying ISO 15378-certified formats for autoclave sterilization cycles.
United States
FDA's Drug Supply Chain Security Act drives unit-level serialization adoption across parenteral and biologic packaging segments by 2025. The Boston-Cambridge biotech cluster and New Jersey pharmaceutical corridor absorb premium borosilicate volumes for monoclonal antibody production. DSCSA compliance costs are compressing supplier panels from multi-vendor arrangements to strategic partnerships with backward-integrated converters.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru are qualifying European glass suppliers for USFDA-inspected facilities. CDSCO regulations align with international pharmacopeial standards, enabling export-oriented production. The country's pharmaceutical procurement is shifting toward imported Type I borosilicate as domestic biologics pipelines mature.
China
NMPA serialization requirements and pharmacopeial harmonization with USP/EP standards are elevating compliance barriers for local converters. The Yangtze River Delta pharmaceutical manufacturing belt concentrates demand for high-specification primary packaging. Domestic biopharmaceutical growth is creating specifications for thermal shock-resistant formats in autoclave applications.
Switzerland
Swissmedic regulations enforce stringent extractables and leachables protocols for injectable biologics manufactured by Novartis and Roche. The Basel pharmaceutical cluster sources specialized amber and borosilicate formats for oncology and immunology compounds. Procurement teams prioritize ISO 15378-certified suppliers with captive mold-making capabilities for small-batch clinical trial materials.
Glass Medicine Bottles Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The market structure concentrates around three to five major players controlling borosilicate tubing supply, with mid-scale converters occupying regional niches. Strategic archetypes include backward-integrated tubing producers, specialized oncology glass formulators, and research-laboratory custom format suppliers. Competitive moves center on capacity expansion in pharmaceutical corridors and qualification acceleration through ISO 15378 auditor partnerships.
Among Germany-based fabricators, Gerresheimer AG and Schott AG exemplify the backward-integrated archetype with captive borosilicate conversion capabilities. SGD Pharma occupies a position within the specialized formulation tier, targeting light-sensitive oncology compounds through amber glass expertise. These three companies represent the dominant competitive positioning across European and North American supply agreements.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| O-I Glass, Inc. |
| SGD Pharma |
| Corning Incorporated |
| Bormioli Pharma |
| Stevanato Group |
| Nipro Corporation |
| West Pharmaceutical Services, Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between biopharmaceutical contract manufacturers and borosilicate tubing suppliers lock in both supply access and price visibility across the analysis window. EMA serialization mandates and FDA DSCSA compliance timelines compress procurement cycles, forcing buyers to trade spot-market flexibility for multi-year capacity reservations with Gerresheimer and Schott.
Pricing Analysis
Certification level creates the primary spread across glass medicine bottle tiers, with ISO 15378-certified formats commanding substantial premiums over uncertified alternatives. Three-tier pricing structure separates Type I borosilicate for injectable biologics from Type II treated soda-lime for liquid pharmaceuticals and Type III soda-lime for oral dosages. Cost compression in standard soda-lime segments is intensifying because Indian CDMOs are qualifying European suppliers for price-competitive export production. Research laboratories show the lowest price sensitivity due to small-batch custom specifications, while generic pharmaceutical manufacturers concentrate procurement volumes on economy-tier formats.
Supply Chain Analysis
Just-in-time inventory strategies dominate parenteral pharmaceutical procurement, though EMA dual-sourcing mandates are forcing strategic stockpiles of qualified borosilicate formats. Supply concentrates in Germany, the United States, and China, with Schott and Corning controlling captive tubing production that feeds downstream conversion. Raw material dependencies center on high-purity silica sand, boron compounds, and aluminum oxide for thermal shock resistance. Single-source vulnerability pervades pharmaceutical-grade boron trioxide supply. Distribution runs through direct supplier-to-manufacturer contracts with minimal intermediary involvement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 15378 auditor scarcity and borosilicate tubing supply concentration have created a capability bottleneck where qualified conversion capacity outruns available certification bandwidth. This scarcity dynamic rewards incumbents with backward-integrated supply chains while elevating barriers for aspirant converters.
For Market Incumbents: Fortify captive mold-making capabilities and expand borosilicate conversion capacity in the Rhine-Main corridor to capture EMA-mandated dual-sourcing volumes. Schott and Gerresheimer should accelerate ISO 15378 auditor partnerships to compress qualification timelines for contract manufacturers facing FDA serialization deadlines. Defend against COP and COC polymer substitution by emphasizing oxygen barrier performance in autoclave sterilization applications. For New Entrants and Emerging Players: Anchor in India's CDMO expansion corridor, where Hyderabad and Bengaluru facilities are qualifying European glass suppliers for USFDA-inspected export production. Target research laboratory segments with small-batch custom formats for clinical trial materials, capturing margin premiums that offset lower absolute volumes. Pursue partnerships with ISO 15378 certification bodies to differentiate through accelerated qualification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with captive tubing supply and certification infrastructure. Long-term viability hinges on exposure to biologics serialization mandates and cell therapy cryogenic storage specifications. Watch for inflection when carbon border adjustment mechanisms in the EU Green Deal shift procurement preferences toward glass over petroleum-derived alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Captive supply of pharmaceutical-grade tubing eliminates single-source vulnerability for converters serving FDA-mandated serialization. |
| ISO 15378 Certification Acceleration | Partnerships with European auditor bodies compress 18-month qualification timelines for Asian CDMO market entry. |
| Cell Therapy Packaging Development | Ultra-low temperature resistant formats capture CAR-T and mRNA vaccine storage specifications from Novartis and Roche. |
| Long-term Supply Agreements with CDMOs | Multi-year offtake contracts with Hyderabad and Bengaluru manufacturers lock in volume visibility across the analysis window. |
| Digital Printing and Serialization Integration | Laser etching and ceramic ink deposition capabilities satisfy FDA DSCSA and EMA Falsified Medicines Directive unit-level tracking mandates. |
Research Methodology
Operator-level perspectives from pharmaceutical packaging procurement managers, regulatory affairs directors at biopharmaceutical manufacturers, glass conversion plant engineers, and CDMO supply chain executives anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA DSCSA guidance documents, EMA Falsified Medicines Directive implementation reports, USP glass classification monographs, and pharmacopeial harmonization negotiation records. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down market sizing from customs data and industry association disclosures.
Sensitivity analysis tested forecast robustness against energy cost volatility, boron compound price fluctuations, and polymer substitution rates across the projection horizon. Segmentation dimensions modeled include glass pharmacopeial classification, sterilization modality, API sensitivity requirements, and regional regulatory cluster. CAGRs were derived from trend extrapolation of biologics pipeline expansion, serialization mandate compliance timelines, and CDMO facility qualification rates. Industry-specific inputs incorporated autoclave sterilization cycle specifications, extractables and leachables testing protocol durations, and carbon border adjustment mechanism implementation schedules.
Material uncertainties — regulatory harmonization delays, energy price shocks, and auditor capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about EMA and FDA serialization enforcement timelines, borosilicate tubing supply expansion rates, and Indian CDMO import substitution velocity. Revision becomes warranted when polymer substitution rates in parenteral applications or carbon pricing implementation thresholds cross materiality bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market