
 Nigeria Plastic Bottles Market | 2026-2036
Nigeria Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Plastic Bottles Market Insights
PET is restructuring Nigeria's rigid packaging economics as beverage brands abandon glass and metal alternatives for lightweight, shatter-resistant containers. Panar Group leverages integrated resin-to-bottle operations across West African supply corridors. Nigerian Bottling Company anchors its procurement through captive distribution networks serving Coca-Cola system partners. Sacvin Nigeria Limited competes on pharmaceutical-grade certification, supplying chlorinated and fluorinated barrier bottles for liquid drug formulations.
Nigeria plastic bottles are hollow thermoplastic containers manufactured through extrusion blow molding or injection stretch blow molding, typically formed from polyethylene terephthalate resin with intrinsic viscosity between 0.72 and 0.82 dL/g for carbonated applications, serving primarily as portable liquid containment and retail distribution vessels. PET dominates volume throughput due to its clarity, barrier performance, and established recycling collection streams in Lagos and Abuja municipal zones. HDPE sustains growth in household and industrial chemical segments where chemical resistance outweighs aesthetic requirements. The 500ml and 1L size brackets concentrate demand from single-serve beverage and personal care marketers chasing on-the-go consumption patterns in Nigerian urban centers.
The National Agency for Food and Drug Administration and Control enforces material migration limits and labeling standards that determine which resin grades qualify for food and pharmaceutical contact, while the Standards Organisation of Nigeria mandates dimensional and performance testing under MS 459 for plastic containers. These frameworks elevate compliance costs for importers while creating protected terrain for domestic converters with certified laboratory capabilities. Stakeholders must weigh backward integration into preform manufacturing against resin import dependency as naira volatility and port congestion reshape total delivered cost structures.
Market Dynamics
NAFDAC's tightening food-contact material rules are forcing beverage bottlers across Lagos and Kano to upgrade resin specifications and laboratory testing capabilities, compressing margins for converters without certified in-house quality systems.
Growth Catalysts
- Preform localization:Ogun State's industrial corridor is attracting blow-molding investments that reduce import dependency and cut lead times for Lagos-based beverage distributors.
- Pharmaceutical-grade demand:Chlorinated barrier bottles for liquid drug formulations are commanding certification premiums as domestic drug manufacturers expand sterile filling capacity.
- MS 459 compliance infrastructure:Standards Organisation of Nigeria mandates are creating protected terrain for domestic converters with dimensional testing laboratories, locking out uncertified imports.
Market Restraints
- Naira volatility:Resin import dependency exposes converters to foreign exchange swings that shred margin predictability on PET and HDPE feedstock.
- Port congestion at Lagos:Container dwell time spikes inflate working capital requirements and disrupt just-in-time preform supply to Kano bottlers.
- Glass persistence in premium spirits:Heritage brands in Nigerian alcoholic beverages resist PET migration, capping volume upside in high-margin categories.
Strategic Opportunities
- Abuja municipal collection streams:Formalized recycling infrastructure in the capital region offers feedstock security for rPET converters ahead of other Nigerian cities.
- Household chemical HDPE pivot:Industrial and agricultural chemical distributors are abandoning metal drums for stackable plastic containers, opening non-beverage volume.
- Barrier technology convergence:Fluorination and plasma coating advances enable single-layer PET to replace multilayer structures in sensitive pharmaceutical applications.
Industry Challenges
- Blow-molding technician scarcity:Injection stretch blow molding expertise concentrates in legacy Lagos operations, constraining expansion into northern production nodes.
- NAFDAC migration testing timelines:Certification delays for new resin grades stretch six to nine months, freezing product development cycles for seasonal beverage launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Plastic Bottles Market |
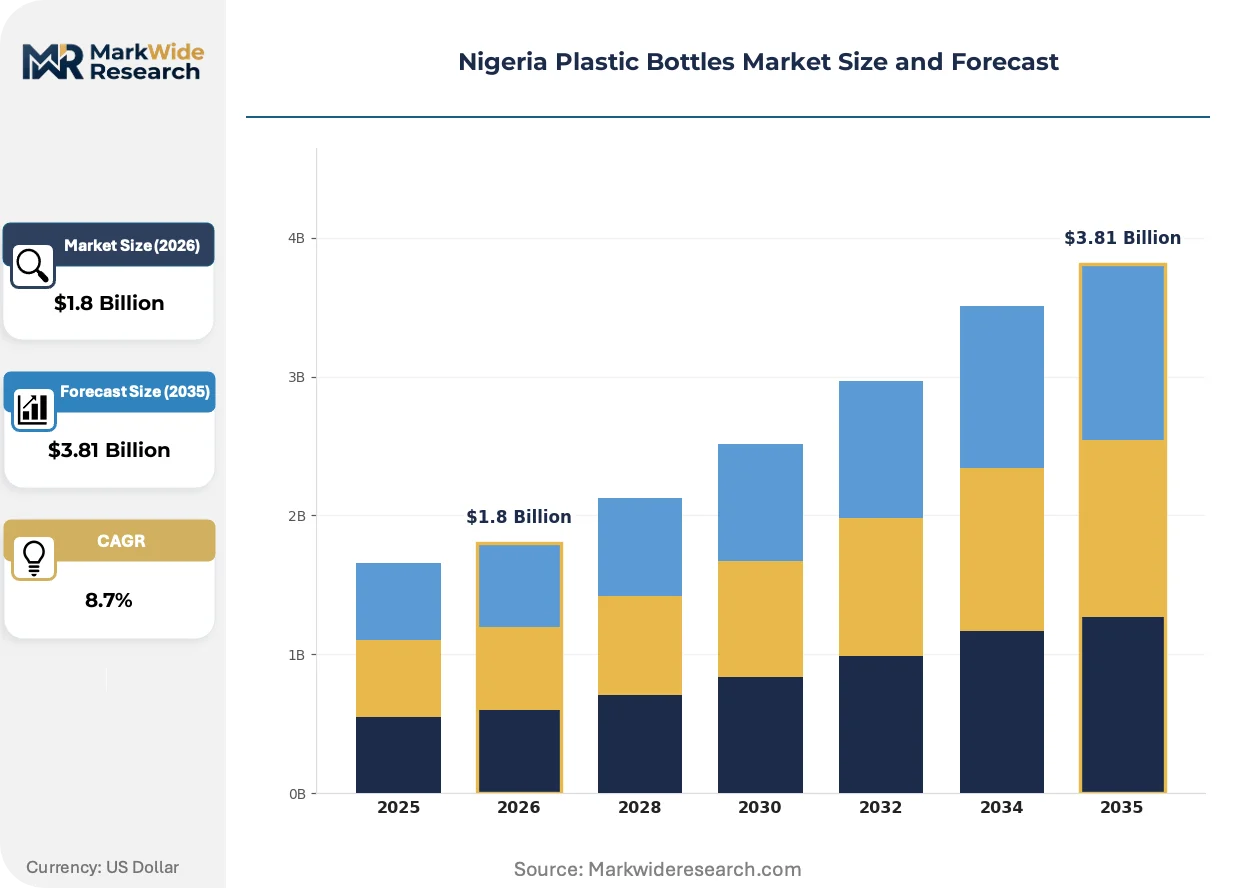
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End User: Beverage, Personal Care, Pharmaceutical, Household Size: 500ml, 1L, 2L, 5L Closure Type: Screw Cap, Snap-on Cap, Flip-top Cap, Others |
| Companies Covered | Panar Group, Sacvin Nigeria Limited, Bestaf Holdings, Nigerian Bottling Company, Veritas Plastic Limited, Shan Packaging Limited, Ok Plast Nigeria Ltd, Platinum Bottling Company, Geeta Plastic Products Nigeria Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Plastic Bottles Market Trends and Innovations
Lightweighting pressures and circularity mandates are compressing traditional container specifications while opening technical white space for advanced barrier and recycled content solutions across Nigerian conversion facilities.
rPET flake-to-preform processing is expanding into beverage supply chains as Coca-Cola system partners and independent bottlers face internal sustainability targets that outpace domestic collection infrastructure. Lagos-based converters with European-sourced washing and extrusion lines are capturing early-mover premiums. The technology is expanding into mid-tier water brands previously locked out by virgin PET cost advantages.
NAFDAC's 2024 food-contact material migration limits are forcing resin grade upgrades across carbonated and still beverage categories. Converters without in-house gas chromatography capabilities are outsourcing testing to certified Lagos laboratories, adding cost but creating compliance moats. Pharmaceutical liquid formulations face the strictest enforcement, driving fluorinated bottle adoption.
Single-serve consumption patterns are fragmenting procurement lot sizes as convenience retailers in Lagos and Abuja demand mixed-SKU pallets with shorter lead times. Traditional bulk preform contracts are yielding to flexible scheduling arrangements with penalty clauses for forecast variance. Northern distributors are consolidating volume to secure priority allocation during resin shortage periods.
Nigeria Plastic Bottles Market Segmentation
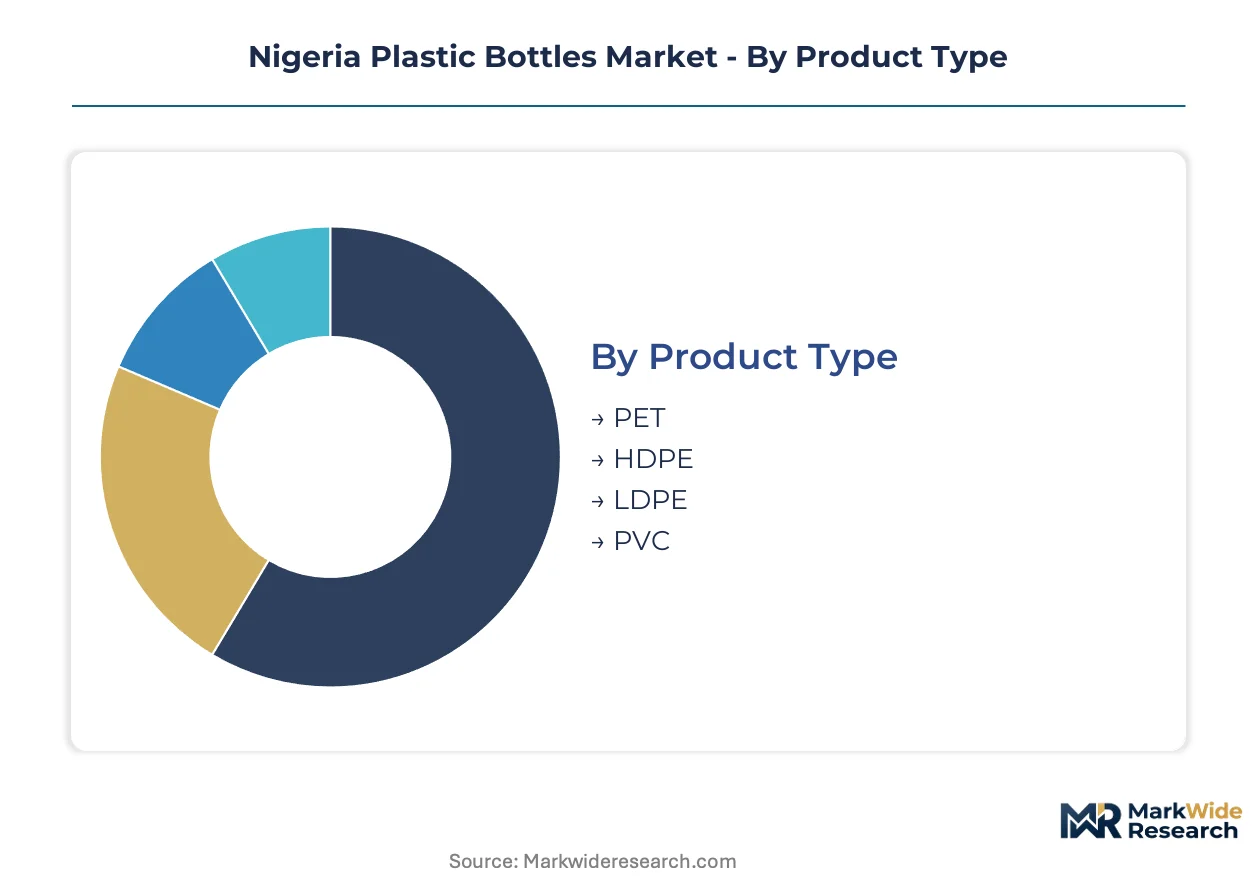
Resin selection and size configuration determine capital deployment patterns across Nigerian conversion facilities. Bottlers in Lagos and Kano prioritize segments that align with NAFDAC compliance timelines and port-proximate logistics.
Product Type:
PET and HDPE demand the heaviest upfront investment in injection stretch blow molding lines and barrier coating equipment.
- PET:Clear thermoplastic polyester with intrinsic viscosity between 0.72 and 0.82 dL/g for carbonated applications. Beverage bottlers across Lagos and Kano anchor procurement here, though naira volatility on virgin resin imports compresses margin predictability.
- HDPE:High-density polyethylene with superior chemical resistance for aggressive contents. Household and agricultural chemical distributors in northern Nigeria are abandoning metal drums for stackable HDPE containers, opening non-beverage volume.
- LDPE:Lower-density variant with flexibility advantages for squeeze applications. Personal care marketers in Abuja municipal zones specify LDPE for shampoo and lotion dispensers where hand-feel differentiation commands shelf attention.
- PVC:Chlorinated polymer with cost advantages in non-food industrial packaging. Limited beverage penetration due to NAFDAC migration testing complexity and consumer perception constraints.
PET absorbs the bulk of installed capacity; HDPE is expanding most quickly.
End User:
Pharmaceutical and beverage applications impose the steepest certification burdens on converters.
- Beverage:Carbonated soft drinks, water, and juice bottlers generate the highest throughput volumes. Coca-Cola system partners and independent water brands in Lagos drive mixed-SKU pallet demand with compressed lead times.
- Pharmaceutical:Liquid drug formulations require chlorinated or fluorinated barrier bottles with sterile filling compatibility. Domestic drug manufacturers expanding capacity in Ogun State corridor command certification premiums.
- Personal Care:Shampoo, conditioner, and lotion marketers chase on-the-go consumption patterns. Abuja convenience retailers fragment procurement lot sizes with flexible scheduling demands.
- Household:Industrial and agricultural chemical distributors pivot from metal drums to plastic. Northern Nigeria consolidation trends secure priority allocation during resin shortage periods.
Beverage segments dominate current throughput; pharmaceutical specifications climb the fastest.
Size:
Tooling costs scale non-linearly with cavity configuration and neck finish complexity.
- 500ml:Single-serve format concentrates demand from on-the-go consumption channels. Lagos urban retailers specify this bracket for convenience store placement and transit-oriented sales.
- 1L:Standard household format balancing portability with value perception. Kano distributors consolidate volume here to secure priority preform allocation during supply tightness.
- 2L:Family-size positioning for shared consumption occasions. Price-sensitive water brands in mid-tier segments favor this configuration for home delivery routes.
- 5L:Bulk format for institutional and commercial accounts. Industrial chemical and agricultural inputs dominate this bracket where stackability outweighs aesthetic requirements.
500ml and 1L formats absorb the bulk of installed capacity; 5L specifications gain share fastest.
Closure Type:
Tamper-evidence engineering and line-speed compatibility drive tooling investment decisions.
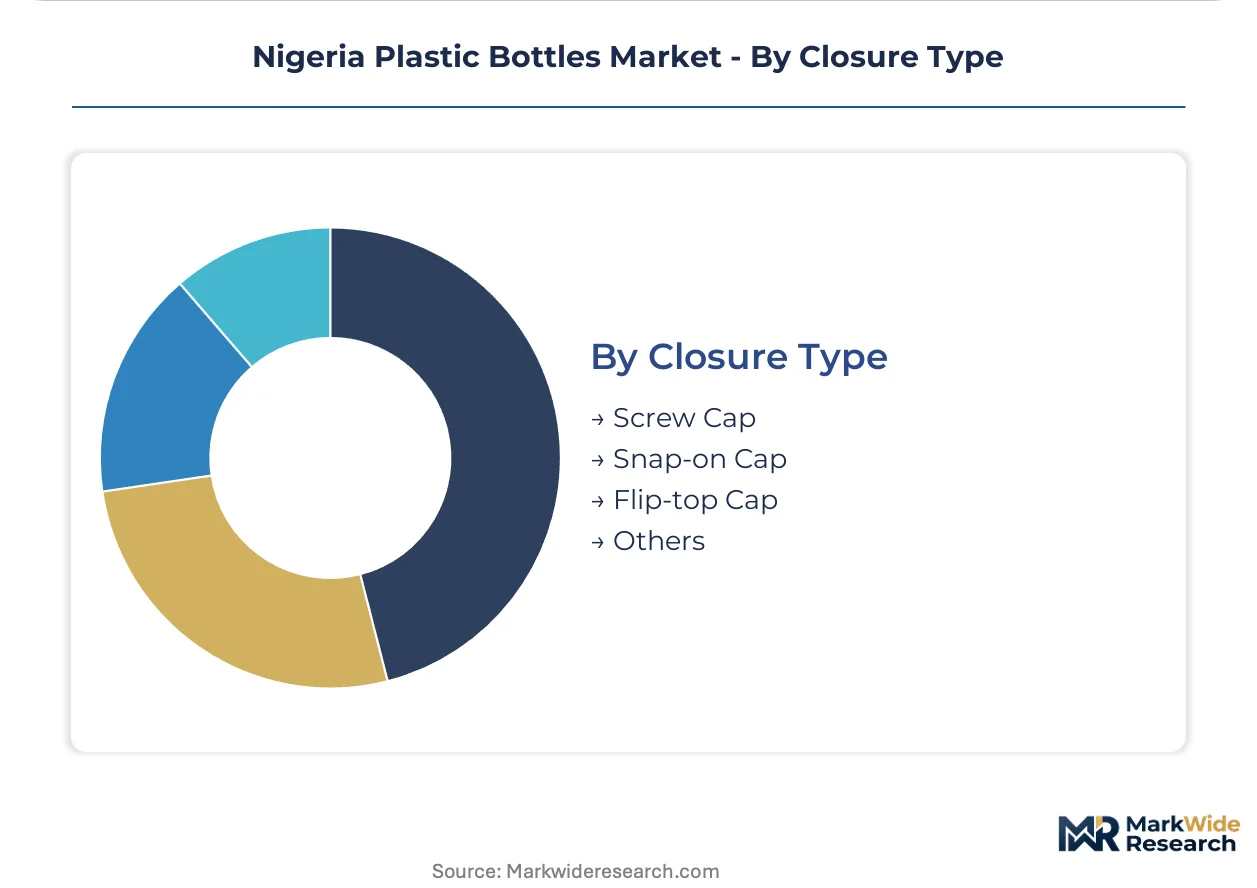
- Screw Cap:Threaded closure with reseal functionality across beverage and household categories. Standard specification for carbonated applications requiring pressure retention.
- Snap-on Cap:Press-fit design enabling faster capping line speeds. Personal care marketers in Lagos specify this format for cost-competitive shampoo and conditioner packaging.
- Flip-top Cap:Hinged dispensing closure for controlled product release. Pharmaceutical liquid formulations and premium personal care applications demand this configuration.
- Others:Dispensing pumps, trigger sprayers, and specialty closures for niche applications. Agricultural chemical distributors specify these for measured-dose requirements.
Screw cap formats absorb the bulk of installed capacity; flip-top configurations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for plastic bottles in Nigeria clusters around three industrial corridors. Lagos and Ogun State anchor beverage and pharmaceutical conversion capacity. Kano serves northern distribution networks. Abuja's municipal recycling infrastructure offers early feedstock security for rPET processors.
Lagos State
Beverage bottlers and pharmaceutical converters concentrate procurement here. NAFDAC enforces food-contact material migration limits that determine resin grade qualification. Apapa port proximity reduces container dwell time exposure for preform imports serving Coca-Cola system partners and independent water brands.
Ogun State
Industrial corridor investments in blow-molding capacity are displacing import dependency. The Standards Organisation of Nigeria mandates MS 459 dimensional testing that locks out uncertified competitors. Local converters with captive laboratory capabilities capture protected terrain as foreign suppliers face compliance barriers.
Kano State
Northern distributors consolidate volume to secure priority preform allocation during resin shortage periods. Central Bank of Nigeria foreign exchange policies expose converters to naira volatility on virgin PET imports. Bottlers here face extended lead times from Lagos port congestion that disrupt just-in-time supply chains.
Abuja Federal Capital Territory
Formalized recycling collection streams offer feedstock security ahead of other Nigerian cities. Municipal waste management partnerships are concentrating rPET flake supply for converters with European-sourced washing lines. Pharmaceutical-grade demand from expanding domestic drug manufacturers drives fluorinated barrier bottle specifications.
Rivers State
Petrochemical feedstock proximity from Port Harcourt refineries shapes regional resin access patterns. Industrial chemical distributors pivot from metal drums to stackable HDPE containers for agricultural inputs. Port infrastructure limitations constrain export-oriented conversion investments compared to Lagos corridor alternatives.
Nigeria Plastic Bottles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The market exhibits moderate concentration with integrated resin-to-bottle operators commanding protected positions. Three archetypes dominate: captive suppliers serving multinational beverage systems, pharmaceutical-grade certification specialists, and regional converters competing on logistics proximity. Capacity expansion and backward integration into preform manufacturing represent the primary competitive vectors as import dependency exposes margins to currency volatility.
Among Nigeria-based converters, Panar Group, Sacvin Nigeria Limited, and Nigerian Bottling Company occupy distinct strategic positions. Panar exemplifies integrated operations spanning West African supply corridors. Sacvin represents the pharmaceutical-grade certification tier with barrier technology capabilities. Nigerian Bottling Company anchors the captive distribution model serving system partners. These three sit within a competitive set where laboratory accreditation and port-proximate logistics determine contract access.
| Leading Market Players |
|---|
| Panar Group |
| Sacvin Nigeria Limited |
| Bestaf Holdings |
| Nigerian Bottling Company |
| Veritas Plastic Limited |
| Shan Packaging Limited |
| Ok Plast Nigeria Ltd |
| Platinum Bottling Company |
| Geeta Plastic Products Nigeria Ltd |
| Others |
Pricing and Supply Chain Analysis
Coca-Cola system partners and independent beverage bottlers in Lagos and Kano concentrate procurement volume, anchoring a contract-based long-term offtake model where resin import exposure and NAFDAC certification tiers stratify pricing bands across virgin PET, barrier-grade, and rPET specifications.
Pricing Analysis
Volume throughput concentrates in 500ml and 1L beverage formats where per-unit margins compress under naira volatility, while pharmaceutical-grade fluorinated bottles command certification premiums that insulate converters from spot resin swings. Price differentiation hinges on NAFDAC migration testing completion and intrinsic viscosity grade qualification, with uncertified imports locked out by MS 459 compliance barriers. Cost compression in standard beverage PET is intensifying because Lagos port congestion inflates working capital requirements for resin-dependent converters. Mid-tier water brands exhibit highest price sensitivity, while sterile drug manufacturers accept premium positioning for barrier technology.
Supply Chain Analysis
Regional distribution centers in Ogun State's industrial corridor are displacing direct Apapa port dependency for Lagos-based bottlers, though Kano distributors still draw from Lagos hub-and-spoke patterns with extended lead times. Virgin PET resin supply concentrates in Saudi Arabia, South Korea, and China, with Nigerian converters resting on import channels exposed to Central Bank of Nigeria foreign exchange policies. Preform manufacturing equipment and gas chromatography testing apparatus represent critical single-source vulnerabilities from European suppliers. Distribution runs through captive networks serving multinational beverage systems alongside independent converter spot sales to northern distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAFDAC certification laboratory scarcity props pricing power for compliant domestic converters, creating a supply-constrained environment where backward integration into preform manufacturing separates sustainable operators from margin-squeezed resin importers.
For Market Incumbents: Cement market position by acquiring captive preform production capacity in Ogun State corridor to sever port congestion exposure, while locking pharmaceutical-grade certification moats against emerging barrier technology competitors. Prioritize in-house gas chromatography capabilities to compress NAFDAC migration testing timelines that freeze seasonal product development cycles. For New Entrants and Emerging Players: Launch via municipal recycling partnerships in Abuja Federal Capital Territory to secure rPET flake feedstock ahead of virgin resin cost volatility, targeting mid-tier water brands previously excluded by premium barrier pricing. Exploit technician scarcity in northern Nigeria by establishing injection stretch blow molding training programs tied to Kano distributor consolidation. For Investors and Strategic Acquirers: The window for entry favors integrated resin-to-bottle operators with existing NAFDAC laboratory accreditation and port-proximate logistics infrastructure. Long-term viability hinges on circularity mandate compliance as Coca-Cola system sustainability targets outpace domestic collection infrastructure. Watch Abuja municipal waste management contract awards as inflection signal for rPET feedstock security.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Severs Lagos port congestion exposure for Ogun State corridor converters serving Coca-Cola system partners. |
| NAFDAC Certification Laboratory Investment | Creates compliance moat locking out uncertified imports under MS 459 dimensional testing mandates. |
| Abuja Municipal Recycling Partnership | Concentrates rPET flake supply for converters with European-sourced washing lines ahead of other cities. |
| Pharmaceutical-Grade Barrier Technology Scale-Up | Captures certification premiums from domestic drug manufacturers expanding sterile filling capacity in Ogun State. |
| Northern Nigeria Distribution Consolidation | Secures priority preform allocation for Kano bottlers during Central Bank of Nigeria foreign exchange tightening periods. |
Research Methodology
Document review covered customs and trade data from Nigerian ports, Standards Organisation of Nigeria MS 459 testing protocols, and NAFDAC food-contact material migration guidelines, complemented by interviews with blow-molding plant managers, beverage procurement leads at Lagos distributors, pharmaceutical packaging engineers, and Ogun State industrial corridor developers. Secondary validation drew from Central Bank of Nigeria foreign exchange policy circulars, petrochemical feedstock import records, and municipal waste management partnership disclosures in Abuja. Bottom-up capacity assessments across Nigerian conversion facilities were triangulated against top-down demand estimates from beverage and pharmaceutical end-use sectors.
Installed capacity outputs across resin type, size configuration, and end-use application were modeled over the projection horizon, with segmentation incorporating closure type complexity and barrier technology tier alongside geographic production cluster. CAGRs were derived from trend extrapolation of preform localization investments and NAFDAC compliance timeline compression, cross-referenced against naira volatility scenarios and port efficiency assumptions. Forecast inputs included Lagos container dwell time patterns and Abuja recycling collection stream formalization rates.
Resin price volatility, regulatory certification delays, and foreign exchange policy shifts are the dominant revision risks that could compress or extend modeled capacity utilization trajectories. Forecasts reflect base-case assumptions regarding NAFDAC enforcement consistency and Ogun State infrastructure development continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Polyethylene Terephthalate-Glycol (PETG) Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Brazil Plastic Bottles Market