
 Global Plastic Tarpaulin Market | 2026-2036
Global Plastic Tarpaulin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Tarpaulin Market Foresight
Aftermarket service revenue for repair patches, grommet replacement, and UV-recoating is reshaping margin distribution across the value chain. Sioen Industries leverages in-house coating technology to sustain premium positioning in architectural membrane derivatives. Heytex Brandenburger GmbH anchors European supply through controlled distribution of technical textiles to German transport fleets. Fulin Plastic Industry Co. Ltd. dominates Asian export volumes by operating integrated extrusion lines from Zhejiang province.
Plastic tarpaulin denotes woven or non-woven polymer sheets, typically 80–300 gsm, manufactured through extrusion-lamination or hot-calendering of polyethylene or PVC resins, then treated with UV stabilizers and flame retardants to serve as weather-resistant protective covers for assets and work sites. Polyethylene tarpaulin leads volume globally due to its cost efficiency in construction covering and agricultural sheeting, though PVC tarpaulin commands higher unit margins in transportation protection where abrasion resistance justifies premium pricing. Mesh tarpaulin represents the fastest-growing product category as event organizers and warehousing providers adopt breathable alternatives for wind-load reduction and condensation control.
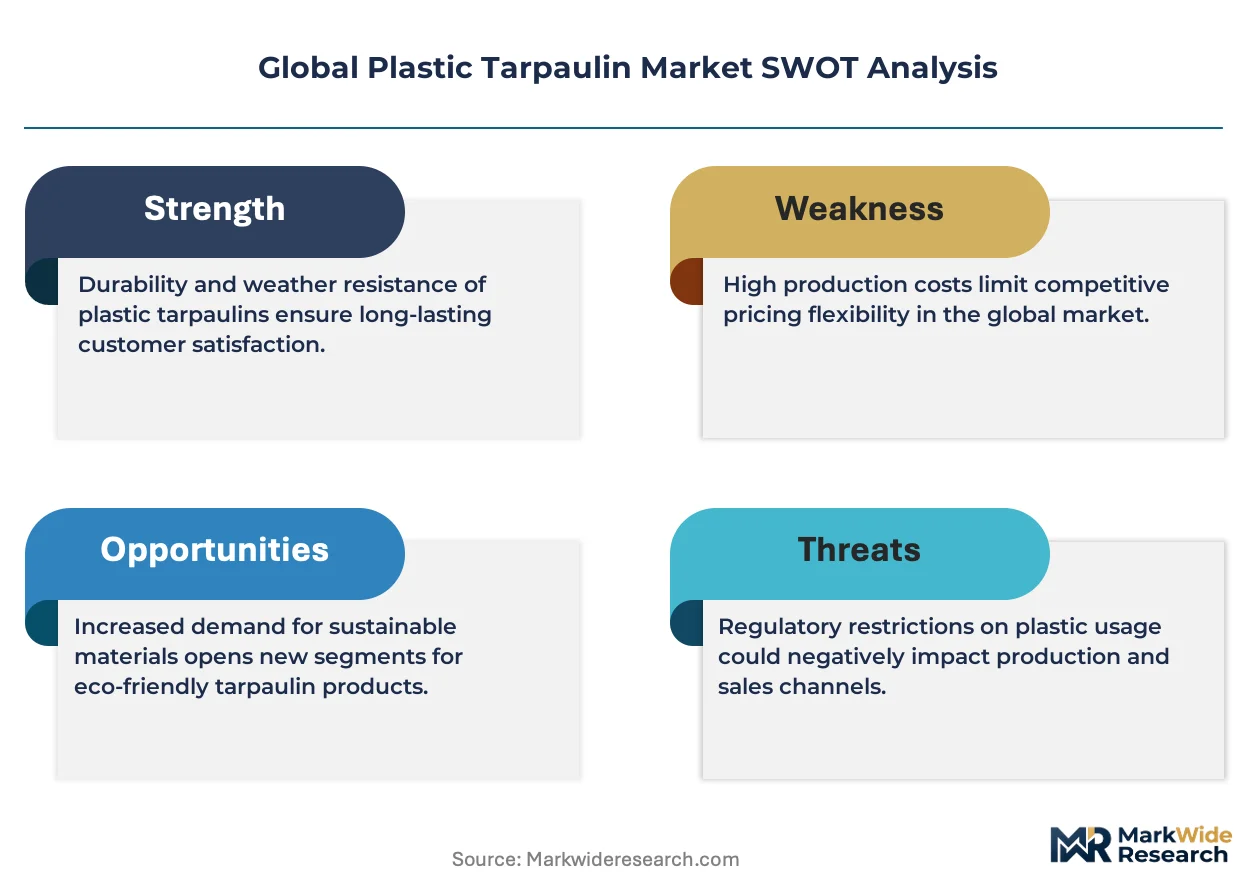
The EPA regulates volatile organic compound emissions from tarpaulin coating operations in the United States, while REACH restricts hazardous additive chemistries across EU member states, and India's BIS mandates tensile strength benchmarks for construction-grade polyethylene sheeting under IS 7903. These frameworks elevate compliance costs for commodity producers while creating certification barriers that favor technically capable manufacturers. Stakeholders must monitor evolving extended-producer-responsibility mandates in the European Union and state-level plastic waste rules in India to anticipate feedstock cost shifts and product redesign requirements.
Market Dynamics
REACH compliance in the European Union is forcing manufacturers to eliminate phthalate-based plasticizers from PVC formulations, while construction contractors in India and Brazil are scaling purchases of reinforced polyethylene sheeting for monsoon-site protection, reshaping feedstock demand patterns across petrochemical corridors.
Growth Catalysts
- Construction-grade polyethylene sheeting:Contractors in India are scaling purchases of reinforced polyethylene sheeting for monsoon-site protection, driving volume demand for 120-200 gsm UV-stabilized grades.
- REACH phthalate restrictions:European Union manufacturers are reformulating PVC tarpaulins with bio-based plasticizers to maintain market access, creating certification premiums for compliant producers.
- Mesh tarpaulin adoption:Event organizers and warehousing providers are adopting breathable mesh alternatives for wind-load reduction and condensation control in temporary structures.
Market Restraints
- Crude oil price volatility:Polyethylene and PVC resin costs fluctuate with naphtha and ethylene feedstock pricing, compressing margins for non-integrated fabricators.
- Gujarat supply concentration:Petrochemical feedstock suppliers and tarpaulin fabricators cluster in Gujarat's chemical manufacturing corridor, creating geographic vulnerability to regional logistics disruptions.
- Mechanical recycling limitations:Multi-layer laminated tarpaulins resist conventional mechanical recycling due to incompatible polymer layers and coating contamination.
Strategic Opportunities
- Brazilian infrastructure expansion:Federal housing programs and highway construction are generating demand for heavy-duty construction covering in São Paulo and Rio de Janeiro states.
- Extended producer responsibility mandates:European Union regulations are creating incentives for take-back programs and design-for-recycling tarpaulin architectures.
- Digital printing integration:UV-curable inkjet systems are converging with coated textile manufacturing to enable on-demand branded tarpaulin production for event and retail applications.
Industry Challenges
- UV stabilization formulation expertise:Manufacturers face scarcity of polymer chemists capable of balancing hindered amine light stabilizer loadings with flame retardant compatibility.
- Hot-calendering equipment lead times:European and Japanese machinery suppliers quote 14-18 month delivery timelines for precision calendering lines, delaying capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Tarpaulin Market |
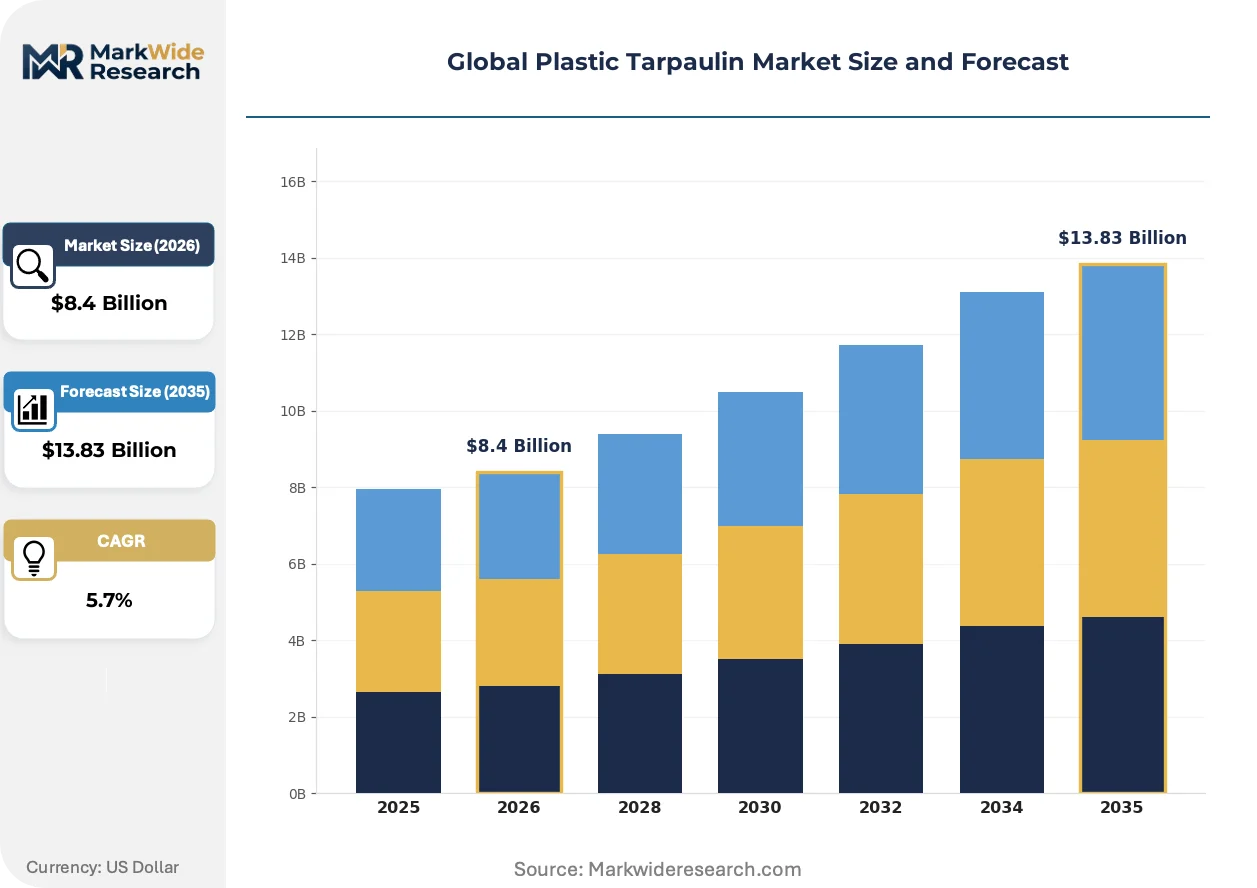
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Tarpaulin, PVC Tarpaulin, Canvas Tarpaulin, Mesh Tarpaulin, Laminated Tarpaulin Application: Construction Covering, Agricultural Sheeting, Transportation Protection, Event Shelters, Packaging Material End User: Farm Operators, Construction Contractors, Transport Companies, Event Organizers, Warehousing Providers Distribution Channel: Wholesale Distributors, Retail Outlets, Online Platforms, Direct Sales, Specialty Traders |
| Companies Covered | Shur-Co LLC, Polytuf Products, Sioen Industries, Fulin Plastic Industry Co. Ltd., KSA Polymer, Heytex Brandenburger GmbH, Tarpaulins Direct Ltd, Sattler AG, Naizil Canada Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Tarpaulin Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to transform how tarpaulin manufacturers formulate coatings, process substrates, and serve end-use verticals across construction, transportation, and temporary architecture.
Coating chemistry is migrating from phthalate-plasticized PVC toward bio-based adipate and citrate ester formulations. German transport fleet operators are specifying these reformulated grades for curtain-sided trailers to preempt REACH enforcement actions. This migration is compressing margins for commodity PVC compounders while rewarding in-house formulation capabilities.
EPA volatile organic compound regulations for coating operations are tightening emission thresholds for solvent-based adhesive lamination. US manufacturers are responding with hot-melt and reactive polyurethane alternatives that eliminate solvent recovery infrastructure. Construction-grade polyethylene sheeting producers in Texas and Louisiana face the steepest compliance cost escalations.
Service unbundling is reshaping buyer-supplier relationships in the transport protection segment. Fleet operators are separating tarpaulin procurement from installation and maintenance services, pressuring distributors to develop in-house technical service capabilities. This pattern is most visible in German and Dutch logistics markets where total-cost-of-ownership purchasing models dominate.
Global Plastic Tarpaulin Market Segmentation
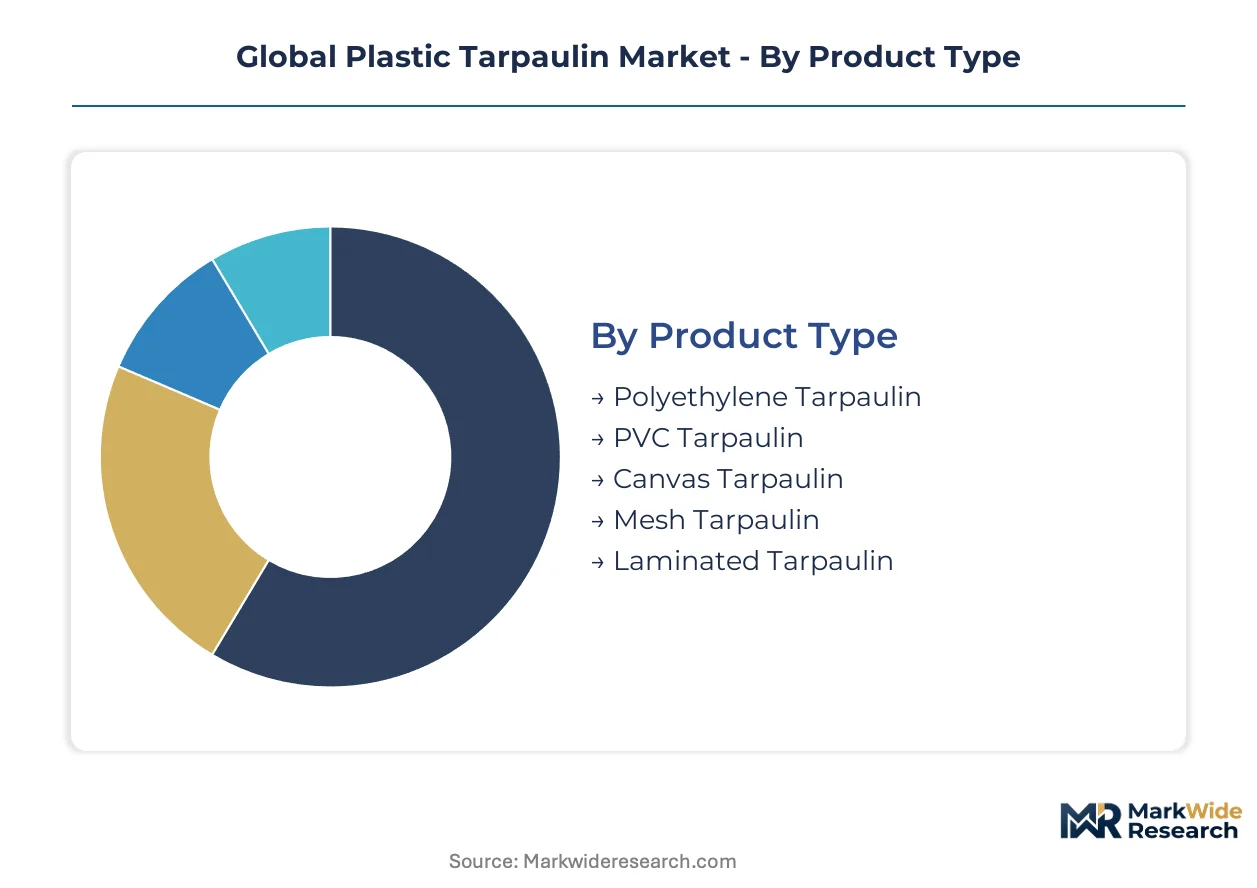
Segmentation in the plastic tarpaulin market reveals distinct performance requirements across material chemistries, end-use exposures, and procurement patterns. Manufacturers configure production lines around these divisions to capture margin premiums in technical grades while maintaining volume throughput in commodity segments.
Product Type:
Material selection spans a use-case spectrum from cost-driven temporary covering to engineered long-life protection, with each chemistry commanding different formulation expertise and capital intensity.
- Polyethylene Tarpaulin:Extrusion-laminated HDPE or LDPE sheets, typically 80–200 gsm, incorporate UV stabilizers and color masterbatch for construction and agricultural deployment. Contractors in India favor reinforced grades for monsoon-site protection, driving volume concentration in Gujarat's petrochemical corridor where resin feedstock costs stay compressed.
- PVC Tarpaulin:Hot-calendered polyester scrim coated with plasticized PVC resin delivers abrasion resistance and weldability for transportation curtains and architectural membranes. German transport fleets specify phthalate-free formulations to satisfy REACH compliance, creating certification premiums that reward in-house compounding capabilities over commodity converters.
- Canvas Tarpaulin:Cotton or polyester canvas substrates treated with wax or synthetic resins serve heritage applications and breathable covering needs.
- Mesh Tarpaulin:Perforated woven structures reduce wind loading and condensation in temporary warehousing and event infrastructure.
- Laminated Tarpaulin:Multi-layer constructions bond woven substrates with extruded films for enhanced puncture resistance in heavy-duty industrial applications.
Established volume favors polyethylene grades; emerging adoption favors mesh architectures for wind-load engineering.
Application:
End-use segmentation tracks asset protection intensity, with exposure duration and environmental severity determining material grade selection and replacement frequency.
- Construction Covering:Polyethylene sheeting shields work sites from precipitation, dust, and debris during building cycles. Brazilian federal housing programs in São Paulo and Rio de Janeiro states are scaling demand for heavy-duty 150-250 gsm grades with reinforced hems and rust-resistant grommets.
- Transportation Protection:Curtain-sided trailers and flatbed coverings require PVC-coated fabrics with tear strength and weld seam integrity. European logistics operators unbundle procurement from installation services, pressuring distributors to develop technical service capabilities for fleet maintenance contracts.
- Agricultural Sheeting:Greenhouse cladding and crop protection films balance light transmission with thermal retention for season extension.
- Event Shelters:Temporary structures demand rapid-deployment fabrics with fire-retardant certification and digital print compatibility for branded environments.
- Packaging Material:Protective wrapping for machinery and palletized goods utilizes lighter-weight laminated constructions.
Construction covering dominates current volume; transportation protection offers the steepest expansion trajectory as fleet specifications tighten.
End User:
Buyer sophistication varies sharply across user categories, with procurement centralization and total-cost-of-ownership analysis concentrating in logistics and construction sectors.
- Construction Contractors:Project-based purchasing of reinforced polyethylene sheeting for weather protection and debris containment. Indian contractors face compressed bidding timelines during pre-monsoon preparation windows.
- Transport Companies:Fleet operators in Germany and the Netherlands specify curtain-sided trailer fabrics through total-cost-of-ownership models that weight durability against maintenance intervals.
- Farm Operators:Seasonal purchasing patterns for greenhouse films and crop covers track planting calendars and harvest protection needs.
- Event Organizers:Temporary structure providers source breathable mesh and printable PVC for branded environments with rapid deployment requirements.
- Warehousing Providers:Logistics real estate operators adopt mesh tarpaulins for temporary storage facilities requiring condensation control and wind-load compliance.
Construction contractors anchor current demand; warehousing providers are gaining share fastest as temporary storage infrastructure expands.
Distribution Channel:
Channel selection reflects order scale, technical specification complexity, and geographic proximity to manufacturing clusters.
- Wholesale Distributors:Regional stockists aggregate construction and agricultural demand, maintaining inventory of standard widths and GSM grades near Gujarat's manufacturing corridor.
- Direct Sales:Large transport fleets and event production companies source technical grades through mill-direct relationships to secure formulation customization and volume pricing.
- Retail Outlets:Hardware and agricultural supply stores serve small-scale farm operators and residential consumers with pre-cut sizes.
- Online Platforms:E-commerce penetration remains limited to standardized dimensions where specification complexity is low.
- Specialty Traders:Technical textile distributors serve architectural membrane and engineered covering applications requiring certification documentation.
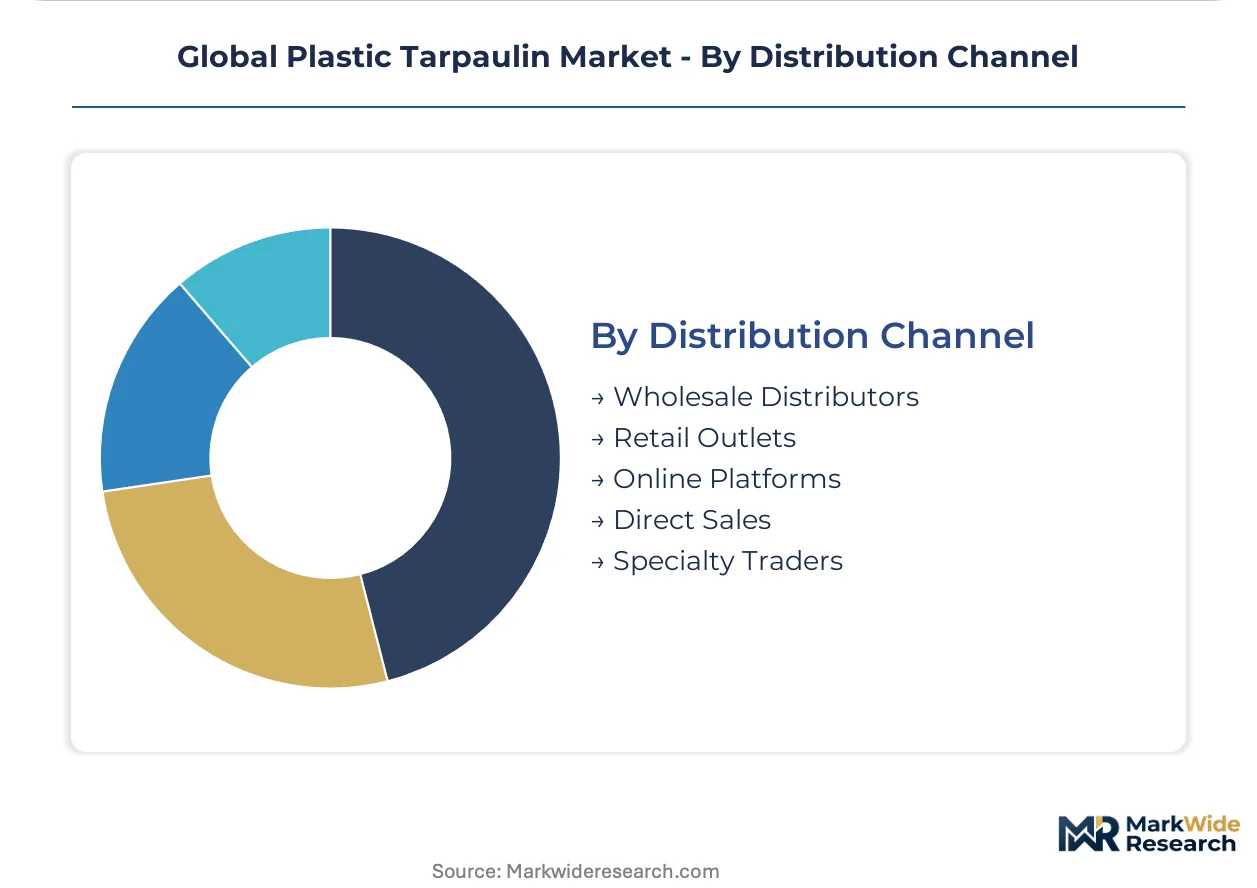
Wholesale distributors capture the deepest volume; direct sales channels are climbing the fastest as fleet procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors in India purchase reinforced polyethylene grades for monsoon protection, while German transport fleets specify phthalate-free PVC formulations—revealing a consumption-mix split between cost-driven temporary covering and compliance-driven technical specifications.
United States
EPA volatile organic compound regulations are tightening emission thresholds for solvent-based adhesive lamination in coating operations. Construction-grade polyethylene sheeting producers in Texas and Louisiana face steep compliance cost escalations as they migrate toward hot-melt alternatives. Houston-area fabricators cluster near petrochemical feedstock suppliers to compress logistics costs.
Germany
German transport fleet operators specify phthalate-free PVC formulations for curtain-sided trailers to preempt REACH enforcement actions. ECHA restrictions on hazardous additive chemistries create certification premiums that reward in-house compounding capabilities. Technical textile distributors in North Rhine-Westphalia serve logistics markets through total-cost-of-ownership purchasing models.
India
BIS mandates tensile strength benchmarks for construction-grade polyethylene sheeting under IS 7903, elevating compliance costs for commodity producers. Contractors scale purchases of 120-200 gsm UV-stabilized grades during pre-monsoon preparation windows. Fabricators cluster in Gujarat's chemical manufacturing corridor near petrochemical feedstock suppliers.
Brazil
Federal housing programs and highway construction in São Paulo and Rio de Janeiro states generate demand for heavy-duty 150-250 gsm construction covering. ANVISA-equivalent industrial safety frameworks influence material selection for temporary worker protection. Regional distributors aggregate demand from infrastructure contractors facing compressed bidding timelines.
China
Zhejiang province fabricators dominate Asian export volumes through integrated extrusion lines serving global construction and agricultural markets. MEE environmental standards tighten wastewater discharge requirements for coating operations. Fulin Plastic Industry Co. Ltd. anchors production gravity in the Yangtze River Delta manufacturing belt.
Global Plastic Tarpaulin Market Competitive Landscape
Capability concentration sits with European compounders possessing in-house formulation expertise; scale advantage sits with Asian producers operating integrated extrusion corridors. The market structures around three archetypes: technical specialists commanding certification premiums, integrated commodity producers capturing volume throughput, and regional distributors developing service capabilities. Dominant competitive moves include backward integration into resin compounding and geographic expansion through distributor acquisition.
Among European technical textile specialists, Sioen Industries and Heytex Brandenburger GmbH exemplify the premium-tier positioning built on coating chemistry capabilities. At the Asian scale-driven end, Fulin Plastic Industry Co. Ltd. represents integrated production architecture. These three anchors illustrate how competitive positioning diverges between formulation-led certification premiums and extrusion-led cost compression.
| Leading Market Players |
|---|
| Shur-Co LLC |
| Polytuf Products |
| Sioen Industries |
| Fulin Plastic Industry Co. Ltd. |
| KSA Polymer |
| Heytex Brandenburger GmbH |
| Tarpaulins Direct Ltd |
| Sattler AG |
| Naizil Canada Inc. |
| Others |
Supply & Pricing Matrix
Gujarat's petrochemical corridor concentration compresses resin feedstock costs for integrated fabricators while margin pools migrate downstream toward aftermarket service layers including repair patches, grommet replacement, and UV-recoating operations. This upstream-downstream tension rewards compounders with captive formulation expertise over commodity converters dependent on spot resin markets.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated extrusion operators and construction contractors in India, while spot purchasing persists for small-scale agricultural buyers. Three-tier pricing structure across premium REACH-compliant PVC, mid-grade reinforced polyethylene, and economy non-UV-stabilized sheeting reflects certification grade and volume scale. Pricing pressure stems from crude oil volatility transmitting through naphtha and ethylene feedstock costs. Fleet operators in Germany exhibit lowest price sensitivity due to total-cost-of-ownership purchasing models, whereas Indian construction contractors face acute margin compression during pre-monsoon bidding windows.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Fulin Plastic Industry Co. Ltd. in Zhejiang province, Sioen Industries in Belgium, and Heytex Brandenburger GmbH in Germany. Raw material dependencies rest on polyethylene and PVC resin supplies from Gulf Coast petrochemical complexes, Saudi ethylene crackers, and Chinese coal-to-olefins facilities. Single-source vulnerability concentrates in Gujarat's chemical manufacturing corridor where regional logistics disruptions cascade through fabricator networks. Distribution runs through wholesale distributors aggregating construction and agricultural demand near manufacturing clusters, with direct sales channels climbing fastest as fleet procurement centralizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue for repair, recoating, and grommet replacement is expanding faster than hardware sales, repositioning margin capture toward recurring-revenue business models. This service-attach dynamic favors incumbents with installed base access and technical service infrastructure.
For Market Incumbents: Pre-empt margin erosion in commodity polyethylene grades by backward integration into resin compounding and captive UV-stabilizer formulation. Defend against Asian scale players by deepening certification moats around REACH-compliant PVC and phthalate-free plasticizer expertise. Prioritize distributor acquisition in Brazil's São Paulo and Rio de Janeiro corridors to capture federal infrastructure spending. For New Entrants and Emerging Players: Pursue white-space opportunity in Brazilian heavy-duty construction covering where domestic supply lags federal housing program demand. Target warehousing providers adopting mesh tarpaulins for temporary storage facilities as the most penetrable end-use segment with limited incumbent service coverage. Lead with digital printing integration offering on-demand branded production for event organizers. For Investors and Strategic Acquirers: Capital is best deployed toward technical specialists commanding certification premiums in European transport protection and architectural membrane derivatives. Long-term viability hinges on formulation capabilities surviving REACH chemistry restrictions and extended producer responsibility mandates. Watch for inflection signals in state-level plastic waste rules across India triggering product redesign requirements and feedstock cost shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of phthalate-free PVC formulations secures REACH compliance margins for European transport fleet contracts. |
| Aftermarket Service Infrastructure Buildout | Repair patch and UV-recoating capabilities capture recurring revenue from construction contractors in India's monsoon cycles. |
| Digital Printing System Integration | UV-curable inkjet convergence enables on-demand branded tarpaulin production for event organizers and retail applications. |
| Geographic Expansion through Distributor Acquisition | Control of Brazilian regional distributors aggregates demand from federal highway and housing construction programs. |
| Design-for-Recycling Architecture Development | Extended producer responsibility mandates in the European Union incentivize take-back programs and recyclable multi-layer constructions. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers at extrusion facilities, procurement leads at German transport fleets, distribution channel partners in Gujarat's chemical corridor, and aftermarket service heads; and secondary validation through customs and trade data, BIS certification registries, SEC filings of listed textile manufacturers, and ECHA REACH substance restriction updates. Bottom-up volume estimates from production line capacities and top-down demand calibration from end-use consumption patterns were triangulated for convergence.
Forecast inputs span material chemistry segments, end-use application intensity, and regional regulatory clusters across the projection horizon. CAGRs were derived from segmented growth rate modeling applied to baseline consumption figures. Industry-specific inputs include monsoon-season construction procurement cycles in India, REACH compliance transition timelines in the European Union, and federal infrastructure program allocations in Brazil.
Sensitivities concentrate around crude oil price volatility transmitting through resin feedstock costs, extended producer responsibility mandate implementation timelines in the European Union, and mechanical recycling technology breakthroughs affecting circular economy business models. Cross-checking against petrochemical industry capacity expansion announcements and regional logistics cost indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
United Kingdom Plastic Bottles Market