
 Plastic Carboy Market | 2026-2036
Plastic Carboy Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Carboy Market Analytics
REACH compliance in Europe is rebalancing the cost-of-entry calculus for imported resin formulations, forcing suppliers to document full substance inventories before market access. Thermo Fisher Scientific leverages its laboratory-grade certification infrastructure to sustain premium positioning in pharmaceutical and biotech channels. Veritiv anchors North American distribution through its integrated packaging supply network, while Qorpak specializes in custom closure and port configurations for niche research applications.
Plastic carboys are rigid, cylindrical containers typically molded from high-density polyethylene or polycarbonate, ranging from one to fifteen gallons in nominal capacity, designed for storage and transport of liquids in controlled environments. HDPE variants withstand autoclave sterilization cycles up to 121 degrees Celsius, making them indispensable in pharmaceutical buffer preparation and chemical reagent handling. Wide mouth carboys capture the fastest growth trajectory as powder handling and solid media preparation expand in bioprocessing workflows, while medical grade material commands the deepest margin pool due to extractables testing and USP Class VI validation requirements. Standard carboys retain volume leadership in beverage bulk dispensing where cost sensitivity dominates procurement criteria.
FDA food-contact substance notifications, EU REACH Annex XVII restrictions on phthalate plasticizers, and ISO 9001 quality management certifications collectively define the compliance perimeter for resin converters and finished goods molders. These frameworks elevate testing burdens but simultaneously lock out uncertified competitors, concentrating supply relationships with laboratories and manufacturers that maintain documented quality systems. Stakeholders must monitor pending revisions to California Proposition 65 labeling requirements and the EU's Packaging and Packaging Waste Regulation, as both will alter material selection criteria and end-of-life recovery obligations without grandfathering existing inventory.
Market Dynamics
REACH Annex XVII restrictions on phthalate plasticizers are compressing formulation flexibility for European resin converters while simultaneously locking in premium pricing for certified suppliers. The regulatory tightening is redrawing competitive boundaries across pharmaceutical and beverage packaging channels.
Growth Catalysts
- Bioprocessing Workflow Expansion:Powder handling and solid media preparation in cell culture operations are pulling wide-mouth carboy configurations into high-volume procurement cycles. Contract manufacturing organizations in Germany's precision manufacturing corridor are standardizing these formats.
- USP Class VI Validation Requirements:Medical-grade material certification creates margin pools that justify dedicated production lines. Extractables testing protocols filter out commodity competitors in pharmaceutical buffer preparation.
- Craft Brewing Procurement:Specialty beverage producers are consolidating bulk dispensing around food-grade HDPE containers with tamper-evident closures. India's expanding pharmaceutical packaging belt is replicating this specification discipline.
Market Restraints
- Resin Input Volatility:High-density polyethylene feedstock costs track naphtha and natural gas liquid pricing with limited hedging instruments available to mid-scale molders.
- Supply Concentration Risk:Food-grade polymer certification infrastructure clusters among a narrow set of laboratory service providers, creating bottleneck vulnerability for new market entrants.
- Glass Substitution Threat:Borosilicate carboys retain preference in analytical laboratories requiring optical clarity and thermal shock resistance beyond polycarbonate limits.
Strategic Opportunities
- India's Pharmaceutical Belt:CDMO capacity expansion in Hyderabad and Ahmedabad is generating demand for validated single-use fluid handling systems with documented chain-of-custody.
- California Proposition 65 Labeling:Pending disclosure requirements for bisphenol-A traces will favor suppliers with preemptive testing documentation, compressing competitor response windows.
- Autoclavable Port Integration:Convergence of sterile welding technology with molded container design enables closed-system media preparation in advanced therapy manufacturing.
Industry Challenges
- Extractables Testing Timeline:USP Class VI validation cycles extend 12-18 months, freezing product development pipelines for reformulated resins.
- Legacy Equipment Retrofit:Pharmaceutical manufacturers face integration friction when connecting new carboy dimensions to existing filling and capping automation lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Carboy Market |
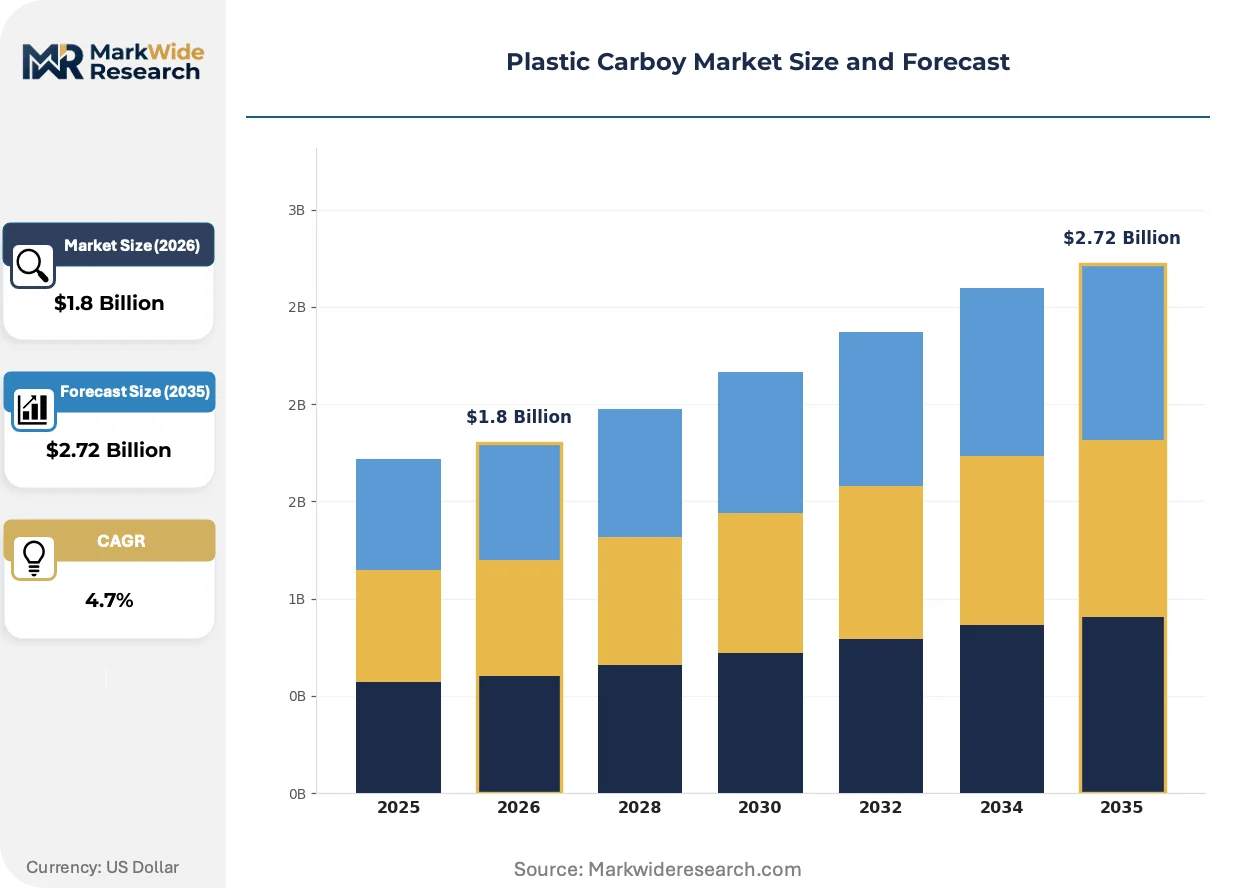
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Carboys, Narrow Mouth Carboys, Wide Mouth Carboys, Custom Carboys End User: Beverage Industry, Pharmaceutical, Chemical Manufacturing, Home Brewing Size: 1 Gallon, 5 Gallon, 10 Gallon, 15 Gallon Material Grade: Food Grade, Industrial Grade, Medical Grade, Recyclable |
| Companies Covered | Veritiv, Thermo Fisher Scientific, Globe Scientific, Sterlitech, Deluxe Scientific Surgico, Marin Scientific Development, Metro Ace Innovplas, Subhang Capsas, Qorpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Carboy Market Evolving Landscape
Material science advances and regulatory disclosure mandates are converging to reshape container specification standards. Suppliers are racing to document full substance inventories ahead of compliance deadlines.
Gamma-stable fluoropolymer liners are expanding into cell and gene therapy manufacturing workflows where single-use sterility assurance is non-negotiable. Biologics contract manufacturers in Switzerland and Massachusetts are adopting these configurations for viral vector production. The technology is expanding into adjacent perfusion bioreactor applications previously served by stainless steel vessels.
EU REACH substance of very high concern candidate list expansion is forcing resin converters to reformulate plasticizer packages and accelerate alternative substance qualification. The industrial consequence is a bifurcation between grandfathered inventory and next-generation formulations with diverging extractables profiles. Pharmaceutical packaging buyers in the Netherlands and Denmark are demanding full SCIP database disclosure before contract renewal.
Bulk procurement consolidation among craft beverage distributors is compressing supplier counts and extending contract durations in exchange for volume commitments. Regional brewing cooperatives in Bavaria and Colorado are pooling specifications to extract pricing leverage. This pattern is most visible in five-gallon dispensing formats where interchangeability reduces SKU complexity for taproom operations.
Plastic Carboy Market Segmentation
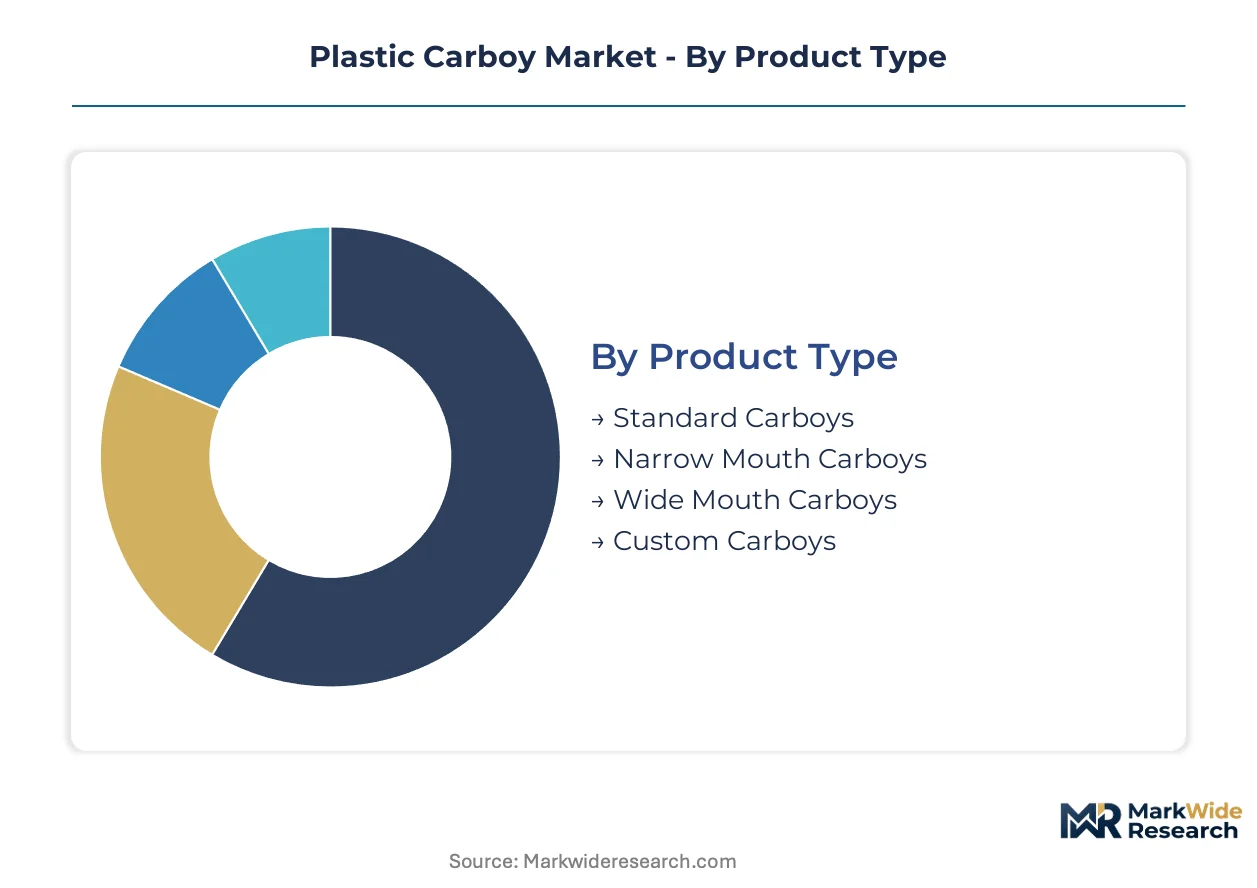
Carboy segmentation separates commodity bulk storage from validated fluid handling systems. Specification tiers determine margin pools, with medical-grade certification commanding premiums against beverage-grade standard formats. Procurement patterns diverge sharply across these boundaries.
Product Type:
Standalone dispensing formats dominate beverage and home brewing channels, while embedded system integration shapes pharmaceutical and chemical manufacturing procurement.
- Standard Carboys:HDPE containers with fixed neck configurations serve high-volume beverage dispensing and chemical reagent storage. India's pharmaceutical packaging belt and Bavarian brewing cooperatives anchor procurement volumes where cost sensitivity dominates specification discipline.
- Wide Mouth Carboys:Powder handling and solid media preparation in cell culture operations pull this configuration into high-volume cycles. Contract manufacturing organizations in Germany's precision manufacturing corridor are standardizing these formats for bioprocessing workflows.
- Narrow Mouth Carboys:Optimized for liquid-only handling in analytical laboratories requiring controlled pour characteristics.
- Custom Carboys:Engineered port configurations and closure systems for niche research applications with specialized sterility requirements.
Standard carboys lead volumes today; wide mouth configurations are gaining share fastest.
End User:
Cost tier stratification separates validated pharmaceutical systems from commodity beverage containers, with certification burden as the dividing mechanism.
- Pharmaceutical:USP Class VI validation and extractables testing create margin pools justifying dedicated production lines. Buffer preparation and single-use fluid handling in CDMO facilities demand documented chain-of-custody.
- Beverage Industry:Food-grade HDPE with tamper-evident closures consolidates bulk dispensing procurement. Craft brewing segments in Colorado and specialty water producers drive specification discipline.
- Chemical Manufacturing:Autoclavable configurations withstand sterilization cycles up to 121 degrees Celsius for reagent handling.
- Home Brewing:Five-gallon dispensing formats dominate where interchangeability reduces SKU complexity for small-scale operations.
Beverage applications lead volumes today; pharmaceutical end use is climbing the fastest.
Size:
Volume scale determines automation compatibility and logistics economics across manufacturing and distribution channels.
- 5 Gallon:The interchangeability sweet spot for taproom operations and regional brewing cooperatives. Bavarian and Colorado distributors consolidate procurement around this format to extract pricing leverage through pooled specifications.
- 15 Gallon:Bulk manufacturing scale for pharmaceutical buffer preparation and chemical reagent production. Integration friction with existing filling lines constrains adoption velocity.
- 1 Gallon:Laboratory-scale handling for analytical applications and small-batch research workflows.
- 10 Gallon:Mid-scale processing for pilot manufacturing and specialty beverage batch production.
Five-gallon formats lead volumes today; fifteen-gallon configurations are expanding most quickly.
Material Grade:
Certification depth stratifies pricing tiers, with regulatory disclosure mandates reshaping supplier qualification requirements.
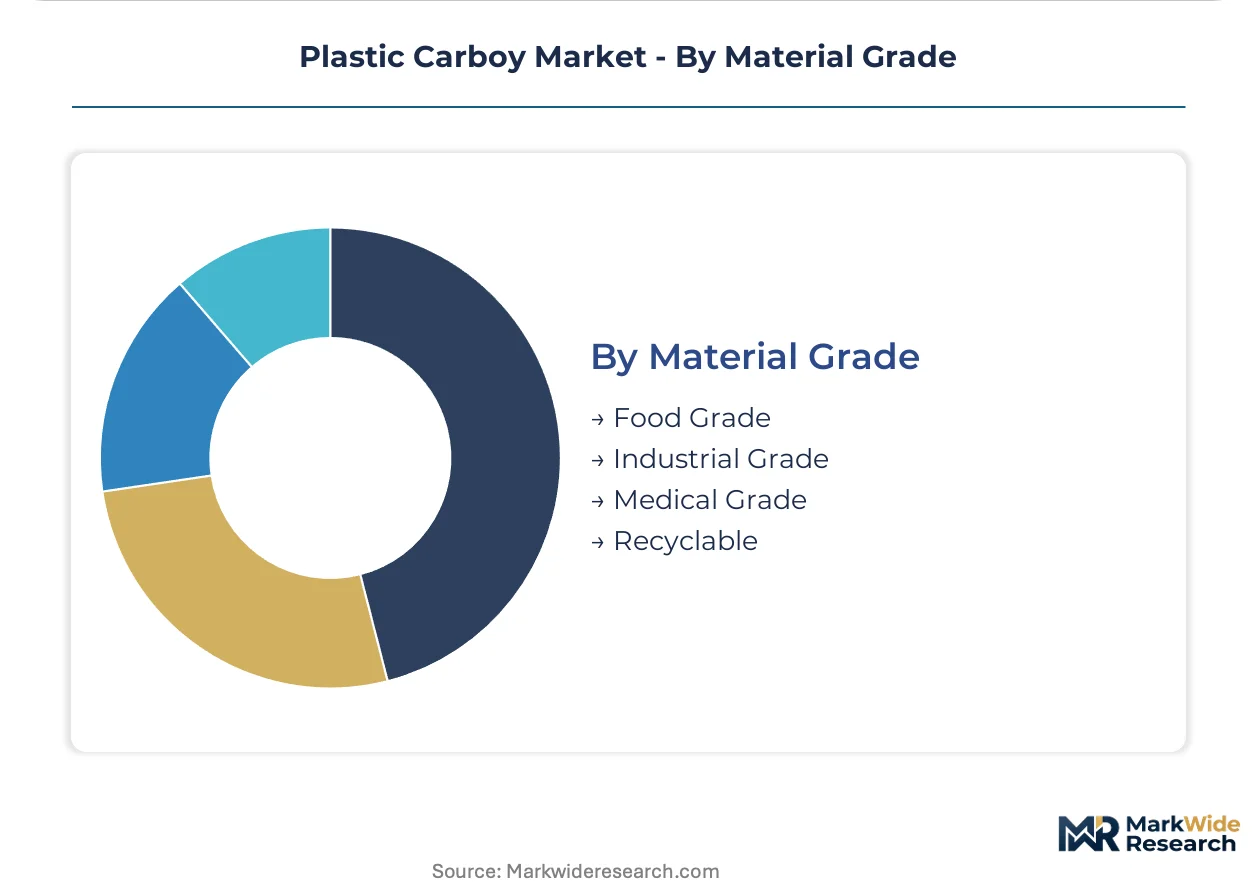
- Medical Grade:Extractables testing protocols and USP Class VI validation filter out commodity competitors. Gamma-stable fluoropolymer liners expand into cell and gene therapy manufacturing where single-use sterility assurance is non-negotiable.
- Food Grade:FDA food-contact substance notifications and evolving notification requirements tighten material certification standards. REACH Annex XVII restrictions on phthalate plasticizers compress formulation flexibility for European resin converters.
- Industrial Grade:Chemical resistance specifications for manufacturing environments without pharmaceutical validation burden.
- Recyclable:End-of-life recovery obligations under pending EU Packaging and Packaging Waste Regulation reshape material selection criteria.
Food grade leads volumes today; medical grade is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale plastic carboy production first scaled in post-war Germany's precision manufacturing corridor, then diffused to North American packaging hubs and Asia-Pacific pharmaceutical belts. Today's demand geography reflects this lineage: validated fluid handling systems concentrate in German and Swiss bioprocessing clusters, while high-volume beverage dispensing anchors in North American craft brewing regions and India's expanding pharmaceutical packaging belt.
United States
FDA food-contact substance notifications and evolving notification requirements tighten material certification standards for polymer resins entering beverage and pharmaceutical channels. Colorado's regional brewing cooperatives consolidate procurement around five-gallon dispensing formats, extracting pricing leverage through pooled specifications and extended contract durations.
Germany
ECHA REACH Annex XVII restrictions on phthalate plasticizers compress formulation flexibility for European resin converters while locking in premium pricing for certified suppliers. Bavaria's precision manufacturing corridor hosts contract manufacturing organizations standardizing wide-mouth carboy configurations for bioprocessing workflows and powder handling operations.
India
CDSCO pharmaceutical packaging regulations and FSSAI food-grade certification requirements reshape procurement specifications for domestic and export-oriented manufacturers. Hyderabad and Ahmedabad's pharmaceutical belt generates demand for validated single-use fluid handling systems with documented chain-of-custody for CDMO capacity expansion.
Switzerland
Swissmedic medical device regulations and EU REACH alignment create dual compliance burdens for biologics contract manufacturers. Cell and gene therapy manufacturing workflows in Basel and Zurich adopt gamma-stable fluoropolymer liners where single-use sterility assurance is non-negotiable.
Netherlands
EU SCIP database disclosure requirements and pending Packaging and Packaging Waste Regulation reshape material selection criteria and end-of-life recovery obligations. Pharmaceutical packaging buyers in Amsterdam and Rotterdam demand full substance inventory documentation before contract renewal, filtering uncertified competitors.
Plastic Carboy Market Competitive Landscape
The competitive structure tilts toward laboratory-grade certification specialists with captive testing infrastructure. Three tiers define the vendor map: integrated scientific supply conglomerates with global distribution networks, regional packaging distributors with custom closure capabilities, and niche research specialists with engineered port configurations. Capacity expansion and strategic partnerships dominate competitive moves, with players securing dedicated production lines for USP Class VI validated materials.
Among North American scientific supply conglomerates, Thermo Fisher Scientific exemplifies the premium-tier archetype through its laboratory-grade certification infrastructure. Veritiv anchors distribution scale through integrated packaging supply networks spanning procurement and logistics. Qorpak occupies a specialist position, representing the custom configuration archetype for niche research applications with specialized sterility requirements.
| Leading Market Players |
|---|
| Veritiv |
| Thermo Fisher Scientific |
| Globe Scientific |
| Sterlitech |
| Deluxe Scientific Surgico |
| Marin Scientific Development |
| Metro Ace Innovplas |
| Subhang Capsas |
| Qorpak |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap molders in Germany's precision manufacturing corridor anchor supply discipline through generational capital commitments, insulating premium-tier pricing from resin volatility while compressing margins for commodity-grade competitors dependent on spot-market polyethylene feedstock.
Pricing Analysis
Three-tier pricing structure across medical, food, and industrial grade levels stratifies the market, with USP Class VI certification and extractables testing protocols commanding substantial premiums over beverage-grade HDPE containers. Price differentiation rests on validation burden and sterilization compatibility rather than raw material cost alone. Cost compression in standard carboy tiers is intensifying because bulk procurement consolidation among Bavarian and Colorado brewing cooperatives extracts volume leverage. Beverage distributors exhibit the highest price sensitivity, while pharmaceutical CDMOs prioritize documented chain-of-custody over unit economics.
Supply Chain Analysis
Returns and end-of-life recovery flows are gaining structural importance as pending EU Packaging and Packaging Waste Regulation reshapes producer obligations without grandfathering existing inventory. Manufacturing concentrates in Germany, India, and the United States, with Hyderabad's pharmaceutical belt and Bavaria's precision corridor serving distinct specification tiers. Resin converters draw from high-density polyethylene and polycarbonate feedstocks tethered to naphtha and natural gas liquid pricing. Single-source vulnerability clusters in laboratory-grade certification infrastructure, where Thermo Fisher Scientific and narrow specialist providers control validation pipelines. Distribution runs through integrated scientific supply networks and regional packaging distributors with custom closure capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic carboy market functions as a stable compounder, with regulatory certification requirements creating durable moats that sustain incumbent positioning across economic cycles.
For Market Incumbents: Deploy captive laboratory-grade certification infrastructure to deepen pharmaceutical and biotech channel lock-in. Expand dedicated production lines for gamma-stable fluoropolymer liners before EU REACH substance of very high concern list expansion accelerates. Glass substitution in analytical laboratories and pending California Proposition 65 disclosure requirements represent the most pressing margin threats. For New Entrants and Emerging Players: The gap between medical-grade USP Class VI validated systems and commodity beverage containers offers entry terrain for mid-tier food-grade specialists. Target India's pharmaceutical packaging belt, where CDMO capacity expansion outruns domestic validation infrastructure. Lead with documented REACH compliance and preemptive SCIP database disclosure to compress incumbent response windows. For Investors and Strategic Acquirers: Laboratory supply conglomerates are the most active acquirer in this space, rolling up regional certification specialists to secure captive testing infrastructure. The five-to-ten year viability window favors platforms with integrated validation pipelines over pure-play molders. Watch for REACH Annex XVII expansion triggering reformulation cycles that freeze smaller competitors' product development pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| USP Class VI Validation Investment | Extractables testing protocols lock out commodity competitors in pharmaceutical buffer preparation. |
| Backward Integration into Resin Compounding | In-house polymer formulation shields margin from naphtha-linked feedstock volatility. |
| Gamma-Stable Fluoropolymer Liner Development | Single-use sterility assurance captures cell and gene therapy manufacturing workflows in Basel and Massachusetts. |
| SCIP Database Pre-Qualification | Full substance inventory disclosure meets Netherlands and Denmark pharmaceutical buyer requirements before contract renewal. |
| Regional Distribution Partnership | Integrated packaging supply networks in North America compress logistics costs for five-gallon beverage dispensing formats. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with resin converter plant managers, pharmaceutical procurement leads at CDMO facilities, beverage distribution channel partners, and laboratory certification specialists with secondary validation against FDA food-contact substance notifications, ECHA REACH Annex XVII filings, customs and trade data for polymer resin flows, and SEC 10-K disclosures from integrated scientific supply conglomerates. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across material grade, end-use industry, product configuration, and regional manufacturing hub drove analytical framework construction throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves and input-cost pass-through coefficients. Modeled inputs included USP Class VI validation cycle timelines, REACH substance of very high concern candidate list expansion trajectories, and craft brewing procurement consolidation patterns.
Caveats apply where resin input volatility, regulatory disclosure mandate acceleration, or glass substitution preference in analytical laboratories could materially shift the outlook. Practitioners should monitor ECHA SVHC list expansion velocity and California Proposition 65 labeling rule finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Italy Plastic Bottles Market