
 Conductive Plastic Boxes Market | 2026-2036
Conductive Plastic Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Plastic Boxes Market Outlook
China is reshaping supply dynamics through expanded polymer compounding capacity serving Asia-Pacific electronics corridors. BASF SE leverages its integrated carbon black and masterbatch operations to sustain cost advantages across conductive formulations. RTP Company anchors North American demand with application-specific compounding expertise in anti-static and EMI-shielding grades. SABIC competes through petrochemical backward integration into specialized polyolefin substrates.
Conductive plastic boxes are engineered enclosures incorporating carbon-based or metallic fillers within thermoplastic matrices to achieve surface resistivity between 10³ and 10¹¹ ohms per square, dissipating electrostatic discharge during handling of sensitive semiconductors and electronic components. Standard Boxes dominate volume shipments for routine component protection, while Rackmount Enclosures command premium positioning in telecommunications infrastructure and server deployment. Electronics Packaging represents the fastest-growing application segment as chip fabrication scales drive intensified cleanroom logistics requirements.
FDA and EPA frameworks govern medical device and electronics manufacturing facility standards in the United States, directly influencing material selection and cleanroom certification protocols for conductive packaging systems. ESD Association standards and IEC 61340 specifications define product-level compliance thresholds that determine market access across regulated industrial channels. Stakeholders must monitor evolving semiconductor fabrication node transitions and corresponding ESD sensitivity thresholds to align product development with next-generation component protection requirements.
Market Dynamics
Semiconductor fabrication node transitions below 5nm are tightening ESD sensitivity thresholds, forcing conductive packaging specifications to compress surface resistivity ranges and accelerating material innovation cycles across the supply base.
Growth Catalysts
- RoHS and REACH compliance mandates:European electronics manufacturers face binding restrictions on halogenated flame retardants, compelling migration toward carbon nanotube and inherently conductive polymer formulations that satisfy both ESD performance and environmental standards.
- Cleanroom logistics intensification:Advanced chip packaging facilities in Taiwan and South Korea now require Class 1000-compatible conductive containers with particle emission below 0.5 microns, expanding addressable volume for premium-grade box categories.
- EV power electronics proliferation:Automotive inverter and battery management system assembly lines demand rackmount conductive enclosures capable of dissipating charges during high-voltage component handling, creating dedicated demand streams distinct from general electronics packaging.
Market Restraints
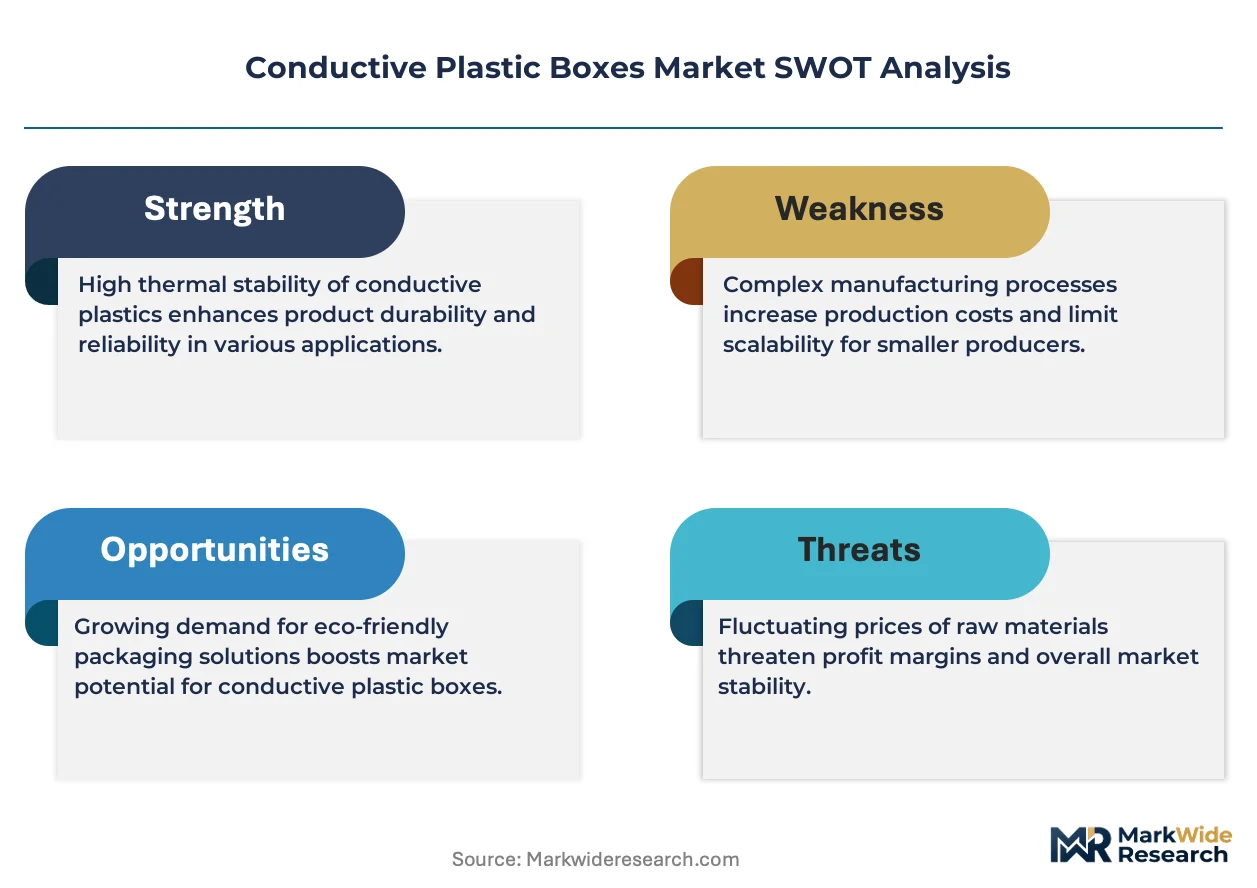
- Carbon black supply concentration:Over sixty percent of conductive filler production clusters in China, exposing compounders elsewhere to freight cost volatility and tariff exposure when sourcing furnace-grade blacks for polypropylene matrices.
- Technical ceiling on polyolefin conductivity:Standard polyethylene and polypropylene substrates face inherent percolation thresholds near 15% filler loading, beyond which mechanical properties degrade and processing becomes uneconomical for thin-walled box designs.
- Substitution by reusable metal systems:High-frequency handlers of premium semiconductors in German and Japanese fabs are reverting to grounded stainless steel tote systems for multi-year lifecycles, compressing replacement demand for disposable conductive plastics.
Strategic Opportunities
- Indian electronics manufacturing zones:PLI scheme subsidies for semiconductor assembly and testing facilities near Gujarat and Tamil Nadu create first-mover positioning for localized conductive box production serving duty-advantaged domestic supply chains.
- Biodegradable conductive compounds:Emerging polylactic acid formulations with graphene loading address medical device packaging applications where single-use sterility conflicts with sustainability mandates from hospital procurement coalitions.
- IEC 61340-5-1 certification expansion:Third-party verification programs now extend to conductive packaging used in explosive atmosphere environments, opening oil and gas instrumentation segments previously served by metal enclosures exclusively.
Industry Challenges
- Compounder technical staffing:Formulation chemists capable of balancing surface resistivity, impact strength, and melt flow index in multi-component systems command premium compensation and remain concentrated at established polymer science hubs.
- Cleanroom validation timelines:New conductive box designs require six-to-nine-month qualification cycles with semiconductor OEMs, delaying revenue recognition and compressing effective product lifecycles before next node transitions obsolete specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Plastic Boxes Market |
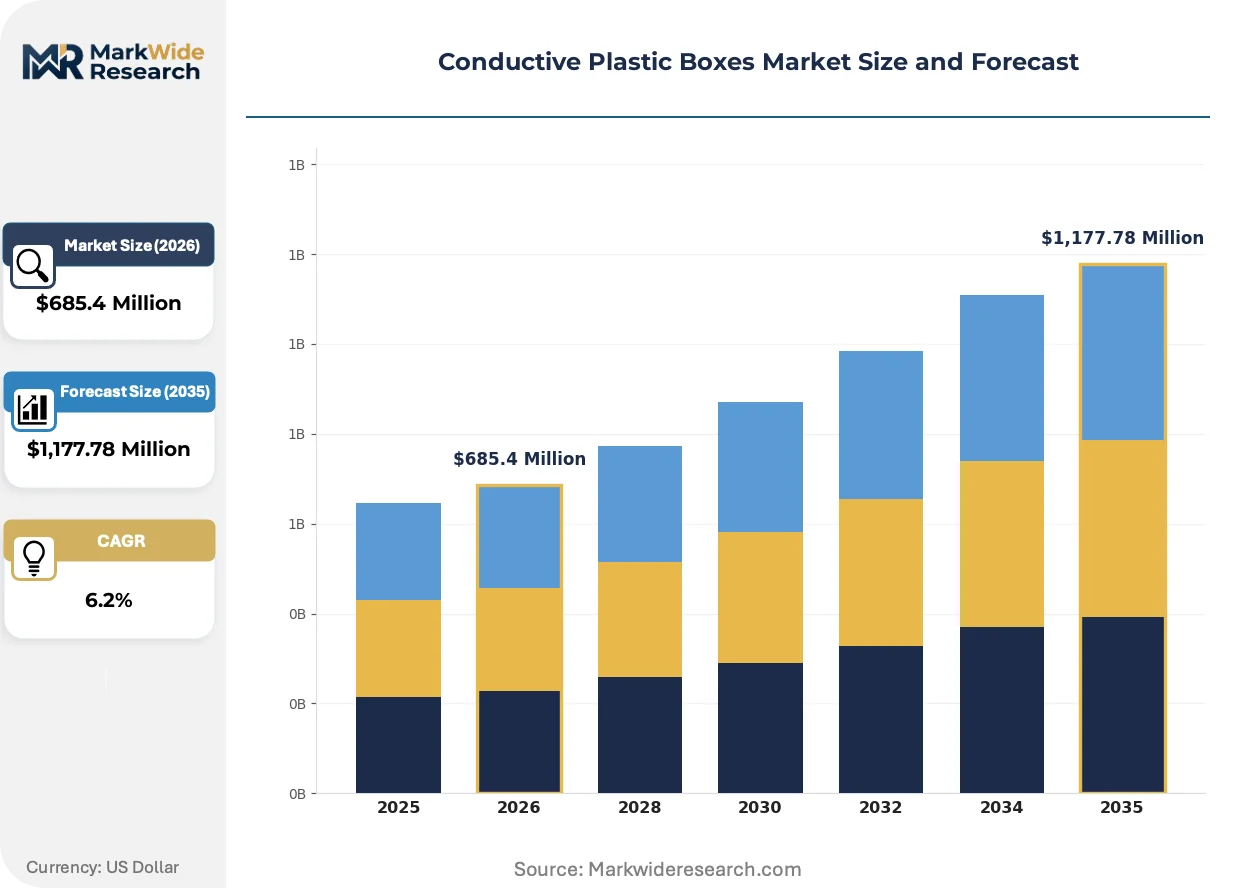
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Boxes, Custom Sizes, Rackmount Enclosures, Stackable Containers Application: Electronics Packaging, Components Storage, Cleanroom Use, Shipping Solutions Material: Polycarbonate, Acrylonitrile Butadiene Styrene, PVC, Polyethylene End User: Telecommunications, Aerospace, Automotive, Medical Devices |
| Companies Covered | BASF SE, RTP Company, Dow Inc., LyondellBasell Industries, Cabot Corporation, Celanese Corporation, DuPont, SABIC, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Plastic Boxes Market Strategic Shifts
Material science breakthroughs and regulatory tightening are converging to redefine performance benchmarks and procurement criteria across conductive packaging applications.
Graphene nanoplatelet masterbatches are achieving percolation thresholds below 5% loading while maintaining surface resistivity below 10⁴ ohms per square. Korean memory manufacturers are qualifying these compounds for DDR5 module shipping trays, drawn by reduced filler content that preserves dimensional stability. Legacy carbon black concentrates at 20-25% loading are rendering obsolete for sub-0.5mm wall thickness applications where warpage control dominates specification compliance.
REACH Annex XVII restrictions on persistent organic pollutants are tightening acceptable impurity levels in recycled conductive feedstocks. Compounders serving Dutch and Belgian electronics clusters must now document full substance inventories through SCIP database filings, adding traceability costs that reshape sourcing economics. Medical device packaging lines in Ireland and Switzerland are responding fastest, requiring virgin-grade conductive resins with certified chain-of-custody documentation.
Consolidated procurement by contract electronics manufacturers is compressing supplier panels and mandating vendor-managed inventory programs. Foxconn and Jabil are transitioning from spot purchasing to three-year framework agreements with compounders holding regional warehouse stocks, displacing traditional distributor intermediaries. This concentration is most visible in Czech and Hungarian manufacturing corridors where automotive electronics assembly feeds directly into German OEM supply chains.
Conductive Plastic Boxes Market Segmentation
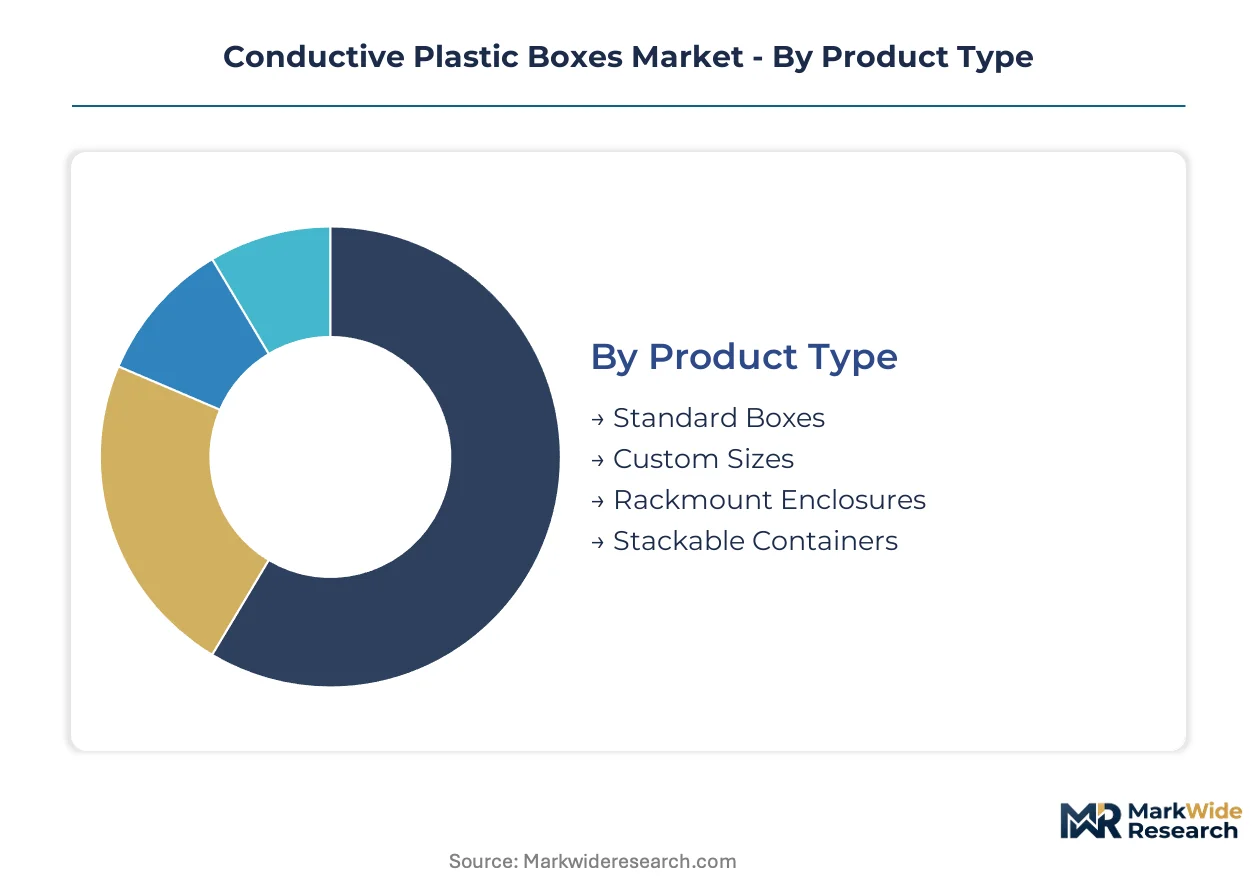
Conductive plastic boxes serve divergent operational requirements across semiconductor handling, medical logistics, and industrial assembly. Segmentation reveals how material specifications, dimensional constraints, and regulatory exposure create distinct procurement channels with limited substitutability.
Product Type:
Form factor selection traces directly to handling frequency, storage density, and integration with automated retrieval systems.
- Standard Boxes:Injection-molded rectangular enclosures with fixed cavity counts serve high-volume component shipping from Taiwanese memory fabs to Malaysian backend facilities. Demand concentrates in DDR module and logic chip tray applications where dimensional repeatability ensures automated handler compatibility.
- Custom Sizes:Application-specific dimensions accommodate irregular component geometries and proprietary automated storage systems. German automotive sensor manufacturers specify these for battery management system module transport, trading unit economics for supply chain integration.
- Rackmount Enclosures:EIA-310 compliant 19-inch widths house server-grade electronics and telecommunications infrastructure during staging and deployment.
- Stackable Containers:Interlocking base-and-lid designs maximize cube utilization in cleanroom vertical storage systems.
The dominant share belongs to Standard Boxes, while Rackmount Enclosures is closing the gap fastest.
Application:
Operating environment severity determines material grade, certification burden, and replacement cycle economics.
- Electronics Packaging:Surface-mount device trays and wafer shipping boxes require Class 1000 cleanroom compatibility with particle emission below 0.5 microns. South Korean foundries drive qualification of carbon nanotube-loaded formulations that satisfy both ESD dissipation and reduced outgassing specifications.
- Cleanroom Use:Permanent storage systems inside semiconductor fabrication bays must withstand repeated autoclave cycles and aggressive chemical wipe-downs. Polycarbonate grades dominate here despite premium positioning.
- Components Storage:Long-term inventory protection in distributor warehouses emphasizes cost efficiency over extreme cleanliness.
- Shipping Solutions:Single-use export packaging prioritizes impact resistance and customs documentation simplicity over reusability.
Electronics Packaging commands the largest revenue pool, with Cleanroom Use expanding most quickly.
Material:
Polymer matrix selection balances conductivity pathway density, mechanical durability, and regulatory compliance exposure.
- Polycarbonate:Amorphous structure delivers optical clarity for component visibility alongside surface resistivity tunable to 10⁴ ohms per square. Medical device packaging lines in Ireland specify virgin-grade resins with certified chain-of-custody documentation.
- Polyethylene:Semi-crystalline structure offers lowest cost per cubic meter but faces percolation thresholds near 15% carbon black loading that constrain thin-wall molding.
- Acrylonitrile Butadiene Styrene:Rubber-modified impact resistance suits handheld tote applications with drop-test requirements.
- PVC:Halogen content triggers REACH Annex XVII restrictions that compounders are abandoning in favor of inherently conductive alternatives.
Polycarbonate holds the premium position, while Polyethylene captures the highest shipment volumes.
End User:
Industry-specific certification regimes and liability exposure create divergent specification tolerances and vendor qualification timelines.
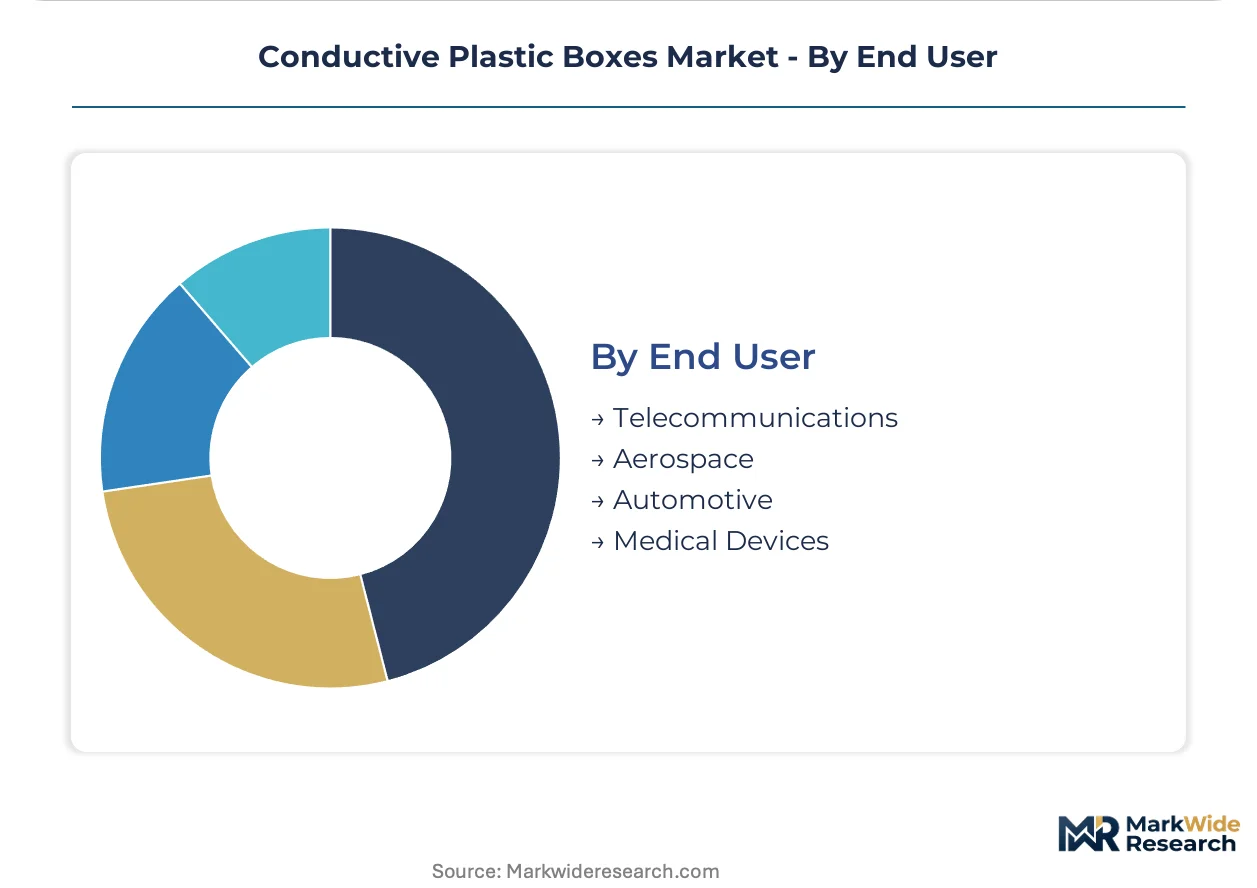
- Telecommunications:Rackmount enclosure demand from 5G infrastructure deployment requires IEC 61340-5-1 certification for explosive atmosphere compatibility in outdoor cabinet installations.
- Automotive:EV power electronics assembly lines demand rackmount conductive enclosures capable of dissipating charges during high-voltage component handling.
- Aerospace:FAA documentation requirements for traceability and flame resistance limit qualified supplier pools.
- Medical Devices:FDA 21 CFR Part 820 quality system regulations govern packaging validation with documented sterility maintenance.
Telecommunications generates the steepest volume expansion, while Medical Devices maintains the tightest margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon black compounding clusters in China expose foreign compounders to freight volatility and tariff exposure when sourcing furnace-grade blacks. Semiconductor fabrication expansion in Taiwan and South Korea drives cleanroom logistics standardization across Asia-Pacific electronics corridors.
Germany
Automotive OEMs and precision electronics clusters in Bavaria and Baden-Württemberg require certified ESD protection for EV power electronics assembly. REACH and RoHS compliance mandates push material innovation toward halogen-free conductive compounds. Stuttgart-based sensor manufacturers specify custom conductive boxes for battery management system module transport.
China
Expanded polymer compounding capacity serves domestic semiconductor backend facilities and export-oriented electronics corridors. MIIT standards govern electrostatic protection in manufacturing facilities. Yangtze River Delta memory fabs drive qualification of carbon nanotube-loaded formulations for DDR5 module shipping trays.
United States
FDA and EPA frameworks govern medical device and electronics manufacturing facility standards, directly influencing material selection protocols. ESD Association standards define product-level compliance thresholds for regulated industrial channels. Texas and Arizona semiconductor fabrication investments intensify demand for Class 1000-compatible conductive containers.
South Korea
Advanced chip packaging facilities now require Class 1000-compatible conductive containers with particle emission below 0.5 microns. MFDS regulations extend to medical electronics packaging validation. Pyeongtaek and Hwaseong foundry clusters drive fastest-growing qualification cycles for next-generation ESD protection specifications.
India
PLI scheme subsidies for semiconductor assembly and testing facilities near Gujarat and Tamil Nadu create first-mover positioning for localized production. BIS certification requirements shape procurement criteria for electronics manufacturing zones. Sanand and Sriperumbudur industrial corridors attract compounders seeking duty-advantaged domestic supply chain integration.
Conductive Plastic Boxes Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in formulation and masterbatch supply. The vendor base spans petrochemical conglomerates with captive carbon black operations, independent compounders with application-specific expertise, and regional fabricators serving localized electronics corridors. Three archetypes dominate: backward-integrated petrochemical majors, specialized conductive compounders, and distributor-forward logistics players. Competitive moves concentrate on regional warehouse stocking for vendor-managed inventory programs and IEC 61340-5-1 certification expansion into explosive atmosphere environments.
Among petrochemical majors with in-house production of specialized polyolefin substrates, BASF SE and SABIC exemplify the backward-integrated archetype. RTP Company occupies a position within the North American specialist tier, representing application-specific compounding expertise in anti-static and EMI-shielding grades. These three anchors illustrate how geographic proximity to carbon black sourcing and semiconductor fabrication clusters determines competitive positioning across conductive formulation supply.
| Leading Market Players |
|---|
| BASF SE |
| RTP Company |
| Dow Inc. |
| LyondellBasell Industries |
| Cabot Corporation |
| Celanese Corporation |
| DuPont |
| SABIC |
| Avient Corporation |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta freight corridors expose compounders to bunker fuel volatility that amplifies cost differentials between carbon black sourcing clusters and semiconductor fabrication demand centers, compressing margins for non-integrated suppliers while rewarding regional warehouse positioning near Taiwanese memory fabs and German automotive electronics clusters.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European electronics corridors, separating virgin-grade polycarbonate formulations with SCIP database documentation from recycled feedstock alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and chain-of-custody completeness. Cost compression in standard polyethylene grades is intensifying because South Korean foundries are qualifying carbon nanotube-loaded compounds that obsolete legacy carbon black concentrates. Contract electronics manufacturers exhibit highest price sensitivity, while medical device packaging lines in Ireland and Switzerland accept premium positioning for FDA-validated materials.
Supply Chain Analysis
Extended payment terms from Foxconn and Jabil are reshaping working capital requirements for compounders serving Czech and Hungarian automotive electronics corridors. Carbon black production clusters in China, furnace-grade black processing in Germany, and carbon nanotube synthesis in South Korea anchor raw material sourcing. Conductive plastic box manufacturing draws from polypropylene matrices, graphene nanoplatelet masterbatches, and polycarbonate resins. Single-source vulnerability concentrates in Chinese carbon black supply, exposing compounders to tariff exposure and freight cost volatility. Distribution runs through vendor-managed inventory programs with regional warehouse stocks, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication node transitions below 5nm are disrupting ESD protection specifications, creating first-mover advantages for compounders qualifying carbon nanotube formulations before next-generation chip packaging standards crystallize.
For Market Incumbents: Build certification moats around IEC 61340-5-1 explosive atmosphere validation to defend against stainless steel tote substitution in German and Japanese fabs. Deepen backward integration into carbon black masterbatch production to offset freight volatility from Chinese sourcing clusters. Anchor capacity additions near Gujarat and Tamil Nadu PLI zones to capture duty-advantaged Indian electronics manufacturing demand. For New Entrants and Emerging Players: Indian electronics manufacturing zones offer the most penetrable white-space opportunity, with Sanand and Sriperumbudur industrial corridors lacking localized conductive box production. Biodegradable conductive compounds for medical device packaging represent a second entry vector where sustainability mandates from hospital procurement coalitions outpace incumbent formulation capabilities. Pursue qualification partnerships with Yangtze River Delta memory fabs seeking carbon nanotube-loaded alternatives to legacy carbon black concentrates. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors with dormant conductive formulation divisions that lack semiconductor industry application expertise. Five-to-ten-year viability hinges on compounder positioning at the intersection of cleanroom logistics intensification and REACH-compliant material innovation. Watch for carbon nanotube percolation threshold breakthroughs below 5% loading as the inflection signal separating obsolete carbon black formulations from next-generation market share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Black Masterbatch | BASF SE's captive carbon black operations insulate margin structures from Chinese supply concentration. |
| IEC 61340-5-1 Certification Expansion | Third-party verification opens oil and gas instrumentation segments previously served by metal enclosures exclusively. |
| Regional Warehouse Stocking Programs | Vendor-managed inventory with Foxconn and Jabil displaces distributor intermediaries in Czech manufacturing corridors. |
| Carbon Nanotube Formulation Qualification | South Korean foundries drive adoption for DDR5 module shipping trays requiring sub-0.5mm wall thickness control. |
| PLI Zone Manufacturing Localization | Gujarat and Tamil Nadu facilities capture duty-advantaged supply chain integration for Indian electronics assembly. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from petrochemical conglomerates, ECHA SCIP database filings, and semiconductor industry capex disclosures. Interviews with polymer formulation chemists, procurement leads at contract electronics manufacturers, cleanroom logistics coordinators, and regulatory compliance officers informed supply-side and demand-side dynamics. Bottom-up shipment estimates from compounder production volumes triangulate against top-down electronics packaging demand projections.
Forecast inputs include semiconductor fabrication node transition timelines, REACH Annex XVII restriction evolution, and carbon black pricing volatility indices. Segmentation dimensions span product type, application severity, polymer matrix, and end-user industry across the projection horizon. CAGRs derive from regression analysis of historical volume-price relationships adjusted for substitution elasticity between conductive plastics and grounded metal systems. Carbon nanotube loading thresholds and cleanroom particle emission specifications serve as technology-specific forecast anchors.
Practitioners should monitor semiconductor fabrication node transitions, REACH restriction expansion, and carbon black supply concentration for early signals of specification obsolescence or input cost disruption. Forecasts reflect assumptions about continued electronics manufacturing zone expansion and sustained ESD sensitivity tightening. Macroeconomic contraction in semiconductor capital expenditure, regulatory acceleration of halogen-free mandates, or breakthroughs in reusable metal tote economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
GCC PET Packaging Market