
 United States PET Packaging Market | 2026-2036
United States PET Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States PET Packaging Market Intelligence
Recycled-content sourcing is reconfiguring margin pools across virgin resin substitution and post-consumer flake procurement. Berry Global leverages its integrated rPET washing and pelletizing infrastructure to secure supply chain position. Plastipak Packaging anchors its competitiveness through proprietary bottle-to-bottle recycling technology. Amcor plc sustains market presence via geographic breadth across multiple US manufacturing regions.
United States PET packaging comprises polyethylene terephthalate containers and films engineered with intrinsic viscosity between 0.72 and 0.82 dL/g, manufactured through stretch blow molding or injection-stretch blow molding to achieve biaxial orientation and barrier performance for carbonated and non-carbonated contents. Bottles dominate product type volume due to beverage industry procurement scale, while trays exhibit structural growth from fresh produce and prepared meal channel expansion. Food & Beverage end users command the largest demand share, with Pharmaceuticals representing a higher-margin segment driven by USP and FDA compliance requirements.
FDA food-contact notification rules, EPA recycled materials standards, and state-level extended producer responsibility frameworks shape material certification pathways and market access conditions for domestic producers. California SB 54 and similar state mandates are forcing capital allocation toward verified recycled-content verification systems. Stakeholders must monitor evolving FDA guidance on chemical recycling feedstocks and state-by-state compliance fragmentation.
Market Dynamics
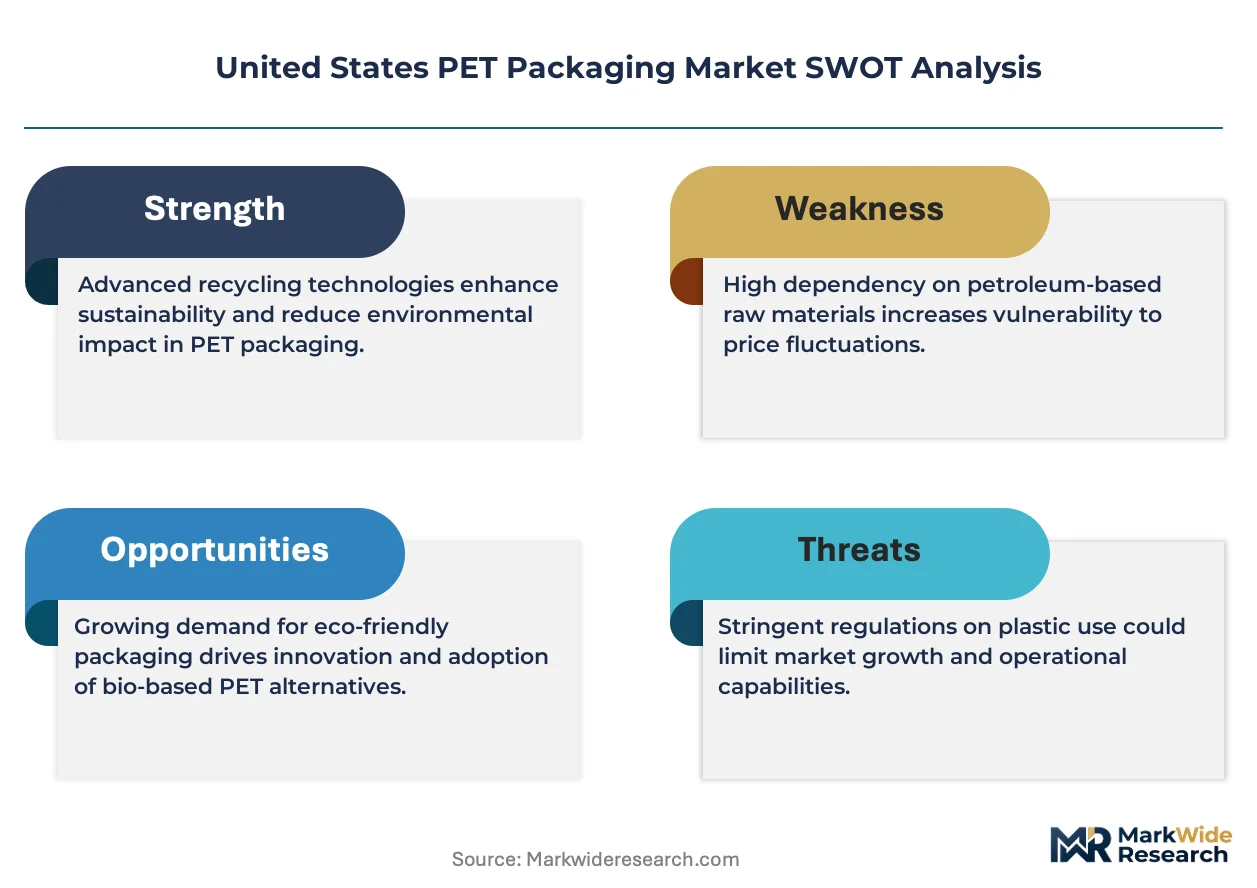
State-level recycled-content mandates are compressing virgin resin demand curves and forcing capital reallocation toward verified rPET infrastructure across the United States.
Growth Catalysts
- California SB 54:The extended producer responsibility framework mandates 25% recycled content in plastic packaging by 2025, creating guaranteed offtake for domestic rPET flake producers.
- Beverage brand procurement:Coca-Cola and PepsiCo bottlers are executing multi-year supply agreements that specify bottle-to-bottle recycled content thresholds, locking in demand visibility.
- Gulf Coast resin cluster:Concentrated ethylene and PTA production along the Texas-Louisiana corridor reduces inbound logistics costs for blow-molding operations serving Southeast distribution networks.
Market Restraints
- rPET feedstock volatility:Post-consumer bottle bale prices swing with collection rates and export competition, compressing margin predictability for reclaimers.
- Mechanical recycling ceiling:Thermal degradation during repeated reprocessing limits rPET to lower-intrinsic-viscosity applications, excluding high-performance barrier bottles.
- Natural gas input exposure:Paraxylene and ethylene glycol production remains tethered to Gulf Coast petrochemical economics, transmitting hydrocarbon price shocks to resin converters.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and glycolysis technologies promise food-contact-grade output from mixed-waste feedstocks, bypassing mechanical recycling purity constraints.
- Pharmaceutical compliance tier:USP <661> and FDA Type III drug master file pathways for PET containers command 40-60% price premiums over beverage-grade equivalents.
- Southeast manufacturing expansion:Georgia and South Carolina offer tax abatements and port access for export-oriented blow-molding capacity serving Caribbean and Latin American markets.
Industry Challenges
- Food-contact notification timelines:FDA's 120-day review window for novel recycling process submissions delays commercial launch schedules and ties up technical staff.
- Legacy blow-molding retooling:Converting single-stage injection-stretch lines to handle 100% rPET requires screw and hot-runner modifications that idle capacity for 6-8 weeks.
- Collection infrastructure gaps:Curbside PET recovery rates vary from 12% to 45% across municipal programs, creating supply uncertainty for planned washing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States PET Packaging Market |
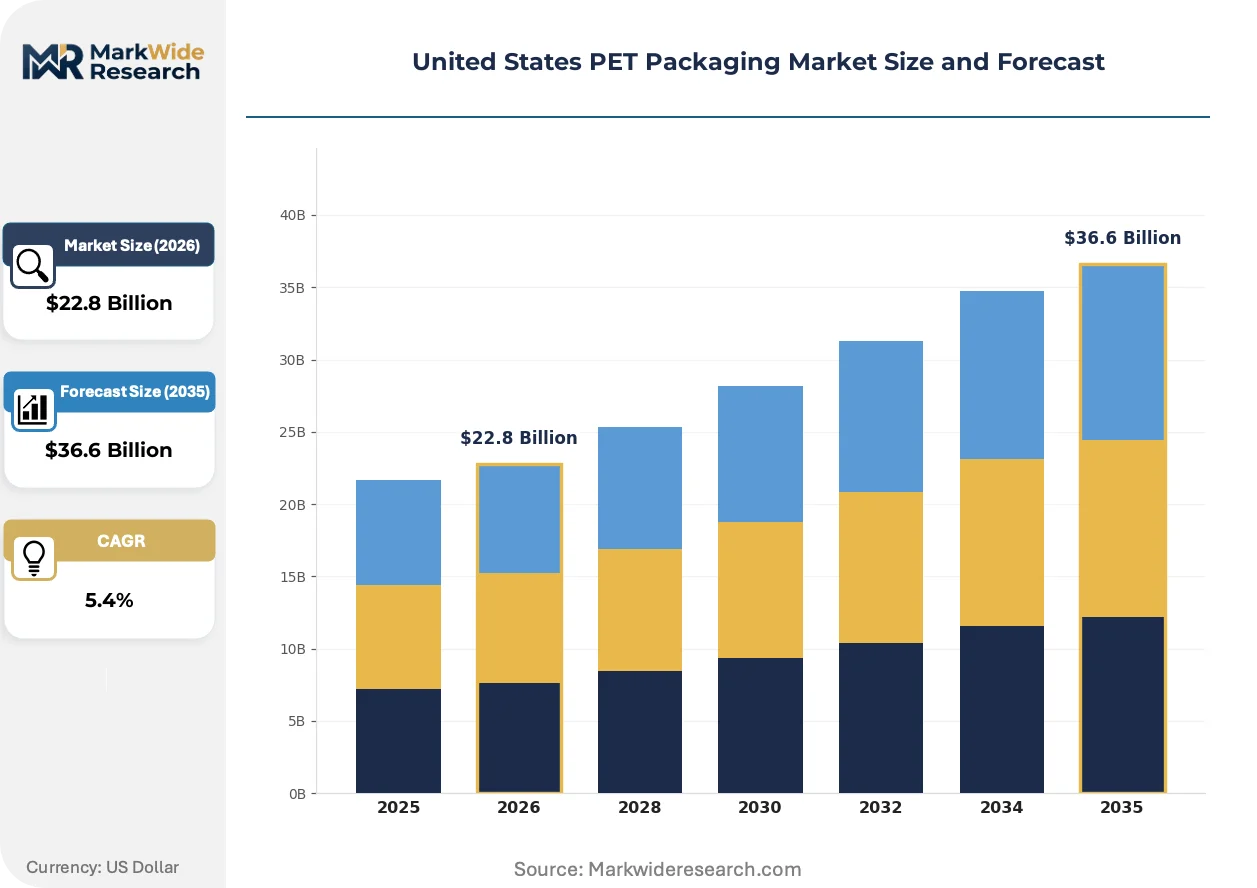
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Trays, Films End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Manufacturing Stage: Preform, Blown, Injection Molded, Thermoformed Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Distributors |
| Companies Covered | Amcor plc, Berry Global, Sonoco Products Company, Plastipak Packaging, Graham Packaging Company, Huhtamaki Oyj, Gerresheimer AG, ALPLA Group, Silgan Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States PET Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory compliance automation are converging to redefine performance specifications and verification protocols across the United States PET packaging value chain.
Advanced glycolysis depolymerization systems are rendering obsolete the mechanical washing and pelletizing infrastructure that has dominated rPET supply for two decades. Food and beverage brand technical teams are piloting these units at commercial scale in Ohio and California facilities. The technology enables direct return to virgin-equivalent intrinsic viscosity without the yellowing and contamination carryover inherent in mechanical routes.
EPA's recycled materials standards and state-level extended producer responsibility frameworks are tightening audit and certification requirements for domestic producers. California's CalRecycle verification protocol now requires mass-balance documentation from flake through finished container. Brand owners serving California distribution channels are absorbing compliance costs or passing them through tiered supplier qualification requirements.
Direct-to-retailer procurement contracts are displacing traditional resin distributor intermediaries in large-volume beverage applications. Walmart and Target beverage category managers are negotiating specification-controlled supply agreements that specify rPET percentage, carbon footprint thresholds, and shelf-ready secondary packaging. This pattern concentrates most visibly in the Southeast and Midwest retail distribution corridors where private-label water and carbonated soft drink volumes have expanded.
United States PET Packaging Market Segmentation
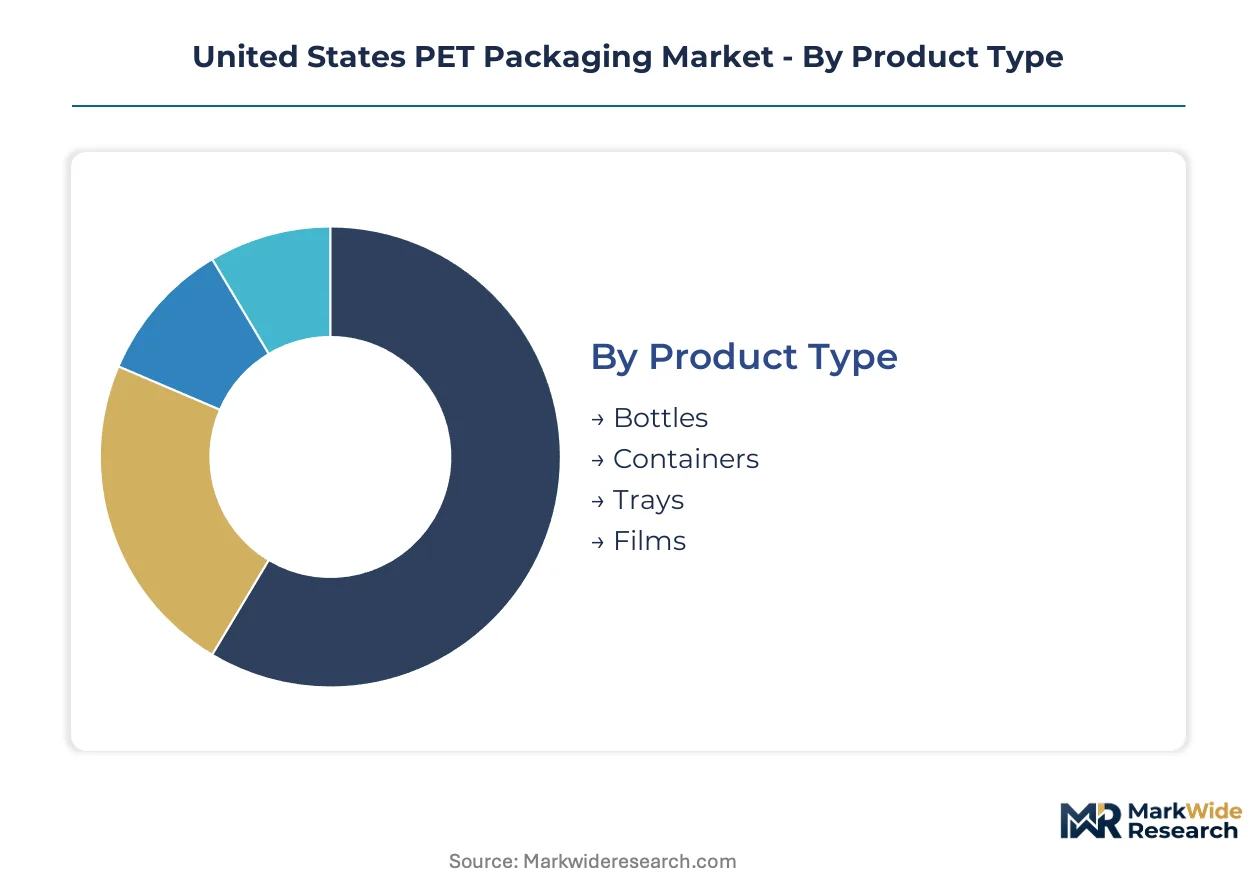
PET packaging segmentation in the United States reveals how manufacturing capabilities, regulatory pathways, and channel economics fragment addressable demand. Each dimension carries distinct margin profiles and capital requirements that shape producer specialization.
Product Type:
Mature blow-molding infrastructure dominates the landscape, while emerging formats exploit material science advances to penetrate adjacent categories.
- Bottles:Stretch blow-molded containers with intrinsic viscosity between 0.72 and 0.82 dL/g serve carbonated and still beverage applications. Procurement concentrates with Coca-Cola and PepsiCo bottlers in the Southeast, where Gulf Coast resin access minimizes inbound logistics costs and state recycled-content mandates lock in multi-year supply agreements.
- Containers:Wide-mouth jars and canisters for food, personal care, and household applications command premium positioning through custom neck finishes and barrier coatings. Demand clusters in Ohio and Illinois manufacturing corridors serving Midwest retail distribution networks, with FDA food-contact notification timelines extending commercialization cycles.
- Trays:Thermoformed structures for fresh produce and prepared meals.
- Films:Biaxially oriented sheet for blister packs and lidding applications.
Bottles handle the majority of throughput; trays are expanding most quickly on share as prepared meal channels penetrate suburban markets.
End User:
Volume concentration diverges sharply from margin concentration across customer categories.
- Food & Beverage:Bottled water and ready-to-drink brands drive procurement scale. Procurement from Walmart and Target beverage category managers now specifies rPET percentage and carbon footprint thresholds, concentrating supply relationships with blow-molders possessing verified recycling infrastructure.
- Pharmaceuticals:USP compliance and FDA Type III drug master file pathways for PET containers command substantial price premiums. Demand centers on New Jersey and Pennsylvania manufacturing clusters serving generic and branded drug distribution, with USP <661> testing protocols extending qualification timelines.
- Personal Care:Cosmetic and hygiene brands emphasizing visual differentiation.
- Household Products:Cleaners and detergents requiring chemical resistance.
Food & Beverage absorbs the greatest resin tonnage; Pharmaceuticals posts the steepest expansion trajectory as generic drug volumes climb.
Manufacturing Stage:
Process selection determines capital intensity, cycle economics, and rPET compatibility boundaries.
- Preform:Injection-molded parisons for subsequent stretch blow molding represent the dominant intermediate format. Production concentrates with Berry Global and Plastipak integrated operations along the Texas-Louisiana corridor, where captive resin supply and rPET washing infrastructure secure margin position.
- Blown:Finished container output from stretch blow molding lines.
- Injection Molded:Direct-to-shape thick-walled containers bypassing preform stage.
- Thermoformed:Sheet extrusion and vacuum forming for trays and clamshells.
Preform operations capture the greatest capital deployment; thermoforming gains share fastest as fresh produce retailers convert from polystyrene.
Distribution Channel:
Channel restructuring is compressing intermediary margins and rewriting specification control.
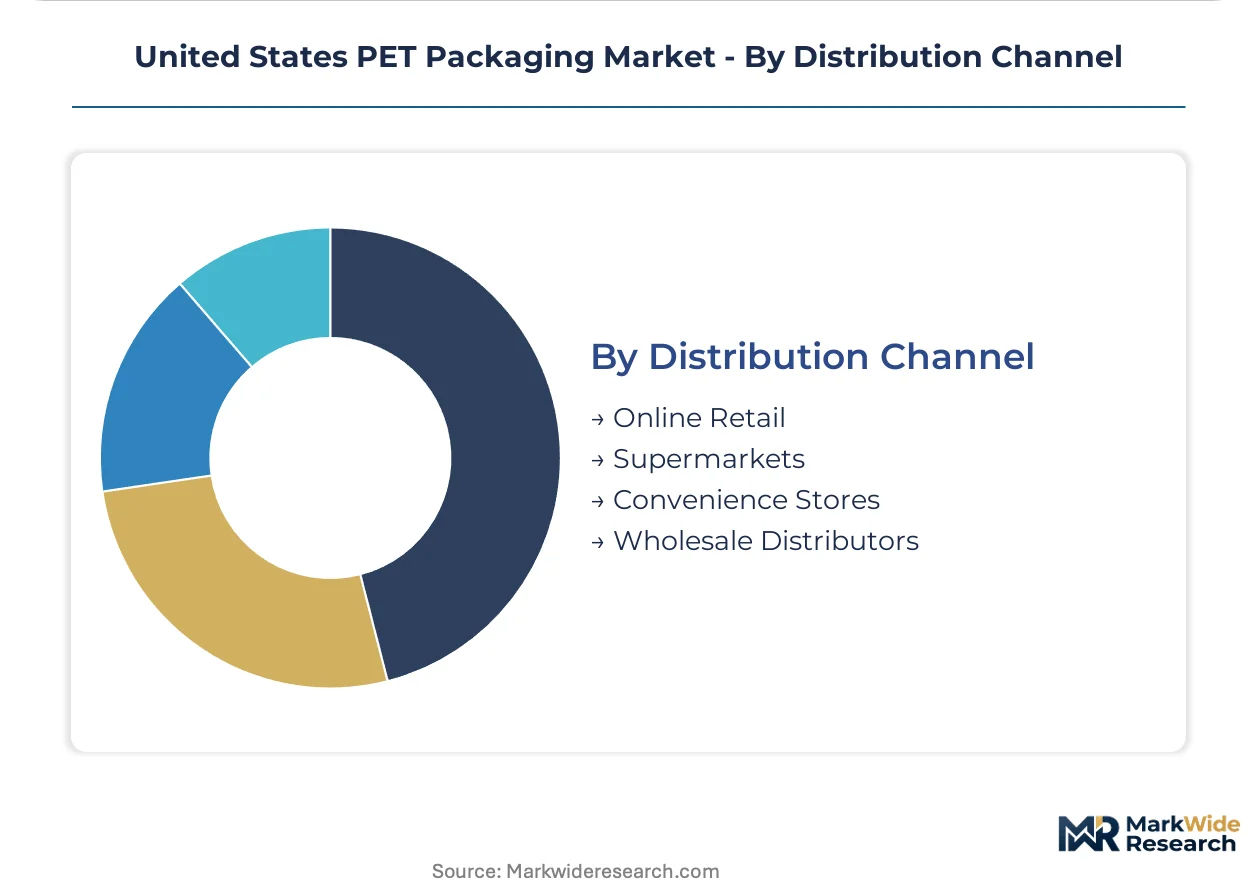
- Supermarkets:Kroger and Albertsons category managers negotiate direct supply agreements specifying shelf-ready secondary packaging and rPET content verification. Procurement bypasses traditional resin distributors in favor of specification-controlled contracts with blow-molders possessing CalRecycle-compliant mass-balance documentation.
- Wholesale Distributors:McLane and Core-Mark serve convenience store and foodservice accounts with consolidated SKU portfolios. Relationships concentrate in the Southeast and Gulf Coast states where blow-molding capacity clusters minimize outbound freight to regional distribution centers.
- Online Retail:Amazon and direct-to-consumer fulfillment.
- Convenience Stores:7-Eleven and Circle K private-label water and carbonated soft drinks.
Supermarkets channel the greatest volume; online retail is climbing the fastest as beverage subscription models penetrate suburban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers in the Southeast absorb virgin resin price swings with minimal procurement disruption, while pharmaceutical converters in the Northeast face steep compliance premiums that insulate them from commodity volatility.
Southeast
Coca-Cola and PepsiCo bottlers anchor procurement scale across Georgia and Florida. Georgia's tax abatements for recycled-content manufacturing equipment accelerate rPET washing line deployments. The Savannah port corridor hosts blow-molding capacity serving Caribbean export markets.
Gulf Coast
Ethylene and PTA production clusters along the Texas-Louisiana corridor feed captive resin supply to integrated preform operations. Texas state environmental permits for chemical recycling pilot facilities outpace federal EPA timelines. Houston-area logistics hubs minimize inbound freight costs for resin converters.
California
SB 54 mandates force brand technical teams to maintain CalRecycle-verified mass-balance documentation. FDA food-contact notification review timelines extend commercialization cycles for novel container designs. Los Angeles and Central Valley distribution centers concentrate private-label water procurement.
Midwest
Walmart and Target beverage category managers negotiate direct supply agreements specifying rPET percentage thresholds. Ohio and Illinois manufacturing corridors serve retail distribution networks with FDA-compliant food-contact infrastructure. Chicago-area thermoforming capacity expands into fresh produce tray applications.
Northeast
Pharmaceutical PET container demand centers on New Jersey and Pennsylvania generic drug manufacturing clusters. USP testing protocols and FDA Type III drug master file requirements command substantial price premiums. Boston-area biotech packaging procurement emphasizes barrier performance specifications.
United States PET Packaging Market Key Industry Players
Capability concentration sits with integrated rPET specialists; scale advantage sits with diversified packaging conglomerates. The market structure splits between resin-integrated blow-molders and specification-focused pharmaceutical converters. Three archetypes dominate: Gulf Coast resin-captive operators, FDA compliance-tier specialists, and retail-direct specification controllers. Competitive moves concentrate on recycled-content verification infrastructure and pharmaceutical certification pathway investments.
Within the integrated recycling tier, Berry Global and Plastipak Packaging occupy positions anchored by proprietary washing and pelletizing infrastructure. Amcor plc exemplifies geographic breadth across multiple manufacturing regions. These three entities represent the dominant competitive anchors in a market where rPET supply security and regulatory compliance credentials determine procurement access.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Sonoco Products Company |
| Plastipak Packaging |
| Graham Packaging Company |
| Huhtamaki Oyj |
| Gerresheimer AG |
| ALPLA Group |
| Silgan Holdings |
| Others |
Cost & Logistics Intelligence
rPET feedstock volatility determines both margin compression patterns and supply chain reconfiguration priorities across converter tiers. Post-consumer bottle bale price swings transmit directly to finished container economics, forcing producers to choose between virgin resin hedging strategies and backward integration into washing infrastructure.
Pricing Analysis
After-sales revenue from technical service contracts and FDA compliance consulting drives lifetime value for pharmaceutical-grade PET converters. Three-tier pricing structure across premium, standard, and economy levels stratifies by intrinsic viscosity grade and food-contact certification tier. Pricing pressure stems from Gulf Coast ethylene cost pass-through mechanisms that compress beverage-grade margins. Private-label water bottlers exhibit highest price sensitivity, while pharmaceutical generic manufacturers absorb premium positioning for USP-certified supply security.
Supply Chain Analysis
Upstream paraxylene and ethylene glycol production anchors in Texas and Louisiana petrochemical corridors. The United States PET packaging sector draws from domestic PTA manufacturing clusters and imported purified terephthalic acid from Canada and Mexico. Single-source vulnerability concentrates in Gulf Coast resin supply corridors exposed to hurricane disruption risk. Distribution runs through direct-to-retailer contracts with Walmart and Target beverage category managers, bypassing traditional resin distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States PET packaging market sits at an early-cycle expansion phase justified by state-level recycled-content mandate penetration that remains below 40% national coverage.
For Market Incumbents: Pre-empt margin erosion by locking multi-year rPET supply agreements before chemical recycling capacity floods the market. Accelerate screw and hot-runner modifications on legacy blow-molding lines to handle 100% rPET feedstocks. Invest in CalRecycle mass-balance verification infrastructure to defend supermarket channel access against emerging competitors.
For New Entrants and Emerging Players: Pursue pharmaceutical compliance tier specialization where USP certification barriers limit incumbent agility. Target Southeast manufacturing expansion leveraging Georgia tax abatements and Savannah port access for Caribbean export markets. Lead with barrier coating technology for generic drug blister pack applications.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated rPET specialists with captive washing infrastructure. Long-term viability over the next decade hinges on chemical recycling feedstock access and FDA food-contact notification expertise. Monitor California SB 54 compliance cost pass-through rates as the inflection signal for margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Pyrolysis and glycolysis units bypass mechanical recycling purity constraints for food-contact-grade output. |
| Backward Integration into rPET Washing | Captive flake supply secures margin position against post-consumer bale price volatility. |
| Pharmaceutical USP Certification Investment | FDA Type III drug master file pathways command substantial price premiums over beverage-grade equivalents. |
| Southeast Manufacturing Expansion | Georgia and South Carolina tax abatements reduce capital deployment costs for export-oriented capacity. |
| Direct-to-Retailer Contract Negotiation | Walmart and Target specification-controlled agreements displace traditional resin distributor relationships. |
Research Approach
The analysis maps bottles, containers, trays, and films, each validated through blow-molding operations managers, beverage brand procurement directors, pharmaceutical packaging engineers, and FDA regulatory consultants. Primary interview data triangulates against secondary sources including FDA food-contact notifications, EPA recycled materials standards, CalRecycle verification protocols, and SEC 10-K filings from packaging conglomerates. Bottom-up volume modeling and top-down value reconciliation cross-check segment outputs.
Assumptions held fixed include state-level mandate enforcement timelines and Gulf Coast petrochemical feedstock availability; variables tested include chemical recycling commercialization rates and curbside collection infrastructure expansion. Segmentation dimensions span product type, end-use industry, manufacturing stage, and distribution channel. CAGRs derive from regression analysis of historical procurement patterns and elasticity-adjusted demand projections. Key inputs incorporate resin price forecasting and retail channel shift modeling.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing and consumer packaged goods volume growth would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and collection rate improvements. Cross-checking against American Chemistry Council resin production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Egypt Plastic Packaging Market