
 Germany Plastic Bottles Market | 2026-2036
Germany Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Plastic Bottles Market Insights
Recycled PET is repositioning cost structures across the German plastic bottles landscape as virgin resin volatility and brand sustainability commitments converge. Amcor Group GmbH leverages its European recycling partnerships to secure flake supply for food-grade applications. Berry Global Inc. anchors its position through blow-molding scale serving beverage multinationals with high-volume contracts. Alpla Group differentiates via in-house rPET production at its German plants, closing loop quality for premium clients.
Germany plastic bottles are hollow container structures formed through extrusion blow molding, injection stretch blow molding, or reheat blow processes, typically ranging from ten milliliters to twenty liters in capacity and engineered for barrier performance, drop resistance, and closure compatibility. PET dominates the product type landscape due to its clarity, lightweight strength, and established deposit-return collection infrastructure, while HDPE retains share in dairy and household chemicals where chemical resistance matters. The beverages end use commands the largest volume commitment, though personal care applications generate superior per-unit margins through custom shapes and decorative finishes. Small and medium sizes attract reformulation activity as portion-control and on-the-go consumption patterns reshape filling line investments.
Germany's national packaging regulator enforces the Verpackungsgesetz requirements for extended producer responsibility and minimum recycling quotas, while the EU F-Gas Regulation and REACH framework govern additives and barrier coatings used in multilayer constructions. KBA involvement remains peripheral except for automotive fluid containers, though DIN standards and CE marking protocols shape export eligibility for German converters supplying adjacent European markets. Stakeholders must monitor rPET certification costs and sortation technology yields as mechanical recycling capacity becomes the binding constraint on volume growth.
Market Dynamics
Mechanical recycling capacity has become the binding constraint on German plastic bottle volume growth as brand rPET commitments outpace flake supply infrastructure, forcing converters to absorb certification premiums and secure long-term offtake agreements with specialized sorters.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content thresholds for beverage containers are pulling investment into food-grade rPET purification lines across North Rhine-Westphalia.
- Deposit-return infrastructure:Germany's DRS collection network delivers clean, mono-material PET streams that mechanical recyclers can process at yields exceeding mixed-waste alternatives.
- Lightweighting technology:Advanced stretch-blow molding protocols are reducing gram weight per bottle without sacrificing top-load strength, cutting resin demand per unit shipped.
Market Restraints
- rPET price volatility:Virgin PET resin fluctuations transmit directly into recycled flake markets, compressing converter margins when oil prices collapse.
- Sortation technology yields:Near-infrared detection systems at German MRFs still misroute 12-15% of food-grade PET into fiber or strapping bales due to label contamination.
- Barrier coating restrictions:REACH compliance for multilayer oxygen scavengers adds 8-14 weeks to new product qualification timelines versus monolayer alternatives.
Strategic Opportunities
- Refillable personal care formats:Concentrate and tablet brands in Berlin and Hamburg are piloting durable PET bottles with standardized neck finishes for closed-loop retail systems.
- Chemical recycling partnerships:Pyrolysis projects in the Ruhr region can process colored and degraded PET that mechanical lines reject, expanding feedstock pools.
- Pharmaceutical serialization integration:Track-and-trace mandates under the EU Falsified Medicines Directive favor blow-molders with in-house printing and aggregation capabilities.
Industry Challenges
- Food-grade certification timelines:EFSA novel food approvals for chemically recycled PET require 18-24 month safety dossier preparation, delaying commercial launches.
- Legacy filling line retrofit costs:Converters serving dairy and juice must revalidate capping torque specifications when transitioning to lightweighted preforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Plastic Bottles Market |
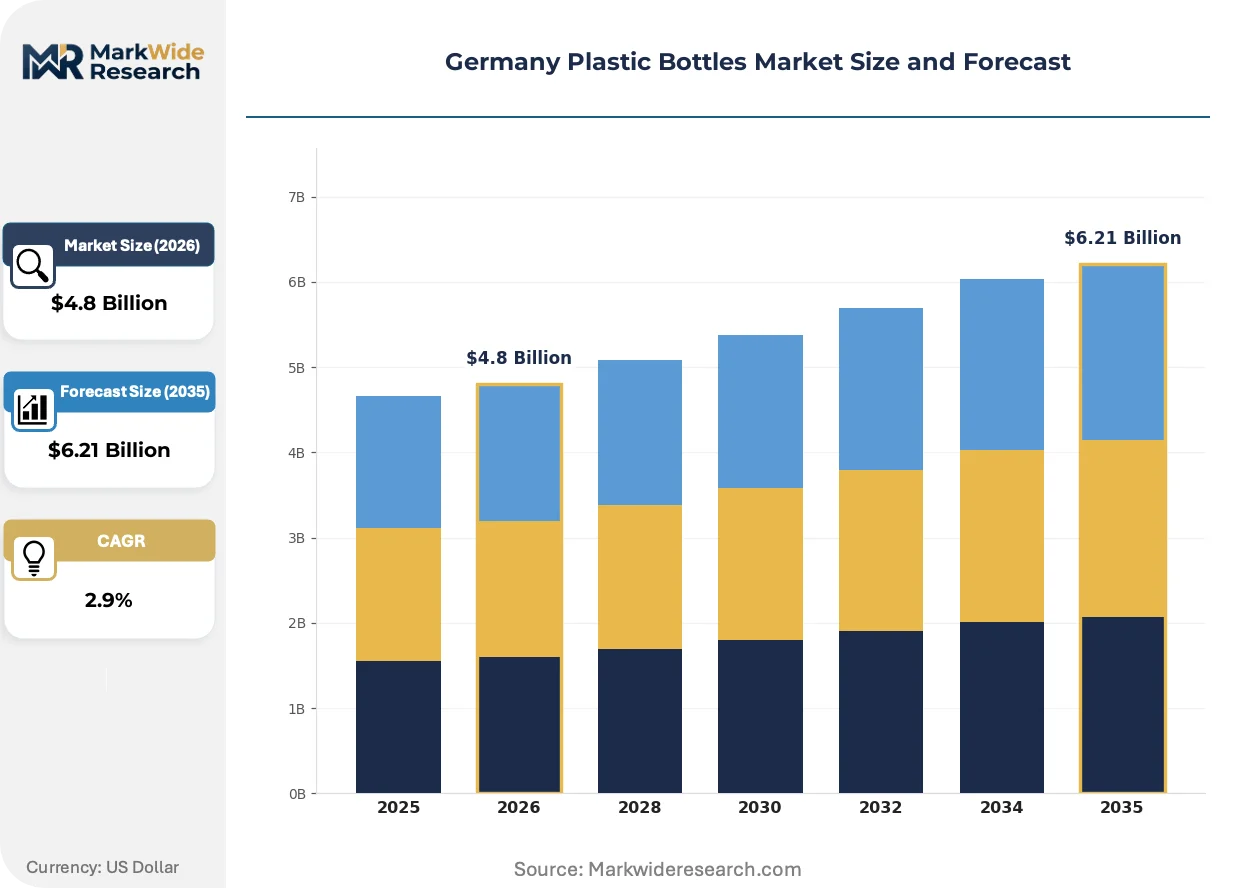
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 2.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End Use: Food, Beverages, Personal Care, Household Size: Small, Medium, Large, Extra Large Closure Type: Screw Cap, Snap-on Cap, Cork, Others |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., Alpla Group, Gerresheimer AG, Rixius AG, Weener Plastic Packaging, PFR Nord GmbH, Berlin Packaging GmbH, Eproplast GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Plastic Bottles Market Trends and Innovations
Digital manufacturing controls and polymer traceability systems are converging to reshape how German converters demonstrate compliance and optimize yield. These developments favor operations with integrated quality verification and real-time production monitoring.
Digital printing on PET bottles is consolidating decoration workflows by eliminating label substrates and adhesive application stations. Beverage brands in Bavaria and Baden-Württemberg are adopting direct-to-shape UV inkjet for short-run SKUs and seasonal promotions. This technology is compressing minimum order quantities and enabling regional flavor launches without plate changeover downtime.
Germany's Packaging Act enforcement is tightening extended producer responsibility calculations through granular mass-balance auditing. Converters must now document recycled content by specific resin batch rather than annual averages. Small and medium-sized blow-molders lacking ERP integration face disproportionate compliance costs relative to integrated groups with captive recycling assets.
On-the-go consumption patterns are fragmenting volume commitments across smaller bottle formats. Convenience retailers in Frankfurt and Munich are expanding chilled grab-and-go sections, pulling demand toward sub-500ml sizes with premium closure features. This rotation is forcing filling line investments that sacrifice throughput efficiency for rapid changeover flexibility.
Germany Plastic Bottles Market Segmentation
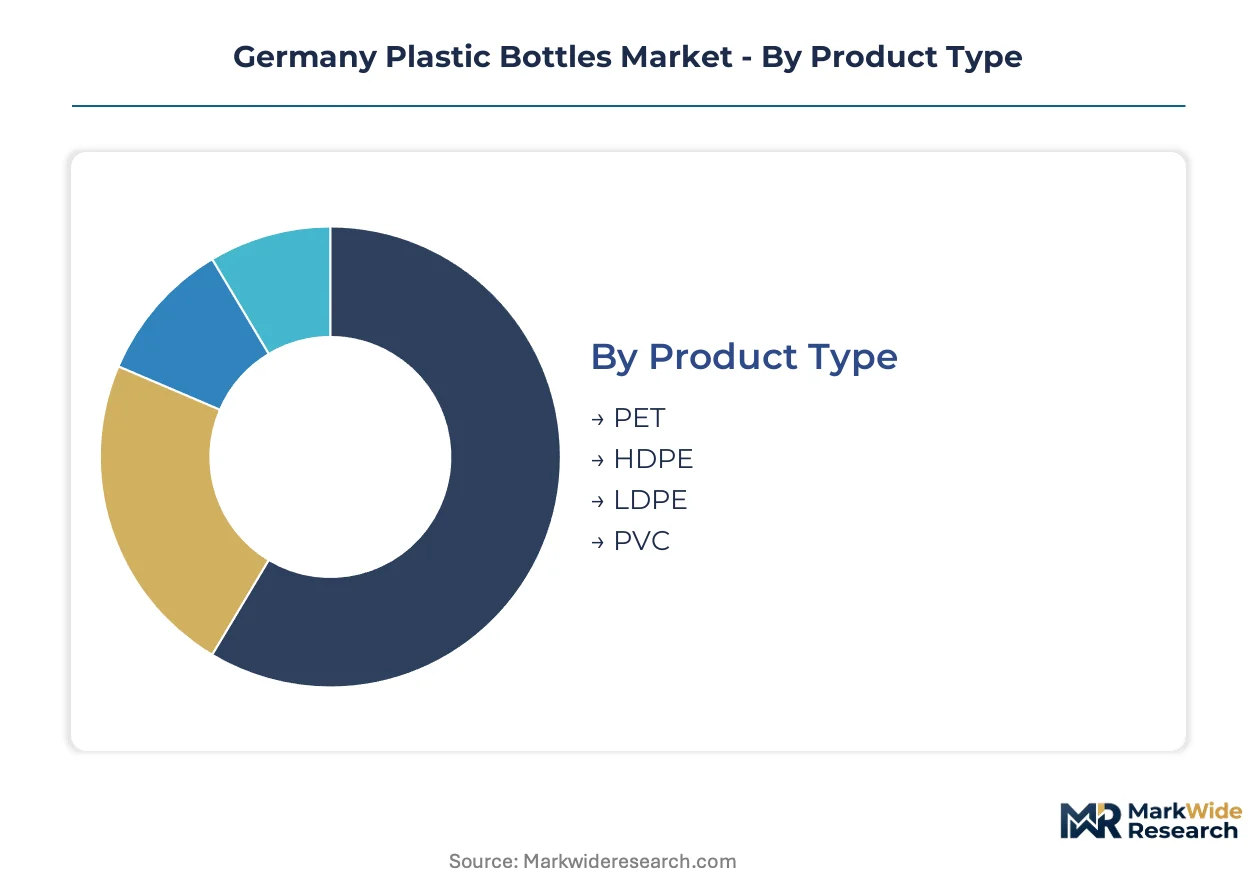
German converters calibrate production assets against four distinct segmentation axes. Each dimension shapes capital allocation, margin structure, and regulatory exposure differently across the North Rhine-Westphalia manufacturing cluster.
Product Type:
Material selection hinges on barrier requirements, recycling infrastructure compatibility, and virgin-to-recycled resin cost spreads.
- PET:Thermoplastic polyester delivers clarity, tensile strength, and established food-grade recycling pathways through Germany's deposit-return system. Beverage multinationals in Cologne and Düsseldorf anchor procurement volumes, though rPET flake shortages are forcing long-term offtake renegotiations.
- HDPE:High-density polyethylene offers chemical resistance and stress-crack durability for aggressive contents. Dairy processors across Bavaria specify HDPE for cultured products where pH stability matters, with post-consumer bale quality determining converter qualification timelines.
- LDPE:Low-density polyethylene serves squeeze applications and flexible dispensing closures where haptic softness drives consumer preference.
- PVC:Polyvinyl chloride retains niche pharmaceutical blister and medical packaging roles despite REACH registration burdens and declining beverage adoption.
PET leads volumes today; HDPE is gaining share fastest through dairy and chemical resistance applications.
End Use:
Application-specific performance standards dictate blow-molding protocols, barrier layer complexity, and closure torque specifications.
- Food:Edible oil and condiment brands demand oxygen scavenger integration and UV light blocking. Sauces and dressings in Baden-Württemberg require multilayer coextrusion capable of 12-month shelf stability without refrigeration.
- Beverages:Carbonated soft drinks, mineral water, and beer alternatives consume the largest resin tonnages. Deposit-return logistics in North Rhine-Westphalia deliver mono-material streams that mechanical recyclers process at superior yields versus mixed-waste alternatives.
- Personal Care:Shampoo and lotion brands prioritize custom shapes, soft-touch surfaces, and premium closure acoustics. Berlin-based indie beauty labels are piloting refillable formats with standardized neck finishes.
- Household:Cleaning and laundry products specify chemical-resistant resins and child-resistant closure mechanisms. Concentrate formats are reducing bottle sizes and shipping weights for e-commerce fulfillment.
Beverages dominates tonnage commitments; personal care commands the steepest per-unit margin expansion.
Size:
Volume-to-surface-area ratios determine resin efficiency, logistics cube utilization, and retail shelf placement economics.
- Small:Sub-330ml formats target on-the-go consumption and portion-controlled dispensing. Frankfurt convenience retailers are expanding chilled grab-and-go sections, pulling filling line investments toward rapid changeover flexibility.
- Medium:330ml to 1 liter spans standard beverage and personal care SKUs. This bracket captures the highest production throughput per mold cavity across German blow-molding assets.
- Large:1 to 3 liter formats serve family-size beverages and bulk household chemicals. Lightweighting protocols are reducing gram weights without sacrificing top-load performance during palletized distribution.
- Extra Large:Above 3 liter containers address institutional catering, automotive fluids, and industrial chemical totes. KBA automotive specifications govern select applications in this bracket.
Medium sizes anchor production volumes; small formats are climbing the fastest through convenience retail expansion.
Closure Type:
Sealing mechanism selection interfaces with filling line speed, consumer ergonomics, and tamper-evidence regulations.
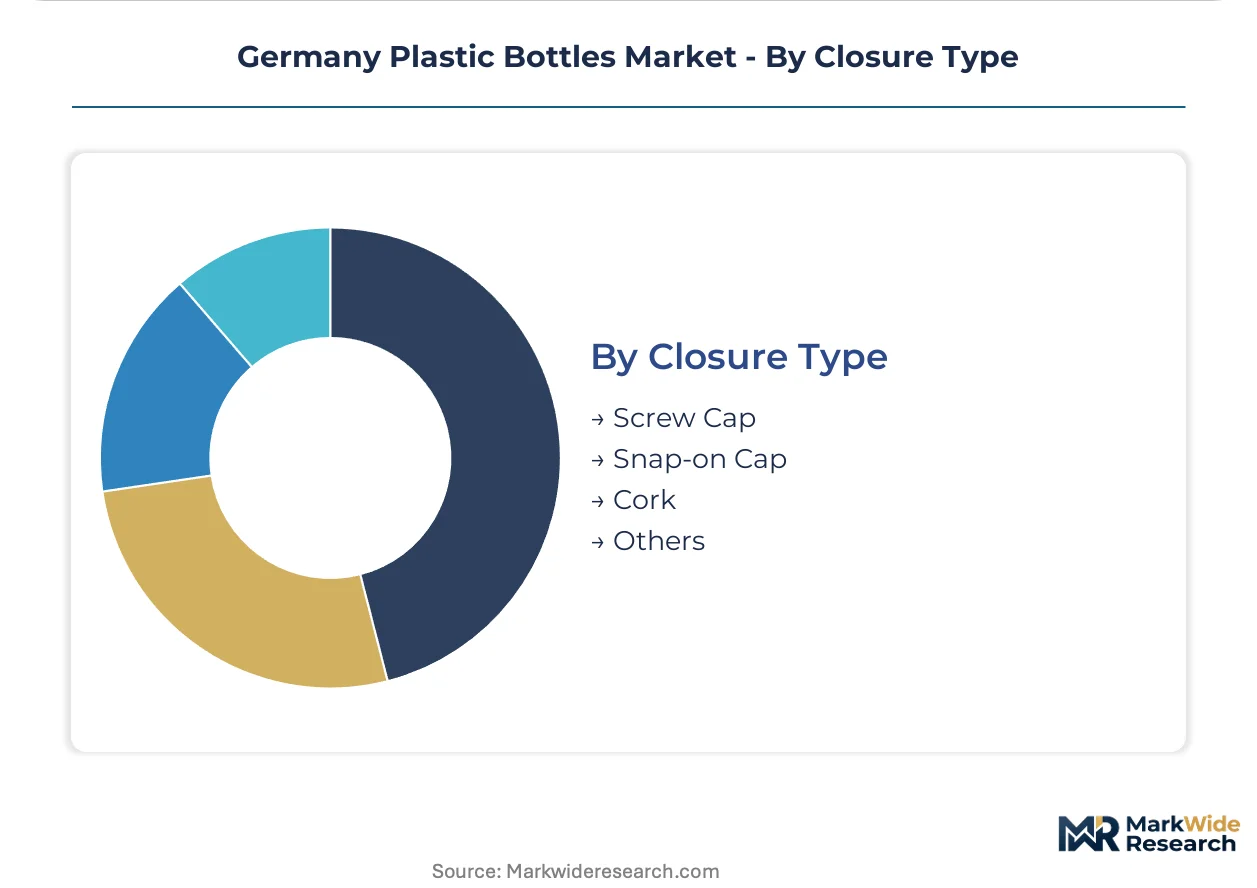
- Screw Cap:Threaded polypropylene closures dominate beverage and personal care applications. Hamburg converters are investing in torque-controlled capping systems that accommodate lightweighted preform transitions without leakage failures.
- Snap-on Cap:Press-fit designs serve single-serve dairy and juice portions where opening force must balance child accessibility against senior usability. DIN testing protocols validate seal integrity across temperature cycling.
- Cork:Natural and synthetic cork closures retain premium wine and spirits positioning. Bavarian wineries specify cork for export markets where traditional closure signals quality tier.
- Others:Pump dispensers, trigger sprayers, and dispensing valves address specialized viscosity and dosing requirements. Pharmaceutical serialization mandates favor integrated closure-printing capabilities for track-and-trace compliance.
Screw cap commands installed filling line infrastructure; snap-on designs are expanding most quickly through single-serve dairy innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia anchors German plastic bottle manufacturing through its concentration of blow-molding converters and mechanical recycling infrastructure. The state's industrial corridor between Cologne and Düsseldorf processes the majority of food-grade rPET flake entering German beverage supply chains.
Bavaria
Dairy processors across Upper and Lower Bavaria specify HDPE bottles for cultured products requiring pH stability. The state's dairy association enforces strict hygiene protocols that extend converter qualification timelines. Munich-based packaging distributors coordinate just-in-time deliveries to Alpine dairy cooperatives.
Baden-Württemberg
Precision engineering culture in Stuttgart and Karlsruhe drives demand for pharmaceutical-grade bottles with integrated serialization. The state's Ministry of the Environment enforces extended producer responsibility calculations that exceed federal Verpackungsgesetz baselines. Heidelberg converters specialize in small-batch cosmetic bottles for indie beauty brands.
Lower Saxony
Petrochemical feedstock availability near Wilhelmshaven and Brunsbüttel supports HDPE production for household chemical applications. The state's coastal location enables direct resin importation from North Sea terminals. Hannover logistics hubs distribute bulk containers to northern European retail chains.
Hesse
Frankfurt's convenience retail density pulls demand toward sub-500ml on-the-go formats with premium closure features. The city's regional council enforces strict commercial waste sorting mandates that improve PET bale quality for mechanical recyclers. Offenbach converters pilot digital direct-to-shape printing for seasonal beverage promotions.
Hamburg
Port infrastructure enables rPET flake importation from Nordic suppliers when domestic mechanical recycling capacity binds. The city's environmental authority operates Germany's most granular mass-balance auditing system for packaging compliance. Altona blow-molders serve Scandinavian export markets through CE-marked production lines.
Germany Plastic Bottles Market Competitive Landscape
Global majors compete with regional champions across recycling integration and blow-molding scale. The market structure consolidates around three to four integrated groups with captive rPET assets, while mid-sized converters specialize in pharmaceutical and cosmetic niches requiring serialization or decorative finishing. Strategic archetypes include vertically integrated resin-to-bottle operators, toll-blowers serving beverage multinationals, and specialists in barrier-coated multilayer constructions. Capacity expansion and long-term offtake agreements for food-grade flake represent the dominant competitive moves as rPET shortages persist.
Among the integrated groups, Amcor Group GmbH, Berry Global Inc., and Alpla Group occupy positions defined by their recycling asset footprints and customer contract structures. Amcor leverages European recycling partnerships to secure flake supply positions. Berry anchors volume relationships through high-capacity blow-molding assets serving multinational beverage brands. Alpla exemplifies closed-loop integration through in-house rPET production at German manufacturing sites. Gerresheimer AG and Rixius AG represent specialist archetypes focused on pharmaceutical compliance and custom cosmetic formats respectively. Weener Plastic Packaging, PFR Nord GmbH, Berlin Packaging GmbH, and Eproplast GmbH populate the mid-tier segment where regional logistics and flexible tooling configurations determine contract viability.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| Alpla Group |
| Gerresheimer AG |
| Rixius AG |
| Weener Plastic Packaging |
| PFR Nord GmbH |
| Berlin Packaging GmbH |
| Eproplast GmbH |
| Others |
Pricing and Supply Chain Analysis
Lightweighting protocols and rPET flake shortages are simultaneously compressing per-unit resin costs and concentrating bargaining power among integrated converters with captive recycling assets. This dual dynamic forces mid-tier blow-molders to absorb certification premiums while integrated groups extract margin through backward control over food-grade purification lines.
Pricing Analysis
Input-cost pass-through from virgin PET resin volatility transmits directly into recycled flake markets, compressing converter margins when oil prices collapse. Three-tier pricing structure across premium, standard, and economy levels separates food-grade rPET-certified bottles from industrial-grade alternatives and virgin-only commodity formats. Pricing pressure stems from mechanical recycling capacity binding as brand sustainability commitments outpace flake supply infrastructure. Small and medium-sized blow-molders lacking ERP integration face disproportionate compliance costs and exhibit highest price sensitivity, while beverage multinationals with volume commitments secure long-term offtake stability.
Supply Chain Analysis
rPET flake supply rests on German mechanical recyclers clustered in North Rhine-Westphalia, with supplemental feedstock drawn from Nordic suppliers through Hamburg port infrastructure. Virgin PET resin sources from European petrochemical producers, while barrier coatings and oxygen scavengers hinge on REACH-registered specialty chemical suppliers. Single-source vulnerability concentrates in food-grade purification lines where EFSA novel food approvals require 18-24 month safety dossier preparation. Distribution runs through just-in-time logistics hubs in Cologne, Düsseldorf, and Frankfurt serving beverage filling lines and retail distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's plastic bottles market functions as a stable compounder anchored by the EU Single-Use Plastics Directive's mandatory recycled content thresholds, which institutionalize demand growth regardless of macroeconomic cyclicality.
For Market Incumbents: Anchor market position through long-term offtake agreements with specialized sorters and in-house rPET production investments that offset flake price volatility. Threats from chemical recycling entrants processing colored PET rejected by mechanical lines necessitate defensive patenting around purification technologies. Backward integration into deposit-return collection logistics represents the critical lever for securing mono-material feedstock streams at superior yields versus mixed-waste alternatives. For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical-grade serialization-capable bottles and economy virgin-only commodity formats offers white-space entry through mid-tier barrier-coated multilayer constructions for sauces and dressings. Most penetrable segment sits in refillable personal care formats piloting durable PET with standardized neck finishes for closed-loop retail systems in Berlin and Hamburg. Go-to-market angle should emphasize rapid digital direct-to-shape printing capabilities for seasonal beverage promotions without plate changeover downtime. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized converters lacking ERP integration for granular mass-balance auditing compliance. Long-term viability over a five-to-ten year window favors targets with pharmaceutical serialization capabilities and CE-marked production lines for Scandinavian export markets. Signal to watch is EFSA approval timelines for chemically recycled PET, which would re-rate mechanical recycling assets and redirect capital toward pyrolysis partnerships in the Ruhr region.| Strategic Initiative | Industry Significance |
|---|---|
| Food-Grade rPET Purification Investment | EFSA novel food approvals unlock premium pricing tiers for beverage containers under EU directive mandates. |
| Digital Direct-to-Shape Printing Adoption | UV inkjet decoration compresses minimum order quantities for Bavarian seasonal flavor launches without plate downtime. |
| Long-Term Flake Offtake Agreements | Specialized sorter partnerships secure mechanical recycling capacity ahead of competing converters in North Rhine-Westphalia. |
| Pharmaceutical Serialization Integration | EU Falsified Medicines Directive compliance favors blow-molders with in-house printing and aggregation capabilities. |
| Chemical Recycling Partnership Formation | Pyrolysis projects in the Ruhr region expand feedstock pools beyond mechanical line reject streams. |
Research Methodology
Coverage spans German federal states and adjacent European markets, with primary inputs from each region's manufacturing clusters. Primary interviews engaged blow-molding plant managers, beverage procurement leads at multinational brand headquarters, mechanical recycling facility operators, and packaging compliance officers at regulatory consultancies. Secondary validation drew from Verpackungsgesetz enforcement reports, EFSA novel food approval databases, DIN standards documentation, and customs records tracking rPET flake import flows. Bottom-up capacity assessments triangulated against top-down demand modeling from beverage filling line investments and retail distribution expansion.
Granularity-level framing modeled volume and value outputs at product type, end use, size bracket, and closure type dimensions, with additional cross-segmentation by rPET certification tier and barrier layer complexity. CAGRs across the analysis window derived from production capacity buildout schedules, deposit-return collection yield projections, and lightweighting protocol adoption curves. Industry-specific forecast inputs included EFSA approval pipeline timelines for chemically recycled PET and KBA automotive fluid container specifications.
Caveats apply where EFSA safety dossier delays, virgin PET resin price collapses, or sortation technology yield improvements could materially shift the outlook. Forecasts reflect assumptions around mechanical recycling capacity expansion rates and brand rPET commitment fulfillment timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Poland Plastic Packaging Tubes Market