
 Plastic Buckets Market | 2026-2036
Plastic Buckets Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Buckets Market Analytics
Post-consumer recycled polypropylene compounding is tilting manufacturing economics toward circular feedstock integration. Berry Global Inc. leverages vertical integration across resin sourcing and blow molding to sustain cost leadership in food-grade packaging. ALPLA anchors its position through dedicated recycling infrastructure and closed-loop partnerships with European brand owners. Shanghai Zijiang Enterprise Group Co. Ltd. dominates Asia-Pacific volume through scale-focused extrusion and regional logistics density.
Plastic buckets are injection-molded or blow-molded containers, typically constructed from high-density polyethylene or polypropylene, with wall thickness ranging from 0.8 to 2.5 millimeters and integral handles or metal bail assemblies for transport loads exceeding 25 kilograms. These vessels serve as standardized packaging for chemicals, coatings, food products, and agricultural inputs where UN certification or FDA compliance governs commercial acceptance. Food-grade buckets command premium positioning due to migration testing requirements and traceability protocols, while utility buckets face commoditization pressure from private-label competition. Industrial end users concentrate procurement around 5-gallon and 10-gallon capacities for material handling efficiency, whereas household demand clusters in 1-gallon and 2-gallon formats for cleaning and storage applications.
The EPA oversees hazardous material containment standards that dictate UN-rated bucket specifications for chemical and coating distribution in the United States. REACH and the EU Packaging and Packaging Waste Regulation impose recycled content thresholds and extended producer responsibility obligations that reshape European product design and cost structures. FDA food contact regulations govern resin selection and additive packages for food-grade buckets distributed domestically. Stakeholders must monitor evolving state-level recycled content mandates and chemical disclosure requirements that will determine which production configurations retain market access.
Market Dynamics
Post-consumer recycled content mandates from the European Commission's Packaging and Packaging Waste Regulation are forcing material transition investments across the plastic buckets value chain, compressing virgin resin demand curves while elevating circular feedstock premiums.
Growth Catalysts
- REACH compliance thresholds:European chemical distributors are accelerating UN-certified container procurement ahead of extended producer responsibility deadlines, pulling forward replacement cycles for legacy inventory.
- Food processing automation:Commercial kitchens and co-packing facilities in the United States are standardizing on FDA-compliant 5-gallon buckets for ingredient batching, creating pull-through for traceable resin sourcing.
- Agricultural input consolidation:Fertilizer and crop protection distributors across the Midwest are centralizing procurement through cooperative buying groups, concentrating volume with certified suppliers capable of 10-gallon bulk formats.
Market Restraints
- Propylene feedstock volatility:Cracker maintenance cycles and naphtha price swings are compressing margin stability for polypropylene compounders serving the bucket segment.
- Single-source recycling infrastructure:Post-consumer resin availability concentrates in German and Dutch mechanical recycling clusters, creating geographic dependency for European manufacturers.
- Steel drum substitution:Chemical handlers in heavy corrosion environments retain preference for coated steel in specific pH exposure applications, capping plastic penetration.
Strategic Opportunities
- Indian FSSAI food-grade certification:Processed food exports from Maharashtra and Gujarat are creating demand for internationally compliant packaging that domestic blow molders can capture.
- Closed-loop agricultural collection:Seed and pesticide buckets are being recovered through retailer take-back schemes, enabling circular resin flows with verified chain of custody.
- Smart labeling convergence:Integration of RFID-enabled traceability with standard bucket molding is digitizing inventory management for chemical distributors.
Industry Challenges
- Migration testing backlog:FDA food contact notifications for novel recycled resin blends are extending certification timelines, delaying product launches.
- Multi-cavity mold retooling:Transitioning from virgin to high-percentage recycled feedstock requires screw and hot runner modifications that idle production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Buckets Market |
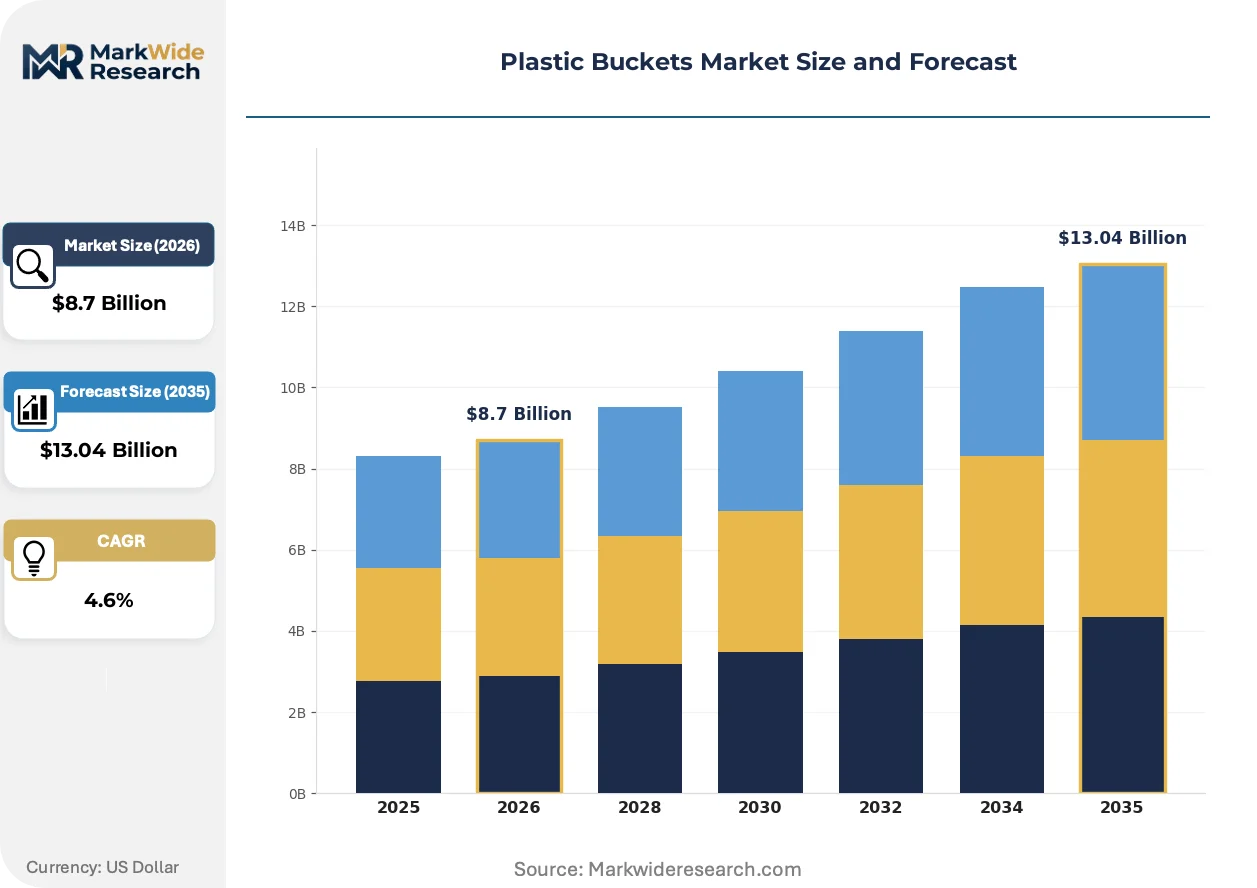
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Utility Buckets, Cleaning Buckets, Storage Buckets, Food-Grade Buckets End User: Households, Commercial, Industrial, Agriculture Capacity: 1 Gallon, 2 Gallons, 5 Gallons, 10 Gallons Color: Clear, Blue, Green, Red |
| Companies Covered | Plastipak Holdings, Inc., Berry Global Inc., ALPLA, Shanghai Zijiang Enterprise Group Co. Ltd., Greiner Packaging, Pretium Packaging LLC, Graham Packaging Company, Visy, Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Buckets Market Evolving Landscape
Active digitization of supply chain verification and material traceability is compressing the information asymmetry between resin origin and end-user certification requirements across the plastic buckets sector.
Embedded RFID and QR-code serialization is digitizing batch-level traceability from resin pellet to filled container. Chemical distributors in the United States are adopting these systems at the enterprise tier to satisfy EPA hazardous material documentation requirements. The technology is digitizing audit workflows and compressing compliance labor costs while enabling real-time recall targeting.
REACH authorization requirements for specific additive packages are forcing reformulation of UV stabilizers and colorants used in outdoor agricultural buckets. Compounders serving the European market are accelerating substitution timelines ahead of sunset dates. Food-grade applications face the most complex transition given dual compliance with EFSA migration limits.
Direct procurement relationships between agricultural cooperatives and molding facilities are displacing traditional distributor intermediaries in the United States. Volume buyers in Iowa and Illinois are negotiating captive production slots for seasonal input delivery. The shift is most visible in pre-seed treatment applications where timing precision outweighs SKU breadth.
Plastic Buckets Market Segmentation
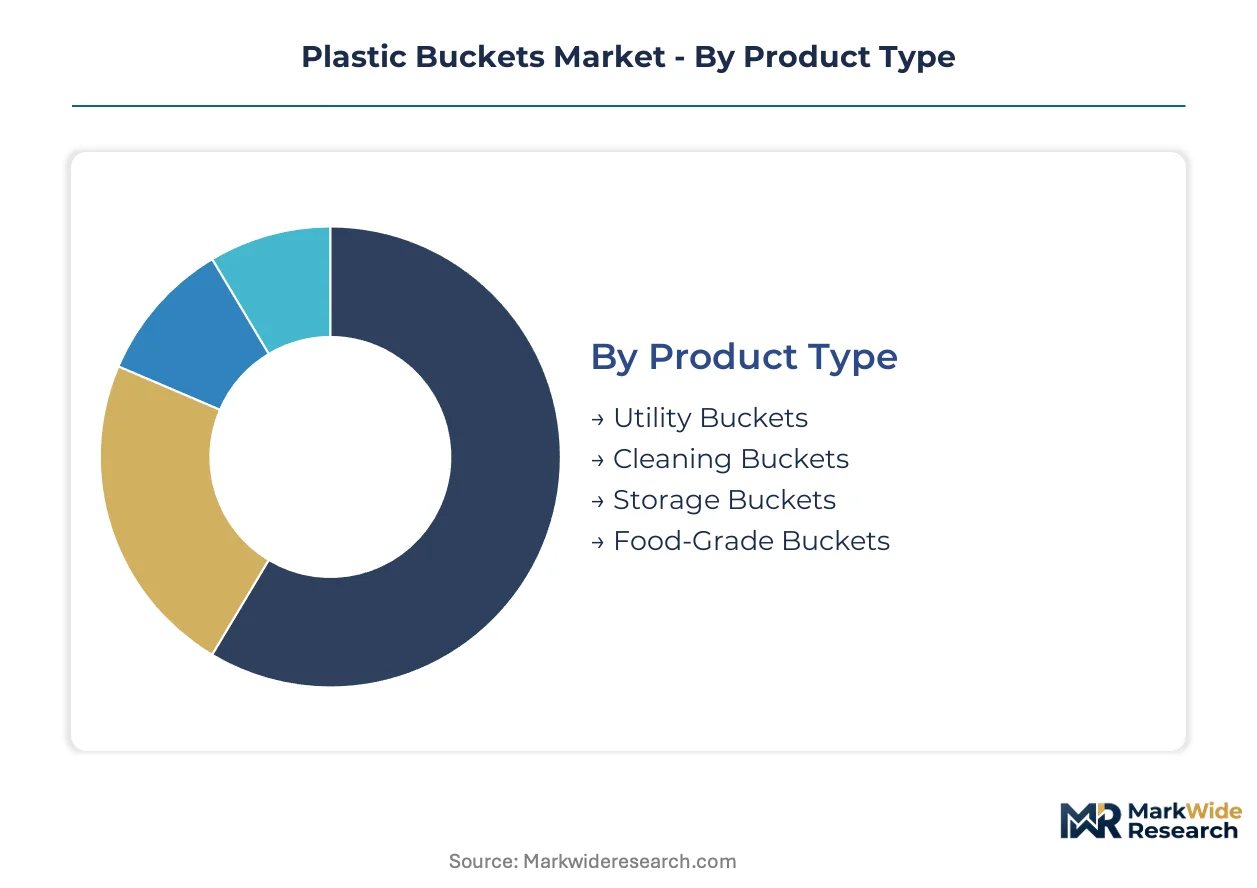
Segmentation in plastic buckets reveals how specification requirements fragment manufacturing economics. Cycle times vary dramatically across categories, with food-grade certification extending production runs while utility formats turn inventory rapidly.
Product Type:
Food-grade buckets command extended production cycles due to migration testing and traceability protocols, whereas utility formats rotate inventory fastest through private-label channels.
- Food-Grade Buckets:High-density polyethylene or polypropylene construction with FDA-compliant additive packages and lot-level traceability. Commercial food processing operations in the United States concentrate procurement here, driven by batch-level documentation requirements for ingredient handling.
- Utility Buckets:Standard HDPE or recycled-content construction without certification overhead, optimized for cost minimization. Household cleaning and general storage applications across mass retail channels drive volume, with private-label competition compressing margin structures.
- Cleaning Buckets:Chemical-resistant formulations with graduated volume markings for dilution control.
- Storage Buckets:Thicker wall construction with gasket-sealed lids for moisture protection.
Utility buckets dominate installed base. Food-grade buckets are where expansion concentrates.
End User:
Cost tiers stratify sharply across end-user categories, with industrial procurement commanding premium specifications and household demand absorbing commoditized output.
- Industrial:UN-certified containers for chemical and coating distribution with wall thickness exceeding 2 millimeters and metal bail assemblies. EPA hazardous material containment standards govern specifications, with chemical handlers in corrosion environments driving demand for high-performance grades.
- Agriculture:Seasonal volume concentration through cooperative buying groups, with 10-gallon formats for fertilizer and crop protection inputs. Midwest distributor consolidation is pulling procurement toward certified suppliers with captive production slots.
- Commercial:Food service, hospitality, and institutional applications with intermediate durability requirements.
- Households:Price-sensitive demand clustering in 1-gallon and 2-gallon formats for cleaning and storage.
Households dominate installed base. Agriculture is where expansion concentrates.
Capacity:
Volume economics favor 5-gallon and 10-gallon formats where material handling efficiency justifies specialized logistics, while smaller capacities distribute through general retail.
- 5 Gallons:Standardized industrial and commercial format optimizing pallet cube utilization and manual handling ergonomics. FDA-compliant variants serve commercial kitchens and co-packing facilities for ingredient batching, with traceable resin sourcing becoming a procurement filter.
- 10 Gallons:Bulk agricultural and chemical distribution format requiring reinforced handles and thicker walls. Fertilizer and crop protection distributors centralize procurement through cooperative buying groups, concentrating volume with certified molders.
- 1 Gallon:Retail household format for cleaning concentrates and small-batch storage.
- 2 Gallons:Intermediate capacity serving DIY and light commercial applications.
5-gallon formats dominate installed base. 10-gallon formats are where expansion concentrates.
Color:
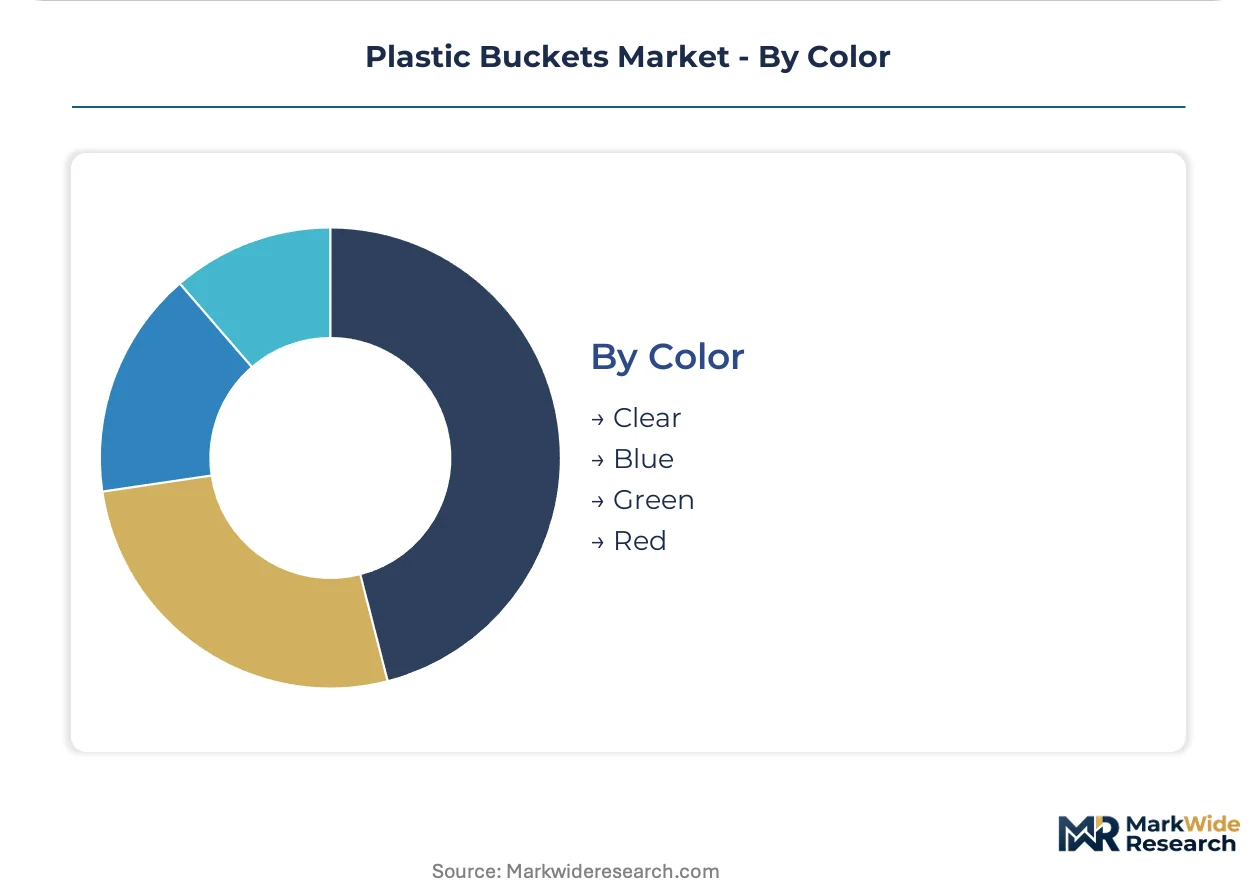
Application-driven color coding separates premium specification tiers from undifferentiated commodity supply, with functional transparency commanding technical premiums.
- Clear:Food-grade and chemical applications requiring visual content verification without container opening. FDA food contact regulations restrict additive packages for optical clarity, extending certification timelines and compressing qualified supplier bases.
- Blue:Industry-standard color for food processing segregation and chemical resistance signaling.
- Green:Agricultural and sustainability-marketed applications with recycled-content positioning.
- Red:Hazardous material identification and high-visibility safety applications.
Blue dominates installed base. Clear is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German blow molders supply UN-certified containers to chemical distributors across the Benelux corridor, while Chinese extrusion houses dominate Asia-Pacific volume through Pearl River Delta logistics density.
United States
Midwest agricultural cooperatives centralize procurement of 10-gallon fertilizer buckets through Iowa and Illinois buying groups. EPA hazardous material containment standards govern UN-rated specifications for chemical distribution. Houston-Galveston petrochemical corridors feed HDPE resin to regional molding facilities serving Gulf Coast refineries.
Germany
REACH authorization deadlines accelerate replacement cycles for UV-stabilized agricultural containers ahead of additive sunset dates. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that reshape compounding economics. Mechanical recycling clusters in North Rhine-Westphalia concentrate post-consumer resin supply for circular feedstock integration.
China
Yangtze River Delta extrusion facilities scale output for domestic chemical and food processing demand. GB standards govern food contact migration limits that parallel FDA requirements for export-oriented production. Zhejiang and Jiangsu provinces host dense networks of mold fabrication and blow molding capacity.
India
Maharashtra and Gujarat processed food exporters seek FSSAI-compliant packaging for international shipment certification. BIS quality standards intersect with state-level plastic waste management rules that vary across jurisdictions. Mumbai-Pune industrial corridors concentrate blow molding capacity for western India distribution.
Brazil
São Paulo agricultural input distributors standardize on 20-liter formats for crop protection chemical handling. ANVISA pharmaceutical packaging regulations create compliance overhead for food-grade bucket crossover applications. Campinas and Sorocaba molding clusters serve the southeastern agricultural heartland.
Plastic Buckets Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation concentrates among resin-integrated multinationals while regional fabricators fragment the utility-grade segment. Three archetypes dominate: vertically integrated resin-to-package operators, recycling infrastructure specialists, and scale-focused extrusion houses. Capacity expansion and closed-loop partnership formation represent the dominant competitive moves reshaping supply relationships.
Among resin-integrated multinationals, Berry Global Inc. and ALPLA occupy positions exemplifying backward control over feedstock and molding operations. Shanghai Zijiang Enterprise Group Co. Ltd. anchors the scale-driven archetype through Asia-Pacific logistics density. These three represent distinct strategic configurations: captive resin sourcing, dedicated recycling infrastructure, and regional volume concentration.
| Leading Market Players |
|---|
| Plastipak Holdings, Inc. |
| Berry Global Inc. |
| ALPLA |
| Shanghai Zijiang Enterprise Group Co. Ltd. |
| Greiner Packaging |
| Pretium Packaging LLC |
| Graham Packaging Company |
| Visy |
| Amcor Plc |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and Dutch mechanical recycling clusters compresses margin stability for European compounders while widening the spread between virgin-resin and circular-feedstock pricing tiers. This chokepoint forces molders to pre-position inventory ahead of mandate deadlines, reshaping working capital requirements across the value chain.
Pricing Analysis
Feedstock-generation pricing gaps separate virgin-polypropylene tiers from post-consumer recycled blends and next-generation bio-based alternatives. Three-tier pricing structure across food-grade certified, industrial UN-rated, and utility-grade unlabeled buckets reflects migration testing overhead and traceability protocol costs. Cost compression in utility segments is intensifying because private-label retail concentration transfers bargaining power to mass-merchandise buyers. Household end users exhibit the highest price sensitivity, whereas chemical distributors absorbing EPA compliance costs show the least.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts resin flow patterns for HDPE compounders serving North American molding facilities. Supply concentrates in the United States, Germany, and China, with the Yangtze River Delta and Houston-Galveston corridor anchoring extrusion capacity. Raw material flows draw from naphtha crackers, propane dehydrogenation units, and post-consumer bale supply. Distribution runs through agricultural cooperative buying groups in the Midwest and chemical distributor networks across the Gulf Coast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified suppliers capable of simultaneous FDA food-contact and UN hazardous-material certification remain scarce, creating asymmetric returns for molders that invested early in dual-compliance infrastructure. This capability gap separates premium-positioned players from commodity competitors facing margin erosion.
For Market Incumbents: Entrench position through captive recycling infrastructure investments and closed-loop partnerships with European brand owners facing extended producer responsibility deadlines. Accelerate screw and hot runner retooling for high-percentage recycled feedstock ahead of competitor capacity additions. Defend against steel drum substitution in corrosion applications by advancing fluoropolymer-lined bucket formulations. For New Entrants and Emerging Players: Establish a beachhead in Indian FSSAI food-grade certification services for Maharashtra and Gujarat processed food exporters seeking international shipment compliance. Target cooperative buying group procurement officers in Iowa and Illinois agricultural input distribution with seasonal delivery precision capabilities. Lead with RFID-enabled traceability integration as a digitization wedge against legacy molders. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors resin-integrated multinationals with backward control over feedstock and molding operations. Long-term viability across a 5-10 year window rests on circular feedstock access and regulatory certification breadth. Watch for FDA food contact notification backlogs as an inflection signal for recycled-resin blend availability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Cluster Investment | Secures post-consumer resin supply ahead of EU Packaging and Packaging Waste Regulation thresholds. |
| Closed-Loop Agricultural Collection Partnership | Enables verified chain of custody for seed and pesticide bucket recovery through retailer take-back schemes. |
| RFID-Enabled Traceability Integration | Digitizes EPA hazardous material documentation workflows for chemical distributor enterprise tiers. |
| Dual-Compliance Certification Infrastructure | Captures premium positioning at the intersection of FDA food-contact and UN-rated industrial specifications. |
| Cooperative Buying Group Captive Production | Locks seasonal volume concentration through direct procurement relationships with Midwest agricultural distributors. |
Research Methodology
A standing panel of blow molding plant managers, resin procurement leads at compounders, agricultural cooperative buying group officers, and EPA compliance directors provided ongoing calibration across the study period. Primary interview data combined with secondary validation from customs trade records, SEC 10-K filings of resin-integrated packaging multinationals, and EU Packaging and Packaging Waste Regulation implementation tracking. Bottom-up volume modeling triangulated against top-down market sizing from trade association capacity surveys.
Scenario-bracketing framed low, base, and high cases around recycled content mandate enforcement timing and propylene feedstock price volatility assumptions. Segmentation dimensions spanned product type, end user category, capacity format, and color specification across the projection horizon. CAGRs derived from curve-fitting historical shipment data against capacity expansion announcements and regulatory deadline pull-forward effects.
Sensitivities concentrate around FDA food contact notification approval timelines and mechanical recycling cluster operating rates. Forecasts reflect documented assumptions regarding mandate compliance trajectories and feedstock availability curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
Cast Films Market