
 Post-Consumer Recycled Plastic Packaging Market | 2026-2036
Post-Consumer Recycled Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Consumer Recycled Plastic Packaging Market Outlook
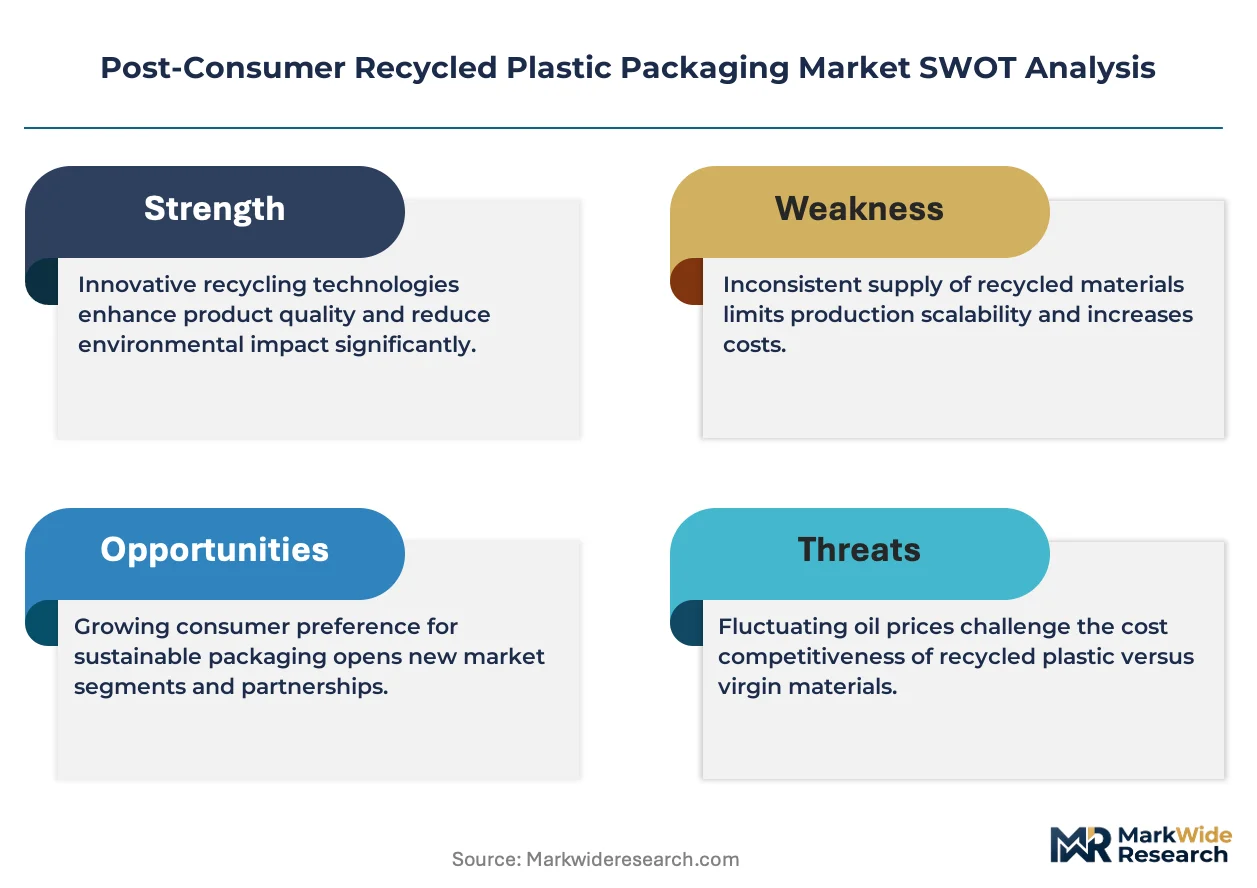
Green bond issuance and sustainability-linked project finance is reconfiguring capital access for post-consumer recycled plastic packaging ventures, allowing mid-scale recyclers to fund optical sorting and decontamination lines without balance-sheet strain. LyondellBasell Industries leverages its integrated polymer position to secure long-term offtake agreements with brand owners seeking food-grade recycled resins. Veolia sustains geographic dominance through municipal waste concession contracts that guarantee feedstock volumes for its European reprocessing hubs. KW Plastics anchors North American supply with its specialized focus on HDPE and PP rigid container recycling at industrial scale.
Post-consumer recycled plastic packaging comprises containers, films, and rigid structures manufactured from reprocessed polymers derived from collected consumer waste streams, typically requiring melt filtration, solid-state polymerization, or advanced decontamination to achieve food-contact compliance thresholds. Its primary purpose is to displace virgin petrochemical-derived packaging while satisfying retailer and regulatory mandates for circular material content. Bottles command the largest volume share within product type segments due to established collection infrastructure and brand-owner commitments, though films represent the fastest-expanding category as flexible packaging recyclability improves. Within end use industry segments, food and beverage applications absorb the majority of premium-priced food-grade recycled output, while personal care brands compete for limited cosmetic-grade rPET supply.
The EPA advances landfill diversion targets that indirectly elevate post-consumer plastic collection economics, while FDA issued letters of no objection for specific recycling processes enable food-contact applications that command price premiums over non-food grades. REACH and the EU Packaging and Packaging Waste Regulation impose binding recycled content percentages that reshape converter procurement criteria and exclude non-compliant suppliers from European market access. Stakeholders must monitor chemical recycling capacity announcements and regulatory recognition of mass-balance accounting methods, as these developments will determine which resin producers capture margin from next-generation feedstock flexibility.
Market Dynamics
Extended producer responsibility mandates are forcing brand owners to secure long-term recycled resin offtake, concentrating procurement power among converters with food-grade certification capabilities.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding recycled content thresholds for rigid packaging formats compel converters to reformulate supply chains around certified post-consumer feedstock.
- Chemical recycling scale-up:Pyrolysis and depolymerization investments in Germany are expanding food-contact eligible resin supply beyond mechanical recycling limitations.
- Food and beverage procurement:Major bottlers are embedding recycled content commitments into supplier scorecards, creating pull-through demand for decontaminated rPET.
Market Restraints
- Feedstock cost volatility:Baled post-consumer plastic prices fluctuate with virgin polymer spreads, compressing reprocessor margins when oil prices drop.
- Sorting infrastructure concentration:Advanced optical sorting capacity clusters in Germany and the Netherlands, leaving Southern European markets dependent on cross-border feedstock transfers.
- Mass-balance accounting uncertainty:Lack of harmonized certification standards for chemical recycling output creates procurement friction for converters seeking regulatory compliance documentation.
Strategic Opportunities
- Flexible packaging recyclability:Mono-material film innovations are opening post-consumer collection streams previously excluded from mechanical reprocessing.
- Green bond financing:Sustainability-linked project finance instruments enable mid-scale recyclers to fund decontamination lines without dilutive equity raises.
- Personal care premium positioning:Cosmetic-grade rPET scarcity allows certified suppliers to command price premiums in fragrance and skincare packaging.
Industry Challenges
- Food-contact certification timelines:FDA letters of no objection and EFSA safety assessments require 18-24 month validation cycles that delay commercialization of novel recycling processes.
- Optical sorting technician scarcity:Advanced near-infrared and robotics systems demand specialized maintenance skills that outpace vocational training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Consumer Recycled Plastic Packaging Market |
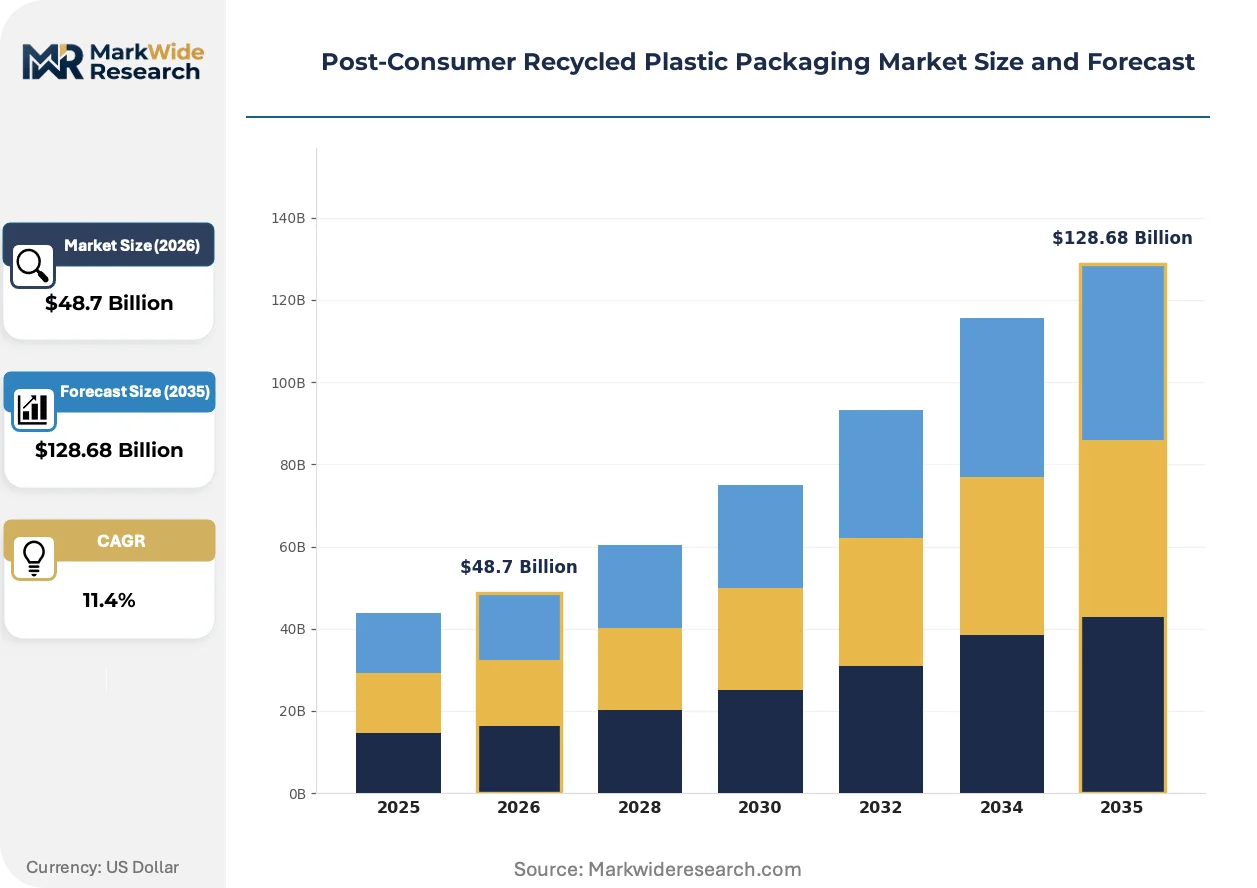
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Films, Rigid Packaging End Use Industry: Food & Beverage, Personal Care, Household Products, Electronics Form: Flexible, Rigid, Injection-Molded, Blow-Molded Thickness: Thin, Medium, Heavy, Extra Heavy |
| Companies Covered | LyondellBasell Industries, Remondis SE & Co. KG, KW Plastics, Ultra-Poly, Envision Plastics, Veolia, Avangard Innovative, Parc Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Consumer Recycled Plastic Packaging Market Strategic Shifts
Decontamination technology maturation is bifurcating the competitive landscape between mechanical recyclers achieving food-grade purity and those confined to lower-value non-contact applications.
Advanced melt filtration combined with solid-state polymerization is migrating from pilot demonstrations to commercial-scale lines. Food and beverage brand technical teams are validating these systems for direct food-contact applications. This migration is compressing the historical price premium between virgin and food-grade recycled resins.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are tightening contamination thresholds for recycled content claims. Converter procurement departments are excluding suppliers lacking EFSA-compliant process certifications. Rigid container segments in France and Italy are responding by consolidating supplier bases around certified German and Dutch reprocessors.
Brand-owner sustainability scorecards now weight recycled content percentage above unit cost in supplier selection algorithms. Traditional spot-market resin purchasing is giving way to multi-year offtake agreements with volume guarantees. This behavioral shift is most visible in German beverage packaging, where converters are locking five-year supply contracts to secure PPWR compliance pathways.
Post-Consumer Recycled Plastic Packaging Market Segmentation
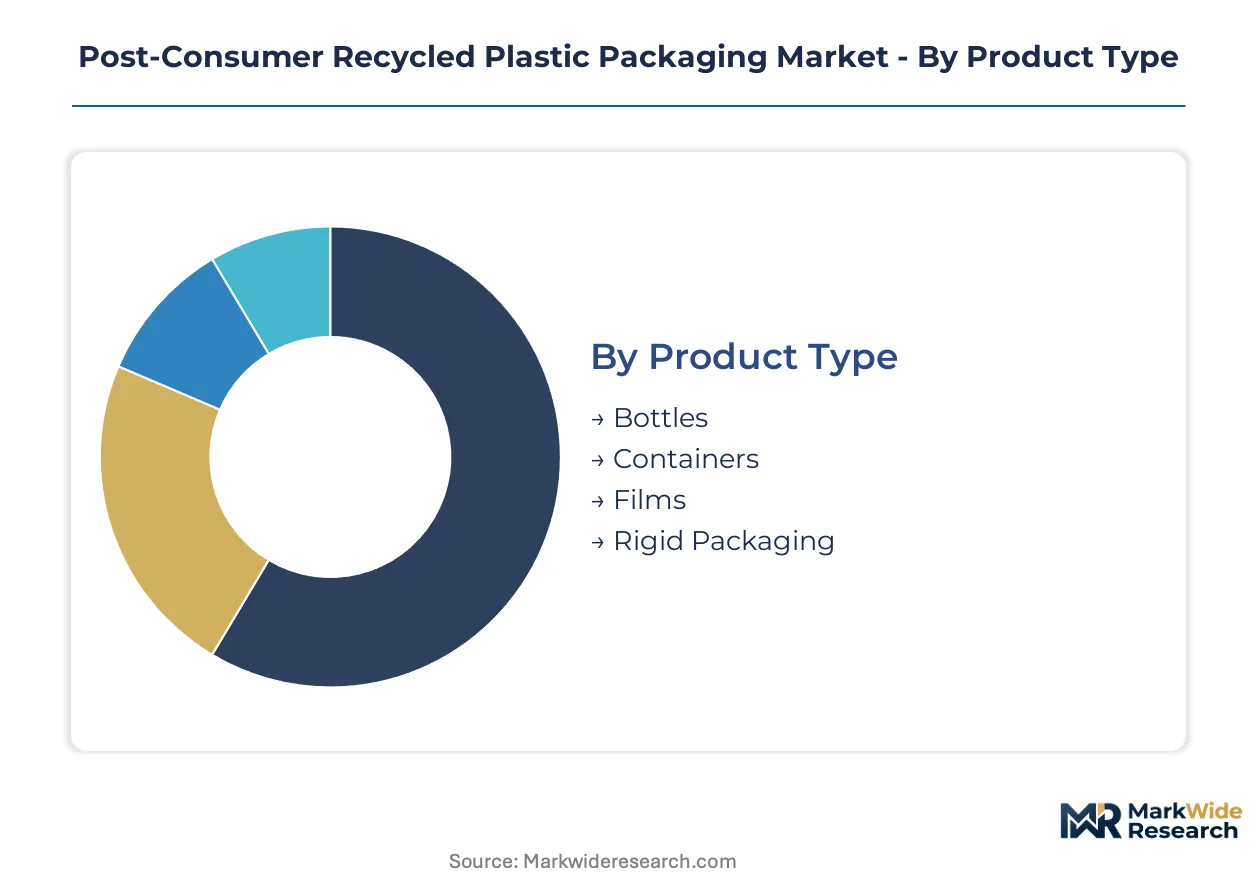
Post-consumer recycled plastic packaging segments diverge sharply by technical certification requirements and value capture potential. Food-contact compliance thresholds create tiered pricing structures that reshape procurement patterns across converter categories.
Product Type:
Volume concentration and collection infrastructure maturity separate high-throughput formats from emerging categories.
- Bottles:Established curbside collection streams and brand-owner commitments anchor demand. German beverage converters lock multi-year rPET supply contracts under PPWR mandates, compressing historical price premiums against virgin resin.
- Films:Mono-material innovations are unlocking previously excluded flexible packaging streams. French and Italian food brands pilot collection programs for multilayer barrier films, though optical sorting limitations constrain scale.
- Containers:HDPE and PP rigid formats serve household and industrial applications with lower purity thresholds than food-contact grades.
- Rigid Packaging:Structural formats including trays and clamshells compete for limited food-grade output from advanced decontamination lines.
Bottles command the established base. The steepest expansion runs through films.
End Use Industry:
Regulatory pressure intensity and certification timelines segment demand by compliance urgency.
- Food & Beverage:EFSA-compliant process certifications gate market access. Bottlers embed recycled content percentage into supplier scorecards, displacing spot-market purchasing with volume-guaranteed offtake agreements.
- Personal Care:Cosmetic-grade rPET scarcity allows certified suppliers to extract premiums. Fragrance and skincare brands compete for limited EFSA-validated output from German and Dutch reprocessors.
- Household Products:Non-contact applications absorb lower-purity mechanical recycling output, insulating margins from food-grade certification costs.
- Electronics:ESD-sensitive packaging demands specialized conductive additives that complicate post-consumer feedstock integration.
Food & Beverage anchors procurement volume. Personal Care climbs fastest on premium positioning.
Form:
Processing technology compatibility determines feedstock flexibility and margin structure.
- Flexible:Film and pouch formats require mono-material construction for mechanical recyclability. Collection infrastructure gaps in Southern Europe limit feedstock security.
- Rigid:Structural formats tolerate broader contamination spectra, preserving reprocessor margins.
- Injection-Molded:Precision tolerances demand consistent melt flow indices that challenge post-consumer feedstock blending ratios.
- Blow-Molded:Container wall thickness uniformity requires advanced filtration that only scaled German and Dutch facilities reliably deliver.
Rigid formats hold the installed base. Flexible packaging gains share fastest on recyclability improvements.
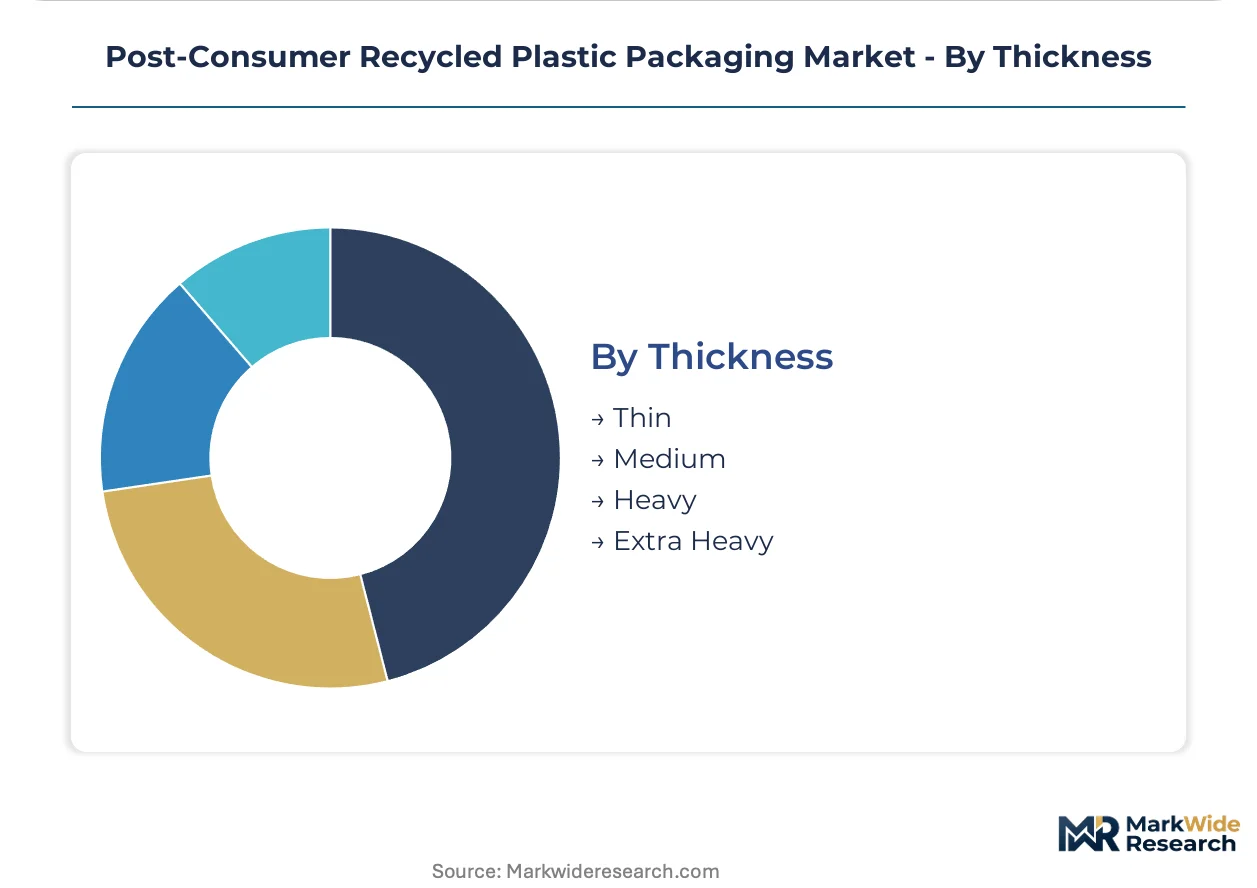
Thickness:
Material intensity and collection economics stratify by unit weight recovery value.
- Thin:Lightweight films maximize transport efficiency but complicate optical sorting identification. Near-infrared systems in German MRFs achieve higher capture rates than Southern European equivalents.
- Medium:Standard gauge formats balance collection economics with reprocessing yield, dominating current throughput.
- Heavy:Industrial totes and drums generate concentrated feedstock streams with lower contamination risk.
- Extra Heavy:Pallet and bulk container applications remain niche due to limited post-consumer collection pathways.
Medium thickness commands current volume. Thin formats expand fastest on lightweighting trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German reprocessors capture food-grade certification premiums that Italian converters cannot replicate locally, creating a north-south pricing asymmetry across European supply chains. This divergence intensifies as EU Packaging and Packaging Waste Regulation deadlines approach.
Germany
Mechanical and chemical recycling investments concentrate in North Rhine-Westphalia and Bavaria, where municipal waste concessions guarantee feedstock security. The country's national packaging regulator enforces strict EFSA compliance timelines that exclude uncertified competitors. Sorting infrastructure in the Ruhr industrial cluster processes volumes unmatched elsewhere in Europe.
United States
EPA landfill diversion targets elevate collection economics for HDPE and PP rigid containers across Midwest manufacturing corridors. FDA letters of no objection enable food-contact applications that command price premiums over non-food grades. KW Plastics anchors North American supply from its Alabama base, serving beverage brands with decontaminated resin.
France
Extended producer responsibility mandates force brand owners to secure long-term recycled resin offtake, concentrating procurement among certified converters. REACH substance restrictions tighten contamination thresholds for recycled content claims. The Paris basin packaging cluster consolidates supplier bases around German and Dutch reprocessors to secure PPWR compliance.
Netherlands
Advanced optical sorting capacity clusters in Rotterdam-Antwerp corridor facilities, enabling high-purity rPET output for beverage applications. The country's environmental regulator recognizes mass-balance accounting methods for chemical recycling output. Eindhoven-region technology providers export sorting systems to Southern European markets lacking domestic capacity.
Italy
Flexible packaging recyclability pilots target multilayer barrier films previously excluded from mechanical reprocessing. The EU Packaging and Packaging Waste Regulation imposes binding recycled content thresholds that reshape converter procurement criteria. Northern Italian packaging hubs in Lombardy and Emilia-Romagna depend on cross-border feedstock transfers from German sorting facilities.
Post-Consumer Recycled Plastic Packaging Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in feedstock aggregation and purification technology. The vendor base stratifies between integrated polymer producers with captive resin positions and independent recyclers competing on certification speed. Two archetypes dominate: vertically integrated chemical companies leveraging long-term offtake agreements, and specialized mechanical recyclers focused on single-resin scale. Competitive moves concentrate on securing municipal waste concessions and achieving food-grade process certifications ahead of regulatory deadlines.
Within the integrated polymer tier, LyondellBasell Industries and BASF SE exemplify platform strategies that combine virgin production with recycled content streams. Among specialized recyclers, Veolia represents the waste-management-integrated archetype, while KW Plastics occupies a position as a North American rigid-container specialist. These three anchors demonstrate how geographic feedstock control and certification timing determine competitive positioning.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Remondis SE & Co. KG |
| KW Plastics |
| Ultra-Poly |
| Envision Plastics |
| Veolia |
| Avangard Innovative |
| Parc Corporation |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in German chemical recycling facilities is pulling food-grade rPET premiums upward while compressing margins for Southern European converters lacking local decontamination capacity. This utilization asymmetry rewards integrated polymer producers with captive resin positions and penalizes spot-market-dependent packaging converters facing EFSA certification deadlines.
Pricing Analysis
Food-grade certification premiums versus non-contact grade spreads are widening as EU Packaging and Packaging Waste Regulation thresholds tighten. Three-tier pricing structure across food-contact, cosmetic-grade, and industrial non-contact levels reflects decontamination investment recovery timelines. Cost compression in non-food grades is intensifying because virgin polymer price volatility erodes mechanical recycler margins. Household product converters exhibit highest price sensitivity due to substitution elasticity with virgin HDPE, while fragrance brands absorb premiums for cosmetic-grade rPET scarcity.
Supply Chain Analysis
Tariff exposure between post-consumer plastic waste exporters and German reprocessors remains minimal, though cross-border feedstock transfers from Southern Europe concentrate logistics risk. Feedstock security draws from municipal waste concession contracts in Germany, the Netherlands, and France, with baled post-consumer plastic flows resting on sorting infrastructure clustered in North Rhine-Westphalia and Rotterdam-Antwerp corridor. Single-source vulnerability sits with optical sorting equipment providers based in Eindhoven-region technology clusters. Distribution runs through long-term offtake agreements with volume guarantees rather than spot-market resin purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-consumer recycled plastic packaging sits in early-cycle expansion as extended producer responsibility mandates force brand-owner procurement reformulation ahead of regulatory deadlines. Food-contact certification scarcity creates first-mover advantages for reprocessors achieving EFSA validation.
For Market Incumbents: Harden municipal waste concession positions in Germany and the Netherlands through contract renewals that lock feedstock volumes for chemical recycling scale-up. Deepen backward integration into optical sorting technology to reduce equipment vendor dependency. Prioritize solid-state polymerization line investments ahead of PPWR compliance deadlines to capture food-grade premium positioning.
For New Entrants and Emerging Players: Establish a beachhead in flexible packaging recyclability pilots targeting mono-material film collection streams in France and Italy. Personal care cosmetic-grade rPET supply gaps offer penetrable white-space with premium pricing power. Pursue green bond financing instruments to fund decontamination capacity without dilutive equity raises.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized mechanical recyclers with single-resin scale in HDPE and PP rigid containers. Long-term viability across the analysis window favors facilities with demonstrated food-grade certification speed and geographic feedstock control. Mass-balance accounting standardization progress serves as the critical signal to watch for chemical recycling margin capture inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Food-Grade Certification Investment | EFSA-compliant process validation gates European market access for rigid packaging converters. |
| Chemical Recycling Scale-Up | Pyrolysis capacity expansion in Germany unlocks food-contact eligible resin beyond mechanical limits. |
| Municipal Concession Renewal | Waste management contracts in North Rhine-Westphalia guarantee feedstock security for reprocessing hubs. |
| Green Bond Financing | Sustainability-linked instruments enable mid-scale recyclers to fund optical sorting without balance-sheet strain. |
| Long-Term Offtake Agreements | Multi-year volume guarantees displace spot-market purchasing among German beverage packaging converters. |
Study Parameters
Cross-validation between regulatory filing analysis and reprocessor capacity announcements anchors the qualitative findings in this study. Primary interviews with municipal waste procurement officers, packaging converter technical directors, polymer plant managers, and brand-owner sustainability leads combined with secondary validation from EFSA safety assessments, EPA landfill diversion reports, EU Packaging and Packaging Waste Regulation impact assessments, and customs trade data for post-consumer plastic bale movements. Bottom-up facility capacity modeling and top-down demand projection from end-use industry procurement commitments provided triangulation.
Calibration against historical certification timeline data and feedstock price elasticity patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, form, thickness, and regional regulatory cluster. CAGRs derived from facility-by-facility capacity buildout schedules and brand-owner recycled content commitment trajectories. Chemical recycling mass-balance accounting recognition progress and optical sorting technician training program output served as industry-specific forecast inputs.
Sensitivities concentrate around regulatory deadline enforcement intensity, virgin polymer price volatility, and chemical recycling output certification speed. Forecasts reflect documented assumptions on EFSA validation cycle durations and municipal concession renewal success rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Europe PET Packaging Market