
 Paper Glass Maker Market | 2026-2036
Paper Glass Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Glass Maker Market Analytics
Indian machinery clusters is consolidating output of mid-speed paper glass forming equipment for domestic and export buyers. Huhtamaki leverages its integrated pulp-to-cup operations to anchor demand for high-throughput lines across Nordic markets. Paper Machinery Corporation sustains engineering leadership in double-wall insulated cup forming for North American beverage chains. New Debao Machinery dominates compact servo-driven systems priced for Asian small-to-mid converters.
A paper glass maker forms disposable beverage containers from pulp slurry, bamboo fiber, or coated paperboard using heated molds and mechanical pressing at pressures exceeding 10 bar to achieve leak-resistant walls. The primary purpose is producing single-use cups that replace plastic and foam alternatives in foodservice supply chains. Disposable Cups captures the largest volume share as quick-service restaurants standardize paper-based cold and hot drink vessels. Biodegradable Containers represents the fastest-expanding category as PLA-lined and bamboo-fiber equipment attracts premium pricing from sustainability-focused buyers in European and East Asian markets.
India's BIS food-contact safety standards and China's SAMR disposable tableware regulations mandate migration testing and fiber sourcing documentation that shapes equipment specification sheets. The EU Green Deal and REACH restrictions on perfluorinated coatings push European converters toward PFAS-free barrier technologies, redirecting R&D budgets for mold surface engineering. Stakeholders must monitor how fragmented national bioplastic certification regimes alter tooling compatibility requirements before committing to multi-material platform investments.
Market Dynamics
Single-use plastic bans across foodservice markets are compressing equipment replacement cycles, forcing converters to retool for fiber-based barrier technologies faster than typical capital planning horizons allow.
Growth Catalysts
- BIS food-contact mandates:India's safety certification requirements for molded fiber tableware are accelerating domestic machinery upgrades and creating export-ready production capacity.
- Quick-service restaurant standardization:Global beverage chains are mandating paper-based cold and hot drink vessels across franchise networks, locking in equipment demand for double-wall forming lines.
- Bamboo fiber processing advances:New pulping and refining methods for agricultural residues are expanding raw material availability beyond wood pulp, reducing feedstock concentration risk.
Market Restraints
- PFAS barrier chemistry restrictions:REACH and state-level US prohibitions on perfluorinated coatings are forcing premature mold retooling before alternative barrier technologies mature.
- Specialized alloy supply concentration:Precision heating elements and corrosion-resistant mold surfaces depend on nickel and cobalt supply chains concentrated in specific mining jurisdictions.
- Energy cost volatility:Thermal forming processes require sustained high temperatures, exposing converters to natural gas and electricity price swings that compress operating margins.
Strategic Opportunities
- Indonesian foodservice expansion:Quick-service restaurant penetration in secondary Indonesian cities remains below saturation, creating first-mover equipment placement potential.
- EU Green Deal procurement incentives:Public sector catering contracts now prioritize biodegradable containers, redirecting institutional buyer specifications toward certified fiber equipment.
- Servo-electric and ultrasonic welding convergence:Hybrid forming systems combining precision motion control with cold-seal bonding are opening premium pricing tiers for leak-proof double-wall production.
Industry Challenges
- Multi-material platform integration:Converters must engineer tooling compatibility across PLA-lined, aqueous-coated, and uncoated fiber grades without dedicated production lines per substrate.
- PFAS-free certification timelines:Third-party migration testing and compostability verification for new barrier chemistries extend product launch schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Glass Maker Market |
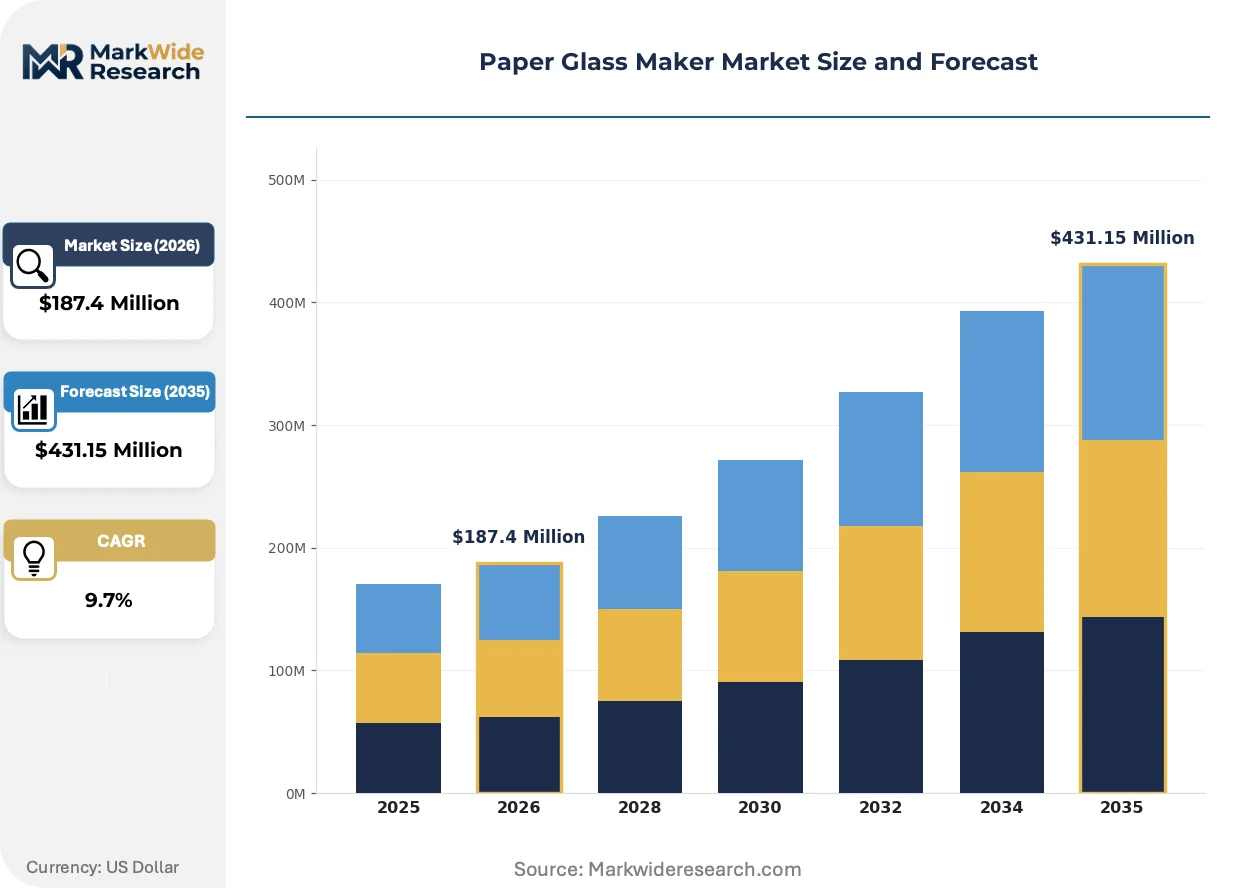
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Cups, Biodegradable Containers, Eco-Friendly Packaging, Recyclable Glasses Material: Pulp, Bamboo Fiber, Recycled Paper, PLA End User: Restaurants, Cafes, Events, Catering Services Distribution Channel: Online Retail, Wholesale Distributors, Supermarkets, Specialty Stores |
| Companies Covered | Huhtamaki, Paper Machinery Corporation, New Debao Machinery, Ruian Mingyuan Machinery, Jain Industries, Win Shine Machinery, Sunwell Global, SEE Machinery, JBZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Glass Maker Market Evolving Landscape
Equipment architecture is fragmenting into modular, speed-tiered platforms that let converters scale throughput without full line replacement. This shift is compressing the traditional distinction between entry-level and industrial-grade machinery.
Servo-driven forming stations are decentralizing production economics by enabling mid-volume converters to achieve precision previously locked behind high-capital rotary systems. Boutique coffee roasters and regional bakery chains are adopting these compact units for captive cup supply. The technology is decentralizing geographic production patterns, allowing distributed manufacturing closer to urban consumption centers rather than centralized export hubs.
China's GB standards on disposable tableware are tightening migration limits for heavy metals and fluorescent whitening agents, forcing equipment makers to redesign heating element alloys and mold surface treatments. Domestic converters face compliance deadlines that outpace alternative barrier coating availability. The regulation is accelerating R&D partnerships between machinery builders and chemical suppliers to validate new barrier formulations before enforcement dates.
Direct equipment financing from pulp suppliers is restructuring how converters acquire forming lines, with fiber producers embedding machinery costs into long-term feedstock contracts. Small-to-mid converters in Vietnam and Thailand are bypassing traditional equipment loans through these bundled arrangements. The model is most visible in Southeast Asian markets where banking infrastructure for industrial credit remains underdeveloped relative to manufacturing expansion rates.
Paper Glass Maker Market Segmentation
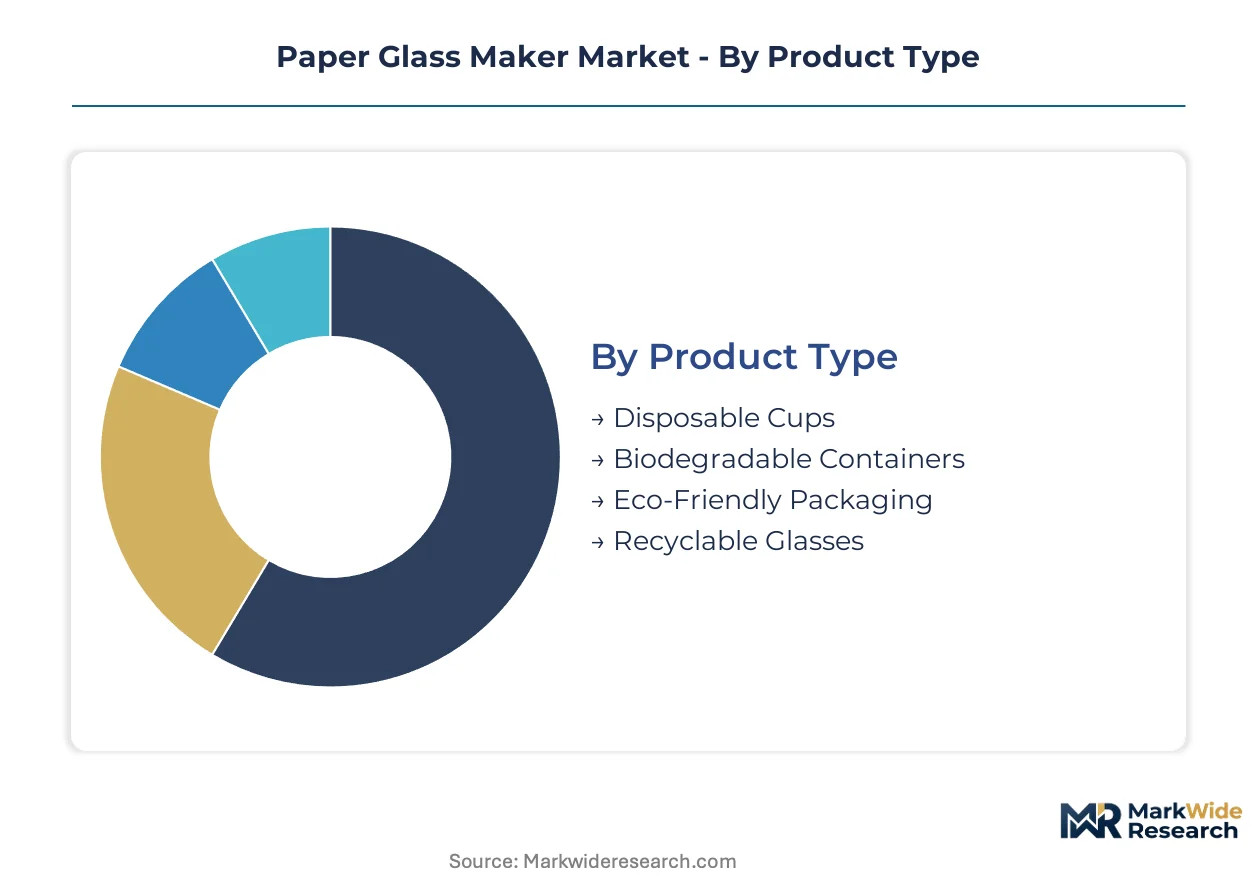
Paper glass maker equipment serves distinct production workflows ranging from standalone forming stations to integrated barrier-coating lines. Segmentation reveals how converter scale, substrate choice, and end-use specifications reshape machinery specifications across installation types.
Product Type:
Standalone forming units dominate small-to-mid converter installations, while integrated pulp-to-cup lines anchor large-scale fiber operations with captive barrier coating.
- Disposable Cups:Heated mold systems press pulp slurry into single-wall and double-wall configurations at pressures exceeding 10 bar. Quick-service restaurant procurement standardization across India and Southeast Asia concentrates demand for high-throughput rotary forming lines capable of cold and hot beverage compatibility.
- Biodegradable Containers:PLA-lined and aqueous-coated fiber processing requires modified heating profiles and mold surface treatments to prevent coating degradation during forming. European institutional catering contracts under EU Green Deal procurement rules accelerate specification shifts toward certified compostable output.
- Eco-Friendly Packaging:Secondary containment and retail-ready presentation formats.
- Recyclable Glasses:Uncoated fiber and minimal-barrier designs for closed-loop collection systems.
Disposable Cups leads volumes today; Biodegradable Containers is gaining share fastest.
Material:
Substrate selection determines heating element alloy requirements, mold surface engineering, and barrier compatibility validation protocols.
- Pulp:Wood fiber slurry remains the baseline feedstock for conventional forming equipment. Maharashtra and Gujarat manufacturing clusters in India source bleached and unbleached grades from integrated pulp suppliers, with BIS food-contact mandates driving migration testing documentation.
- Bamboo Fiber:Agricultural residue pulping expands raw material availability beyond wood supply chains. New refining methods reduce fiber length variability, enabling processing on standard forming lines with modified screening stations.
- Recycled Paper:Post-consumer fiber streams with controlled contaminant thresholds.
- PLA:Bioplastic lining requires temperature-restricted forming zones and specialized bonding stations.
Pulp retains the largest installed base; Bamboo Fiber shows the steepest expansion trajectory among alternative feedstocks.
End User:
Equipment specifications diverge sharply between high-frequency beverage service operations and intermittent event-based consumption patterns.
- Restaurants:Full-service and quick-service chains demand double-wall insulated forming lines with integrated rim-rolling and leak-testing stations. China's SAMR disposable tableware regulations and India's BIS certification requirements mandate equipment upgrades for migration compliance across franchise networks.
- Cafes:Boutique coffee roasters and regional chains adopt compact servo-driven systems for captive cup supply. Distributed production economics enable urban manufacturing proximity rather than centralized export hub dependency.
- Events:Seasonal and stadium-based consumption with surge-volume requirements.
- Catering Services:Institutional and contract foodservice with specification-driven procurement.
Restaurants command the majority of installed capacity; Cafes are expanding equipment placement most rapidly through decentralized servo-electric adoption.
Distribution Channel:
Machinery acquisition pathways fragment between direct manufacturer relationships, bundled pulp-supplier financing, and traditional equipment financing.
- Online Retail:Digital platforms facilitate spare parts, consumables, and compact auxiliary equipment procurement. Southeast Asian converters in Vietnam and Thailand leverage online channels where industrial banking infrastructure remains underdeveloped relative to manufacturing expansion rates.
- Wholesale Distributors:Regional machinery dealers provide installation, commissioning, and aftermarket service networks. Indonesian foodservice expansion in secondary cities depends on distributor presence for technical support and spare parts logistics.
- Supermarkets:Limited machinery relevance; primarily finished goods retail.
- Specialty Stores:Niche equipment and retrofit components for specific forming line upgrades.
Wholesale Distributors maintains the deepest equipment placement relationships; Online Retail is climbing fastest for auxiliary and replacement component procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting paper glass maker equipment procurement toward jurisdictions where compliance costs remain manageable relative to enforcement rigor. India's BIS certification timeline and China's GB standards implementation have created divergent equipment specification demands that converters exploit through strategic facility placement.
India
Quick-service restaurant chains in Mumbai and Bangalore are mandating double-wall paper vessels across franchise networks. BIS food-contact safety standards for molded fiber tableware require migration testing documentation that shapes equipment specification sheets. Maharashtra and Gujarat manufacturing clusters concentrate domestic machinery output for both local consumption and Southeast Asian export.
China
GB standards on disposable tableware are tightening migration limits for heavy metals and fluorescent whitening agents. SAMR enforcement deadlines outpace alternative barrier coating availability, forcing equipment makers to redesign heating element alloys. Zhejiang and Guangdong provinces host the densest concentrations of compact servo-driven system fabricators serving domestic small-to-mid converters.
Indonesia
Quick-service restaurant penetration in Surabaya and Bandung remains below saturation, creating first-mover equipment placement potential. The national food and drug regulator mandates food-contact material safety assessments that parallel ASEAN harmonization efforts. Java-based distributors are expanding technical service networks to support secondary city converter installations.
Germany
EU Green Deal procurement rules prioritize biodegradable containers for public sector catering contracts. REACH restrictions on perfluorinated coatings redirect R&D budgets toward PFAS-free barrier technologies. Bavarian and Baden-Württemberg industrial zones concentrate precision mold surface engineering capabilities for high-throughput European lines.
United States
State-level prohibitions on perfluorinated coatings are forcing premature mold retooling before alternative barrier technologies mature. FDA food-contact notification requirements apply to new barrier chemistries entering interstate commerce. Midwest manufacturing corridors maintain legacy installed bases of rotary forming equipment awaiting upgrade cycles.
Paper Glass Maker Market Competitive Landscape
European producers anchor the premium-tier equipment segment; Asian specialists hold volume positions in compact servo-driven systems. The vendor base stratifies across three tiers: integrated pulp-to-cup operators, dedicated machinery engineering houses, and regional compact system fabricators. Strategic moves center on R&D partnerships with chemical suppliers for barrier validation and direct equipment financing bundled with long-term feedstock contracts.
Within the integrated operations tier, Huhtamaki anchors demand for high-throughput lines through its captive pulp-to-cup facilities. Paper Machinery Corporation exemplifies engineering-focused specialists with sustained leadership in double-wall insulated forming configurations. New Debao Machinery occupies the compact servo-driven segment, pricing systems for Asian small-to-mid converters seeking distributed production economics.
| Leading Market Players |
|---|
| Huhtamaki |
| Paper Machinery Corporation |
| New Debao Machinery |
| Ruian Mingyuan Machinery |
| Jain Industries |
| Win Shine Machinery |
| Sunwell Global |
| SEE Machinery |
| JBZ |
| Others |
Value Network & Pricing Analysis
Wood pulp futures pricing cascades through paper glass maker supply chains into three distinct equipment tiers, with bleached kraft index movements in Nordic markets transmitting within quarters to Asian machinery quotations. Maharashtra and Gujarat manufacturing clusters absorb feedstock volatility through long-term offtake contracts that anchor mid-speed line pricing for domestic and Southeast Asian buyers.
Pricing Analysis
Distributor margins of 12-18% separate factory gate from landed equipment costs across Indonesian and Vietnamese markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with BIS-compliant lines commanding 15-25% premiums over uncertified alternatives. Pricing pressure stems from nickel and cobalt alloy cost volatility in precision heating elements. Small-to-mid converters in secondary Asian cities exhibit highest price sensitivity, while European institutional buyers prioritize PFAS-free barrier compatibility over capital expenditure.
Supply Chain Analysis
Specialty alloy supply rests on Indonesian nickel mining jurisdictions and Congolese cobalt extraction, creating concentrated upstream dependency for corrosion-resistant mold surfaces and precision heating elements. Pulp slurry preparation equipment draws from Finnish and Brazilian wood fiber suppliers, while servo-drive components source from Japanese and German motion control specialists. Single-source vulnerability in rare earth magnet supply for compact forming motors threatens production schedules. Distribution runs through regional machinery dealers in Surabaya and Bandung with captive spare parts inventory, supplemented by direct manufacturer relationships for large-scale integrated lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
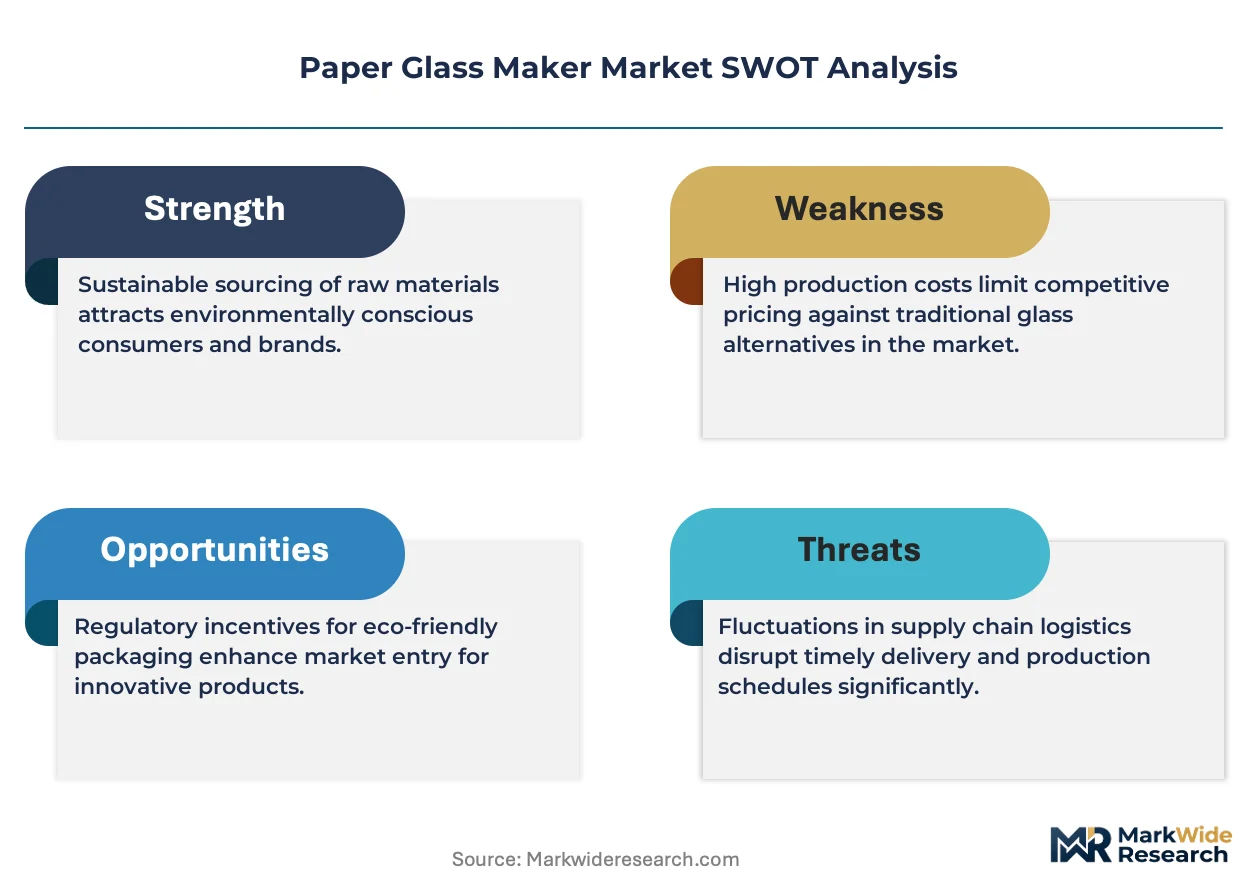
Paper glass maker equipment has transitioned to a late-cycle quality story as quick-service restaurant procurement standardization shifts specifications toward double-wall insulated forming with integrated leak-testing. Premium tier equipment capturing this demand commands sustained pricing power despite feedstock volatility.
For Market Incumbents: Deploy backward integration into captive pulp supply to secure feedstock cost predictability against Asian fiber price swings. Consolidate aftermarket service networks in Indonesian secondary cities before distributor saturation locks out expansion. Defensive positioning requires PFAS-free barrier R&D partnerships with chemical suppliers ahead of REACH enforcement tightening. For New Entrants and Emerging Players: BIS certification mandates in India open a window for compact servo-driven system placement among Maharashtra and Gujarat converters seeking export-ready capacity. Target boutique coffee roaster captive supply in urban Indian and Southeast Asian markets where distributed production economics displace centralized hub dependency. Go-to-market through direct equipment financing bundled with long-term fiber contracts bypasses underdeveloped industrial banking infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with precision mold surface engineering specialists serving European PFAS-free barrier transitions. Five-to-ten year viability favors equipment makers with validated multi-material platform compatibility across PLA-lined, aqueous-coated, and uncoated fiber grades. Watch for Indonesian foodservice penetration rates in Surabaya and Bandung as inflection signal for regional capacity demand.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Barrier R&D Partnership | REACH restrictions in Europe and state-level US prohibitions force premature mold retooling before alternative chemistries mature. |
| Direct Equipment Financing Bundling | Pulp suppliers in Vietnam and Thailand embed machinery costs into long-term feedstock contracts, bypassing traditional equipment loans. |
| Servo-Electric Platform Convergence | Hybrid forming systems combining precision motion control with cold-seal bonding open premium pricing tiers for leak-proof double-wall production. |
| Indonesian Secondary City Expansion | Quick-service restaurant penetration in Surabaya and Bandung remains below saturation, creating first-mover equipment placement potential. |
| Multi-Material Platform Integration | Converters must engineer tooling compatibility across PLA-lined, aqueous-coated, and uncoated fiber grades without dedicated production lines per substrate. |
Research Methodology
Multiple input streams — equipment procurement databases, regulatory filing repositories, and pulp futures pricing indices — were reconciled through bottom-up and top-down triangulation. Primary interviews with paper glass forming equipment plant managers, quick-service restaurant procurement leads, pulp supplier technical directors, and aftermarket service heads in India, China, and Southeast Asia were validated against secondary sources including BIS certification registries, SAMR disposable tableware standards documentation, EU Green Deal procurement rule filings, and customs trade data for specialty alloy imports.
Data-stream reconciliation anchored volume and value projections across the analysis window through segmented modeling of product type, material substrate, end-user scale, and distribution channel. Segment-level growth trajectories reflected equipment replacement cycles compressed by single-use plastic bans, bamboo fiber processing advances expanding raw material availability, and servo-driven forming station adoption decentralizing production economics. CAGRs were derived from installed base turnover rates and new capacity absorption patterns in regional manufacturing clusters.
Revisions become necessary when PFAS-free barrier certification timelines extend beyond enforcement deadlines, nickel and cobalt supply disruptions alter specialty alloy availability, or Indonesian quick-service restaurant penetration accelerates faster than distributor technical service expansion. A small set of named triggers — regulatory compliance deadlines, critical mineral supply shocks, and foodservice expansion rates in secondary Asian cities — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Pharma Glass Tubing Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Global Scratch Resistant Glass Market
Glass
East Africa Flat Glass Market
Glass
Coated Glass Market
Glass
Flexible Glass Market
Glass
Laboratory Glassware Market
Glass
Foam Glass Granulate Market
Glass
Latin America Flat Glass Market
Glass
Shatterproof Glass Market
Glass
Glass Insulator Market
Glass
North America Flat Glass Market
Glass
Impact Resistant Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Optical Materials Market
Glass
Global Silicone Structural Glazing Market