
 GCC Flat Glass Market | 2026-2036
GCC Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Flat Glass Market Intelligence
Buyer concentration among large-scale developers and government-backed project owners is expanding across the GCC, shifting procurement power toward entities with multi-billion-riyal pipelines. Guardian Glass LLC leverages its regional float glass capacity to serve mega-project contracts with predictable volume commitments. Saint-Gobain Middle East anchors its position through specialized coated glass formulations designed for extreme solar gain conditions. Emirates Glass LLC competes on tempered and laminated fabrication proximity to Dubai and Riyadh construction clusters.
Flat glass comprises soda-lime silica sheets produced through the float process, typically ranging from 2 mm to 25 mm in thickness, engineered for optical clarity, thermal performance, and structural integrity in building envelopes and transportation applications. Tempered glass dominates volume flows into high-rise facades across the GCC, where safety mandates require heat-strengthened or fully tempered glazing above specified heights. Insulated glass units command premium positioning as energy codes tighten, with double-glazed configurations becoming baseline specifications for new commercial stock in Saudi Arabia and the UAE.
Saudi Standards, Metrology and Quality Organization (SASO) energy efficiency requirements and UAE's Estidama Pearl Rating System shape product compliance thresholds for glazing U-values and solar heat gain coefficients. Dubai Municipality's Green Building Regulations and Specifications mandate performance-tested glass in all new construction above defined floor areas. Stakeholders must monitor how evolving national building codes across individual GCC states synchronize or diverge on thermal performance benchmarks, as this determines whether pan-regional product platforms or country-specific SKUs prove more economical.
Market Dynamics
Buyer consolidation among Saudi giga-project developers and UAE sovereign wealth-backed contractors is compressing supplier margins while demanding guaranteed volume commitments from float glass manufacturers.
Growth Catalysts
- Neom and Red Sea Project Pipelines:Saudi Arabia's gigaproject construction schedules are pulling forward multi-year coated glass procurement contracts, locking in supplier capacity through 2030.
- Estidama Pearl Rating System:Abu Dhabi's green building mandate is accelerating specification of low-emissivity glazing across commercial developments exceeding defined floor area thresholds.
- Float Glass Process Refinement:Thinner-gauge production capabilities are expanding addressable applications in lightweight curtain wall systems for high-rise towers across Dubai and Riyadh.
Market Restraints
- Natural Gas Price Volatility:Float glass furnaces in the GCC depend on subsidized natural gas feedstock; any subsidy reduction would compress manufacturing margins immediately.
- Raw Material Import Dependence:High-purity silica sand and soda ash supply concentrates outside the Gulf, exposing producers to shipping cost fluctuations and currency risk.
- Technical Limitation in Thinner Gauges:Sub-3mm float production for specialized electronics and automotive applications remains uneconomical at regional scale, forcing import reliance.
Strategic Opportunities
- Kuwait and Bahrain Construction Recovery:Post-pandemic infrastructure investment cycles in these smaller GCC markets offer first-mover advantages for insulated glass unit suppliers establishing local fabrication.
- Building-Integrated Photovoltaics Convergence:Transparent photovoltaic glass technology is creating new specification channels where solar performance and architectural glazing merge.
- Dubai 2040 Urban Master Plan:The emirate's density targets mandate higher-performance building envelopes, expanding the addressable market for triple-glazed and dynamic glazing systems.
Industry Challenges
- Specialized Coating Technician Scarcity:Magnetron sputtering and chemical vapor deposition operations require skilled operators whose training pipelines lag regional capacity expansion.
- SASO Certification Timelines:Saudi product conformity assessment procedures for energy-efficient glazing extend market entry cycles for new coated formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Flat Glass Market |
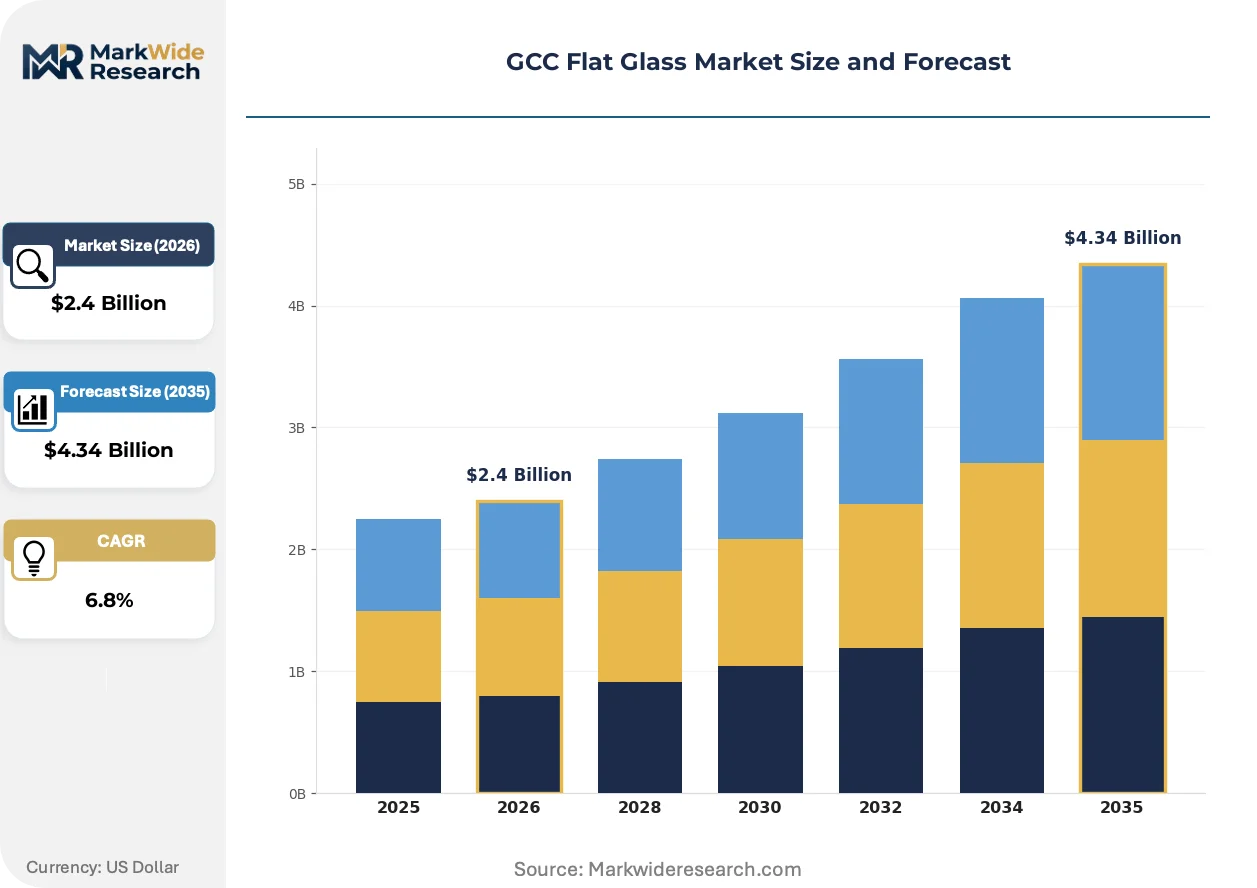
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Insulated Glass, Coated Glass Application: Construction, Automotive, Electronics, Furniture End User: Architects, Builders, Manufacturers, Retailers Thickness: Single Glazed, Double Glazed, Triple Glazed, Multi Glazed |
| Companies Covered | Guardian Glass LLC, AGC Inc., Emirates Glass LLC, Sisecam Group, Saint-Gobain Middle East, Gulf Glass Industries LLC, Obeikan Glass Company, Nippon Sheet Glass Co., Ltd., Saudi American Glass Company Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Flat Glass Market Strategic Shifts & Innovations
Electrochromic and thermochromic glazing technologies are migrating from aviation and automotive origins into commercial building specifications, compressing the performance gap between static and dynamic solar control.
Electrochromic glass is electrifying facade design possibilities across Dubai's premium commercial towers. Developers at Burj Khalifa District and DIFC Gate District are specifying tint-on-demand systems that eliminate external shading hardware. This technology is electrifying the traditional static-glazing procurement model, shifting specifications toward performance-guaranteed service contracts rather than commodity sheet purchases.
UAE's updated Al Sa'fat green building regulations now mandate solar heat gain coefficient disclosures for all external glazing in new construction above 5,000 square meters. The industrial consequence is a forced upgrade of fabrication line capabilities toward online low-E coating. Saudi Arabia's SASO is observing these compliance patterns, with technical committees reviewing parallel disclosure requirements for Riyadh's developing building code.
Consolidated procurement desks at Saudi Public Investment Fund project entities are displacing fragmented contractor purchasing. Single-source glazing specifications now cover entire district developments rather than tower-by-tower procurement. This concentration is most visible at Neom's The Line and Oxagon, where master supply agreements span decade-long horizons and lock out smaller fabrication competitors.
GCC Flat Glass Market Segmentation
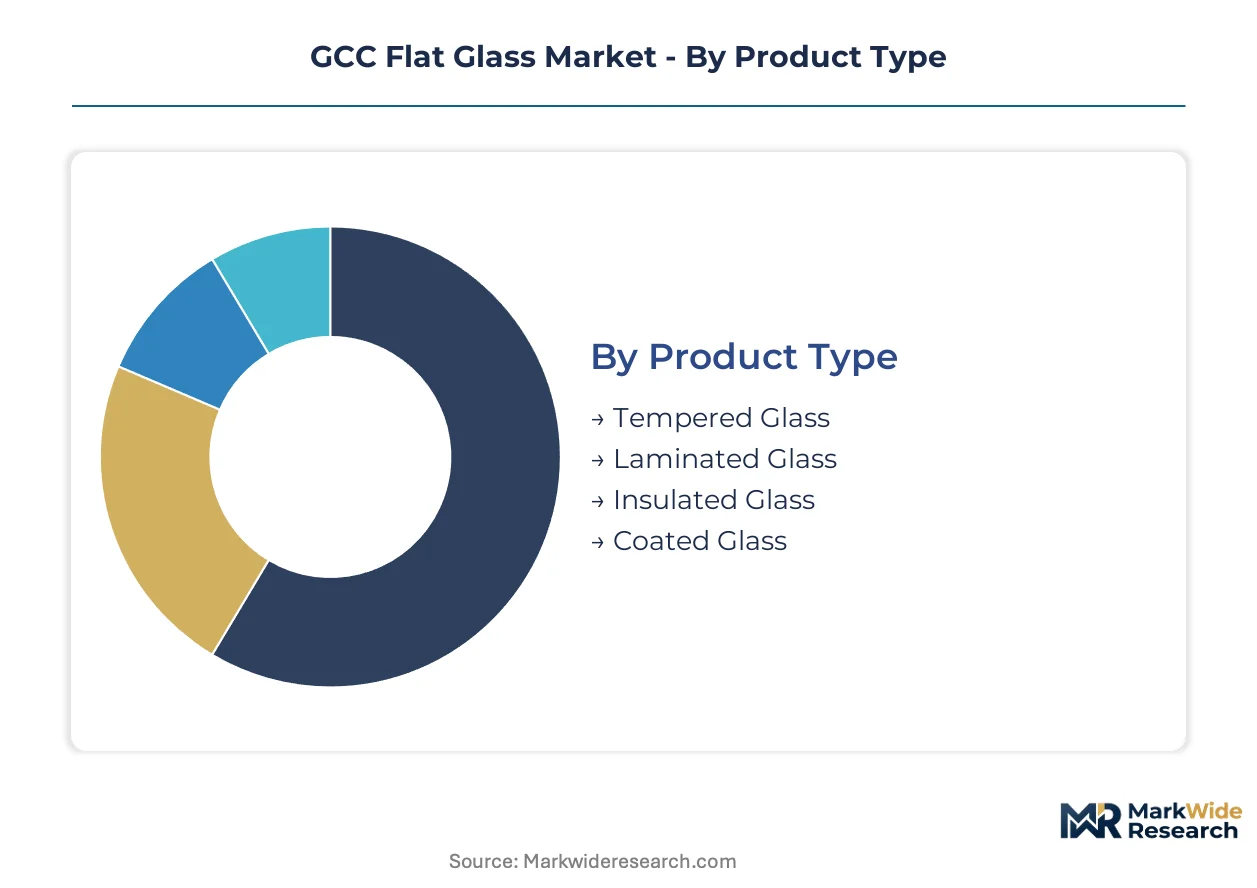
Product differentiation across the GCC flat glass market determines furnace allocation, coating line investment, and margin capture. Segmentation reveals how technical specifications align with regulatory mandates and project-scale procurement patterns.
Product Type:
Float glass capacity concentrates on value-added processing segments where Saudi and UAE manufacturers have secured giga-project supply contracts.
- Tempered Glass:Heat-strengthened sheets undergo controlled thermal treatment to achieve 4-5x mechanical strength versus annealed float. Saudi Arabia's Neom and Red Sea developments specify tempered glazing for all facade elements above ground level, pulling volume toward domestic heat-treatment furnaces.
- Coated Glass:Magnetron sputtered low-emissivity and solar control layers modify optical properties without compromising visible light transmission. Dubai Municipality's green building disclosure mandates are accelerating procurement of online and offline coated products for commercial towers exceeding 5,000 square meters.
- Laminated Glass:Polyvinyl butyral interlayers bond multiple glass plies for safety and acoustic performance. Automotive windscreen and high-security building applications in Riyadh and Jeddah drive specification.
- Insulated Glass:Factory-sealed double and triple glazing units deliver thermal performance through inert gas fills and warm-edge spacers. Abu Dhabi's Estidama Pearl Rating System requires these configurations for commercial developments seeking sustainability certification.
Tempered glass absorbs the bulk of installed capacity; coated glass is expanding most quickly.
Application:
End-use demand distributes across construction intensity, automotive assembly localization, and electronics manufacturing feasibility.
- Construction:Curtain wall, window, and skylight specifications dominate volume flows. Saudi giga-projects and Dubai high-rise pipelines command multi-year procurement commitments.
- Automotive:Windshield, side lite, and backlite requirements from regional vehicle assembly plants. Laminated and tempered products serve OEM and aftermarket channels.
- Electronics:Display substrate and touch panel cover glass demand. Sub-3mm gauge requirements force import reliance as regional float lines lack thin-gauge economics.
- Furniture:Tabletop, shelving, and decorative applications. Tempered and processed mirror products serve retail and hospitality fit-out segments.
Construction commands the dominant share of regional float output; electronics applications show the steepest expansion trajectory.
End User:
Procurement authority concentrates among entities controlling project pipelines and specification authority.
- Architects:Design-phase specification of performance characteristics including U-values, solar heat gain coefficients, and visible light transmission. Dubai and Riyadh practices increasingly mandate dynamic glazing for premium commercial towers.
- Builders:Construction-phase procurement and installation coordination. Saudi Public Investment Fund project entities consolidate purchasing across district-scale developments.
- Manufacturers:Downstream processing into windows, doors, and automotive components. Local fabrication clusters in Jebel Ali and Riyadh Second Industrial City source float and coated parent stock.
- Retailers:Distribution of replacement glass and consumer products. Smaller volume flows with higher service requirements.
Builders control the largest procurement volumes; architects are gaining specification influence fastest.
Thickness:
Glazing configuration determines thermal performance compliance and fabrication complexity.
- Double Glazed:Two glass lites separated by spacer and desiccant with air or argon fill. Baseline specification for new commercial construction across Saudi Arabia and the UAE under tightening energy codes.
- Triple Glazed:Three lites with dual cavities delivering enhanced thermal resistance. Premium commercial and residential applications in Dubai's sustainable building pipeline.
- Single Glazed:Single lite applications in interior partitions, furniture, and legacy building stock. Declining share in new construction.
- Multi Glazed:Four or more lites for specialized acoustic or extreme climate performance. Niche applications in airport terminals and recording facilities.
Double glazed configurations absorb the bulk of insulated glass unit capacity; triple glazed systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia and the UAE, where giga-project pipelines and green building mandates are compressing procurement timelines. Smaller GCC markets present recovery-driven entry points for fabrication capacity.
Saudi Arabia
Neom and Red Sea Project construction schedules are pulling forward multi-year coated glass procurement contracts through 2030. SASO energy efficiency requirements shape product compliance thresholds for glazing U-values across Riyadh and Jeddah corridors. Riyadh Second Industrial City hosts domestic heat-treatment furnaces serving district-scale developments.
United Arab Emirates
Dubai's high-rise pipeline and Abu Dhabi's commercial stock expansion drive specification of low-emissivity glazing. Dubai Municipality Green Building Regulations mandate performance-tested glass in new construction above defined floor areas. Jebel Ali fabrication clusters source float and coated parent stock for regional distribution.
Kuwait
Post-pandemic infrastructure investment cycles are reopening procurement channels for insulated glass unit suppliers. The country's national building regulator is reviewing thermal performance benchmarks for commercial developments. Local fabrication presence remains limited, creating first-mover advantages for establishing capacity.
Bahrain
Construction recovery is accelerating demand for tempered and laminated products in retail and hospitality fit-out segments. Municipal building codes are tightening disclosure requirements for external glazing performance. Manama and surrounding districts show concentrated project activity.
Qatar
Legacy project completion and new transport infrastructure are sustaining flat glass demand beyond the 2022 cycle. The country's national standards body maintains certification timelines for energy-efficient glazing formulations. Doha industrial zones host downstream processing into windows and facade systems.
GCC Flat Glass Market Key Industry Players
GCC-based producers anchor one tier; international specialists with regional fabrication presence hold another. Buyer consolidation among sovereign wealth-backed developers has compressed supplier margins while demanding guaranteed volume commitments. Three archetypes dominate: integrated float-coating operators, downstream fabrication specialists, and import-dependent distributors. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure giga-project supply contracts.
Within the integrated operator tier, Guardian Glass LLC and Saint-Gobain Middle East exemplify scale-driven positions serving multi-billion-riyal pipelines. Emirates Glass LLC occupies a fabrication-specialist position proximate to Dubai and Riyadh construction clusters. These anchors represent how geographic positioning and process integration determine contract access in a market where procurement desks are consolidating.
| Leading Market Players |
|---|
| Guardian Glass LLC |
| AGC Inc. |
| Emirates Glass LLC |
| Sisecam Group |
| Saint-Gobain Middle East |
| Gulf Glass Industries LLC |
| Obeikan Glass Company |
| Nippon Sheet Glass Co., Ltd. |
| Saudi American Glass Company Ltd. |
| Others |
Cost & Logistics Intelligence
Natural gas feedstock costs anchor GCC float glass economics, flowing from subsidized regional supply through furnace operations into three-tier pricing structures across premium coated, standard tempered, and economy annealed products. Buyer consolidation among Saudi Public Investment Fund project entities compresses margins at the volume tier while coating specialization sustains premium capture.
Pricing Analysis
Volume commitments dominate margin structures; multi-year offtake contracts for Neom and Red Sea developments trade price certainty against compressed unit economics. Price differentiation hinges on SASO energy efficiency certification tier and guaranteed volume scale, with smaller fabricators facing acute pressure from consolidated procurement desks. Pricing pressure stems from buyer consolidation demanding decade-long supply agreements. Mega-project developers show least price sensitivity; aftermarket distributors and smaller retail channels exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from Saudi giga-project procurement desks require qualified suppliers to maintain redundant float and coating capacity across the UAE and Saudi Arabia. Geographic supply concentrates in Saudi Arabia, the UAE, and Egypt for float parent stock, while high-purity silica sand and soda ash draw from Egypt, Turkey, and India. Raw material dependencies span high-purity silica, soda ash, and natural gas feedstock. Single-source vulnerability looms around specialized magnetron sputtering equipment for low-E coating. Distribution runs through Jebel Ali and Riyadh Second Industrial City fabrication clusters serving district-scale developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Float furnace capacity constraints across the GCC prop pricing power toward integrated operators with captive energy supply. Coating line bottlenecks represent the binding capacity limitation sustaining margin structures.
For Market Incumbents: Lock in multi-year supply agreements with Saudi Public Investment Fund project entities before additional float capacity enters service. Deepen backward integration into high-purity silica sand sourcing through offtake partnerships with Egyptian and Turkish suppliers. Magnetron sputtering technician scarcity threatens coating expansion timelines; invest in dedicated training pipelines with regional technical institutes.
For New Entrants and Emerging Players: Launch via local insulated glass unit fabrication in Kuwait and Bahrain, where post-pandemic recovery cycles lack established supply bases. Target Bahrain's retail and hospitality fit-out segment for tempered and laminated products. Pursue partnership routes with Saudi distributors holding existing SASO certification pathways rather than greenfield regulatory submission.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale coating specialists with established SASO compliance in Saudi Arabia's Riyadh corridor. Long-term viability over a five-to-ten-year window rests on positioning for building-integrated photovoltaics convergence. Watch electrochromic glazing adoption rates in Dubai's premium commercial tower pipeline as the inflection signal for dynamic glazing service contract economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Float Furnace Capacity Expansion | Saudi Arabia's Neom and Red Sea pipelines require dedicated regional float supply to meet decade-long procurement commitments. |
| Magnetron Sputtering Coating Investment | Dubai Municipality's green building disclosure mandates force upgrade toward online low-E capability for commercial towers. |
| Backward Integration into Silica Sand | Import dependence on Egyptian and Turkish high-purity silica exposes margins to shipping cost volatility and currency risk. |
| Building-Integrated Photovoltaics Partnership | Transparent solar glazing merges architectural specification channels with energy performance contracting in UAE developments. |
| Specialized Technician Training Pipeline | Scarcity of magnetron sputtering and chemical vapor deposition operators lags regional capacity expansion timelines. |
Research Approach
Multi-period observation of float furnace utilization rates, coating line capacity additions, and giga-project procurement timelines anchored the trend analysis, supplemented by interviews with plant managers at regional float operations, procurement leads at Saudi Public Investment Fund project entities, technical directors at coating specialists, and distribution channel partners in Jebel Ali and Riyadh Second Industrial City. Secondary validation drew from SASO technical regulations, Dubai Municipality green building disclosure requirements, customs and trade data on silica sand and soda ash imports, and SEC filings of publicly traded glass manufacturers. Bottom-up project pipeline quantification triangulated against top-down regional construction spend estimates.
Segment-weighting approaches distributed value across tempered, coated, laminated, and insulated glass unit product categories, with further stratification by construction, automotive, electronics, and furniture end-use applications. Thickness configurations and glazing performance tiers provided additional analytical dimensions throughout the forecast period. CAGRs derived from regression analysis of historical capacity expansion patterns against projected giga-project construction schedules, incorporating natural gas subsidy policy trajectories and evolving national building code synchronization across GCC states.
Natural gas subsidy reduction, SASO certification timeline extension for new coated formulations, and electrochromic glazing technology cost curves are the dominant revision risks to the outlook. Deviation in Saudi giga-project construction pacing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Polishing Powder Market
Glass
3D Glass Market
Glass
Glass Alternative Materials Market
Glass
Insulating Glass Market
Glass
Solar Reflective Glass Market
Glass
North America and Australia Silica Market
Glass
Screen-Printing Glass Market
Glass
Porous Glass Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Soda Feldspar Market
Glass
Glass Recycling Market
Glass
Sapphire Glass Market
Glass
Solar Control Glass Market
Glass
North America Industrial Silica Sand Market
Glass
Laboratory Glassware Market
Glass
Ultra Violet Glass Bottles Market