
 Japan Satellite Imagery Services Market | 2026-2036
Japan Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Satellite Imagery Services Market Insights
A shortage of geospatial data scientists is reorganizing how Japanese satellite imagery firms structure their service delivery. PASCO Corporation leverages its decades of domestic surveying heritage to anchor government contracts for land use mapping. Synspective Inc. specializes in synthetic aperture radar analytics, competing on all-weather imaging capability that optical providers cannot match.
Japan satellite imagery services encompass the acquisition, processing, and analytic distribution of Earth observation data captured by orbiting platforms, with spatial resolutions ranging from sub-meter panchromatic to 30-meter multispectral depending on sensor class and orbital altitude. These services transform raw orbital captures into decision-ready intelligence for infrastructure planning, agricultural yield forecasting, and post-disaster damage assessment. Optical imaging dominates current revenue streams due to mature sensor networks and lower processing overhead, while radar imaging represents the fastest-expanding service type as climate volatility intensifies demand for cloud-penetrating observation. Defense and environmental monitoring end users command premium pricing, whereas agriculture segments face margin compression from standardized commodity offerings.
METI licensing frameworks govern commercial remote sensing operations, while JAXA coordinates public orbital asset allocation and data dissemination protocols that shape market access for private analytics providers. Japan's alignment with ISO 19115 geospatial metadata standards ensures interoperability with international disaster response systems, expanding exportable service potential. Stakeholders must weigh sovereign data localization requirements against the cost advantages of foreign constellation partnerships when scaling analytics infrastructure.
Market Dynamics
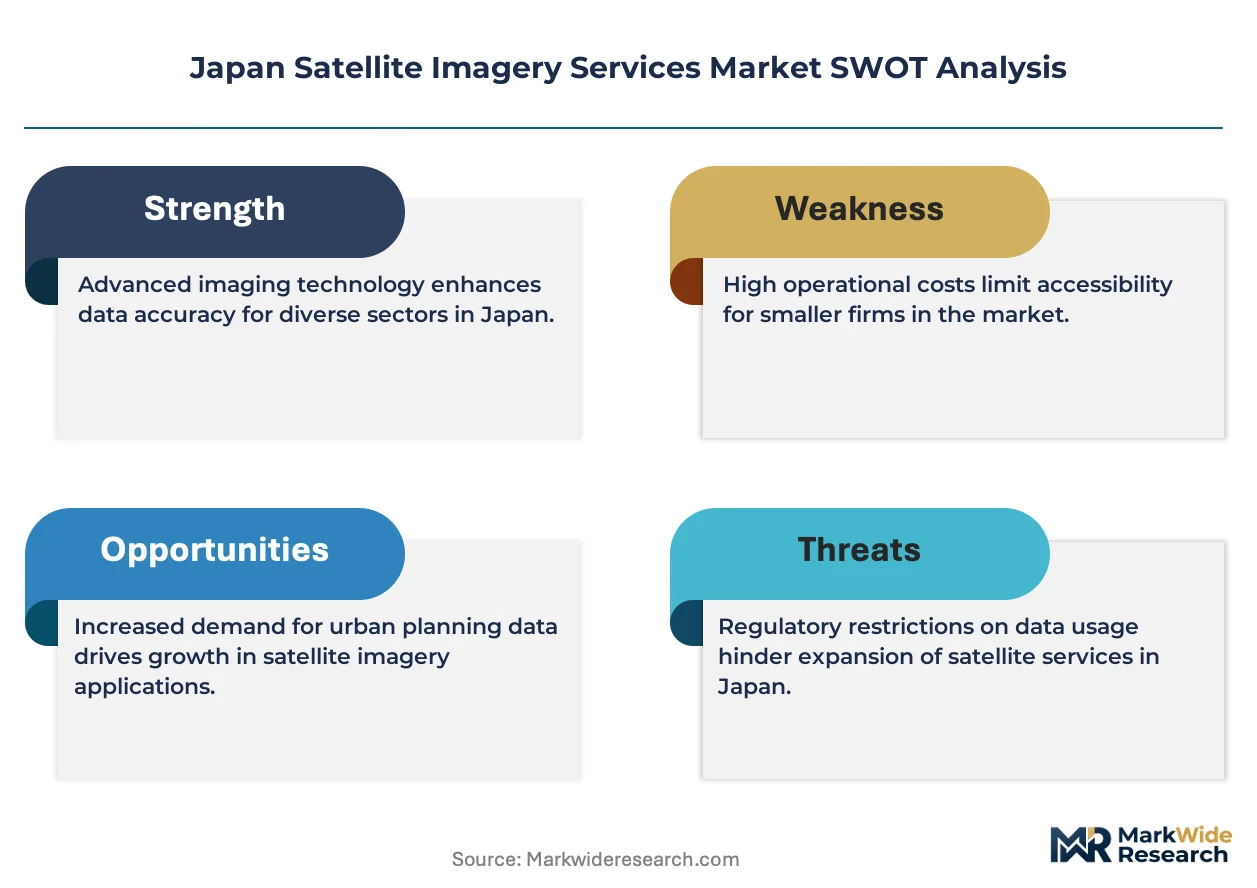
METI's disaster resilience mandates are accelerating government procurement of all-weather imaging capabilities, restructuring competitive positioning between optical and synthetic aperture radar providers across Japan's prefectural procurement frameworks.
Growth Catalysts
- Precision agriculture protocols:Japanese rice and vegetable cooperatives are adopting sub-meter resolution imagery for yield forecasting and irrigation optimization, creating sustained demand for processed agricultural analytics.
- Urban densification monitoring:Tokyo and Osaka prefectural governments fund continuous land use surveillance to enforce zoning compliance and infrastructure planning decisions.
- METI orbital data localization policies:Sovereign data requirements channel government contracts toward domestic processing facilities, reinforcing local analytics provider market access.
Market Restraints
- Geospatial data scientist scarcity:The specialized workforce shortage forces service providers to restructure delivery models and compress margins on complex analytics projects.
- Optical sensor weather dependency:Cloud cover limitations in Japan's maritime climate reduce effective observation windows and delay time-sensitive deliverables for disaster response contracts.
- Foreign constellation partnership restrictions:JAXA coordination protocols and METI licensing frameworks limit rapid scaling through international satellite access agreements.
Strategic Opportunities
- Hokkaido agricultural expansion:Large-scale farming operations in northern Japan remain underpenetrated by precision imagery services relative to Honshu corridor saturation.
- Climate volatility adaptation:Escalating typhoon frequency is expanding addressable demand for rapid post-event damage assessment and reconstruction planning analytics.
- AI-ML fusion with SAR processing:Machine learning integration with synthetic aperture radar data streams enables automated change detection for infrastructure monitoring applications.
Industry Challenges
- Interoperability standardization delays:Fragmented metadata protocols between JAXA public assets and commercial provider systems complicate multi-source analytics integration.
- High-performance computing capex intensity:Sub-meter imagery processing and AI model training require substantial infrastructure investment that constrains mid-tier provider scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Satellite Imagery Services Market |
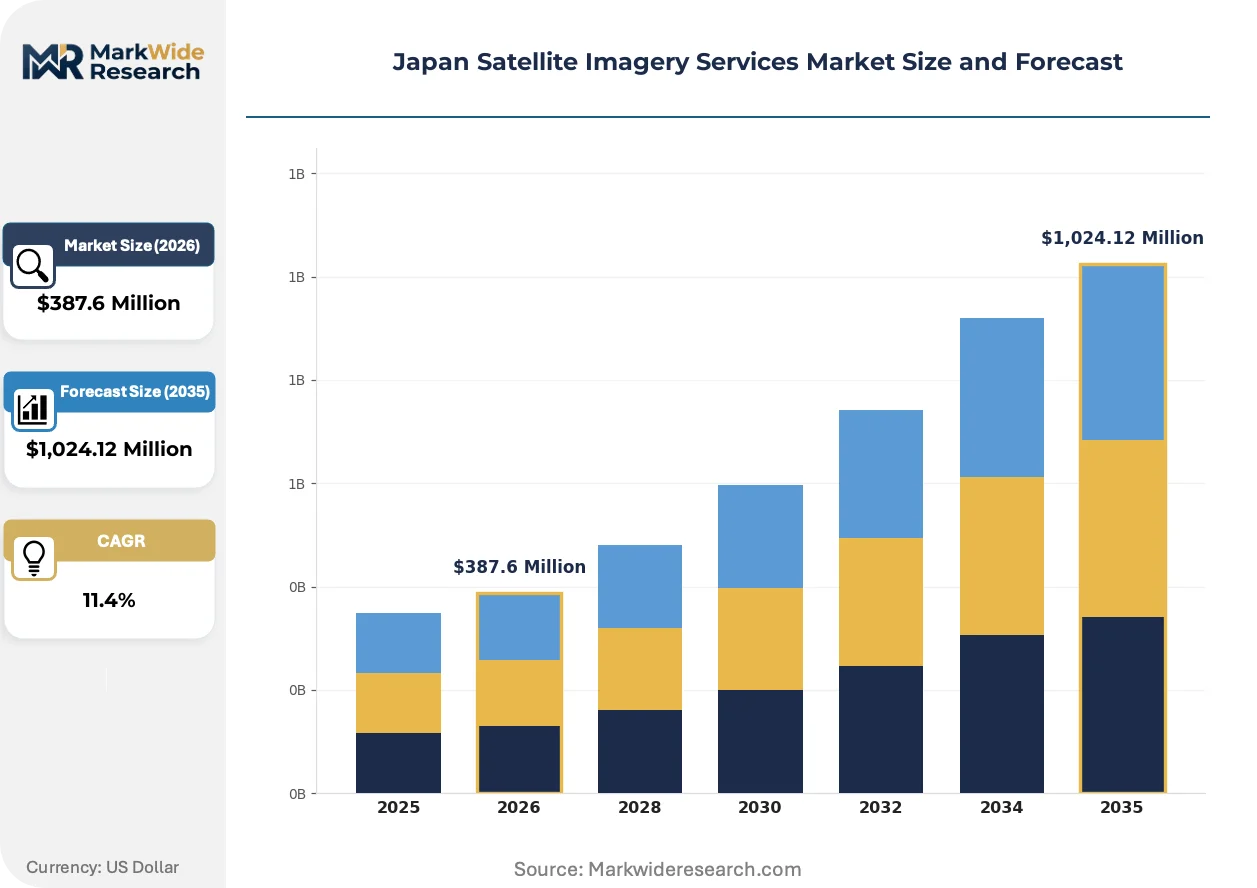
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Optical Imaging, Radar Imaging, Hyperspectral Imaging, LiDAR End User: Agriculture, Environmental Monitoring, Urban Planning, Defense Application: Disaster Management, Land Use Mapping, Climate Study, Natural Resource Management Technology: GIS, Remote Sensing, Image Processing, Data Analytics |
| Companies Covered | Japan Aerospace Exploration Agency (JAXA), PASCO Corporation, Kokusai Kogyo Co., Ltd., Mitsubishi Electric, NTT Data Corporation, Remote Sensing Technology Center of Japan (RESTEC), Synspective Inc., Axelspace Corporation, Japan Space Imaging Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Satellite Imagery Services Market Trends and Innovations
Cloud-penetrating observation technologies are displacing optical dominance in time-critical applications, while automated analytics pipelines compress delivery timelines from raw capture to decision-ready intelligence.
Edge computing architectures for satellite data preprocessing are decomposing traditional ground station bottlenecks. Japanese defense and environmental monitoring agencies are piloting orbital-edge analytics to reduce downlink latency. This compression of the processing chain is decomposing incumbent providers' reliance on centralized processing facilities for competitive differentiation.
METI's updated remote sensing licensing framework tightens operational parameters for commercial orbital data collection. The regulation mandates enhanced geospatial metadata standards aligned with ISO 19115 for international disaster response interoperability. Defense and infrastructure planning segments are adapting procurement specifications to comply with the new certification requirements.
Prefectural governments are consolidating imagery procurement through framework agreements rather than project-specific tenders. Municipal buyers in the Tokyo-Osaka corridor now access pre-negotiated service catalogs, displacing direct vendor relationships. This aggregation pattern is most visible in urban densification monitoring contracts where standardization reduces transaction costs.
Japan Satellite Imagery Services Market Segmentation
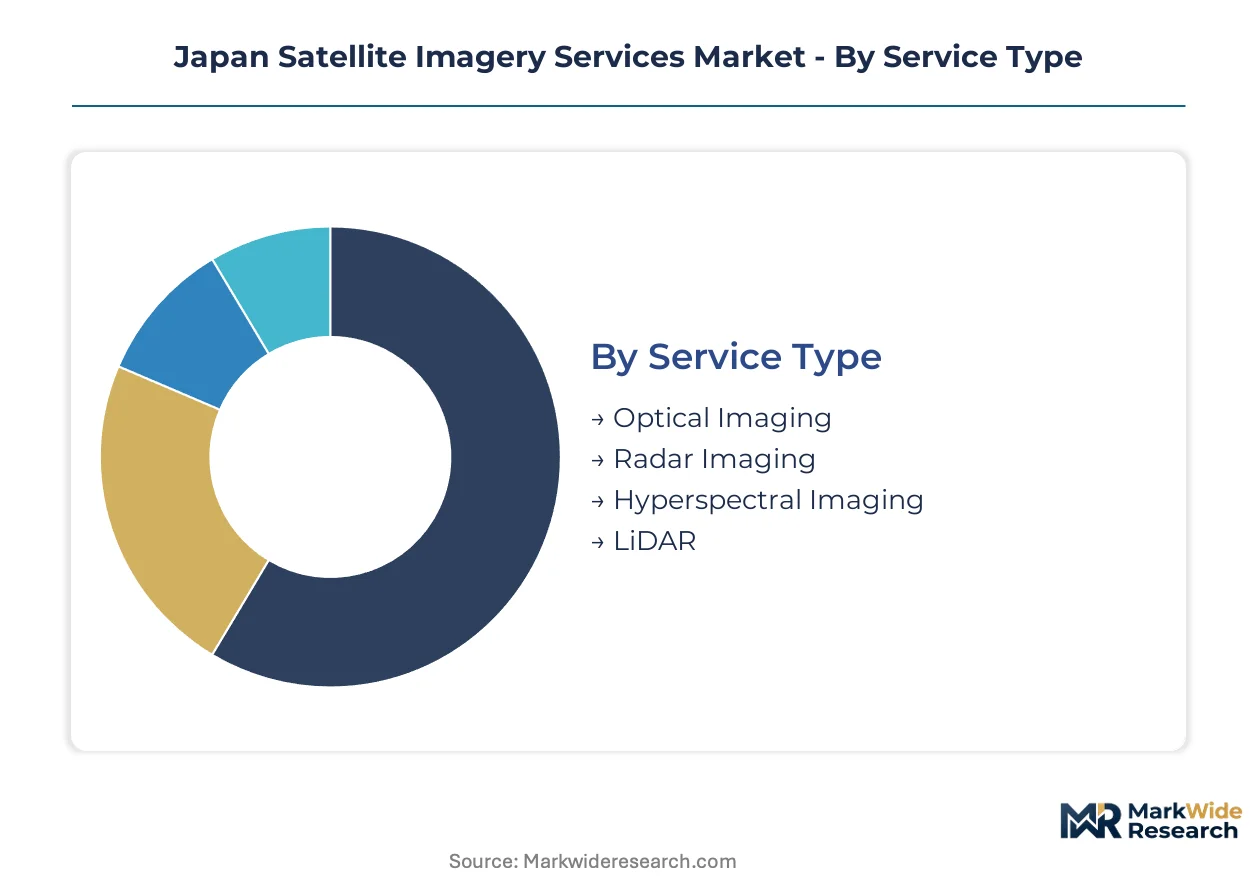
Service differentiation across imaging modalities, end-use verticals, and processing technologies determines competitive positioning in Japan's satellite imagery market. Substitution pressures from alternative data sources and in-house analytics capabilities reshape how providers structure their offerings across each dimension.
Service Type:
Optical imaging faces intensifying substitution pressure from synthetic aperture radar as climate volatility and METI disaster resilience mandates elevate all-weather observation requirements.
- Optical Imaging:Panchromatic and multispectral capture systems deliver sub-meter to 30-meter resolution depending on orbital altitude. Rice and vegetable cooperatives in Honshu drive procurement for yield forecasting, though cloud cover limitations in Japan's maritime climate constrain effective observation windows.
- Radar Imaging:Synthetic aperture radar penetrates cloud cover and operates independent of solar illumination. Prefectural governments across the Tokyo-Osaka corridor fund SAR-based urban densification monitoring as JAXA coordination protocols expand domestic constellation access.
- Hyperspectral Imaging:Contiguous narrow-band spectral capture enables material identification for agricultural stress detection and mineral exploration applications.
- LiDAR:Active laser ranging generates high-precision elevation models for infrastructure planning and flood risk assessment in dense metropolitan zones.
Optical imaging retains volume leadership; radar imaging holds the steepest expansion curve.
End User:
Cost tier stratification separates premium-priced defense and environmental monitoring contracts from margin-compressed agricultural segments facing commodity pricing pressure.
- Agriculture:Precision agriculture protocols among Japanese rice and vegetable cooperatives create sustained demand for processed yield analytics. Standardized service offerings compress margins as cooperatives consolidate procurement through prefectural framework agreements.
- Environmental Monitoring:Climate volatility adaptation expands addressable demand for ecosystem surveillance and carbon sequestration verification services across archipelago waters.
- Urban Planning:Tokyo and Osaka prefectural governments fund continuous land use surveillance to enforce zoning compliance and infrastructure planning decisions.
- Defense:Sovereign data localization requirements channel sensitive procurement toward domestic processing facilities with enhanced security certifications.
Environmental monitoring commands premium pricing; agriculture segments face the sharpest margin compression.
Application:
Volume concentration clusters around time-critical use cases where satellite observation delivers decisive advantages over aerial or ground-based alternatives.
- Disaster Management:Rapid post-event damage assessment and reconstruction planning analytics. Escalating typhoon frequency expands recurring procurement cycles for all-weather imaging capabilities.
- Land Use Mapping:Continuous surveillance for zoning enforcement and property taxation verification. PASCO Corporation anchors government contracts leveraging decades of domestic surveying heritage.
- Climate Study:Long-term atmospheric and oceanic pattern analysis supporting national adaptation policy formulation.
- Natural Resource Management:Forest inventory, fisheries monitoring, and marine protected area surveillance across Japan's extensive territorial waters.
Disaster management absorbs the largest procurement volumes; climate study applications are climbing the fastest.
Technology:
Maturity gradients separate established geospatial infrastructure from emerging AI-ML fusion capabilities requiring substantial high-performance computing investment.
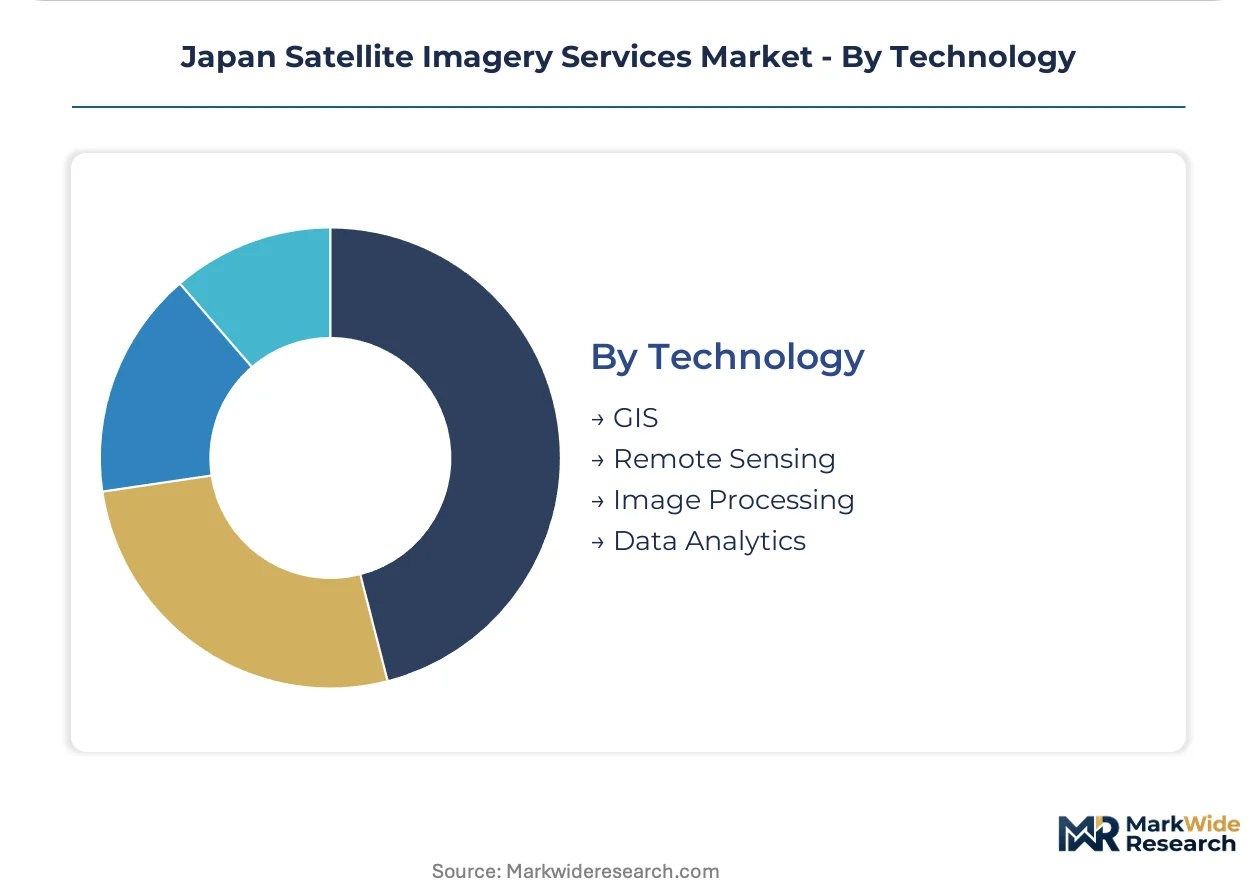
- GIS:Spatial data management and visualization platforms form the foundational layer for integrated analytics pipelines across all end-use verticals.
- Remote Sensing:Sensor calibration, atmospheric correction, and orthorectification workflows transform raw orbital captures into analysis-ready datasets.
- Image Processing:Edge computing architectures decompress traditional ground station bottlenecks. Defense agencies pilot orbital-edge preprocessing to reduce downlink latency.
- Data Analytics:Machine learning integration with SAR data streams enables automated change detection for infrastructure monitoring applications.
GIS and remote sensing retain infrastructure dominance; data analytics capabilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Honshu's Tokyo-Osaka corridor while Hokkaido agricultural regions absorb margin pressure from standardized service offerings. Prefectural procurement frameworks reshape competitive positioning across Japan's archipelago.
Kanto/Tokyo
Urban densification monitoring and defense procurement drive premium-tier demand. METI's disaster resilience mandates channel government contracts toward domestic processing facilities with enhanced security certifications. The Tokyo metropolitan government funds continuous land use surveillance for zoning enforcement.
Kansai/Osaka
Infrastructure planning and port logistics surveillance absorb substantial imagery procurement volumes. JAXA coordination protocols expand access to domestic constellation assets for regional analytics providers. Osaka prefectural authorities consolidate procurement through framework agreements reducing transaction costs.
Chubu/Nagoya
Manufacturing supply chain monitoring and automotive facility planning generate specialized demand. METI licensing frameworks govern commercial remote sensing operations shaping provider market access. Nagoya's industrial corridor attracts precision agriculture protocols for surrounding vegetable cooperatives.
Hokkaido
Large-scale farming operations remain underpenetrated by precision imagery services relative to Honshu saturation. Sovereign data localization requirements channel agricultural analytics toward domestic processing facilities. Sapporo-based cooperatives drive emerging demand for yield forecasting and irrigation optimization.
Kyushu
Post-disaster reconstruction planning and marine protected area surveillance expand addressable demand. Escalating typhoon frequency accelerates procurement cycles for all-weather synthetic aperture radar capabilities. Fukuoka prefectural government pilots automated change detection for infrastructure monitoring.
Japan Satellite Imagery Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's satellite imagery services market. The vendor base organizes around heritage surveying conglomerates, radar analytics specialists, and emerging constellation operators. Three strategic archetypes dominate: legacy geospatial firms leveraging decades of government relationships, SAR-native challengers competing on all-weather capability, and upstream satellite manufacturers integrating downstream. M&A activity concentrates on AI-ML analytics capabilities while strategic partnerships address foreign constellation access restrictions.
Within the heritage surveying tier, PASCO Corporation and Kokusai Kogyo Co., Ltd. exemplify established market presence. Among radar-native specialists, Synspective Inc. occupies a position representing the all-weather imaging segment. These three anchors illustrate how competitive positioning splits between optical legacy and SAR innovation vectors.
| Leading Market Players |
|---|
| Japan Aerospace Exploration Agency (JAXA) |
| PASCO Corporation |
| Kokusai Kogyo Co., Ltd. |
| Mitsubishi Electric |
| NTT Data Corporation |
| Remote Sensing Technology Center of Japan (RESTEC) |
| Synspective Inc. |
| Axelspace Corporation |
| Japan Space Imaging Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Framework agreements locking in multi-year procurement cycles anchor both supply access and price predictability for Japanese prefectural governments, insulating domestic providers from spot-market volatility while compressing margins on standardized service tiers.
Pricing Analysis
Configured-to-order pricing for defense and environmental monitoring contracts commands substantial premiums over standardized agricultural analytics. Three-tier pricing structure across premium, standard, and economy levels stratifies by data resolution, processing complexity, and security certification tier. Cost compression in agricultural segments is intensifying because cooperatives consolidate procurement through prefectural framework agreements. Agricultural buyers exhibit the highest price sensitivity; defense agencies demonstrate the lowest, prioritizing sovereign data localization and rapid turnaround over unit economics.
Supply Chain Analysis
Strategic stockpiling of orbital capacity reservations dominates over just-in-time procurement, given the fixed launch schedules and constellation deployment timelines that constrain rapid supply adjustment. Raw capture hardware concentrates in the United States, France, and Japan, while specialized SAR processing components draw from South Korea and Taiwan. Ground station infrastructure and high-performance computing clusters rest on semiconductor supply chains vulnerable to single-source bottlenecks. Distribution runs through JAXA-coordinated public asset channels and commercial downlink partnerships with domestic telecommunications carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's satellite imagery services market sits in early-cycle expansion, with METI's disaster resilience mandates accelerating procurement velocity beyond historical infrastructure planning baselines.
For Market Incumbents: Fortify government contract anchoring by deepening vertical integration into SAR analytics capabilities, countering Synspective's all-weather imaging threat. Secure ISO 19115 certification ahead of METI's updated licensing deadlines to lock in procurement eligibility for defense and environmental monitoring segments. For New Entrants and Emerging Players: Lead with Hokkaido's underpenetrated large-scale farming operations, where precision agriculture protocols remain nascent relative to Honshu corridor saturation. Deploy AI-ML fusion capabilities as a differentiated go-to-market angle for automated change detection in infrastructure monitoring applications. For Investors and Strategic Acquirers: The market sits at a consolidation-prone phase that favors analytics-specialist acquisition targets over hardware-heavy constellation operators. Long-term viability hinges on machine learning integration depth and domestic processing facility ownership. Watch JAXA coordination protocol expansions as the critical signal for foreign constellation partnership accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| AI-ML Analytics Acquisition | Machine learning integration with SAR data streams enables automated infrastructure monitoring differentiation. |
| Domestic Processing Facility Buildout | Sovereign data localization requirements channel METI contracts toward Japan-based analytics infrastructure. |
| Prefectural Framework Agreement Entry | Tokyo-Osaka corridor consolidation patterns favor providers with pre-negotiated service catalog access. |
| SAR Constellation Partnership | All-weather imaging capability addresses optical sensor limitations in Japan's cloud-prone maritime climate. |
| Edge Computing Architecture Deployment | Orbital-edge preprocessing reduces downlink latency for defense and disaster response time-critical applications. |
Research Methodology
A spread of perspectives from JAXA program officers, prefectural procurement managers, geospatial data scientists, and agricultural cooperative directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against METI policy documents, JAXA orbital asset allocation records, and prefectural government procurement databases. Bottom-up service provider revenue triangulation against top-down addressable demand estimation anchored the market sizing framework.
Segmentation dimensions modeled span imaging modality, end-use vertical, application use case, and processing technology tier across the projection horizon. CAGRs derive from fitted growth curves incorporating adoption rate trajectories for precision agriculture protocols and disaster resilience procurement cycles. Forecast inputs include SAR constellation deployment schedules and METI licensing framework implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained government funding continuity and stable JAXA coordination protocols would require recalibration. Forecasts reflect documented assumptions regarding climate volatility frequency and agricultural cooperative consolidation patterns. Revision becomes warranted when foreign constellation partnership restrictions ease or domestic geospatial workforce scarcity crosses critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Internet Market
Satellite
Communication Satellite Launch Services Market
Satellite
Satellite Link Emulator Market
Satellite
Satellite Connectivity Market
Satellite
China Satellite Imagery Services Market
Satellite
Russia Satellite Communications Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Europe Satellite IoT Market
Satellite
Europe Small Satellite Market
Satellite
North America Remote Sensing Services Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
UK Satellite Imagery Services Market
Satellite
Spain Satellite-Based Earth Observation Market