
 Satellite Gateway Market | 2026-2036
Satellite Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Gateway Market Analytics
Defense agencies are reorganizing satellite gateway procurement priorities, shifting from legacy GEO-dependent architectures toward multi-orbit, software-defined ground systems. L3Harris Technologies leverages its classified waveform portfolio to anchor military gateway contracts across NATO-aligned programs. Viasat competes through vertical integration into modem and antenna subsystems, while Hughes Network Systems sustains dominance in consumer broadband gateways through manufacturing scale and North American distribution density.
A satellite gateway functions as the terrestrial interface between satellite networks and ground-based infrastructure, typically incorporating RF chains operating in Ku, Ka, or Q/V bands with baseband processing units that modulate, demodulate, encrypt, and route traffic. Its primary purpose is to aggregate and distribute data, voice, and video services between space segments and end-user terminals across defense, maritime, aviation, and terrestrial broadband applications. Fixed satellite gateway installations retain the largest installed base due to decades of GEO anchor tenancy, though LEO technology segments are capturing the fastest growth as constellation operators demand phased-array ground entry points with beam-hopping agility. Hybrid installations are emerging as a margin-rich category, blending on-premises security with cloud-based orchestration to serve dual-use government-commercial operators.
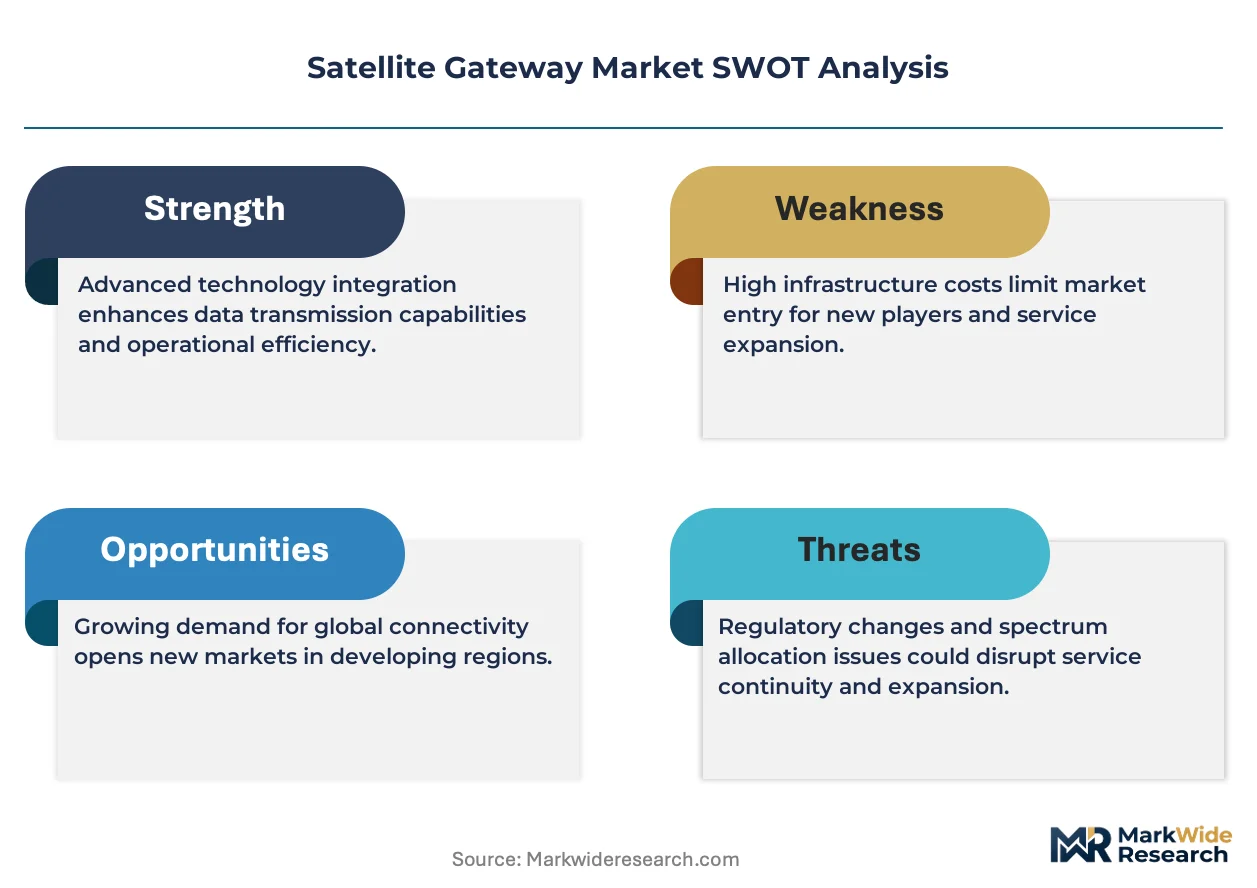
The U.S. Space Force, FCC, and EU Space Programme Agency collectively shape gateway certification, spectrum allocation, and cybersecurity hardening requirements that vendors must satisfy for market access. FCC Part 25 licensing rules constrain earth station coordination, while the EU's IRIS² constellation program imposes European sovereignty standards on gateway procurement. Stakeholders must monitor evolving open architecture mandates and frequency reallocation proceedings that will determine which ground segment suppliers retain incumbent positions versus new entrants.
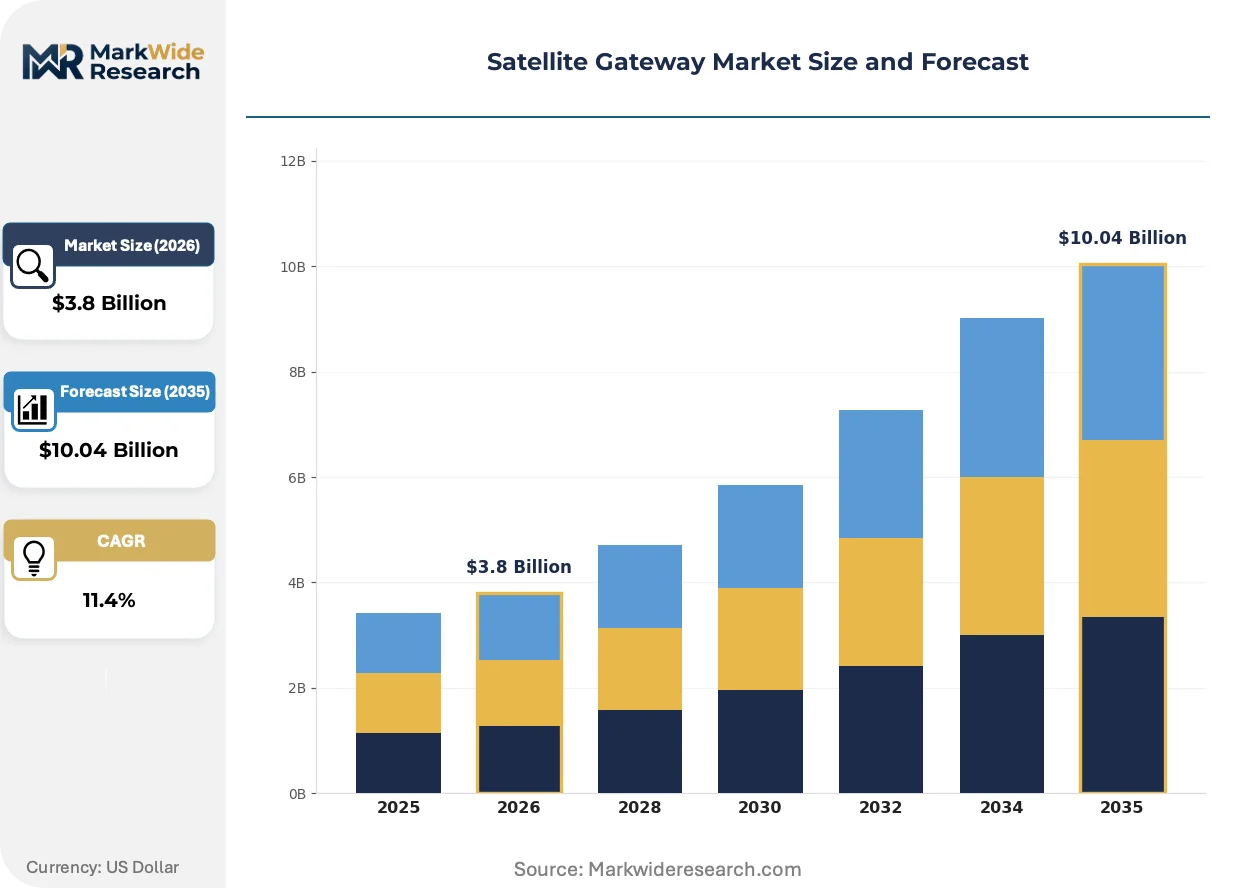
Market Dynamics
LEO constellation operators are compressing gateway refresh cycles from ten-year GEO horizons to three-year hardware cycles, forcing incumbents to abandon proprietary architectures for modular, software-defined ground systems that interoperate across multiple orbital regimes.
Growth Catalysts
- Open Architecture Mandates:The U.S. Space Force's Enterprise Ground Services framework compels vendors to adopt interoperable standards, dismantling vendor lock-in and accelerating procurement velocity for multi-orbit gateways.
- Defense Modernization:NATO-aligned militaries are replacing stovepiped tactical terminals with unified gateway hubs that aggregate classified and commercial satellite feeds for expeditionary command posts.
- Phased-Array Ground Entry:Electronically steerable antenna terminals are miniaturizing RF front-ends while enabling beam-hopping agility that mechanical dishes cannot match, attracting maritime and aviation integrators.
Market Restraints
- Gallium Nitride Supply Concentration:High-power amplifier substrates depend on a narrow supplier base concentrated in East Asian foundries, exposing gateway manufacturers to input volatility and export control friction.
- Spectrum Coordination Costs:FCC Part 25 licensing timelines for new earth station deployments routinely extend eighteen to twenty-four months, delaying revenue recognition for gateway operators seeking Ka-band expansion.
- Optical Ground Station Substitution:Free-space laser terminals for LEO downlinks threaten to bypass traditional RF gateways entirely for high-throughput data relay, compressing addressable market scope for microwave-dependent vendors.
Strategic Opportunities
- Hybrid Cloud Orchestration:Government-commercial dual-use operators are blending on-premises encryption with AWS Ground Station and Azure Orbital for burst capacity, creating margin-rich managed service contracts.
- EU IRIS² Sovereignty Procurement:The European Union's secure connectivity constellation mandates European-owned gateway infrastructure, opening dedicated tender streams for continental system integrators excluded from U.S. classified programs.
- Aviation IFC Retrofit Cycles:Narrow-body fleet operators are ripping out legacy Ku-band radomes for flat-panel Ka-band terminals, demanding compact gateway hubs at regional hub airports with constrained real estate.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave circuit design expertise concentrates among retiring defense-sector veterans, forcing gateway manufacturers to retrain digital signal processing specialists for analog front-end work.
- Legacy System Integration Friction:Software-defined gateways must interoperate with decades-old GEO hub equipment through protocol translation layers, multiplying test matrices and field deployment risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Gateway Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Satellite Gateway, Mobile Satellite Gateway, Hybrid Satellite Gateway, Multi-band Satellite Gateway Technology: VSAT, MEO, GEO, LEO End User: Government, Military, Commercial, Telecommunications Installation: On-premises, Cloud-based, Hybrid, Remote |
| Companies Covered | General Dynamics Corporation, L3Harris Technologies, RTX, Lockheed Martin Corporation, Airbus, Viasat, SES S.A., Intelsat S.A., Hughes Network Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Gateway Market Evolving Landscape
Ground segment architecture is fragmenting from monolithic hub-and-spoke models toward distributed edge processing nodes that collapse latency for time-sensitive defense and financial applications.
Solid-state power amplifiers based on gallium nitride are miniaturizing RF chain footprints while doubling power efficiency over traveling-wave tube alternatives. Maritime integrators are adopting these compact subsystems for stabilized platforms where volume and thermal budgets are severely constrained. This compression is enabling gateway deployment on vessels and aircraft that previously could not accommodate mechanical steerable dishes.
The FCC's expanded 17 GHz satellite allocation proceedings are reshaping spectrum strategy for next-generation gateways, compelling manufacturers to design multi-band RF chains that can be reconfigured through software rather than hardware swaps. Equipment vendors are pre-certifying modular front-ends across extended frequency ranges to avoid redesign cycles when rulings finalize. Ka-band terminal manufacturers face the steepest compliance burden as they hold the largest installed base requiring retrofit.
Defense procurement officers are unbundling gateway hardware from long-term service contracts, forcing vendors to compete on capital cost while separately pricing sustainment through performance-based logistics agreements. This bifurcation is compressing upfront margins and transferring operational risk to suppliers who must guarantee availability metrics. The shift is most pronounced in U.S. Space Force and Space Development Agency programs, where fixed-price development contracts now dominate previously cost-plus arrangements.
Satellite Gateway Market Segmentation
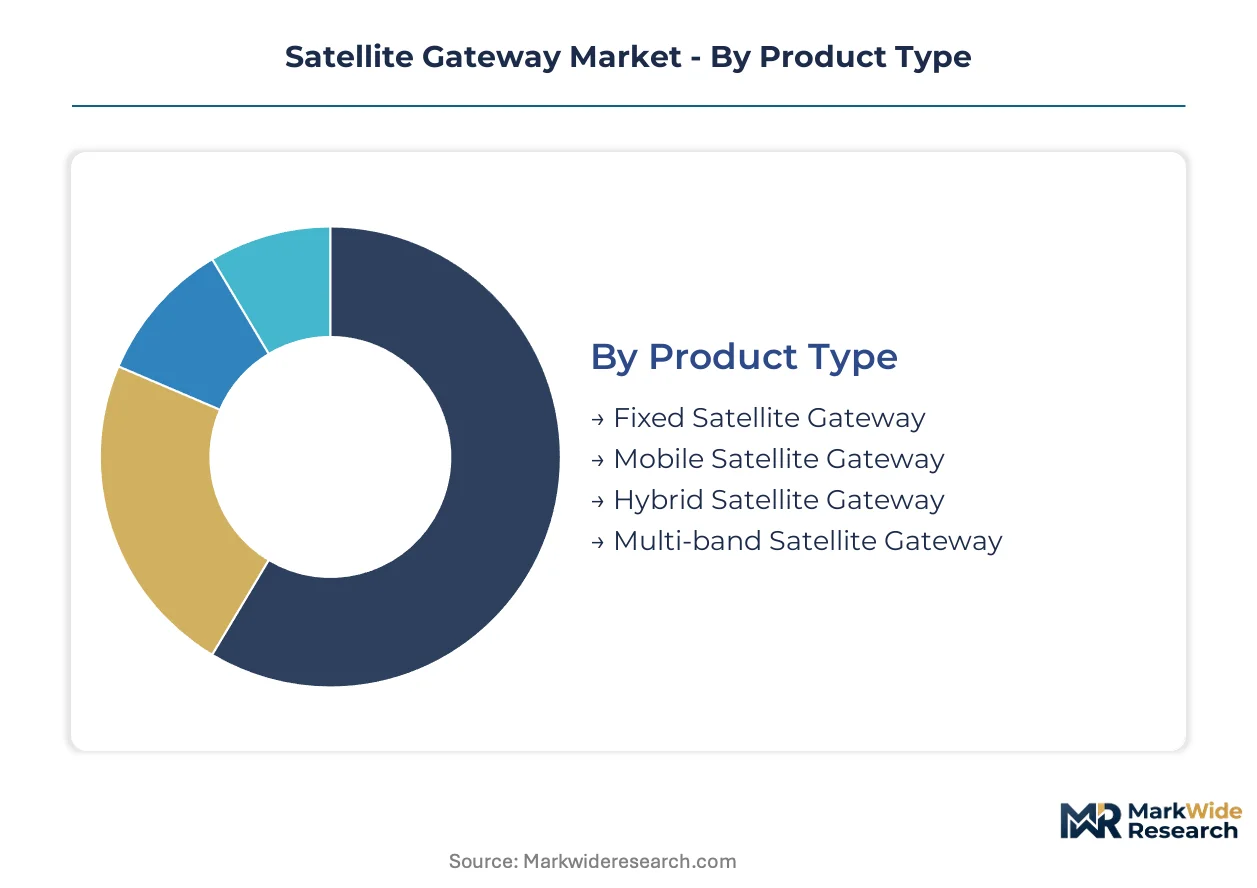
Gateway segmentation reveals divergent investment priorities across defense, commercial broadband, and dual-use operators. Product architecture, orbital technology, and deployment models each create distinct procurement channels with separate certification requirements and margin structures.
Product Type:
Fixed gateways dominate domestic procurement through U.S. Space Force and NATO anchor tenancy programs, while mobile and hybrid variants concentrate in export-led defense modernization and maritime aviation retrofit markets.
- Fixed Satellite Gateway:Permanent installations anchor GEO hub networks with high-gain parabolic antennas and redundant RF chains. U.S. federal communications modernization concentrates procurement at CONUS military bases and downrange relay sites, though mechanical steering limits beam agility.
- Hybrid Satellite Gateway:Blends on-premises encryption hardware with cloud-orchestrated baseband processing. Dual-use operators in Germany and Japan are adopting these architectures for burst capacity scaling without classified data leaving sovereign territory.
- Mobile Satellite Gateway:Deployable terminals serve expeditionary command posts with rapid-reaction transit cases. Demand concentrates in NATO rapid deployment corps and humanitarian relief agencies.
- Multi-band Satellite Gateway:Reconfigurable RF front-ends span Ku through Q/V bands via software-defined waveforms. Satellite operators in the United Kingdom and Australia are procuring these for constellation interoperability.
Fixed installations hold the largest share; momentum sits with hybrid architectures.
Technology:
Technology selection determines gateway refresh cycles, with legacy GEO platforms requiring decade-long capital planning while LEO infrastructure demands compressed three-year hardware turnover.
- GEO:Geostationary systems anchor decades of installed base with predictable link budgets and mature ground equipment supply chains. U.S. rural broadband subsidies sustain procurement despite latency constraints for real-time applications.
- LEO:Low-Earth-orbit gateways require phased-array terminals with beam-hopping agility and Doppler compensation. Commercial constellation operators in Canada and France are driving the steepest expansion trajectory for compact ground entry points.
- VSAT:Very small aperture terminals serve enterprise networks and consumer broadband with standardized modem chipsets. Scale manufacturing in Mexico and Vietnam supports cost compression for emerging market distributors.
- MEO:Medium-Earth-orbit systems split latency and coverage tradeoffs for maritime and aeronautical mobility. Brazilian and Indonesian fleet operators are deploying these for oceanic corridor coverage.
GEO retains incumbent revenue concentration; LEO is climbing the fastest.
End User:
End-user segmentation separates classified procurement with sovereign security requirements from commercial volume markets governed by service-level economics.
- Government:Civilian agencies require FIPS 140-2 encryption and domestic supply chain certification. U.S. federal, German federal, and Japanese national programs each mandate distinct hardening standards.
- Military:Tactical gateways aggregate multiple satellite feeds for expeditionary command posts. NATO-aligned procurement in Poland, Norway, and Italy is unifying previously stovepiped terminal architectures.
- Commercial:Enterprise broadband and maritime connectivity drive volume demand. Australian mining camps and Chilean fishing fleets represent concentrated regional adoption.
- Telecommunications:Mobile backhaul and rural cellular extension create gateway demand with strict availability metrics. Operators in Nigeria and the Philippines are deploying these for last-mile coverage gaps.
Military applications command premium pricing; commercial telecommunications delivers volume scale.
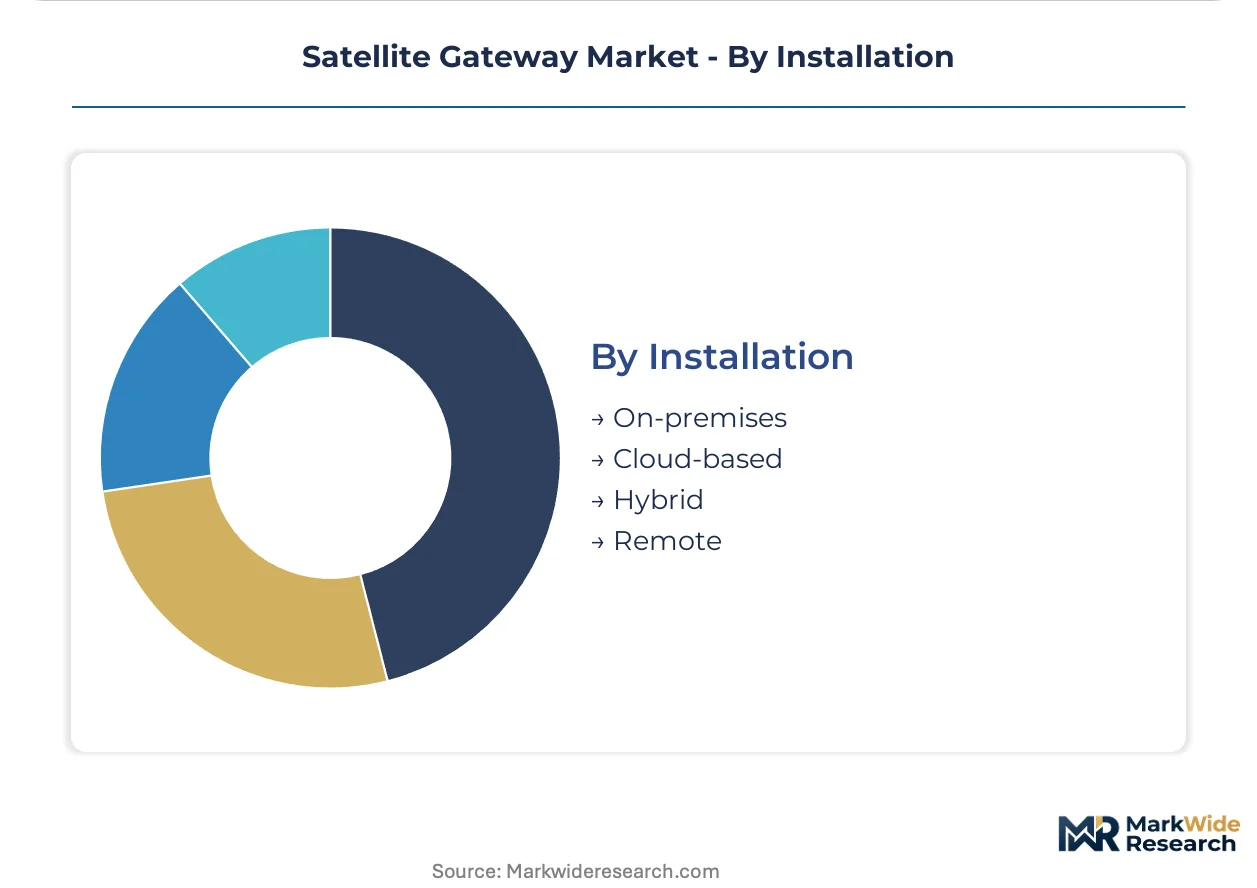
Installation:
Deployment models fragment between sovereignty-conscious on-premises hardware and cost-optimized cloud absorption of baseband processing.
- On-premises:Complete hardware ownership satisfies classified data handling and low-latency requirements. U.S. intelligence community and French defense procurement mandate air-gapped installations.
- Cloud-based:AWS Ground Station and Azure Orbital absorb capital intensity for variable workloads. Research institutions in Switzerland and academic consortia in the Netherlands are adopting these for episodic satellite tasking.
- Hybrid:Encryption appliances remain local while modulation processing shifts to sovereign cloud regions. Canadian and Australian government-commercial operators favor this model for dual-use flexibility.
- Remote:Containerized or trailer-mounted deployments serve disaster response and frontier extraction sites. Humanitarian agencies in Kenya and energy operators in Kazakhstan utilize these for rapid field establishment.
On-premises retains security-sensitive share; hybrid deployments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Coast gateway corridor underwrites United States demand concentration, with terrestrial fiber backhaul linking Vandenberg Space Force Base to Seattle-Tacoma aerospace clusters.
United States
U.S. Space Force Enterprise Ground Services contracts drive procurement at Peterson Space Force Base and Schriever Space Force Base. FCC Part 25 licensing timelines constrain Ka-band earth station deployments. Colorado Springs anchors military gateway integration, where L3Harris Technologies maintains classified waveform development facilities.
Germany
Bundeswehr satellite communications modernization funds dual-use gateway hubs for expeditionary NATO command posts. EU IRIS² sovereignty mandates require European-owned ground infrastructure for secure connectivity constellations. Bavaria concentrates system integration expertise, with Munich-area contractors developing hybrid cloud-orchestrated encryption appliances.
France
Direction Générale de l'Armement procures mobile gateway terminals for African Sahel expeditionary operations. CNES and EU Space Programme Agency coordinate spectrum allocation for Q/V-band experimental gateways. Toulouse hosts satellite manufacturing clusters where Thales Alenia Space integrates ground segment subsystems for export programs.
United Kingdom
UK Space Agency funding accelerates LEO gateway deployment for OneWeb constellation anchor tenancy. Ofcom regulates earth station licensing with cybersecurity hardening requirements for critical national infrastructure. Harwell Space Cluster hosts phased-array terminal developers serving maritime and aviation integrators.
Japan
Japan Self-Defense Forces unify stovepiped tactical terminals into multi-orbit gateway hubs for Indo-Pacific expeditionary operations. METI subsidizes domestic GaN amplifier foundry capacity to reduce East Asian supply concentration exposure. Tsukuba Space Center coordinates QZSS augmentation gateway integration with commercial LEO operators.
Satellite Gateway Market Competitive Landscape
Concentration sits with defense-anchored conglomerates holding classified waveform portfolios and long-term service contracts. The vendor base spans three tiers: prime contractors with satellite manufacturing heritage, specialized ground segment integrators, and modem-focused subsystem suppliers. Strategic moves center on unbundling hardware from sustainment contracts and absorbing cloud orchestration capabilities through partnership structures rather than captive development.
Within the defense prime tier, General Dynamics Corporation and Lockheed Martin Corporation represent archetypes of classified program incumbency, while L3Harris Technologies occupies a position bridging military waveform expertise with NATO export eligibility. These entities exemplify how security clearance barriers and proprietary protocol libraries create defensive moats around federal procurement channels.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| L3Harris Technologies |
| RTX |
| Lockheed Martin Corporation |
| Airbus |
| Viasat |
| SES S.A. |
| Intelsat S.A. |
| Hughes Network Systems |
| Others |
Value Network & Pricing Analysis
Eighteen-month FCC Part 25 licensing timelines for Ka-band earth station deployments concentrate pricing power with incumbent gateway operators holding grandfathered spectrum rights, while compressing margins for new entrants facing extended revenue recognition delays and carrying costs for pre-certified modular RF front-ends.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates classified military gateways with FIPS 140-2 encryption from dual-use hybrid installations and commercial broadband VSAT terminals. Price differentiation rests on certification grade and volume scale, with defense primes commanding substantial premiums for proprietary waveform libraries while commercial operators face intensifying cost compression from Mexican and Vietnamese manufacturing scale. Commercial telecommunications buyers exhibit highest price sensitivity, whereas intelligence community procurement prioritizes security hardening over unit economics.
Supply Chain Analysis
Inbound logistics costs through East Asian semiconductor corridors expose gateway manufacturers to container availability volatility on transpacific trade lanes serving GaN foundry outputs. Manufacturing concentrates in the United States, Germany, and Japan for classified programs, while commercial subsystem assembly feeds from Mexican and Vietnamese facilities. Raw material dependencies span gallium nitride substrates, phased-array antenna elements, and software-defined baseband processors. Single-source vulnerability in East Asian high-power amplifier foundries threatens production continuity. Distribution runs through defense prime integrators for military procurement and direct OEM relationships for commercial constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical ground station substitution for LEO downlinks threatens to bypass RF gateway infrastructure entirely, forcing microwave-dependent incumbents to defend their terrestrial interface position against free-space laser terminal displacement.
For Market Incumbents: Shield classified waveform portfolios through accelerated NATO export program capture, while securing captive supply of GaN amplifier substrates via METI-subsidized Japanese foundry partnerships to reduce East Asian concentration exposure. Prioritize hybrid cloud orchestration service contracts that blend on-premises encryption with sovereign cloud absorption, creating switching costs that optical alternatives cannot easily replicate.
For New Entrants and Emerging Players: Managed service gaps in EU IRIS² sovereignty procurement open dedicated tender streams for continental system integrators excluded from U.S. classified programs. Target Bavaria-based hybrid encryption appliance development and Australian government-commercial dual-use operators favoring sovereign cloud flexibility. Pursue performance-based logistics agreements that unbundle hardware from sustainment, mirroring U.S. Space Force fixed-price contract structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense prime conglomerates divesting non-core ground segment assets amid procurement bifurcation pressures. Long-term viability centers on software-defined architectures interoperable across multi-orbit regimes rather than GEO-legacy hardware. Monitor FCC 17 GHz allocation proceedings as inflection indicator for multi-band RF chain demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Supply Diversification | Reduces East Asian foundry concentration through Japanese and domestic substrate sourcing. |
| Hybrid Cloud Orchestration | Captures margin-rich managed service contracts with Canadian and Australian dual-use operators. |
| EU IRIS² Gateway Certification | Unlocks European sovereignty procurement streams closed to non-continental suppliers. |
| Phased-Array Terminal Miniaturization | Enables maritime and aviation retrofit cycles demanding compact stabilized platforms. |
| Open Architecture Compliance | Satisfies U.S. Space Force Enterprise Ground Services mandates dismantling vendor lock-in. |
Research Methodology
Initial hypotheses were tested against primary input from satellite gateway procurement officers at defense primes, RF engineering directors at phased-array terminal developers, and cloud orchestration specialists at AWS Ground Station and Azure Orbital, then refined through secondary validation across FCC Part 25 licensing databases, U.S. Space Force contract award announcements, and EU Space Programme Agency IRIS² tender documentation. Bottom-up equipment shipment estimates triangulated against top-down addressable market sizing derived from constellation operator capex disclosures.
Variance decomposition across product architecture, orbital technology, and installation model dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by defense modernization spend patterns and commercial broadband subscriber expansion. Forecast inputs incorporated LEO constellation deployment schedules, GaN substrate capacity expansion timelines, and open architecture mandate compliance deadlines.
Underlying assumptions cover sustained U.S. federal communications modernization funding, stable East Asian semiconductor export licensing, and progressive FCC spectrum reallocation proceedings, with deviation risk concentrated in optical ground station technology maturation and EU sovereignty procurement timeline delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
All-Electric Propulsion Satellites Market
Satellite
North America Satellite Bus Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Cubesat Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
China Satellite Imagery Services Market
Satellite
High-Throughput Satellite Market
Satellite
Satellite Backhaul Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
Small Satellite Market