
 Germany Satellite-Based Earth Observation Market | 2026-2036
Germany Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Satellite-Based Earth Observation Market Insights
The gap between premium analytics-grade data and raw commodity imagery is shifting procurement patterns across German Earth observation buyers. Airbus SE leverages sovereign manufacturing capacity in Bremen and Friedrichshafen to anchor defense and institutional contracts. OHB SE competes through specialized small-satellite platforms optimized for rapid revisit cycles. Planet Labs PBC extends daily coverage models into German agricultural compliance monitoring, occupying a distinct volume tier below classified missions.
Satellite-based Earth observation denotes the acquisition of geospatial data through orbital platforms carrying optical, radar, or hyperspectral sensors, typically operating at altitudes between 400 and 800 kilometers with spatial resolutions ranging from sub-meter to 30 meters depending on payload configuration. This infrastructure serves commercial and governmental users requiring persistent land-surface, atmosphere, and ocean monitoring without territorial access constraints. Radar satellites lead structural deployment in Germany due to all-weather reliability for maritime surveillance and flood-plain mapping across the North Sea coast. Agricultural monitoring applications generate the fastest-growing demand segment as CAP compliance verification and precision-farming analytics migrate from aerial to orbital platforms. Machine learning integration within remote sensing pipelines concentrates margin pools among analytics providers rather than raw data distributors.
Germany's Federal Office for Information Security (BSI) and the national implementation of Gaia-X federation rules shape data residency requirements for Earth observation ground segments, directing institutional procurement toward domestic cloud architectures. The EU Space Programme and Copernicus Contributing Missions framework set technical interoperability standards that condition market access for commercial operators serving German agencies. Stakeholders must monitor how the European Space Agency's optional programme contributions and national space budget allocations redistribute between upstream satellite manufacturing and downstream analytics services.
Market Dynamics
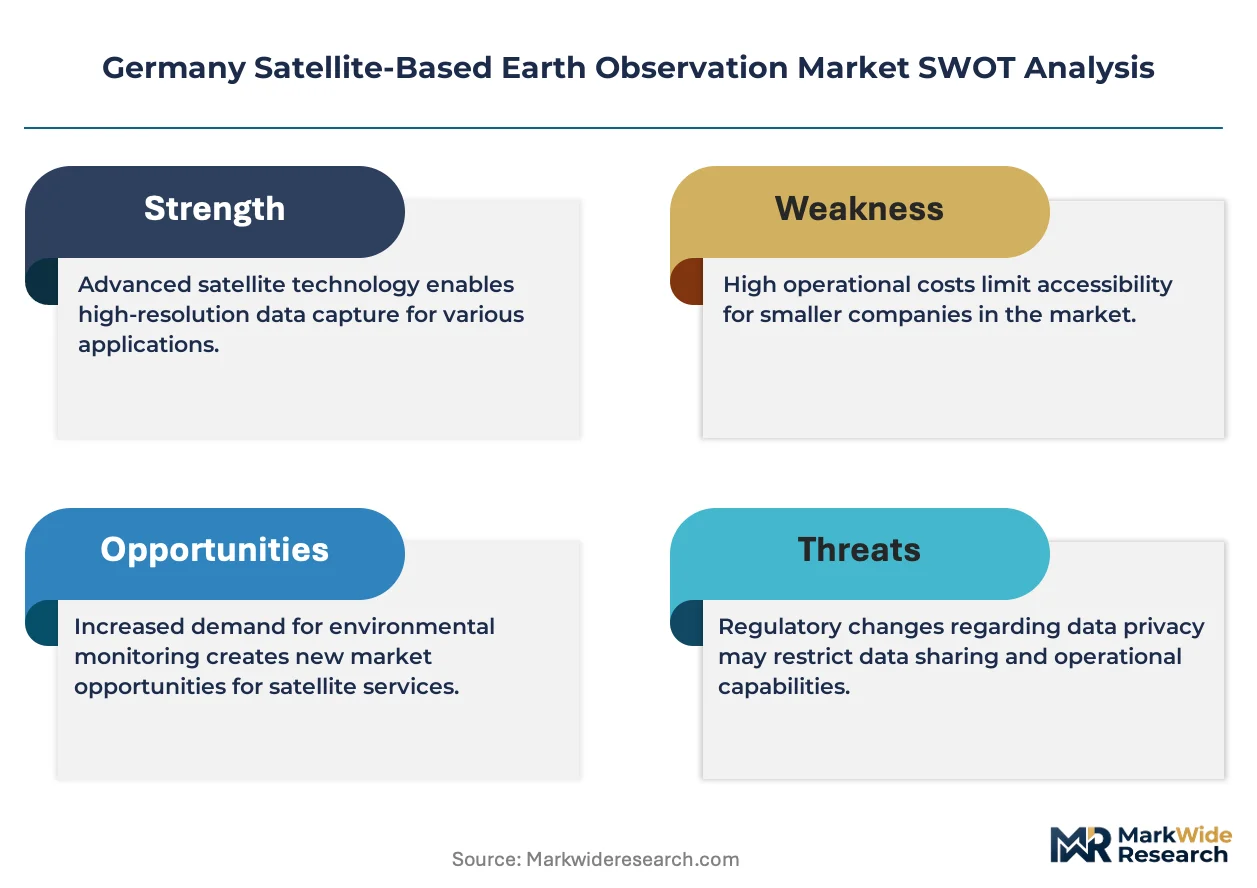
Machine learning pipelines are compressing value capture toward analytics providers and away from raw imagery distributors, restructuring how German Earth observation contracts allocate margin across the value chain.
Growth Catalysts
- Gaia-X Federation Rules:Germany's data sovereignty framework mandates domestic cloud-ground architectures for institutional procurement, redirecting public-sector spending toward compliant domestic operators and certified infrastructure providers.
- CAP Compliance Verification:The Common Agricultural Policy's satellite-based monitoring requirements are displacing aerial surveys with orbital platforms across Lower Saxony and Bavaria, creating subscription demand for high-revisit imagery.
- Synthetic Aperture Radar:All-weather imaging capability addresses persistent cloud cover limitations in maritime surveillance and flood-plain mapping along the North Sea coast, where optical sensors face seasonal reliability constraints.
Market Restraints
- Launch Cost Volatility:Ride-share pricing fluctuations and propellant supply constraints affect small-satellite constellation deployment economics for domestic platform operators.
- Spectral Band Licensing:ITU coordination procedures and national frequency allocation delays create regulatory friction for hyperspectral mission authorization within German orbital filings.
- Optical Sensor Substitution:High-altitude platform systems and stratospheric balloons are capturing persistent surveillance contracts previously served by low-Earth-orbit satellites in border monitoring applications.
Strategic Opportunities
- Rhine-Ruhr Infrastructure Monitoring:Dense urban corridor requirements for structural deformation tracking and construction compliance create concentrated demand for interferometric radar services.
- Carbon Accounting Convergence:Integration of satellite-derived biomass measurements with emissions trading systems opens analytics contracts for forest and agricultural carbon stock verification.
- Copernicus Contributing Missions:ESA framework qualification enables German commercial operators to access institutional procurement channels and technical interoperability certification for pan-European service delivery.
Industry Challenges
- Geospatial Data Science Talent:Shortage of remote sensing specialists capable of operationalizing machine learning pipelines for agricultural and infrastructure analytics limits service provider scaling.
- Ground Segment Capital Intensity:X-band and Ka-band antenna networks for direct satellite tasking require substantial infrastructure investment before revenue-generating service activation.
- Legacy System Interoperability:Federal agency migration from proprietary imagery archives to cloud-native architectures encounters data format conversion and metadata standardization bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Satellite-Based Earth Observation Market |
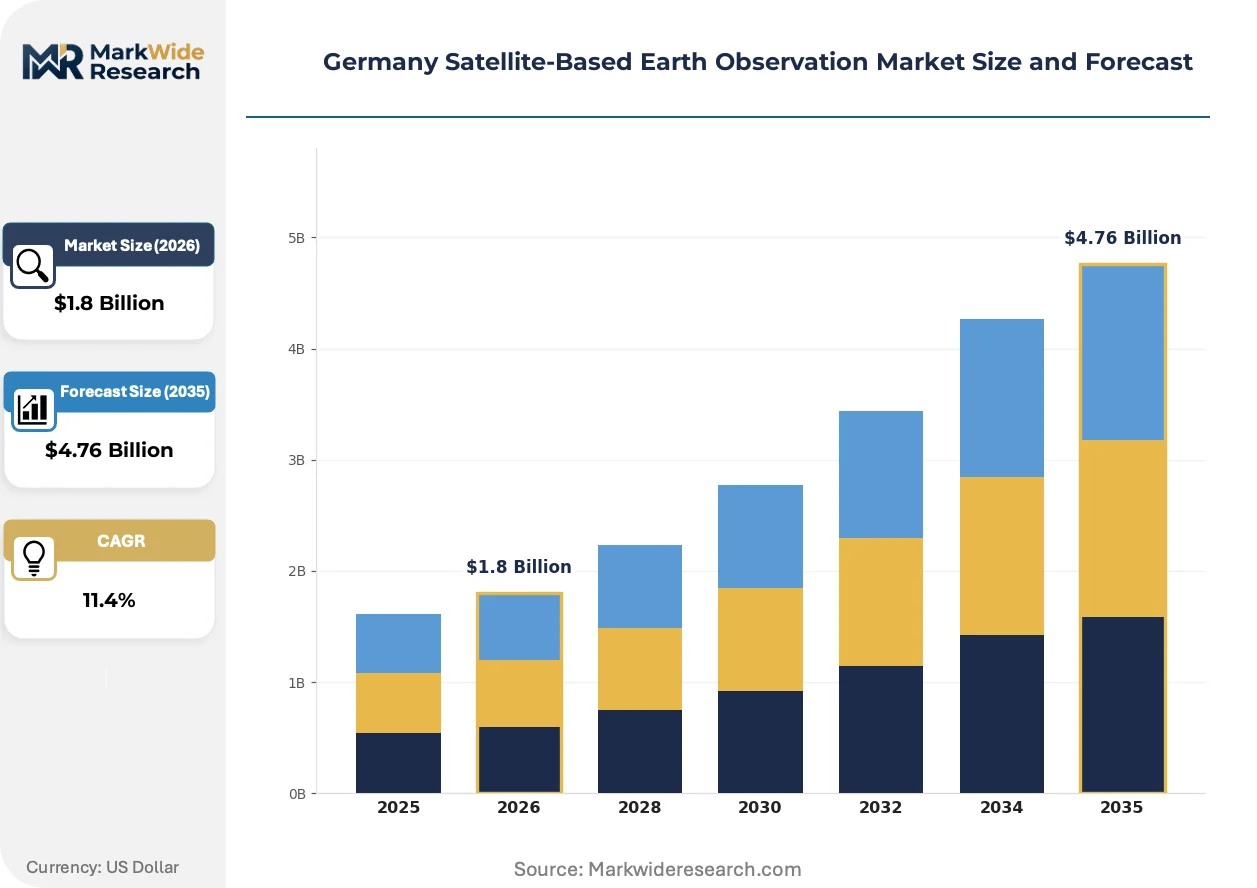
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Hyperspectral Satellites, Lidar Satellites Application: Agricultural Monitoring, Disaster Management, Urban Planning, Climate Research End User: Government Agencies, Research Institutions, Private Enterprises, Non-Governmental Organizations Technology: Data Analytics, Cloud Computing, Machine Learning, Remote Sensing |
| Companies Covered | Airbus SE, OHB SE, German Aerospace Center (DLR), GeoVille Information Systems GmbH, Planet Labs PBC, CloudEO AG, European Space Imaging, GAF AG, Telespazio Germany, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Satellite-Based Earth Observation Market Trends and Innovations
Orbital sensor platforms are converging with edge computing and on-board processing capabilities, enabling real-time analytics delivery that bypasses traditional ground-segment latency constraints for time-critical applications.
Synthetic aperture radar constellations are integrating on-board artificial intelligence accelerators for automated vessel detection and change identification prior to downlink. Maritime surveillance operators in Bremerhaven and Cuxhaven are adopting these capabilities for port traffic management. The technology is integrating near-real-time analytics into customs and border control workflows, compressing decision timelines from hours to minutes for anomaly response.
The EU AI Act's risk classification framework imposes documentation and conformity assessment requirements on automated image analysis systems deployed for public safety and critical infrastructure monitoring. German Earth observation service providers must maintain algorithmic audit trails and human oversight protocols for high-risk applications. Defense and security segments are responding by segregating training data provenance and model versioning to satisfy procurement compliance verification.
Subscription-based imagery procurement is displacing transactional per-scene purchasing across agricultural compliance and insurance verification segments. Bavarian precision farming cooperatives now contract annual data packages with guaranteed revisit frequencies rather than acquiring individual acquisitions. This concentration is most visible in the crop monitoring vertical, where volume commitments enable service providers to optimize constellation tasking schedules and reduce marginal delivery costs.
Germany Satellite-Based Earth Observation Market Segmentation
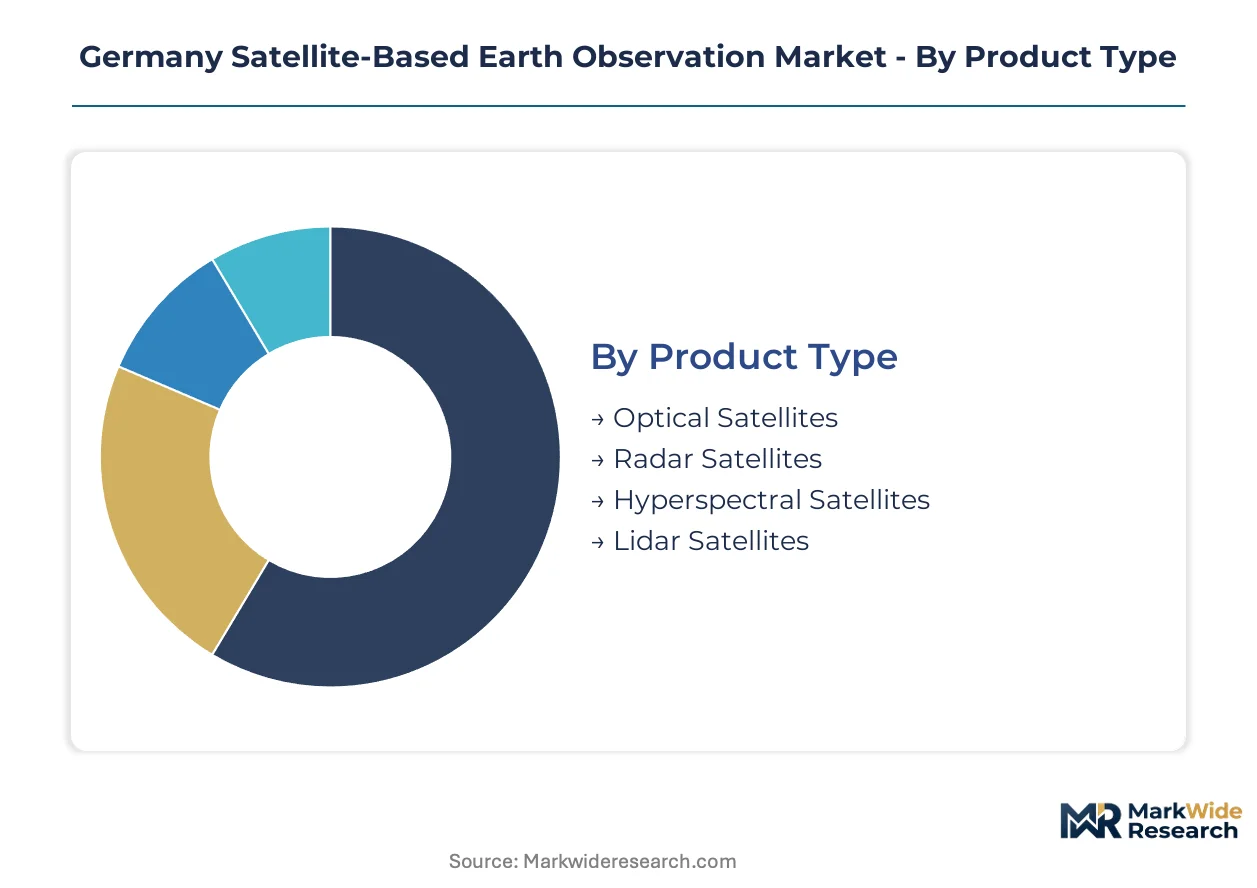
Segmentation in the Germany Satellite-Based Earth Observation Market reveals how procurement patterns concentrate around sovereign manufacturing capacity and compliance-driven data residency requirements. Different buyer types impose distinct technical specifications, from classified defense missions requiring domestic ground segments to agricultural cooperatives prioritizing subscription economics over spectral resolution.
Product Type:
Capital intensity varies sharply across orbital platforms, with synthetic aperture radar constellations demanding the heaviest upfront investment in antenna networks and thermal management systems.
- Optical Satellites:These platforms carry electro-optical sensors capturing panchromatic and multispectral imagery at resolutions reaching sub-meter precision. Lower Saxony's precision agriculture operators procure high-resolution subscriptions from these systems for crop health monitoring, though seasonal cloud cover limits revisit reliability during critical growth windows.
- Radar Satellites:Synthetic aperture radar payloads penetrate cloud cover and darkness using microwave illumination, enabling persistent monitoring regardless of atmospheric conditions. Maritime surveillance operators in Bremerhaven and Cuxhaven deploy these capabilities for vessel detection and oil spill monitoring across the North Sea, where optical sensors face chronic weather constraints.
- Hyperspectral Satellites:Instruments capturing contiguous narrow spectral bands enable material identification and chemical composition analysis.
- Lidar Satellites:Laser altimetry systems measure precise surface elevations for topographic mapping and forest biomass estimation.
Radar satellites absorb the bulk of installed capacity for institutional procurement; hyperspectral platforms are expanding most quickly as carbon accounting applications mature.
Application:
Demand concentration follows regulatory compliance mandates rather than pure technical capability, with EU agricultural policy driving volume procurement.
- Agricultural Monitoring:Satellite-derived vegetation indices and yield prediction models support precision farming and subsidy compliance verification. Bavarian farming cooperatives now contract annual data packages with guaranteed revisit frequencies, displacing aerial surveys as the default monitoring modality under CAP requirements.
- Disaster Management:Rapid damage assessment and flood extent mapping require all-weather imaging with sub-hourly latency for emergency response coordination. The North Sea coastal states prioritize radar constellations for this application given persistent cloud cover during storm seasons.
- Urban Planning:Land-use change detection and informal settlement monitoring leverage high-resolution optical archives.
- Climate Research:Long-term biosphere and cryosphere observation demands radiometrically calibrated sensors with decadal stability.
Agricultural monitoring commands the largest subscription volume; disaster management is climbing the fastest as climate adaptation budgets expand.
End User:
Procurement authority concentrates in federal and state agencies with multi-year budget commitments, while private sector adoption follows regulatory enforcement patterns.
- Government Agencies:Defense, interior, and environmental ministries operate classified and unclassified Earth observation programs with sovereign data handling requirements. BSI certification and Gaia-X compliance filter vendor selection toward domestic operators with certified ground segment infrastructure.
- Research Institutions:Universities and national laboratories access Copernicus data streams and ESA mission products through open science frameworks.
- Private Enterprises:Insurance, agriculture, and infrastructure firms purchase analytics services rather than raw imagery.
- Non-Governmental Organizations:Environmental and humanitarian organizations leverage subsidized data access for conservation and crisis response.
Government agencies dominate absolute spending; private enterprises are gaining share fastest as subscription models reduce entry barriers.
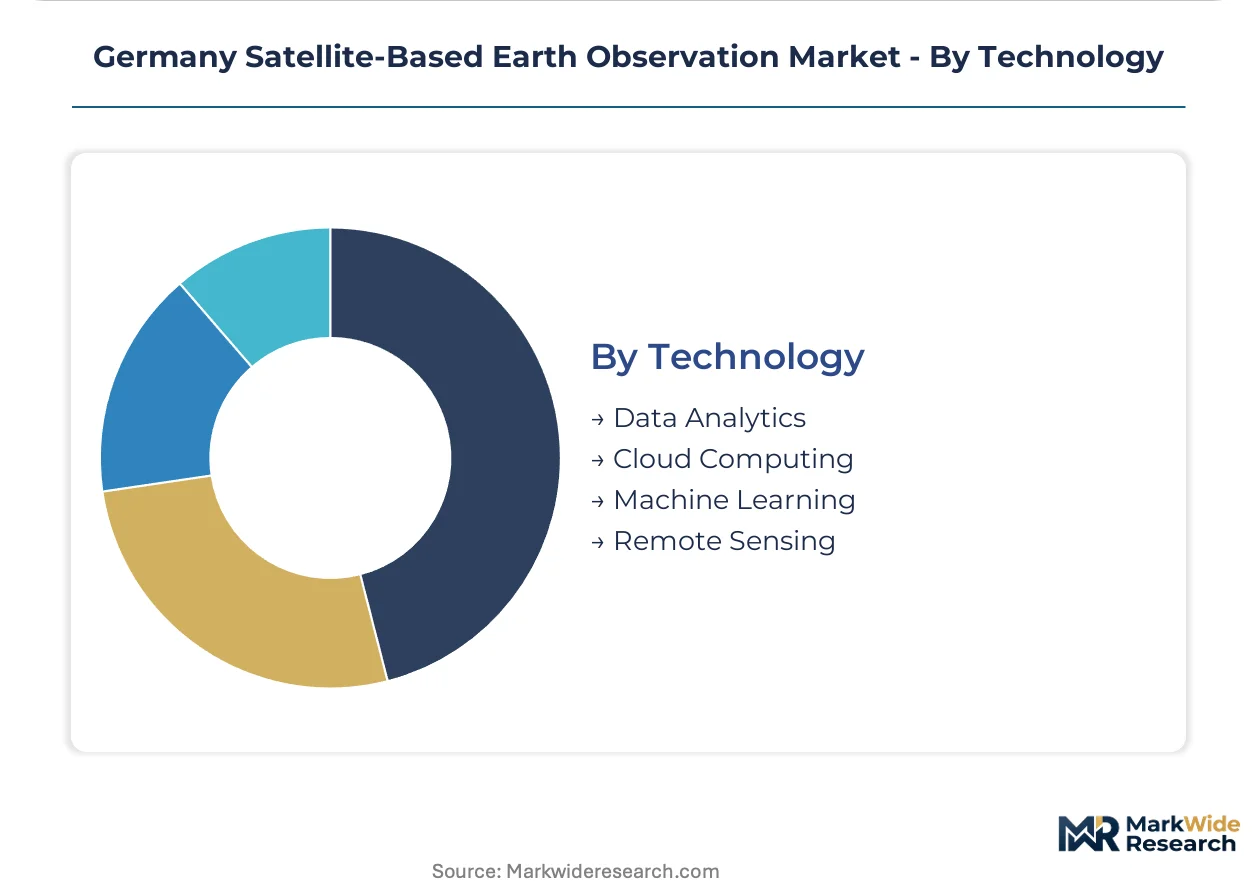
Technology:
Value capture is migrating downstream from hardware to algorithmic processing layers, restructuring competitive positioning across the supply chain.
- Data Analytics:Geospatial processing pipelines transform raw sensor data into decision-ready information products. Machine learning integration concentrates margin pools among specialized analytics providers serving the Rhine-Ruhr corridor's infrastructure monitoring demand.
- Cloud Computing:Gaia-X federation rules mandate domestic cloud architectures for institutional procurement, redirecting public-sector spending toward certified infrastructure providers with sovereign data residency guarantees.
- Machine Learning:Automated feature extraction and change detection algorithms compress analysis timelines from days to minutes.
- Remote Sensing:Fundamental observation physics and sensor calibration science underpin all downstream applications.
Data analytics absorbs the bulk of vendor investment; machine learning is expanding most quickly as the EU AI Act imposes conformity requirements on automated analysis systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan corridor anchors Germany's satellite-based Earth observation demand through infrastructure monitoring contracts and dense industrial analytics requirements.
Bavaria
Precision agriculture cooperatives in Bavaria procure annual high-resolution imagery subscriptions for CAP compliance verification. The state's implementation of Gaia-X federation rules redirects public procurement toward certified domestic cloud-ground architectures. Munich's aerospace cluster hosts specialized analytics providers serving agricultural and carbon accounting verticals.
Lower Saxony
Farming operators across Lower Saxony displace aerial surveys with orbital platforms for subsidy monitoring and yield prediction. The Federal Office for Information Security certifies ground segment infrastructure for institutional data residency compliance. The Hanover-Braunschweig corridor concentrates radar satellite tasking facilities for all-weather agricultural surveillance.
North Rhine-Westphalia
The Rhine-Ruhr urban agglomeration generates concentrated demand for interferometric radar monitoring of structural deformation and construction compliance. State environmental agencies mandate satellite-derived land-use change detection for urban planning authorization. Cologne-Düsseldorf analytics clusters serve infrastructure and insurance verification contracts.
Bremen
Maritime surveillance operators in Bremerhaven and Cuxhaven deploy synthetic aperture radar for vessel detection and oil spill monitoring across the North Sea. The EU Space Programme's Copernicus Contributing Missions framework qualifies local service providers for pan-European institutional channels. Bremen's space manufacturing heritage anchors sovereign satellite production for defense and institutional programs.
Baden-Württemberg
Machine learning integration within remote sensing pipelines concentrates in Stuttgart's automotive and industrial analytics ecosystem. The state's research institutions access ESA mission products through open science frameworks for climate and biosphere observation. Friedrichshafen's aerospace manufacturing base supplies specialized small-satellite platforms optimized for rapid revisit cycles.
Germany Satellite-Based Earth Observation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the analytics-value chain, with algorithmic processing layers capturing margin pools previously retained by raw imagery distributors. The vendor base stratifies between sovereign manufacturing specialists, rapid-revisit constellation operators, and analytics-integrated service providers. Three archetypes dominate: domestic platform manufacturers with defense certification, international daily-coverage providers with agricultural compliance positioning, and geospatial analytics specialists with machine learning pipelines. Competitive dynamics center on constellation capacity expansion and strategic partnerships for ground segment infrastructure.
Within the sovereign manufacturing tier, Airbus SE and OHB SE exemplify domestic platform specialists anchored in Bremen and Friedrichshafen production clusters. Planet Labs PBC occupies a distinct volume position below classified missions through daily coverage models extended into German agricultural compliance monitoring. GeoVille Information Systems GmbH represents the analytics-specialist archetype, concentrating margin capture through remote sensing pipelines serving infrastructure and environmental verticals.
| Leading Market Players |
|---|
| Airbus SE |
| OHB SE |
| German Aerospace Center (DLR) |
| GeoVille Information Systems GmbH |
| Planet Labs PBC |
| CloudEO AG |
| European Space Imaging |
| GAF AG |
| Telespazio Germany |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's carbon accounting mandates gate both qualified supply and premium-tier pricing access, as satellite operators must demonstrate end-to-end emissions traceability to secure institutional contracts in Germany's Gaia-X compliant procurement channels.
Pricing Analysis
Outcome-based pricing anchored to verified carbon stock measurements commands the highest premiums in German Earth observation markets. Subscription models with guaranteed revisit frequencies dominate agricultural compliance segments, while project-based contracting persists for disaster response applications. Price differentiation rests on spectral resolution and BSI certification tier, with hyperspectral analytics carrying substantial premiums over raw imagery. Cost compression in standard-resolution optical tiers is intensifying because Planet Labs and similar operators are flooding agricultural markets with daily coverage commodities. Municipal environmental agencies exhibit the greatest price sensitivity, whereas defense and security buyers prioritize sovereign data handling over unit economics.
Supply Chain Analysis
End-of-mission satellite disposal and sensor refurbishment flows are emerging as critical supply chain nodes, with OHB SE and Airbus SE operating dedicated facilities in Bremen and Friedrichshafen for component recovery and remanufacturing. Manufacturing concentration centers on Germany, France, and the United States for payload integration and platform assembly. Raw material dependencies include gallium arsenide substrates for radar electronics, specialized optical glass for telescope assemblies, and radiation-hardened semiconductors from limited foundry sources. Single-source vulnerability in X-band and Ka-band transmitter supply creates procurement bottlenecks for ground segment expansion. Distribution runs through certified Gaia-X federation nodes for institutional buyers, with direct API access for commercial analytics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's satellite-based Earth observation sector is executing a technology-transition phase, with synthetic aperture radar constellations displacing optical platforms as the default infrastructure monitoring modality across the Rhine-Ruhr corridor and North Sea maritime zones.
For Market Incumbents: Hedge against margin erosion in raw imagery distribution by deepening analytics service integration and securing exclusive ground segment certifications under BSI and Gaia-X frameworks. Incumbent platform manufacturers should accelerate on-board processing capabilities to bypass latency disadvantages against high-altitude platform substitutes. Capacity addition in sovereign cloud infrastructure represents the critical defensive lever for maintaining institutional procurement access. For New Entrants and Emerging Players: Cloud-native analytics marketplaces offer the most penetrable entry vector for specialized machine learning providers lacking constellation assets. Carbon accounting verification services for Bavarian agricultural cooperatives present concentrated white-space opportunity given CAP compliance deadlines and limited incumbent analytics specialization. A direct-to-researcher subscription model targeting university remote sensing departments bypasses entrenched government procurement channels. For Investors and Strategic Acquirers: First commercial Copernicus Contributing Mission qualification is the leading indicator that a German operator has secured sustainable institutional revenue visibility. The five-to-ten-year investment horizon favors analytics-integrated service providers over pure-play constellation operators facing launch cost volatility. Acquisition targets should demonstrate proven machine learning pipelines with EU AI Act conformity documentation. Practitioners should monitor ESA optional programme contribution allocations for early signals of upstream-downstream budget redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Copernicus Contributing Mission Qualification | Opens pan-European institutional procurement channels for German commercial operators under ESA technical interoperability standards. |
| Gaia-X Federation Certification | Mandates domestic cloud-ground architectures that redirect public-sector spending toward BSI-certified infrastructure providers. |
| On-Board AI Accelerator Integration | Enables real-time vessel detection and change identification for Bremerhaven maritime surveillance operators. |
| Carbon Accounting Analytics Development | Captures emerging demand from emissions trading system integration with satellite-derived biomass measurements. |
| Hyperspectral Mission Authorization | Requires ITU coordination and national frequency allocation compliance for material identification services. |
Research Methodology
Independent corroboration across satellite operator executives, ground segment infrastructure providers, and agricultural cooperative procurement officers underwrites the qualitative findings in this study. Primary fieldwork engaged constellation tasking managers, BSI certification auditors, and Copernicus programme coordinators. Secondary validation drew from ESA mission documentation, EU Space Programme implementation reports, Gaia-X federation technical specifications, and German federal space budget appropriations. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Historical reference periods anchored the projection horizon to documented mission deployment timelines and procurement cycle patterns. The analytical framework modeled segmentation across platform type, application vertical, end-user category, and technology layer throughout the forecast period. CAGRs derived from installed capacity expansion curves and subscription pricing trajectory analysis. Forecast inputs incorporated ITU filing queues, ESA optional programme contribution schedules, and CAP compliance deadline enforcement patterns.
The model holds under stable regulatory enforcement of data sovereignty requirements; deviation in ITU coordination timelines or ESA budget reallocation would shift constellation deployment economics. Practitioners should monitor Copernicus Contributing Mission qualification announcements and Gaia-X certification issuance rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Russia Satellite Connectivity Market
Satellite
North America Remote Sensing Services Market
Satellite
Satellite Amplifier Market
Satellite
Germany Satellite Communications Market
Satellite
Satellite Imaging Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Europe Military Satellite Market
Satellite
China Satellite Connectivity Market
Satellite
Satellite Transponder Market
Satellite
Satellite Communication (SATCOM) Market