
 Diesel Common Rail Injection System Market | 2026-2036
Diesel Common Rail Injection System Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Common Rail Injection System Market Intelligence
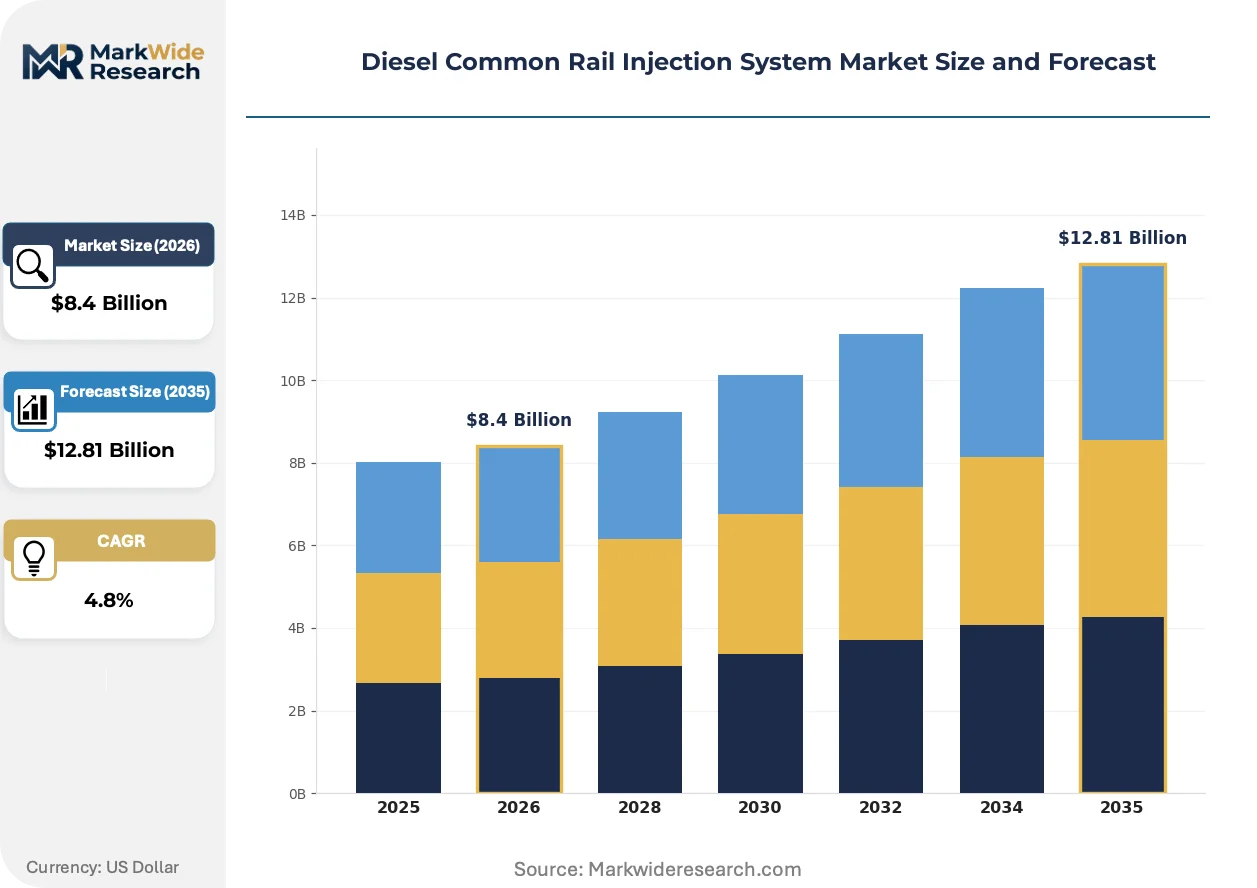
Compliance with Euro 6 and upcoming Euro 7 emissions standards is collapsing the distinction between standard and premium high-pressure systems, forcing all suppliers to meet higher performance baselines. Robert Bosch GmbH sustains its market leadership through its vast R&D investment and global manufacturing footprint. Denso Corporation leverages deep ties with Japanese and other Asian OEMs to secure significant volume. Meanwhile, Continental AG competes by offering integrated powertrain systems that combine its advanced electronic control units with injection hardware.
A diesel common rail injection system is a high-pressure fuel delivery architecture used in modern diesel engines. These systems operate at pressures often exceeding 2,000 bar to precisely control and atomize fuel, enabling cleaner combustion and improved engine efficiency. High-pressure pumps and injectors constitute the core value components and are central to system performance. The heavy-duty trucks application continues to be the largest consumer of these systems, propelled by the constant need for freight transport and logistics globally.
Regulatory frameworks from the US EPA and the European Union's ECHA directly influence system design and material composition. Mandates such as Euro 6 in Europe and similar standards in China and India compel manufacturers to reduce NOx and particulate matter emissions. This regulatory pressure necessitates continuous innovation in injection pressure, timing, and control. The key strategic decision for component suppliers and OEMs is how to allocate investment between advancing diesel technology and pivoting to alternative powertrains.
Market Dynamics
The convergence of emissions regulations, specifically the push toward Euro 7 standards, is the central force shaping the market. This pressure eliminates the performance gap between system tiers, compelling all manufacturers to innovate toward higher injection pressures and more precise electronic controls.
Growth Catalysts
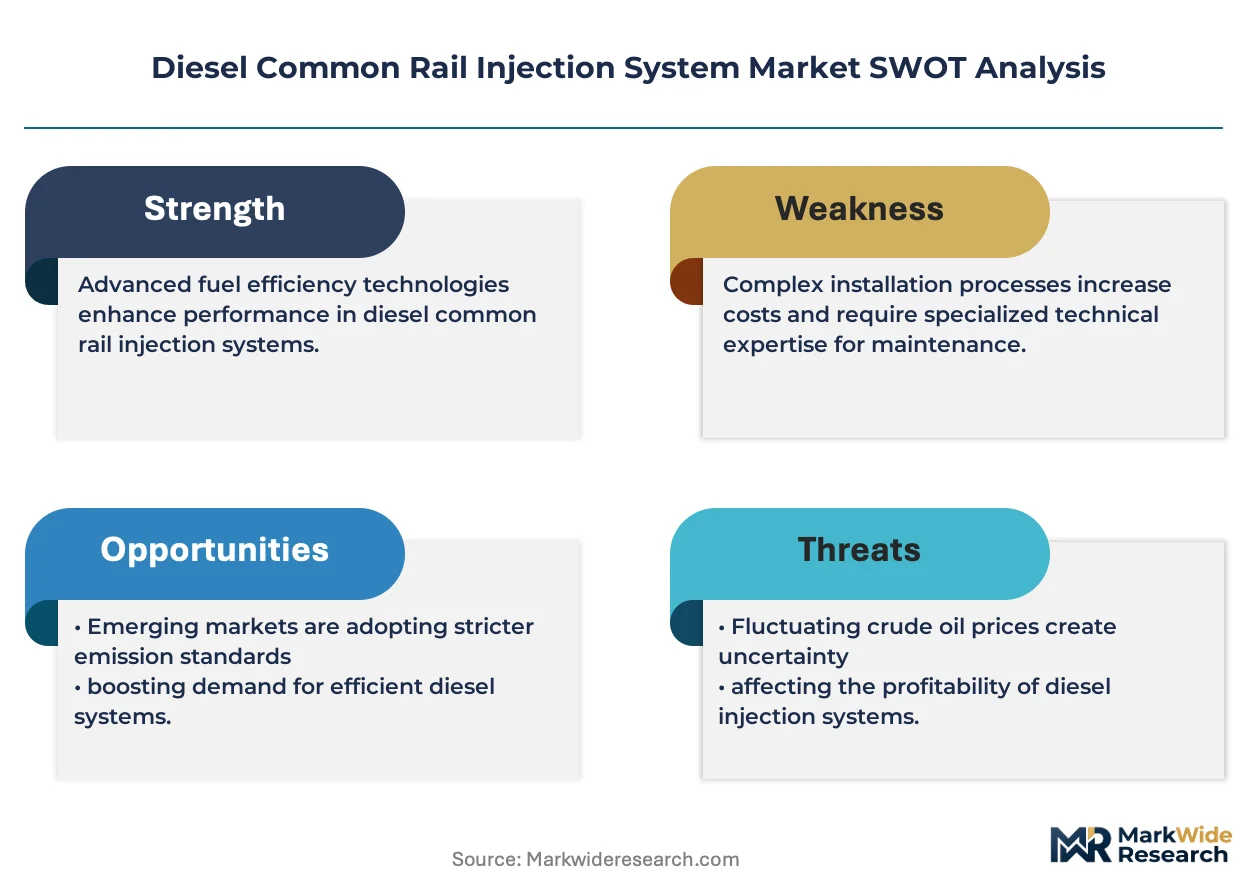
- Stringent Emissions Mandates:Compliance with Euro 6 standards in Europe and similar regulations in India and China necessitates the adoption of advanced common rail systems to reduce NOx and particulate matter, directly driving system upgrades in new heavy-duty trucks.
- Infrastructure Development:Sustained investment in construction and logistics infrastructure, particularly in Asian economies, fuels demand for heavy-duty commercial vehicles, which are the primary consumers of these high-pressure fuel systems.
- Engine Downsizing and Efficiency:The pursuit of greater fuel economy and power density in diesel engines relies on higher injection pressures, making advanced common rail systems essential for achieving performance targets in smaller displacement engines.
Market Restraints
- Substitution by Alternative Powertrains:The strategic shift toward battery-electric and hydrogen fuel cell vehicles, especially in light and medium-duty applications, curtails the long-term addressable market for new diesel injection systems.
- High System Complexity and Cost:The precision engineering and advanced materials required for injectors and pumps to withstand pressures over 2,000 bar result in high component costs, which can be a barrier for cost-sensitive segments.
- Regulatory Divergence:Misalignment in the timing and specific requirements of emissions standards between the EU, the US EPA, and China's MEE complicates global product development and certification, increasing R&D overhead.
Strategic Opportunities
- Aftermarket and Remanufacturing:A large and aging global fleet of diesel vehicles creates a substantial opportunity in the aftermarket for high-quality replacement injectors, pumps, and repair services, particularly for certified remanufactured components.
- Non-Road Mobile Machinery (NRMM):Agricultural and construction equipment in developing nations represents an underpenetrated segment where the benefits of modern common rail systems in terms of fuel efficiency and reliability are highly valued.
- Hydrogen-ICE Adaptation:The potential for hydrogen-fueled internal combustion engines (H2-ICE) offers a pathway for suppliers to adapt their high-pressure direct injection expertise for a new, low-carbon fuel source, extending the life of core technologies.
Industry Challenges
- ECU Software Complexity:Developing and validating the sophisticated software for electronic control units that manage multiple injection events per cycle requires specialized software engineering talent that is in short supply.
- Capital-Intensive Manufacturing:Establishing production lines for high-pressure components demands significant capital investment in cleanroom facilities, precision machining, and specialized testing equipment to ensure quality and reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Common Rail Injection System Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectors, High-Pressure Pumps, Electronic Control Units, Rail Assemblies, Sensors Fuel Type: Ultra-Low Sulfur Diesel, Biodiesel Blends, Synthetic Diesel, Hydrotreated Vegetable Oil, Renewable Diesel Application: Light Commercial Vehicles, Heavy-Duty Trucks, Agricultural Equipment, Construction Machinery, Marine Engines End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Delphi Technologies plc, BorgWarner Inc., Stanadyne LLC, Magneti Marelli SpA, Cummins Inc., HYUNDAI KEFICO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Common Rail Injection System Market Strategic Shifts & Innovations
Intensifying regulatory pressure and the parallel pursuit of operational efficiency are forcing a technological acceleration in diesel injection systems. Innovation is concentrating on achieving cleaner combustion through more precise fuel metering and atomization under a wider range of engine operating conditions.
Advanced piezoelectric injectors enable ultra-fast, multiple injection events within a single combustion cycle. Heavy-duty truck OEMs are the primary adopters, seeking to meet stringent emissions targets without sacrificing performance. This technology is miniaturizing the actuator mechanism, allowing for more compact injector designs that improve spray targeting and enable more flexible cylinder head architecture for future engine platforms.
The European Union's upcoming Euro 7 regulation is a significant driver of system design. It imposes stricter limits on NOx and other pollutants across a broader set of real-world driving conditions than its predecessors. The heavy-duty vehicle segment is most affected, compelling suppliers to engineer systems with higher maximum pressures and faster-acting injectors to maintain compliance.
Large fleet operators are altering aftermarket service patterns, shifting from simple component replacement to certified remanufacturing programs to manage total cost of ownership. This trend disrupts the business model of independent repair shops, favoring OEM-authorized service networks that can guarantee performance and warranty. This behavior is most prominent in the North American and European logistics sectors.
Diesel Common Rail Injection System Market Segmentation
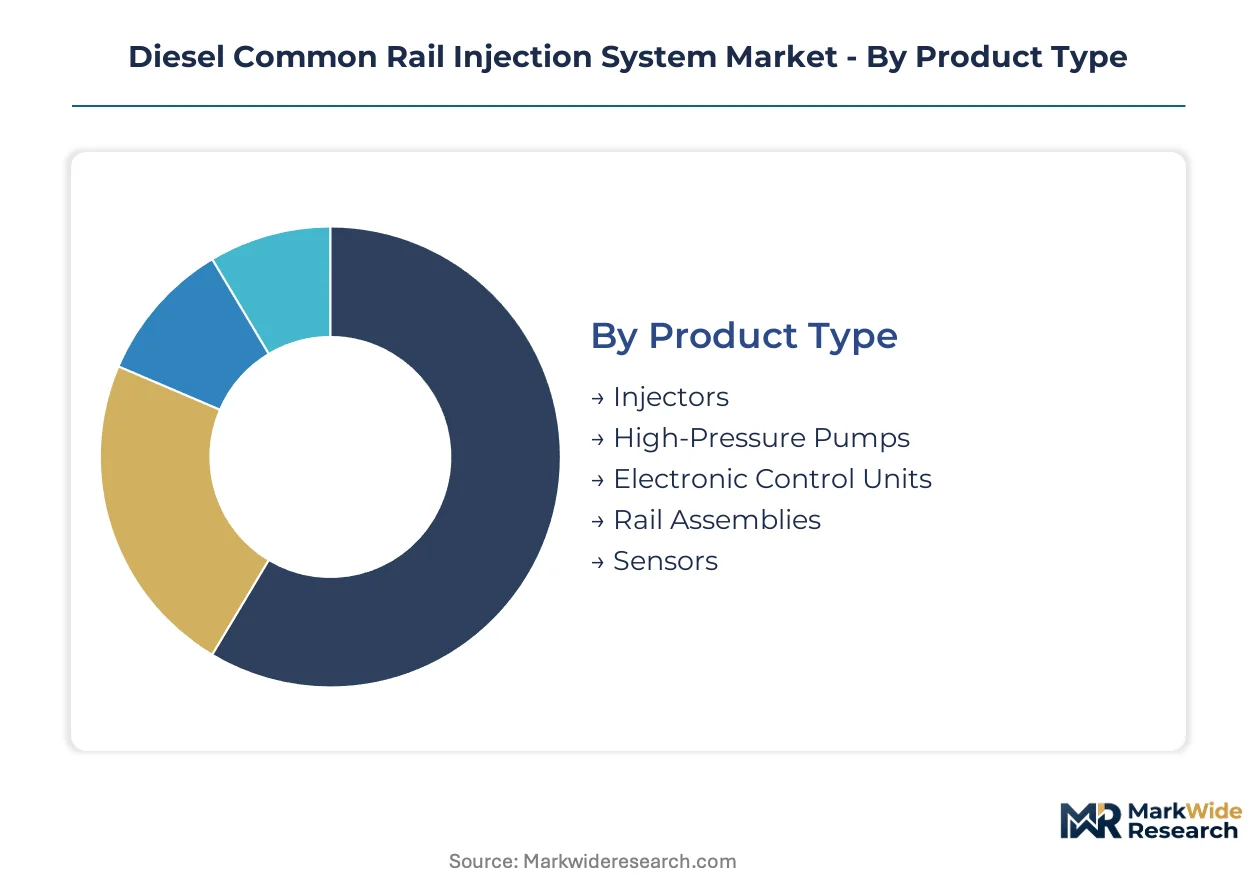
The diesel common rail injection system market categorizes its revenue streams and technological advancements across several critical dimensions. Understanding these segments clarifies the varying demands for precision components, fuel compatibility, application-specific engineering, and distribution channels within the industry.
Product Type:
The geographic spread of manufacturing capabilities influences the availability and cost of various product types across different regions.
- Injectors:These components precisely atomize and deliver fuel into the combustion chamber. Demand for advanced piezoelectric injectors is particularly high in Europe and Japan, where stringent Euro 6 and upcoming Euro 7 emissions standards compel manufacturers to achieve finer control over injection events.
- High-Pressure Pumps:These units generate the immense pressure required for efficient fuel atomization. German and Japanese suppliers dominate the high-pressure pump segment, leveraging their deep engineering expertise and global manufacturing footprints to serve heavy-duty truck OEMs across North America and Asia.
- Electronic Control Units:ECUs manage the complex timing and duration of injection events.
- Rail Assemblies:These systems store fuel at high pressure before distribution to injectors.
- Sensors:Sensors monitor various engine and fuel parameters for optimal system operation.
Injectors command the established base. The steepest expansion runs through High-Pressure Pumps.
Fuel Type:
The maturity of various fuel types dictates investment in compatible common rail systems, from established diesel to emerging renewable alternatives.
- Ultra-Low Sulfur Diesel:This fuel type remains the global standard for diesel engines due to its widespread availability and established infrastructure. Common rail systems are optimized for ULSD, ensuring compliance with current emissions regulations in the US, Europe, and Asia.
- Renewable Diesel:Derived from biomass, renewable diesel offers a significant reduction in carbon emissions and is gaining traction in European and North American markets. Common rail systems require material compatibility and calibration adjustments to handle its distinct properties, supporting its growing adoption.
- Biodiesel Blends:These blends combine conventional diesel with fatty acid methyl esters.
- Synthetic Diesel:Produced from natural gas or coal, synthetic diesel offers high purity and consistent quality.
- Hydrotreated Vegetable Oil:HVO is a second-generation biofuel offering similar performance to renewable diesel.
Demand for Ultra-Low Sulfur Diesel remains foundational. Renewable Diesel is gaining momentum fastest.
Application:
The diverse applications of diesel common rail systems range from primary transport vehicles to specialized machinery, each with unique performance requirements.
- Heavy-Duty Trucks:These vehicles represent the largest consumer of common rail systems, driven by global logistics and freight transport needs. Systems for heavy-duty trucks prioritize durability, high injection pressures, and fuel efficiency to meet demanding operational cycles and stringent emissions standards in Europe and China.
- Construction Machinery:Excavators, loaders, and other construction equipment require robust common rail systems capable of operating reliably in harsh environments. These applications demand high torque output and fuel efficiency, especially in Asian and African infrastructure development projects.
- Light Commercial Vehicles:LCVs utilize common rail systems for improved fuel economy and reduced emissions.
- Agricultural Equipment:Tractors and harvesters benefit from common rail technology for power and efficiency.
- Marine Engines:Common rail systems in marine applications enhance fuel efficiency and reduce emissions in commercial and recreational vessels.
Heavy-Duty Trucks represents the consistent demand base. Construction Machinery shows strong potential.
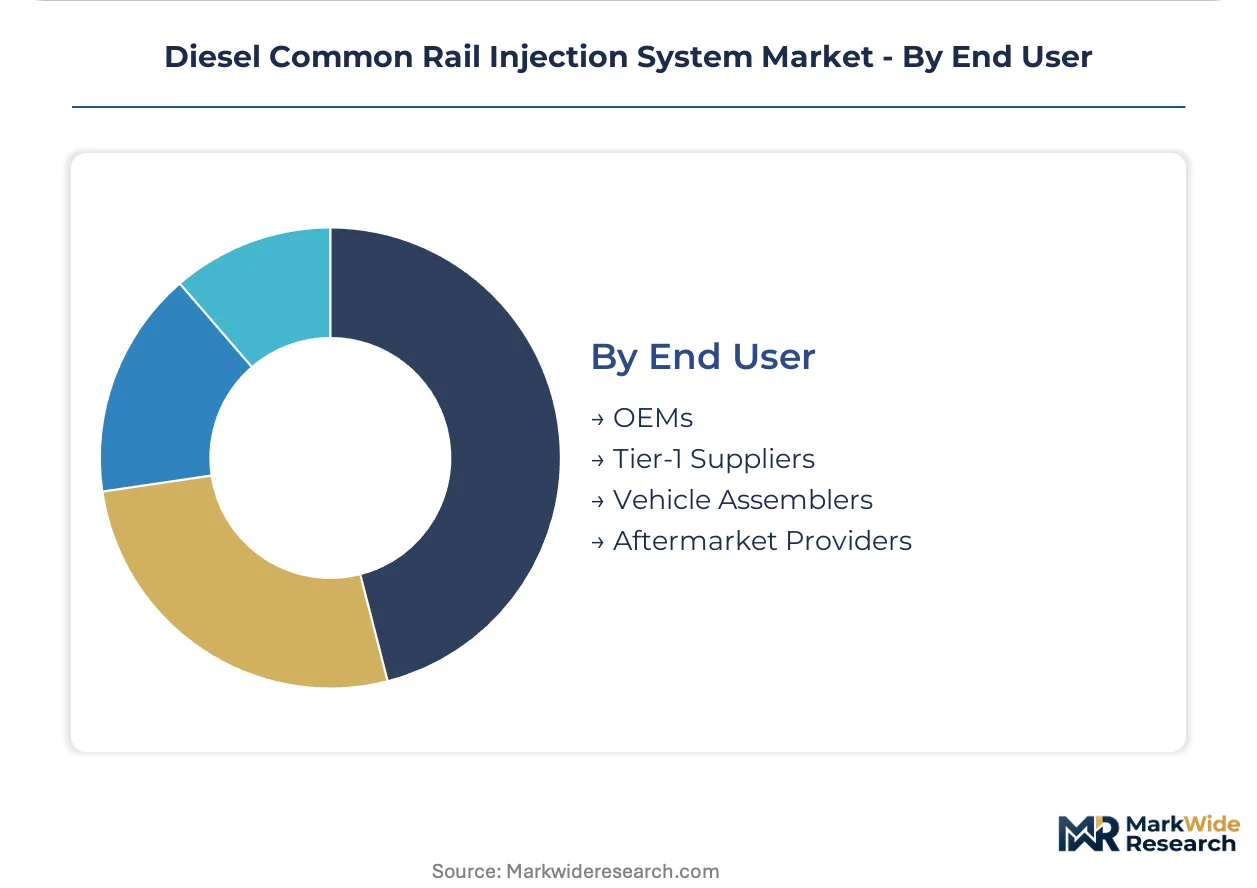
End User:
The customer type influences the sales and distribution strategies for common rail injection systems, spanning initial vehicle production to long-term maintenance.
- OEMs:Original Equipment Manufacturers integrate common rail systems directly into new diesel engines and vehicles during the manufacturing process. These relationships are characterized by long-term contracts and collaborative R&D to meet specific engine design and emissions compliance targets for passenger cars, trucks, and off-highway equipment.
- Aftermarket Providers:This segment includes independent repair shops and authorized service centers that supply replacement parts and services for existing diesel vehicles. The aftermarket is driven by the need for maintenance, repairs, and upgrades for an aging global fleet, particularly for high-wear components like injectors and pumps in North America and Europe.
- Tier-1 Suppliers:These companies supply complete common rail systems or major components directly to OEMs.
- Vehicle Assemblers:Assemblers integrate engines and components from various suppliers into finished vehicles.
The immediate volume originates from OEMs. Long-term value shifts towards Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for diesel common rail injection systems centers heavily on heavy-duty truck manufacturers and large-scale construction equipment producers. These segments, driven by logistics and infrastructure development, dictate regional demand patterns and technological adoption. Regulatory frameworks across major economies continue to shape market evolution.
Germany
Demand for advanced common rail systems in Germany stems from a robust automotive manufacturing sector and a strong focus on emissions reduction in commercial vehicles. The European Union's Euro 6 and upcoming Euro 7 standards compel continuous innovation in fuel efficiency and emissions control. Major engineering hubs in Stuttgart and Munich drive research and development for high-pressure injection technologies.
China
China's extensive infrastructure development and booming logistics industry fuel significant demand for heavy-duty trucks and construction machinery. The Ministry of Ecology and Environment's (MEE) stringent emissions standards, mirroring Euro 6, necessitate the adoption of advanced common rail systems. Industrial clusters in Jiangsu and Guangdong provinces are central to both manufacturing and application of these systems.
India
Sustained investment in infrastructure projects and a growing freight transport sector underpin India's demand for diesel common rail injection systems. Bharat Stage (BS) VI emission norms, equivalent to Euro 6, mandate advanced fuel injection technology across new vehicles. Manufacturing centers in Pune and Chennai are critical for local production and supply chain integration.
United States
The United States market for diesel common rail injection systems is driven by a large fleet of heavy-duty trucks and off-highway equipment supporting logistics and agriculture. The Environmental Protection Agency (EPA) regulations for NOx and particulate matter emissions push for higher performance systems. The Midwest automotive manufacturing belt and Texas's energy sector are key consumption areas.
Japan
Japan's demand for common rail systems is influenced by its advanced automotive industry and a strong emphasis on engine efficiency and environmental compliance. Strict domestic emissions standards, often aligned with European benchmarks, drive the adoption of high-precision injectors and pumps. Tokyo and Nagoya serve as critical centers for automotive R&D and manufacturing.
Diesel Common Rail Injection System Market Key Industry Players
Player mix skews toward established global automotive suppliers with deep engineering capabilities and extensive manufacturing footprints. The market exhibits a consolidated structure at the premium end, with a tiered system allowing for specialized component providers. Strategic partnerships with original equipment manufacturers (OEMs) and continuous investment in research and development are dominant competitive moves.
Within the global technology leader archetype, Robert Bosch GmbH represents a comprehensive system provider, leveraging its vast R&D investment and global manufacturing presence. Denso Corporation exemplifies a strong OEM-centric approach, securing significant volume through deep ties with Japanese and other Asian automotive manufacturers. Continental AG occupies a position as an integrated powertrain systems specialist, combining advanced electronic control units with injection hardware to offer holistic solutions.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Delphi Technologies plc |
| BorgWarner Inc. |
| Stanadyne LLC |
| Magneti Marelli SpA |
| Cummins Inc. |
| HYUNDAI KEFICO Corporation |
| Others |
Cost & Logistics Intelligence
Euro 6 and upcoming Euro 7 emissions standards gate both supply qualification for advanced diesel common rail systems and influence price differentiation among high-performance components. This regulatory pressure mandates continuous innovation, impacting both manufacturing costs and market value for compliant systems.
Pricing Analysis
Cost-plus contracts with indexation to raw material prices, such as specialized steel alloys and piezoelectric ceramics, define the dominant pricing model for common rail systems. Price differentiation stems from the certification level, ensuring compliance with stringent emissions standards like Bharat Stage VI, and the brand premium associated with established Tier-1 suppliers. Pricing pressure intensifies due to the high R&D investment required for continuous regulatory compliance and the competition from alternative powertrain development. Aftermarket providers demonstrate higher price sensitivity compared to Original Equipment Manufacturers, who prioritize performance and integration for new vehicle platforms.
Supply Chain Analysis
Inbound logistics costs, particularly related to specialized component transport and container availability across key trade lanes from Europe and Asia, influence the supply chain. Geographic supply concentration centers in Germany, Japan, and China for high-precision components and electronic controls. Raw material dependencies include advanced steel for pumps and injectors, along with rare earth elements for electronic control units. Single-source vulnerability for highly specialized components, like piezoelectric actuators, represents a structural supply chain risk. Distribution runs through direct channels to OEMs for new vehicle integration, complemented by authorized service networks for aftermarket sales and remanufacturing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a buyer-power-shift story, driven by the consolidation among heavy-duty truck OEMs, which increases their procurement leverage over component suppliers.
For Market Incumbents:
Shield core diesel common rail revenue by aggressively investing in hydrogen-ICE direct injection technology, leveraging existing high-pressure expertise. Expand certified remanufacturing programs to capture long-term aftermarket value, countering the strategic shift toward alternative powertrains. This ensures channel control and maintains relevance across an aging global fleet. Continuous R&D in advanced materials and faster-acting injectors supports compliance with evolving emissions standards.
For New Entrants and Emerging Players:
Lead with cost-effective, high-reliability replacement components for the aftermarket, particularly targeting the large installed base of Euro 5 and BS IV-compliant vehicles. Focus on underpenetrated segments like non-road mobile machinery in developing nations, where fuel efficiency gains are highly valued. A targeted go-to-market angle involves offering certified repair kits and remanufactured parts through independent service networks. This approach minimizes direct competition with OEM-tied suppliers for new vehicle platforms.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core diesel injection assets, or from specialized precision component manufacturers. Long-term viability for diesel common rail systems will persist for 5-10 years in heavy-duty and non-road applications, particularly outside of Europe and North America. Acquire companies with strong intellectual property in high-pressure fuel delivery or advanced materials science. The primary signal to watch is the pace of OEM investment and commercialization of hydrogen-fueled internal combustion engines.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in H2-ICE Direct Injection R&D | This initiative extends core high-pressure injection expertise to a low-carbon fuel source, securing future revenue streams. |
| Expand Certified Remanufacturing Footprint | This move captures aftermarket value from aging diesel fleets, leveraging existing product knowledge and service infrastructure. |
| Develop Integrated Powertrain Solutions | This strategy offers OEMs holistic system performance, combining advanced ECUs with injection hardware for optimized engine control. |
| Secure Long-Term OEM Supply Contracts | These contracts provide revenue stability and volume guarantees, reinforcing market position with major heavy-duty truck manufacturers. |
| Enhance ECU Software Engineering Capabilities | This investment addresses the growing complexity of injection control, enabling faster development of compliant and efficient systems. |
Research Approach
Desk research of regulatory documents, industry association reports, and financial filings preceded structured interviews with heavy-duty truck OEMs, Tier-1 component suppliers, aftermarket distributors, and regulatory compliance officers. This approach combined primary insights from industry stakeholders with secondary validation from published data sources. The analysis employed both bottom-up market sizing and top-down validation to ensure data accuracy and comprehensive coverage.
Variance decomposition informed the analytical framework, disaggregating market growth drivers across the analysis window. Segmentation dimensions modeled included product type, fuel type, application, end user, and regional emissions standards. Compound annual growth rates were derived from historical trends, projected regulatory impacts, and anticipated technological shifts. Key forecast inputs included global heavy-duty truck production forecasts and infrastructure spending projections in Asian economies.
The analysis sits within stated boundaries; outcomes outside significant shifts in regulatory enforcement or accelerated alternative powertrain adoption would require recalibration. Forecasts reflect assumptions documented through expert consensus and historical performance. Unforeseen macroeconomic downturns or geopolitical events represent specific risk factors that could revise these projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Automotive Grease Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Drum Brake Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Synchronous Timing Belts Market