
 Zonal Wiring Harness Platforms for Software-Defined Vehicles Market | 2026-2036
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market Insights
Automotive electrical engineering talent is rotating from legacy domain-controller design toward zonal integration and high-speed signal integrity, tightening the labor pool for OEMs and Tier-1 suppliers. Aptiv leverages its full-stack vehicle architecture capability to sustain early-mover advantage in zonal compute zones. Yazaki Corporation anchors Asian supply relationships through its manufacturing scale in connector and harness assembly. Continental competes by integrating its breadth of sensor and actuator portfolios with wiring platforms.
Zonal wiring harness platforms for software-defined vehicles consolidate multiple discrete harnesses into region-based electrical zones that reduce copper mass, cut connector count, and enable over-the-air updatable power and data distribution through 48V-to-12V hybrid architectures and shielded twisted-pair Ethernet backbones. High-speed wiring harness and Ethernet technology segments lead current revenue contribution as autonomous driving modules and vehicle communication networks demand multi-gigabit data throughput. Fiber optic harness applications are expanding fastest in safety systems where electromagnetic immunity and deterministic latency prove critical.
FCC vehicle-to-everything spectrum rules, NHTSA cybersecurity guidelines, and EU Cyber Resilience Act conformity requirements are reshaping harness validation protocols and supplier qualification timelines across North America and Europe. ISO 26262 functional safety and ISO/SAE 21434 cybersecurity standards now govern zonal harness design, forcing Tier-1 suppliers to restructure development workflows and documentation practices. Stakeholders must monitor how regional divergence in software-defined vehicle certification timelines affects platform standardization decisions and supplier geographic allocation.
Market Dynamics
The migration from domain-based to zonal electrical architectures is compressing supplier margins while demanding simultaneous investments in high-speed data transmission and functional safety certification. This structural transition favors suppliers with captive semiconductor packaging and automated harness assembly capabilities.
Growth Catalysts
- EU AI Act compliance mandates:Vehicle manufacturers must demonstrate traceable decision pathways for autonomous functions, requiring zonal harness platforms with embedded diagnostics and deterministic latency guarantees.
- 48V-to-12V hybrid power distribution:Mild-hybrid powertrains need consolidated zone controllers capable of managing dual-voltage rails through intelligent fuse replacement and load balancing algorithms.
- Copper mass reduction targets:OEM sustainability commitments are driving harness consolidation that eliminates redundant power feeds and grounding paths across vehicle zones.
Market Restraints
- Specialized connector supply concentration:High-speed Ethernet and shielded twisted-pair interconnects rely on precision stamping and plating capacity concentrated in German and Japanese supplier bases.
- Functional safety validation costs:ISO 26262 ASIL-D certification for zonal power distribution modules requires fault injection testing and failure mode analysis that extends development cycles.
- Legacy 12V accessory compatibility:Transition architectures must maintain backward compatibility with established lighting, HVAC, and infotainment subsystems through voltage translation modules.
Strategic Opportunities
- India automotive manufacturing expansion:Domestic OEMs and joint ventures are localizing zonal architecture development to serve export markets and comply with phased domestic content requirements.
- Fiber optic safety backbone integration:Deterministic latency requirements for brake-by-wire and steer-by-wire systems create openings for optical harness segments immune to electromagnetic interference.
- Over-the-air update infrastructure:Zonal platforms with software-defined power distribution enable subscription-based feature activation and remote diagnostic services.
Industry Challenges
- Signal integrity engineering scarcity:The labor pool for multi-gigabit Ethernet harness design and electromagnetic compatibility validation remains shallow relative to demand from autonomous driving programs.
- Cross-functional integration complexity:Zonal architectures require simultaneous coordination between electrical, software, thermal, and mechanical engineering teams without established handoff protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zonal Wiring Harness Platforms for Software-Defined Vehicles Market |
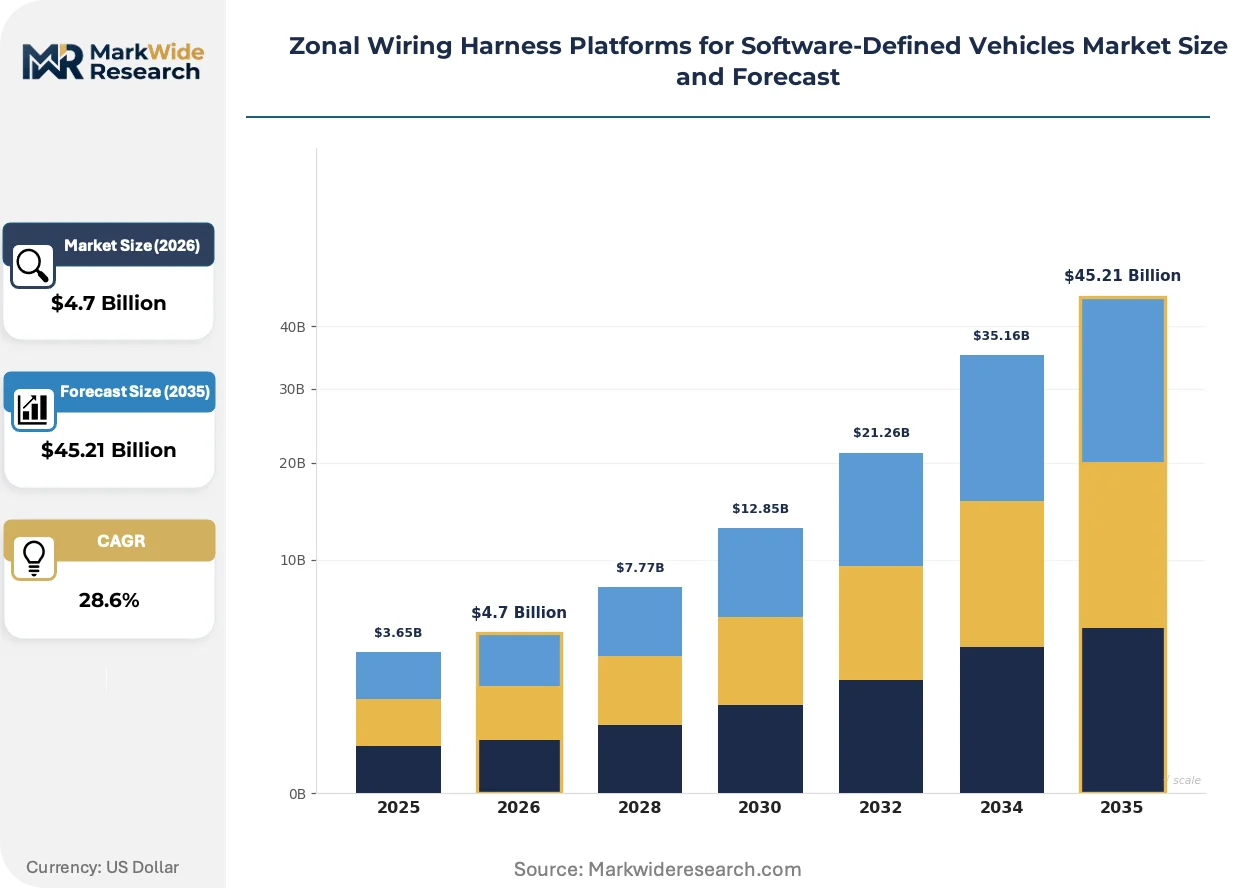
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
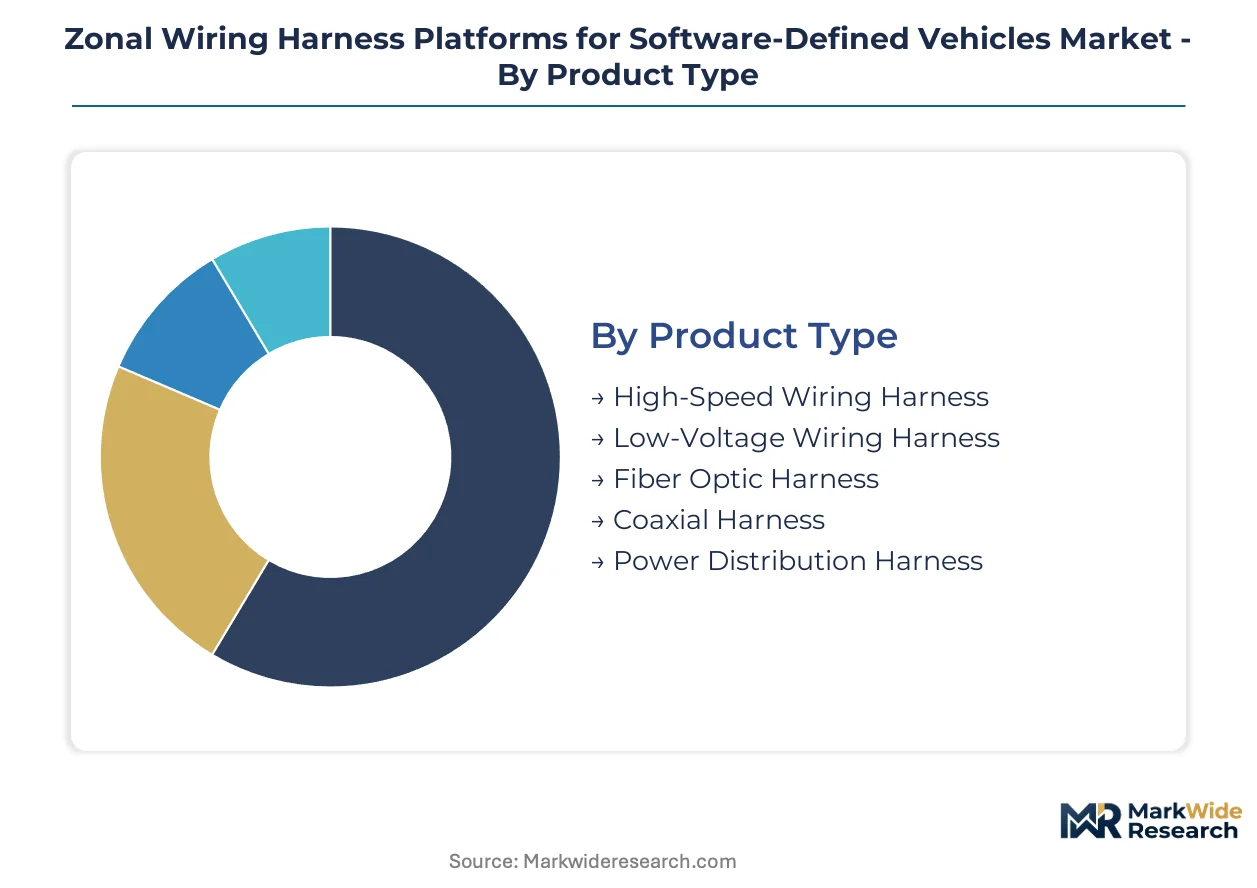
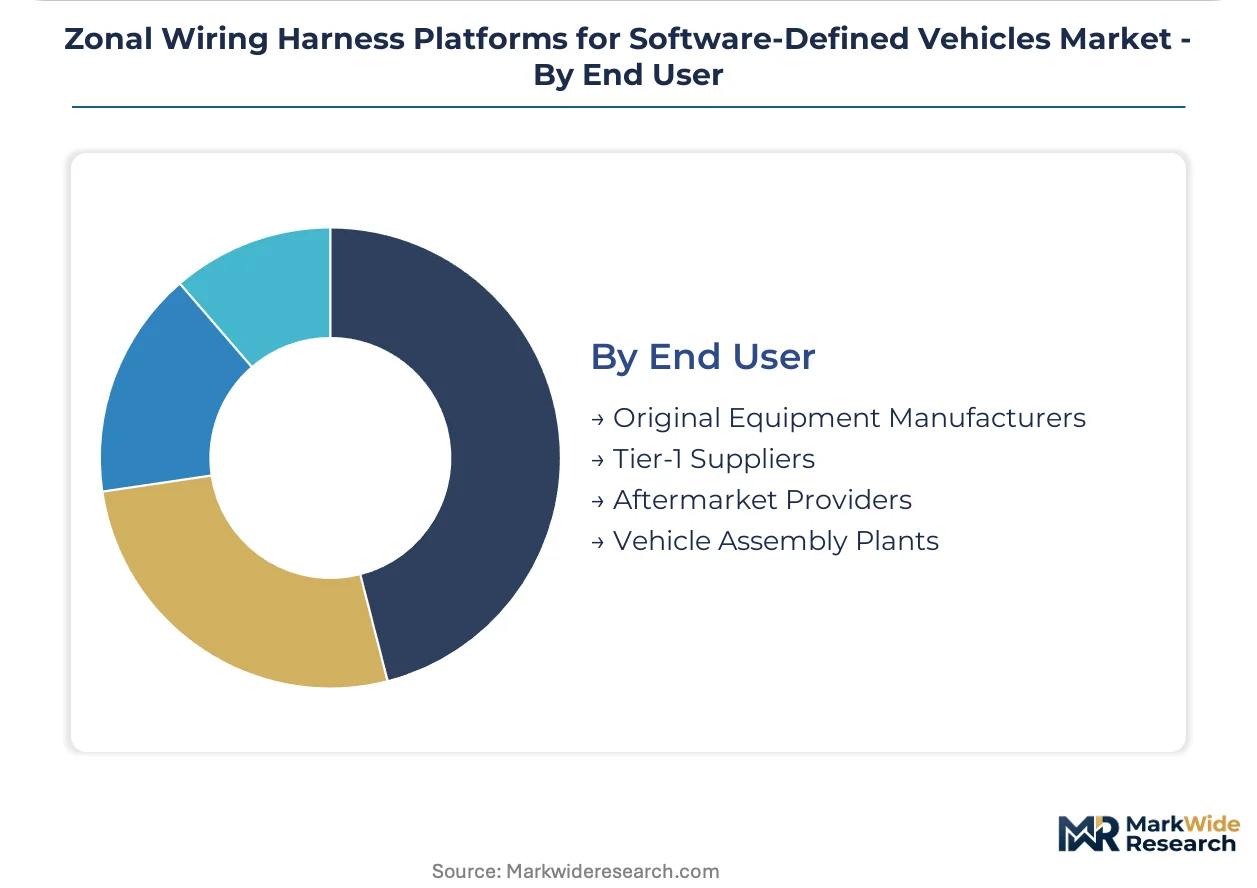
| Segmentation | Product Type: High-Speed Wiring Harness, Low-Voltage Wiring Harness, Fiber Optic Harness, Coaxial Harness, Power Distribution Harness Technology: CAN Bus, FlexRay, Ethernet, LIN Bus, MOST Bus, BroadR-Reach Application: Electrical Distribution, Data Transmission, Safety Systems, Infotainment Controls, Autonomous Driving Modules, Vehicle Communication Networks End User: Original Equipment Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assembly Plants |
| Companies Covered | Aptiv, Leoni, Yazaki Corporation, Sumitomo Electric Industries, TE Connectivity, Robert Bosch, Continental, Denso Corporation, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market Trends and Innovations
Electrical distribution is undergoing architectural disaggregation as discrete fuse boxes and relay centers dissolve into software-controlled solid-state power centers. This transformation demands new competencies in semiconductor integration and thermal management.
Shielded twisted-pair Ethernet cabling is bifurcating the harness market between high-speed data zones and legacy power distribution segments. Autonomous driving module suppliers are specifying multi-gigabit backbone capacity for camera and lidar sensor fusion. The technology is compressing the addressable market for traditional unshielded copper harnesses while expanding requirements for precision impedance control and connector shielding.
EU Cyber Resilience Act implementation timelines are forcing Tier-1 suppliers to restructure documentation practices and vulnerability management workflows. The regulation mandates software bill of materials disclosure and coordinated vulnerability disclosure for vehicle network components. European OEMs are advancing supplier qualification deadlines by 12-18 months to secure certification buffer.
Automotive electrical engineering procurement is consolidating supplier relationships around full-stack architecture capability rather than component commoditization. OEM technical sourcing teams are awarding zonal platform contracts to suppliers with in-house semiconductor packaging and embedded software development. Germany and Japan exhibit the most pronounced concentration of qualified bidders for integrated zone controller programs.
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market Segmentation
Zonal wiring harness platforms fragment across multiple technical dimensions that determine procurement channels, certification requirements, and supplier qualification criteria. Understanding how these segments interlock reveals where OEMs concentrate specification authority and where Tier-1 suppliers retain design autonomy.
Product Type:
Channel distribution varies sharply by harness complexity—high-speed and fiber optic variants flow through direct OEM partnerships with integrated architecture suppliers, while power distribution and low-voltage harnesses route through Tier-1 aggregators serving multiple vehicle programs.
- High-Speed Wiring Harness:Multi-gigabit shielded twisted-pair assemblies with precision impedance control for camera and lidar sensor fusion. Demand concentrates in Germany where Bosch and Continental anchor autonomous driving module supply chains, constrained by electromagnetic compatibility validation bottlenecks.
- Fiber Optic Harness:Deterministic latency optical backbones immune to electromagnetic interference for brake-by-wire and steer-by-wire safety systems. Expansion concentrates in Japanese OEM programs where electromagnetic immunity requirements for autonomous emergency braking exceed regional mandates.
- Low-Voltage Wiring Harness:Consolidated 12V power feeds for legacy lighting and HVAC subsystems.
- Coaxial Harness:Shielded single-conductor assemblies for RF signal transmission in vehicle-to-everything modules.
- Power Distribution Harness:48V-to-12V hybrid rails with intelligent fuse replacement for mild-hybrid architectures.
High-Speed Wiring Harness dominates installed base. Fiber Optic Harness is where expansion concentrates.
Technology:
Cost tier stratification separates premium Ethernet and FlexRay implementations from economy LIN Bus deployments, with technology selection locking in semiconductor partner ecosystems and validation pathway costs.
- Ethernet:Multi-gigabit switched backbones with IEEE 802.3ch compliance for zonal compute zones and over-the-air update infrastructure. Specification authority concentrates with German OEMs advancing 10Gbps+ camera fusion requirements under EU Cyber Resilience Act timelines.
- FlexRay:Time-triggered deterministic bus architecture for powertrain and chassis control with sub-microsecond latency guarantees. Demand persists in Stuttgart and Munich engineering centers developing steer-by-wire systems where deterministic timing exceeds Ethernet capabilities.
- CAN Bus:Controller area network for legacy body electronics and diagnostic interfaces.
- LIN Bus:Low-cost single-wire protocol for door modules and seat controls.
- MOST Bus:Media-oriented systems transport for infotainment backbone applications.
- BroadR-Reach:Single-pair Ethernet variant for unshielded cost-sensitive camera links.
CAN Bus retains volume leadership in production programs. Ethernet is climbing the fastest as zonal architectures displace domain controllers.
Application:
Application segmentation tracks customer type divergence—safety systems and autonomous driving modules demand direct OEM-supplier engineering relationships, while infotainment and vehicle communication networks route through Tier-1 system integrators.
- Autonomous Driving Modules:Redundant power and data distribution for sensor fusion computers with ASIL-D functional safety requirements. Engineering resources concentrate in California and Bavaria where NHTSA guidelines and EU AI Act compliance create parallel validation pathways.
- Safety Systems:Deterministic harness segments for brake-by-wire, steer-by-wire, and occupant protection with fault-tolerant architectures. Procurement concentrates with Japanese suppliers integrating fiber optic immunity for electromagnetic compatibility-critical functions.
- Electrical Distribution:Consolidated zone power management replacing discrete fuse boxes.
- Data Transmission:Inter-zone backbone capacity for software-defined vehicle updates.
- Infotainment Controls:High-bandwidth consumer electronics interfaces.
- Vehicle Communication Networks:V2X spectrum-compliant harnessing for connected infrastructure.
Electrical Distribution commands specification authority. Autonomous Driving Modules represent the steepest expansion trajectory.
End User:
Volume concentration separates captive OEM assembly plants from independent Tier-1 suppliers, with aftermarket providers occupying a narrow retrofit niche constrained by zonal architecture software dependency.
- Original Equipment Manufacturers:Direct specification of integrated zonal platforms with semiconductor packaging and embedded software requirements. Volkswagen Group, BMW, and Mercedes-Benz anchor demand in Germany with 18-24 month supplier qualification timelines.
- Tier-1 Suppliers:Modular harness assembly for OEMs lacking in-house architecture capability, with Aptiv and Yazaki capturing specification influence through full-stack integration.
- Vehicle Assembly Plants:Final integration and testing of pre-validated zonal modules.
- Aftermarket Providers:Limited retrofit scope due to software-defined power distribution dependencies.
Original Equipment Manufacturers control architecture decisions. Tier-1 Suppliers is where manufacturing scale concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes zonal wiring harness platforms as integrated architecture solutions with semiconductor packaging requirements, while India treats them as localization opportunities for export manufacturing. Japan prioritizes fiber optic safety backbones for electromagnetic immunity. The United States concentrates specification authority with California autonomous driving developers.
Germany
EU AI Act compliance deadlines and 48V mild-hybrid powertrain proliferation drive zonal platform demand. KBA vehicle type approval mandates ISO 26262 ASIL-D certification for autonomous functions. Stuttgart and Munich engineering clusters anchor Continental and Robert Bosch development centers for next-generation zone controllers.
United States
NHTSA cybersecurity guidelines and FCC V2X spectrum allocation accelerate high-speed Ethernet backbone deployment. California autonomous driving module suppliers specify multi-gigabit harness capacity for sensor fusion. Michigan and Texas assembly plants integrate zonal architectures from Aptiv and TE Connectivity supply relationships.
Japan
METI carbon neutrality targets and autonomous emergency braking mandates propel fiber optic harness adoption for deterministic latency. JIS standards govern electromagnetic compatibility validation for steer-by-wire safety systems. Toyota City and Hiroshima engineering centers concentrate Yazaki Corporation and Denso Corporation manufacturing scale.
China
MIIT intelligent vehicle development guidelines and dual carbon goals drive zonal architecture localization. GB standards mandate cybersecurity conformity assessment for connected vehicle networks. Yangtze River Delta and Pearl River Delta clusters host Sumitomo Electric Industries joint ventures for domestic OEM supply.
India
PLI scheme automotive component incentives and phased domestic content requirements attract zonal harness assembly investment. BIS certification timelines compress supplier qualification for export market access. Tamil Nadu and Maharashtra manufacturing corridors localize Tier-1 supplier modules for European and North American OEM programs.
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Tier-1 suppliers with captive semiconductor packaging and automated harness assembly capabilities capture specification influence through full-stack integration. Strategic archetypes include architecture-integrated conglomerates, connector-specialist manufacturers, and regional-scale assemblers. Dominant competitive moves center on backward integration into semiconductor packaging and geographic expansion through joint ventures in India and China.
Among Germany-based conglomerates, Continental and Robert Bosch exemplify the architecture-integrated archetype through breadth of sensor and actuator portfolios. Aptiv represents the North American full-stack specialist with vehicle architecture capability spanning embedded software development. Yazaki Corporation anchors the Asian manufacturing scale archetype through connector and harness assembly relationships with domestic OEMs.
| Leading Market Players |
|---|
| Aptiv |
| Leoni |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| TE Connectivity |
| Robert Bosch |
| Continental |
| Denso Corporation |
| ZF Friedrichshafen |
| Others |
Pricing and Supply Chain Analysis
ISO 26262 ASIL-D certification gates both supplier qualification timelines and price differentiation across zonal harness tiers, compressing margins for uncertified assemblers while embedding safety-grade premiums into Ethernet backbone contracts. OEM procurement teams exploit this bifurcation to extract volume discounts from commodity power distribution harnesses while paying structural premiums for deterministic latency guarantees in autonomous driving modules.
Pricing Analysis
Long-term offtake agreements dominate zonal platform procurement, with Volkswagen Group and BMW locking 18-24 month supplier contracts that bundle semiconductor packaging with harness assembly. Price differentiation stratifies across ASIL certification grade and copper alloy purity specifications, with OEMs least sensitive to unit cost in safety-critical steer-by-wire segments and most price-sensitive in consolidated 12V legacy lighting feeds. Cost compression in low-voltage harness tiers is intensifying because Indian manufacturing corridors are localizing assembly for export programs.
Supply Chain Analysis
Inventory lead times for precision-stamped Ethernet connectors now stretch 14-20 weeks, reflecting German and Japanese supplier capacity constraints against accelerating zonal architecture adoption. Manufacturing gravity centers on Germany, China, and Mexico, with raw material dependencies spanning high-conductivity copper rod, fluoropolymer insulation compounds, and semiconductor-grade epoxy molding compounds. Single-source vulnerability concentrates in shielded twisted-pair plating capacity anchored in Stuttgart and Nagoya engineering clusters. Distribution runs through Tier-1 aggregators for modular harness assembly and direct OEM partnerships for integrated zone controller programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The zonal wiring harness market represents a high-growth disruption as 48V-to-12V hybrid architectures and EU AI Act compliance deadlines force simultaneous electrical and software architectural redesign across passenger vehicle programs.
For Market Incumbents: Consolidate specification influence by embedding semiconductor packaging capabilities in-house, capturing zone controller contracts that bundle power distribution with embedded diagnostics. Aptiv and Continental exemplify this defensive posture, using full-stack integration to repel modular harness assemblers from high-margin autonomous driving module supply. Capacity addition in Tamil Nadu and Maharashtra manufacturing corridors secures qualification buffers for European OEM export programs. For New Entrants and Emerging Players: Aftermarket diagnostic service gaps where incumbents under-serve fleet operators present white-space entry points for subscription-based remote harness health monitoring. Target India's domestic OEM joint ventures with localized zonal architecture development partnerships, leveraging PLI scheme incentives to offset ASIL-D certification investment. Fiber optic safety backbone integration for brake-by-wire applications offers the most penetrable technology segment given Japanese OEM electromagnetic immunity requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Ethernet backbone segments as multi-gigabit impedance control equipment and automated optical inspection systems displace legacy harness assembly lines. Acquisition targets should prioritize Tier-1 suppliers with captive semiconductor packaging and established KBA type approval relationships in Stuttgart engineering clusters. Monitor FCC V2X spectrum rulemaking timelines as the critical inflection signal for North American high-speed harness demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Packaging | Captures zone controller margin pools from modular harness assemblers in German OEM supply chains. |
| Fiber Optic Safety Backbone Development | Addresses METI electromagnetic immunity mandates for autonomous emergency braking in Japanese vehicle programs. |
| India Manufacturing Localization | Aligns with PLI scheme incentives and phased domestic content requirements for European export access. |
| Ethernet Impedance Control Certification | Secures 10Gbps+ camera fusion specifications under EU Cyber Resilience Act documentation timelines. |
| Over-the-Air Update Infrastructure Partnership | Enables subscription-based feature activation through software-defined power distribution platforms. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement directors, semiconductor packaging specialists, and KBA type approval consultants anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, IHS Markit vehicle production databases, EU Cyber Resilience Act implementation guidance, and MIIT intelligent vehicle development guidelines. Bottom-up segment sizing triangulated with top-down OEM zonal architecture adoption forecasts.
Sensitivity analysis framed the quantitative modeling, with segmentation dimensions spanning harness product type, communication protocol technology, vehicle application, and end-user procurement channel across the projection horizon. CAGRs derived from vehicle production ramp assumptions, content-per-vehicle trajectories for Ethernet backbone penetration, and regional regulatory compliance deadline clustering. Forecast inputs incorporated ASIL-D certification timeline distributions and copper mass reduction target commitments from major OEM sustainability programs.
Material uncertainties — EU AI Act enforcement variance, NHTSA cybersecurity guideline finalization, and single-source connector supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about zonal architecture adoption curves and supplier qualification pipeline velocities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market