
 Automotive Control Cable Market | 2026-2036
Automotive Control Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Control Cable Market Analysis
IATF 16949 certification is reorganizing supplier hierarchies across the automotive control cable landscape, forcing tier-two manufacturers to upgrade quality systems or exit OEM supply pools. Küster sustains its European manufacturing footprint through precision-engineered cable solutions for premium passenger car platforms. Suprajit Engineering dominates India's two-wheeler and three-wheeler cable segments through extensive backward integration into wire drawing and die-casting operations. Hi-Lex leverages its Japanese technology base to anchor supply relationships with transnational OEMs seeking consistent torque-transmission performance across multiple vehicle programs.
An automotive control cable is a mechanical linkage assembly comprising a stranded steel inner wire, polymer or rubber protective conduit, and precision end fittings, engineered to transmit tensile force between a driver-operated control and an actuated subsystem such as a transmission selector or throttle body. Brake cables and clutch cables incorporate higher-strength wire grades and enhanced corrosion coatings to withstand cyclic loading and environmental exposure in underbody mounting positions. Transmission cables represent the most technically demanding product category, where pull-to-push ratio consistency and low hysteresis directly influence shift quality perceptions in manual and automated manual transmissions. Electric vehicles are emerging as the fastest-growing vehicle type segment, though throttle cable demand is contracting as electronic throttle control architectures displace mechanical linkages in battery-electric powertrains.
China's SAMR enforces GB standards for automotive cable durability and fire resistance, while India's BIS mandates specific tensile strength and fatigue life thresholds under the AIS regulatory framework for vehicle components. The EU's REACH regulation restricts certain phthalate plasticizers in cable jacket compounds, compelling reformulation of PVC and rubber conduit materials across export-oriented suppliers. EPA corrosion-resistance guidelines in the United States shape salt-spray test protocols that determine warranty qualification for underbody cable routing. Stakeholders must monitor the pace of electronic control displacement versus residual mechanical linkage demand as OEMs calibrate cost-versus-reliability trade-offs across hybrid and fully electric vehicle architectures.
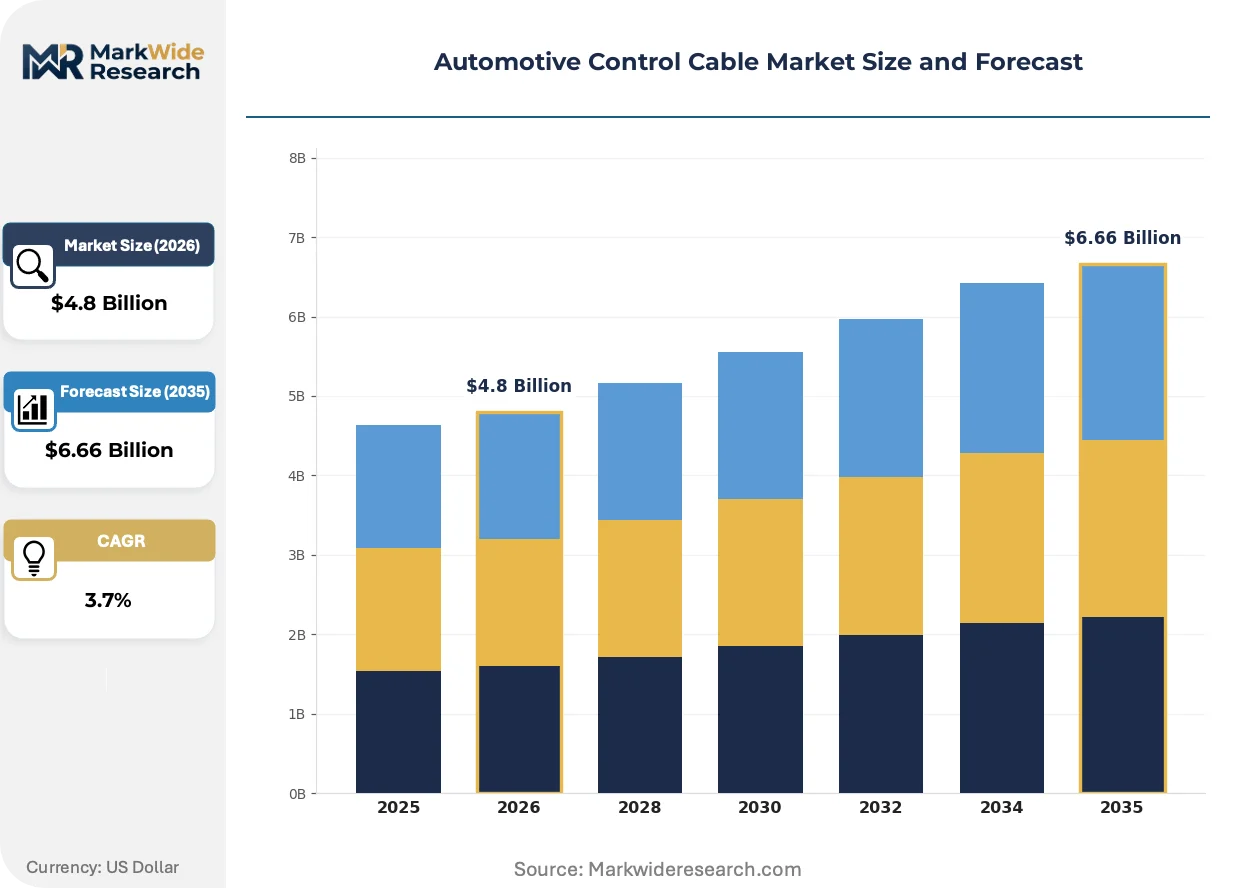
Market Dynamics
Drivetrain electrification is compressing mechanical linkage demand while simultaneously creating specialized cable requirements for hybrid architectures and remaining manual control interfaces in electric vehicles.
Growth Catalysts
- GB Standards Modernization:China's SAMR mandates for fire-resistant cable materials are accelerating lightweighting R&D programs among domestic suppliers seeking OEM qualification.
- Two-Wheeler Production Scaling:Tamil Nadu and Gujarat-based manufacturers are expanding clutch and brake cable procurement for entry-level motorcycle exports to Southeast Asian markets.
- Hybrid Powertrain Complexity:Dual-clutch and automated manual transmissions in plug-in hybrids require precision transmission cables with enhanced pull-to-push ratio consistency.
Market Restraints
- Steel Wire Price Volatility:High-carbon steel rod input costs fluctuate with scrap metal and energy pricing, compressing margin predictability for stranded wire manufacturers.
- Electronic Throttle Displacement:Drive-by-wire architectures in battery-electric vehicles are eliminating accelerator cable demand across premium passenger car segments.
- REACH Compliance Burden:ECHA restrictions on phthalate plasticizers force PVC conduit reformulation, adding certification costs for export-oriented European suppliers.
Strategic Opportunities
- India's Automotive Belt Expansion:Tier-two cable assemblers can capture share in Haryana and Maharashtra as OEMs diversify beyond Tamil Nadu and Gujarat production clusters.
- Aftermarket Channel Digitization:E-commerce platforms for replacement brake and clutch cables are disintermediating traditional distributor networks in price-sensitive segments.
- MIIT Dual Carbon Alignment:China's lightweighting mandates create openings for aluminum-core and polymer-composite cable architectures in domestic EV programs.
Industry Challenges
- IATF 16949 Certification Timeline:Tier-two suppliers face 12-18 month quality system overhauls to maintain OEM supply pool eligibility as certification requirements tighten.
- Legacy System Integration:Cable manufacturers serving hybrid platforms must engineer mechanical linkages that interface with electronic control modules without compromising tactile feedback.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Control Cable Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission Cables, Brake Cables, Throttle Cables, Clutch Cables Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Electric Vehicles Material: Steel, Nylon, PVC, Rubber Application: Steering Control, Brake Control, Gear Shift, Throttle Control |
| Companies Covered | Dura Automotive Systems, Küster, Hi-Lex, Chuo Spring, TSC, Suprajit Engineering, Ficosa International, Atsumitec, Minda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Control Cable Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape cable construction methods, while procurement digitization is compressing traditional distribution hierarchies.
Polymer-composite conduit materials are replacing conventional PVC and rubber jackets in underbody routing applications where weight reduction and temperature resistance prove critical. Tier-one suppliers serving European premium platforms are adopting these compounds fastest, with qualification cycles compressing from 36 months to 24 months. This substitution is miniaturizing cable assembly cross-sections while maintaining tensile load capacity.
REACH Annex XVII restrictions on phthalate plasticizers are compelling reformulation of jacket compounds across export-oriented suppliers serving EU markets. ECHA enforcement actions have intensified testing documentation requirements, with non-compliance penalties now including market withdrawal provisions. Brake cable categories face the steepest compliance costs due to their larger jacket surface area and underbody heat exposure profiles.
Direct procurement relationships between OEM engineering teams and specialized cable assemblers are displacing traditional tier-one distributor intermediaries in specification-heavy transmission cable categories. This disintermediation concentrates volume with IATF-certified manufacturers capable of co-development programs. The pattern is most visible in Japanese and Korean OEM supply chains, where torque-transmission consistency requirements demand early-stage design collaboration.
Automotive Control Cable Market Segmentation
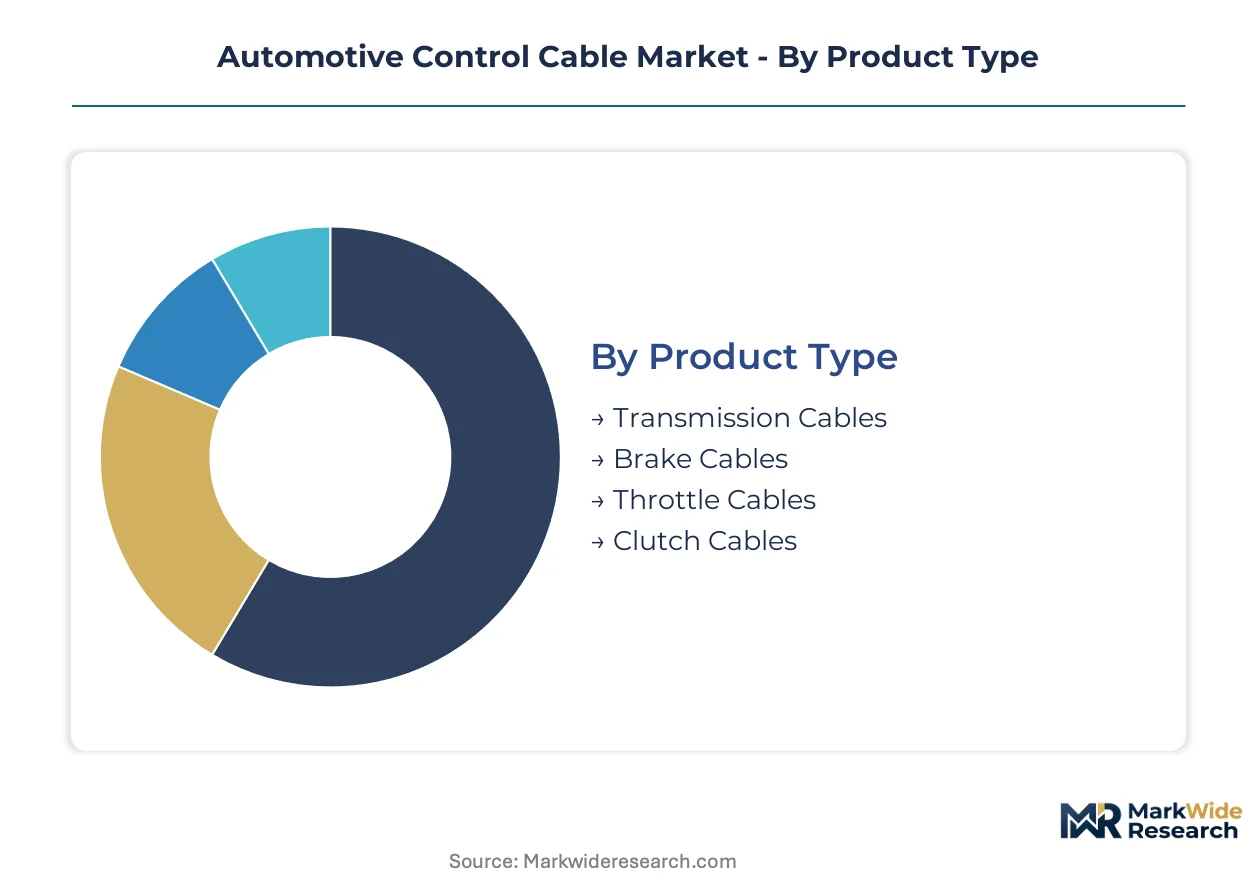
Control cable procurement patterns diverge sharply across product architectures, with transmission and brake categories commanding premium qualification cycles while throttle demand contracts under electronic displacement. Material selection and application specificity further stratify supplier capabilities, as OEMs calibrate cost-reliability trade-offs across hybrid and electric vehicle programs.
Product Type:
China's SAMR enforces divergent GB standards across product categories, with fire-resistance mandates tightening fastest for underbody-mounted brake and clutch assemblies.
- Transmission Cables:These assemblies demand precision-engineered pull-to-push ratio consistency and minimal hysteresis to preserve shift quality perception in manual and automated manual transmissions. Dual-clutch hybrid architectures in German and Japanese OEM programs are concentrating procurement with IATF-certified specialists capable of co-development partnerships. Established volume favors transmission cables; emerging adoption favors brake cables as EV regenerative systems create residual mechanical backup requirements.
- Brake Cables:Higher-strength wire grades and enhanced corrosion coatings distinguish this category for cyclic loading endurance in underbody mounting positions. India's BIS mandates specific tensile strength thresholds under AIS regulations, accelerating qualification timelines for Tamil Nadu and Gujarat-based suppliers serving two-wheeler export markets. Established volume favors brake cables; emerging adoption favors clutch cables as entry-level motorcycle production scales across Southeast Asian markets.
- Throttle Cables:Electronic throttle control architectures in battery-electric powertrains are compressing mechanical linkage demand across premium passenger car segments, though residual demand persists in hybrid manual override interfaces and commercial vehicle cost-optimized platforms.
- Clutch Cables:Entry-level motorcycle and three-wheeler manufacturers in India anchor volume procurement, with Haryana and Maharashtra production clusters emerging as secondary demand centers beyond the established Tamil Nadu and Gujarat belt.
Established volume favors transmission cables; emerging adoption favors brake cables as EV regenerative systems create residual mechanical backup requirements.
Vehicle Type:
Cost tier stratification separates premium passenger car platforms demanding torque-transmission consistency from price-sensitive two-wheeler segments prioritizing procurement scale.
- Passenger Cars:Precision transmission cable specifications dominate procurement, with Japanese and Korean OEMs favoring direct engineering relationships over tier-one distributor intermediaries for specification-heavy categories. Manual transmission retention in European entry-level platforms sustains mechanical linkage demand against electronic displacement trends.
- Commercial Vehicles:Throttle and brake cable architectures persist in cost-optimized heavy-duty platforms where drive-by-wire adoption lags passenger car electrification timelines, particularly in Indian and Southeast Asian freight markets.
- Two-Wheelers:Clutch and brake cable procurement concentrates in India's automotive belt, where Tamil Nadu and Gujarat-based OEMs scale production for Southeast Asian export markets. BIS fatigue life thresholds under AIS regulations shape supplier qualification.
- Electric Vehicles:This category climbs the fastest as specialized cable requirements emerge for hybrid powertrain mechanical interfaces and remaining manual control linkages, even as pure battery-electric architectures eliminate traditional throttle cables. China's MIIT dual carbon goals accelerate lightweighting R&D for aluminum-core and polymer-composite architectures.
Volume concentration favors two-wheelers; technology premium favors electric vehicles as drivetrain electrification reshapes mechanical linkage specifications.
Material:
Supply concentration in high-carbon steel rod production exposes stranded wire manufacturers to scrap metal and energy pricing volatility, compressing margin predictability.
- Steel:Stranded high-carbon wire dominates tensile load transmission, with corrosion coating specifications varying by underbody exposure requirements and EPA salt-spray test protocols for US warranty qualification.
- Nylon:Polymer-composite conduit materials are displacing conventional jackets in underbody routing where weight reduction and temperature resistance prove critical, with European premium platform qualification cycles compressing from 36 months to 24 months.
- PVC:REACH Annex XVII phthalate plasticizer restrictions compel reformulation across export-oriented suppliers serving EU markets, with brake cable categories facing steepest compliance costs due to larger jacket surface area.
- Rubber:Enhanced temperature resistance specifications apply to transmission cable categories where underbody heat exposure profiles demand material durability beyond standard PVC compounds.
Established supply favors steel; regulatory pressure favors nylon as ECHA enforcement intensifies documentation requirements for legacy polymer formulations.
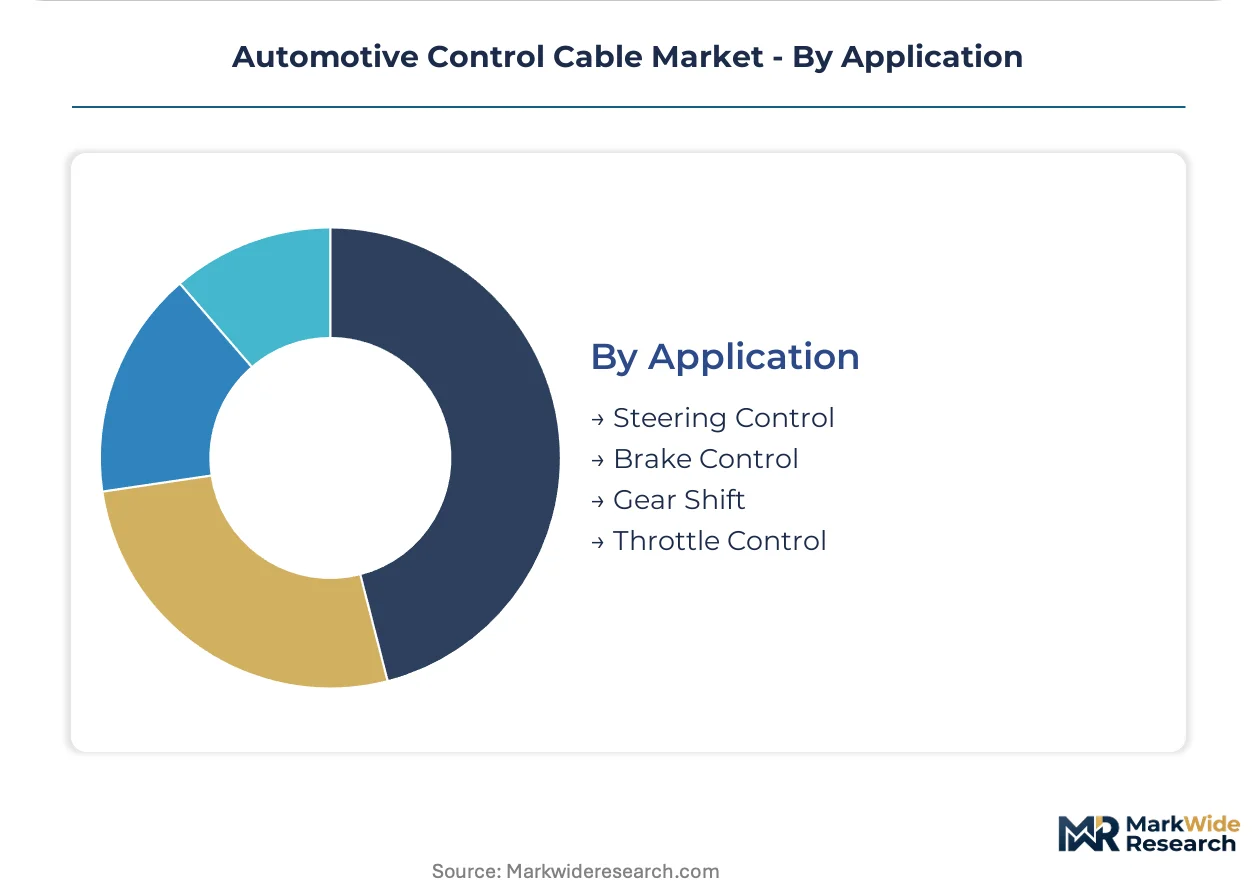
Application:
Customer type differentiation separates OEM engineering co-development programs from aftermarket channel digitization in replacement brake and clutch cable procurement.
- Steering Control:Precision end-fitting engineering and stranded wire torque transmission characteristics define specifications for column-mounted control interfaces in passenger car and commercial vehicle platforms.
- Brake Control:Cyclic loading endurance and corrosion resistance specifications concentrate procurement with suppliers capable of BIS and EPA dual-qualification testing for underbody routing positions.
- Gear Shift:Manual and automated manual transmission architectures demand pull-to-push ratio consistency where tactile feedback directly influences driver quality perception, favoring early-stage OEM engineering collaboration.
- Throttle Control:Electronic displacement in battery-electric powertrains is eliminating mechanical linkage demand across premium segments, though hybrid manual override interfaces and commercial vehicle cost optimization sustain residual procurement.
Specification intensity favors gear shift; volume scale favors brake control as two-wheeler and entry-level passenger car production concentrates in India's automotive belt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT dual carbon mandates and India's PLI scheme for automotive components are redirecting procurement flows toward lightweight cable architectures and localized supply chains. Germany's KBA enforces stringent durability protocols for underbody-mounted assemblies. The United States EPA corrosion-resistance guidelines shape warranty qualification timelines for salt-spray testing protocols.
China
Domestic OEMs are scaling aluminum-core and polymer-composite cable procurement for battery-electric platforms under MIIT lightweighting mandates. SAMR enforces updated GB standards for fire-resistant materials in underbody routing applications. Yangtze River Delta suppliers in Jiangsu and Zhejiang provinces are upgrading die-casting and wire-drawing capacity to capture tier-one qualification.
India
Tamil Nadu and Gujarat-based two-wheeler manufacturers are expanding clutch and brake cable orders for Southeast Asian export markets. BIS mandates specific tensile strength and fatigue life thresholds under AIS regulations for vehicle components. Haryana and Maharashtra production clusters are emerging as secondary demand centers as OEMs diversify beyond the established southern belt.
Germany
Premium passenger car platforms demand precision transmission cables with pull-to-push ratio consistency for dual-clutch hybrid architectures. KBA durability protocols and ECHA REACH restrictions on phthalate plasticizers compel PVC conduit reformulation. Bavaria and Baden-Württemberg engineering centers coordinate directly with IATF-certified assemblers for specification-heavy categories.
United States
Commercial vehicle cost-optimization sustains mechanical throttle and brake cable demand as drive-by-wire adoption lags passenger car electrification timelines. EPA salt-spray test protocols determine warranty qualification for underbody cable routing. Midwest manufacturing corridors in Michigan and Ohio retain stamping and assembly operations for heavy-duty freight platforms.
Japan
Transnational OEM supply chains anchor procurement relationships with torque-transmission specialists capable of co-development programs. METI technology standards influence precision cable specifications across hybrid powertrain architectures. Kanto and Chubu regional suppliers maintain direct engineering collaboration with platform development teams.
Automotive Control Cable Market Vendor Landscape
Player mix skews toward vertically integrated specialists and precision-engineering houses with IATF certification. Tier-one concentration is moderate, with tier-two suppliers facing quality system overhauls to maintain OEM pool eligibility. Dominant archetypes include backward-integrated wire manufacturers, precision conduit specialists, and transmission-focused engineering partners. Competitive moves center on certification acquisition and direct OEM engineering relationships.
Among precision-engineering houses, Küster and Hi-Lex exemplify the torque-transmission specialist archetype, while Suprajit Engineering represents backward-integrated volume players with captive wire-drawing operations. These three companies occupy distinct positioning vectors: European premium-platform focus, Japanese technology-base anchoring, and Indian two-wheeler scale dominance respectively.
| Leading Market Players |
|---|
| Dura Automotive Systems |
| Küster |
| Hi-Lex |
| Chuo Spring |
| TSC |
| Suprajit Engineering |
| Ficosa International |
| Atsumitec |
| Minda |
| Others |
Supply Flow & Price Mechanics
Polymer-composite conduit substitution for PVC and rubber jackets is redrawing supplier geography toward Yangtze River Delta engineering clusters while compressing qualification-cycle premiums that once sustained European margin tiers. This material transition simultaneously concentrates procurement leverage with IATF-certified assemblers capable of accelerated 24-month validation timelines and fragments legacy jacket compounders facing REACH-driven reformulation cost burdens.
Pricing Analysis
Certification level (IATF 16949-grade) creates the primary spread between premium transmission cable tiers and commodity brake and clutch categories. Three-tier pricing structure across premium, standard, and economy levels reflects pull-to-push ratio precision, corrosion coating specifications, and direct OEM engineering access. Cost compression in standard-tier steel-wire categories is intensifying because scrap metal and energy volatility erode margin buffers for stranded wire manufacturers. Two-wheeler OEMs in India's automotive belt exhibit highest price sensitivity; German premium passenger car platforms prioritize torque-transmission consistency over unit cost.
Supply Chain Analysis
Just-in-time inventory protocols dominate OEM supply relationships for transmission cables where specification-heavy co-development demands precise delivery synchronization. Supply concentrates in China, India, and Germany for die-casting, wire-drawing, and precision end-fitting operations respectively. High-carbon steel rod, polymer-composite compounds, and corrosion-resistant coatings constitute critical input dependencies. Single-source vulnerability pervades Yangtze River Delta polymer-conduit qualification where accelerated OEM approval timelines restrict dual-sourcing flexibility. Distribution runs through tier-one assemblers for passenger car platforms and direct procurement channels for specification-heavy transmission categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where IATF 16949 certification timelines and OEM co-development relationships erect switching-cost barriers against unqualified challengers. The defensive moat deepens as dual-clutch hybrid architectures proliferate and torque-transmission consistency requirements tighten.
For Market Incumbents: Compound certification advantages by accelerating aluminum-core and polymer-composite R&D programs under China's MIIT lightweighting mandates. Deepen backward integration into wire-drawing operations to buffer steel rod volatility. Electronic throttle displacement in battery-electric platforms threatens clutch and accelerator cable volumes; defend position through transmission cable specialization for hybrid powertrains and brake cable residual demand from regenerative backup systems. For New Entrants and Emerging Players: Aftermarket channel digitization gaps expose white-space opportunities where traditional distributor networks fragment under e-commerce price transparency. Target Haryana and Maharashtra production clusters as OEMs diversify beyond Tamil Nadu and Gujarat; these secondary demand centers lack entrenched supplier relationships. Pursue BIS qualification under AIS fatigue life thresholds as the go-to-market anchor for two-wheeler export procurement. For Investors and Strategic Acquirers: Capital is best deployed toward IATF-certified specialists with captive die-casting capacity and demonstrated OEM co-development track records. The 5-10 year viability window favors backward-integrated assemblers capable of polymer-conduit qualification compression. Watch electronic control displacement pace versus residual mechanical linkage demand in hybrid architectures as the inflection signal; acceleration of drive-by-wire adoption beyond current OEM roadmaps would compress transmission cable premium tiers.| Strategic Initiative | Industry Significance |
|---|---|
| IATF 16949 Certification Acquisition | Quality system overhaul unlocks tier-one OEM supply pool eligibility and co-development partnerships. |
| Polymer-Composite Conduit Qualification | Lightweighting compliance with MIIT dual carbon goals secures domestic EV platform procurement. |
| Backward Integration into Wire Drawing | Captive steel rod processing buffers margin compression from scrap metal and energy volatility. |
| Aftermarket Channel Digitization | E-commerce platform investment disintermediates traditional distributors in price-sensitive replacement segments. |
| Geographic Expansion to Secondary Clusters | Haryana and Maharashtra capacity placement captures OEM diversification from Tamil Nadu and Gujarat. |
Methodological Framework
Desk research of regulatory filings (SAMR GB standards, BIS AIS regulations, ECHA REACH annexes), trade association publications, and vehicle production databases preceded structured interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and die-casting facility managers. Primary fieldwork across Jiangsu, Tamil Nadu, and Bavaria manufacturing clusters validated secondary demand estimates. Bottom-up cable assembly volume estimates triangulated against top-down vehicle production forecasts.
Variance decomposition across vehicle type, product category, material specification, and regional production cluster shaped the analytical framework. Modeled dimensions included propulsion architecture, content per vehicle by transmission type, OEM tier positioning, and regional regulatory stringency. CAGRs derived from segmented volume projections weighted by average selling price evolution across the projection horizon. Hybrid powertrain penetration assumptions and electronic control displacement curves constituted critical automotive-specific forecast inputs.
Forecasts assume regulatory continuity in China's MIIT enforcement, India's PLI scheme extension, and EU REACH phthalate restrictions; material policy shifts would require re-modeling. Steel rod commodity volatility, IATF certification timeline compression, and electronic throttle adoption acceleration represent specific risk factors. Revision becomes warranted when battery-electric vehicle share crosses thresholds that eliminate residual mechanical throttle demand in commercial vehicle segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Smart Key Market