
 In-Flight Entertainment and Connectivity Market | 2026-2036
In-Flight Entertainment and Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
In-Flight Entertainment and Connectivity Market Intelligence
FAA airworthiness criteria for Ku- and Ka-band satellite installations is hardening the cost-of-entry calculus for hardware vendors. Panasonic Avionics Corporation leverages its vertically integrated antenna-to-screen ecosystem to sustain premium positioning on widebody platforms. Thales Group anchors European supply security through sovereign manufacturing lines in France and certification alignment with EASA. Collins Aerospace competes on the strength of its factory-installed OEM relationships with Boeing and Airbus.
In-flight entertainment and connectivity denotes the integrated suite of hardware, software, and network services that deliver audio-visual content, internet access, and real-time communications to aircraft occupants during flight, typically operating across L-band, Ku-band, Ka-band, and now low-earth orbit satellite frequencies at altitudes above 10,000 feet. The primary commercial purpose centers on passenger experience differentiation, ancillary revenue generation through paid Wi-Fi tiers, and operational data offload for crew and maintenance applications. Satellite connectivity leads installed value due to capital-intensive terminal and radome requirements, while in-flight streaming represents the fastest-expanding segment as airlines shift from seatback screens to bring-your-own-device architectures that reduce weight and simplify maintenance. Wireless systems occupy a maturing but stable position in regional and short-haul fleets where bandwidth economics favor air-to-ground links over satellite.
FAA certification timelines, EASA's continued airworthiness directives for electromagnetic interference, and the EU's Cyber Resilience Act collectively shape product development cycles, testing budgets, and market access conditions for system integrators. The FCC's spectrum allocation proceedings for inflight 5G will determine whether terrestrial network architectures can challenge satellite incumbents on domestic routes. Stakeholders must monitor regulatory divergence between Washington and Brussels on cybersecurity disclosure requirements, as this will force dual-compliance investments or geographic product variants.
Market Dynamics
Retrofit cycles for narrowbody fleets are compressing as airlines prioritize streaming-centric architectures over legacy seatback systems, forcing hardware vendors to recalibrate certification timelines and supply commitments.
Growth Catalysts
- Domestic carrier fleet upgrades in China:Narrowbody retrofit programs are accelerating as carriers pursue connected cabin differentiation on high-traffic domestic routes.
- FAA antenna certification pathways:Updated airworthiness criteria for Ku- and Ka-band satellite installations are streamlining hardware approval processes for qualified vendors.
- LEO satellite constellation deployment:Low-earth orbit networks are expanding bandwidth availability and reducing latency constraints for transoceanic connectivity.
Market Restraints
- Radome and terminal capital intensity:Satellite connectivity hardware requires substantial upfront investment in certified antenna systems and aerodynamic enclosures.
- Electromagnetic interference compliance:EASA continued airworthiness directives impose rigorous testing protocols that extend product development cycles.
- Air-to-ground substitution on short-haul:Terrestrial network architectures challenge satellite economics on domestic routes where 5G spectrum allocation proceeds.
Strategic Opportunities
- Bring-your-own-device penetration:Streaming-centric cabin architectures reduce weight and maintenance burden while opening ancillary revenue tiers.
- Operational data offload services:Crew and maintenance applications create secondary revenue streams beyond passenger connectivity.
- EU Cyber Resilience Act alignment:Early compliance with cybersecurity disclosure requirements positions vendors for streamlined market access.
Industry Challenges
- Dual-compliance investment burden:Divergent cybersecurity disclosure requirements between Washington and Brussels force geographic product variants or redundant certification paths.
- Legacy seatback system integration:Mixed fleet environments complicate maintenance logistics and crew training standardization.
- Specialized avionics certification talent:FAA and EASA qualification pathways require scarce engineering expertise that concentrates among incumbent vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Flight Entertainment and Connectivity Market |
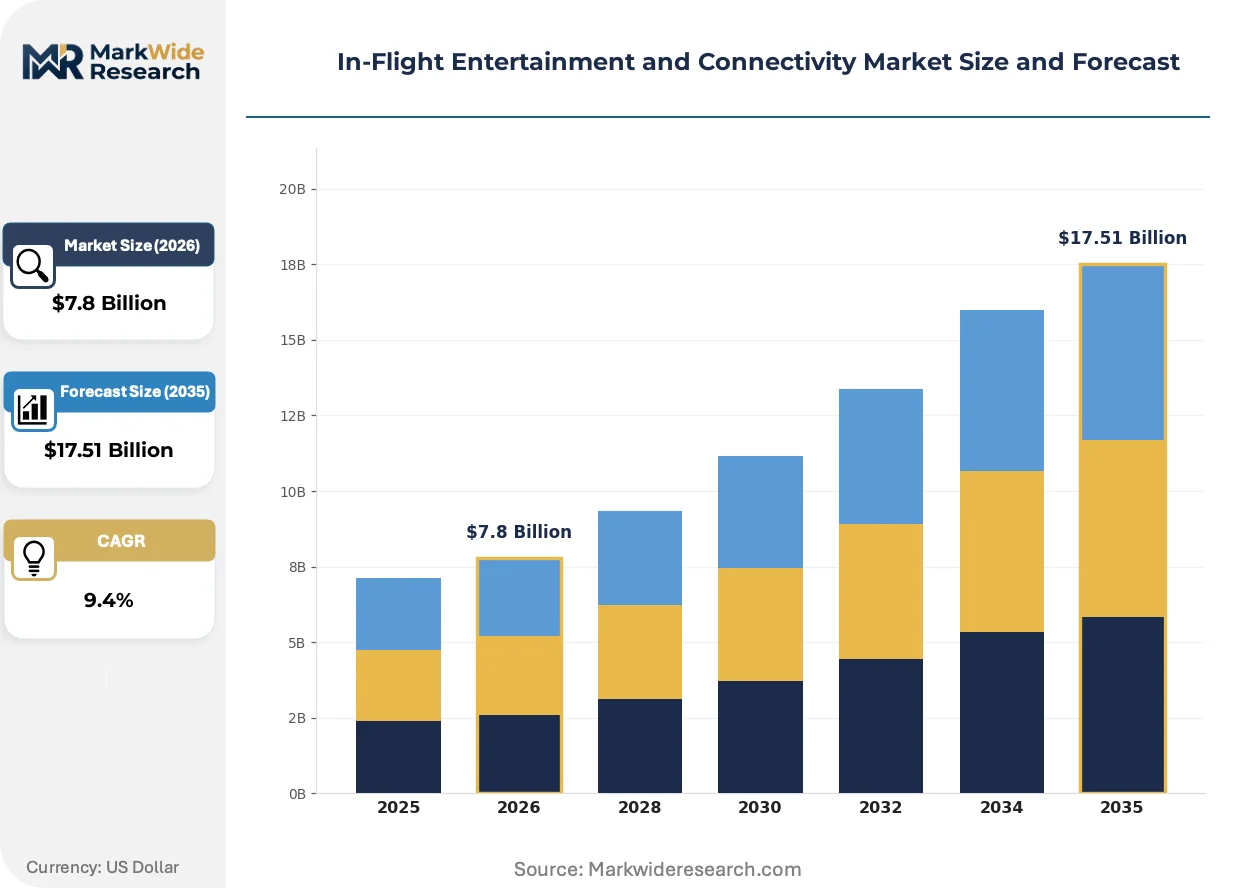
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Systems, In-Flight Streaming, Satellite Connectivity, Cabin Equipment End User: Commercial Airlines, Private Jets, Military, Charter Services Technology: Wi-Fi, Bluetooth, Satellite, 5G Service Type: Content Management, Technical Support, Installation, Maintenance |
| Companies Covered | Panasonic Avionics Corporation, Thales Group, Collins Aerospace, Anuvu, Astronics Corporation, Viasat Inc., Gogo LLC, Burrana Pty Ltd, Lufthansa Systems GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Flight Entertainment and Connectivity Market Strategic Shifts & Innovations
Connectivity architectures are pivoting from hardware-heavy seatback ecosystems toward software-defined streaming platforms that leverage passenger-owned devices and cloud-based content delivery.
Artificial intelligence-driven predictive maintenance is automating antenna health monitoring and failure anticipation across satellite terminal fleets. Full-service carriers in Asia-Pacific are deploying these systems to minimize unplanned removals and extend mean-time-between-failures. The shift is automating maintenance scheduling and reducing ground-time penalties for connectivity-related technical diversions.
The EU Cyber Resilience Act imposes mandatory cybersecurity disclosure and vulnerability reporting obligations on connected cabin system integrators. Hardware vendors must now embed security-by-design principles into antenna-to-screen architectures and maintain continuous compliance documentation. European carriers are prioritizing suppliers with established CSRD-aligned certification pathways to preempt regulatory friction.
Airline procurement of connectivity services is fragmenting from bundled long-term contracts toward modular, term-flexible agreements that separate hardware, bandwidth, and content licensing. Low-cost carriers are driving this unbundling to match connectivity spending with actual passenger uptake rates. This pattern is most visible in North American and European markets where yield management sophistication exceeds legacy contract structures.
In-Flight Entertainment and Connectivity Market Segmentation
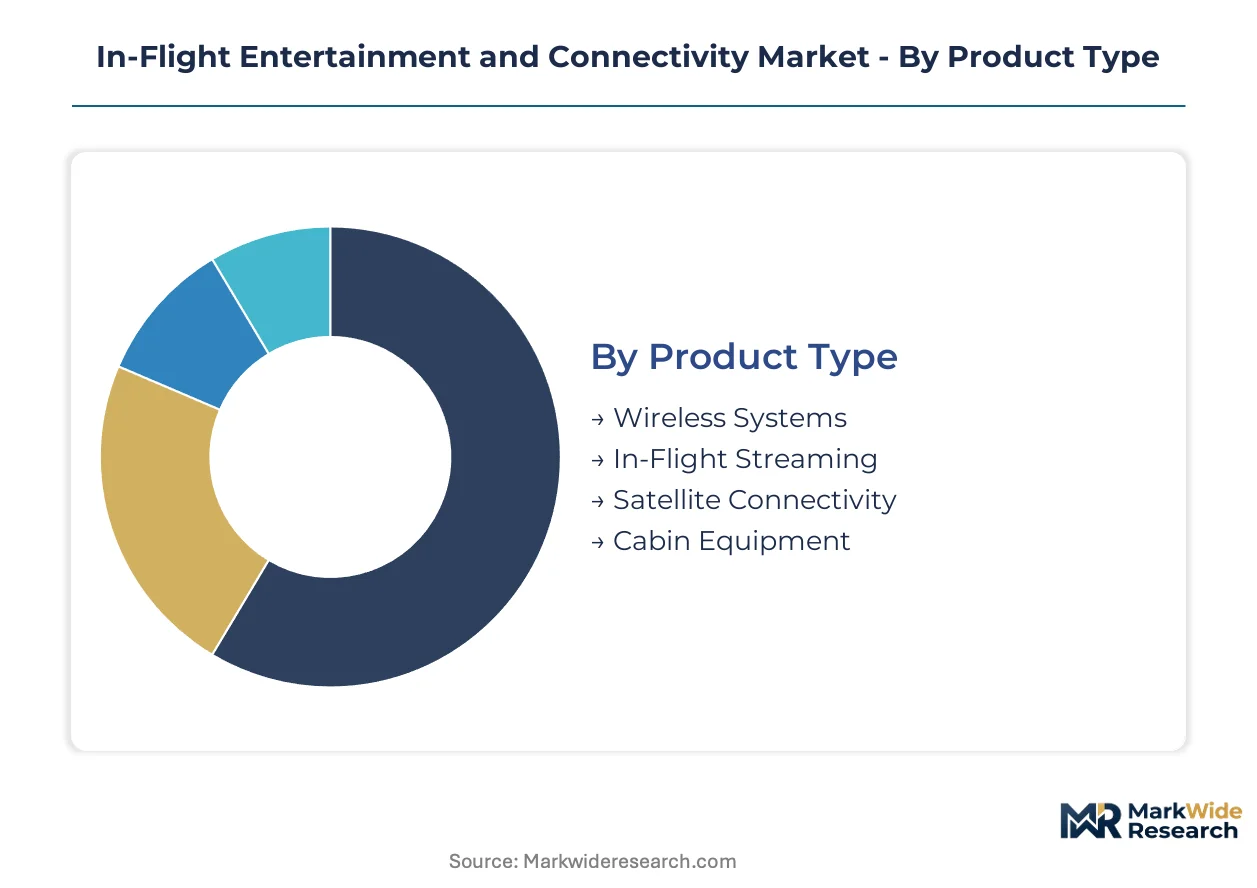
In-flight entertainment and connectivity procurement splits across hardware, service, and technology dimensions that reflect divergent upgrade economics. Fleet retrofit decisions hinge on whether carriers prioritize bandwidth-intensive satellite architectures or lighter streaming-centric deployments.
Product Type:
Retrofit cycles for narrowbody and widebody fleets are compressing as airlines weigh the capital burden of seatback replacement against bring-your-own-device migration paths.
- Satellite Connectivity:Ku-band and Ka-band terminal installations dominate installed value through capital-intensive radome and antenna requirements. Demand concentrates among full-service carriers operating transoceanic routes where geostationary and low-earth orbit networks deliver bandwidth that air-to-ground alternatives cannot match. FAA airworthiness criteria for satellite antenna certifications are streamlining approval timelines for qualified hardware vendors.
- In-Flight Streaming:Software-defined content delivery platforms bypass seatback hardware entirely, streaming to passenger-owned devices over cabin wireless networks. Low-cost carriers in North America and Europe are accelerating adoption to reduce weight, simplify maintenance logistics, and open modular pricing tiers for connectivity services.
- Wireless Systems:Air-to-ground and cabin-distribution architectures serve regional fleets where route economics favor terrestrial links over satellite.
- Cabin Equipment:Seatback screens, power outlets, and embedded IFE hardware persist in premium widebody configurations where passenger experience differentiation justifies the weight penalty.
Satellite Connectivity sits at the top of the volume ranking, with In-Flight Streaming climbing the fastest.
End User:
Customer procurement sophistication varies sharply across operator types, with commercial airlines driving standardization while private aviation demands bespoke integration.
- Commercial Airlines:Full-service and low-cost carriers represent the core demand base, with fleet-scale retrofits generating multi-year hardware and service contracts. Narrowbody upgrade programs in China are accelerating as domestic carriers pursue connected cabin differentiation on high-traffic routes. Procurement patterns are fragmenting from bundled long-term agreements toward modular contracts that separate hardware, bandwidth, and content licensing.
- Private Jets:Business aviation operators prioritize seamless global roaming and installation flexibility over unit cost, accepting premium pricing for compact terminals and rapid certification timelines.
- Military:Defense applications require hardened terminals with anti-jam capabilities and sovereign network control, operating under classified procurement channels with extended development cycles.
- Charter Services:Fractional ownership and ad-hoc charter operators favor portable or quick-change connectivity solutions that accommodate irregular fleet utilization patterns.
Commercial Airlines command the dominant share of procurement volume, with Private Jets expanding most quickly on post-pandemic business aviation recovery.
Technology:
Technology selection traces a direct path to spectrum allocation decisions by national regulators and constellation deployment timelines by satellite operators.
- Satellite:Geostationary Ku/Ka-band and emerging low-earth orbit networks deliver the bandwidth foundation for transoceanic and remote-area connectivity. LEO constellation deployment is reducing latency constraints that previously disadvantaged satellite against terrestrial alternatives.
- Wi-Fi:IEEE 802.11 standards govern cabin distribution to passenger devices, with Wi-Fi 6 and Wi-Fi 7 upgrades enabling denser device concentrations without access point proliferation.
- 5G:Terrestrial air-to-ground 5G remains contingent on FCC spectrum allocation proceedings, with domestic route economics potentially shifting if millimeter-wave bands open for inflight use.
- Bluetooth:Short-range wireless supports seatback controller pairing and hearing aid connectivity, occupying a peripheral role in the connectivity stack.
Satellite technology anchors current deployment value, with 5G presenting the steepest expansion trajectory contingent on regulatory clearance.
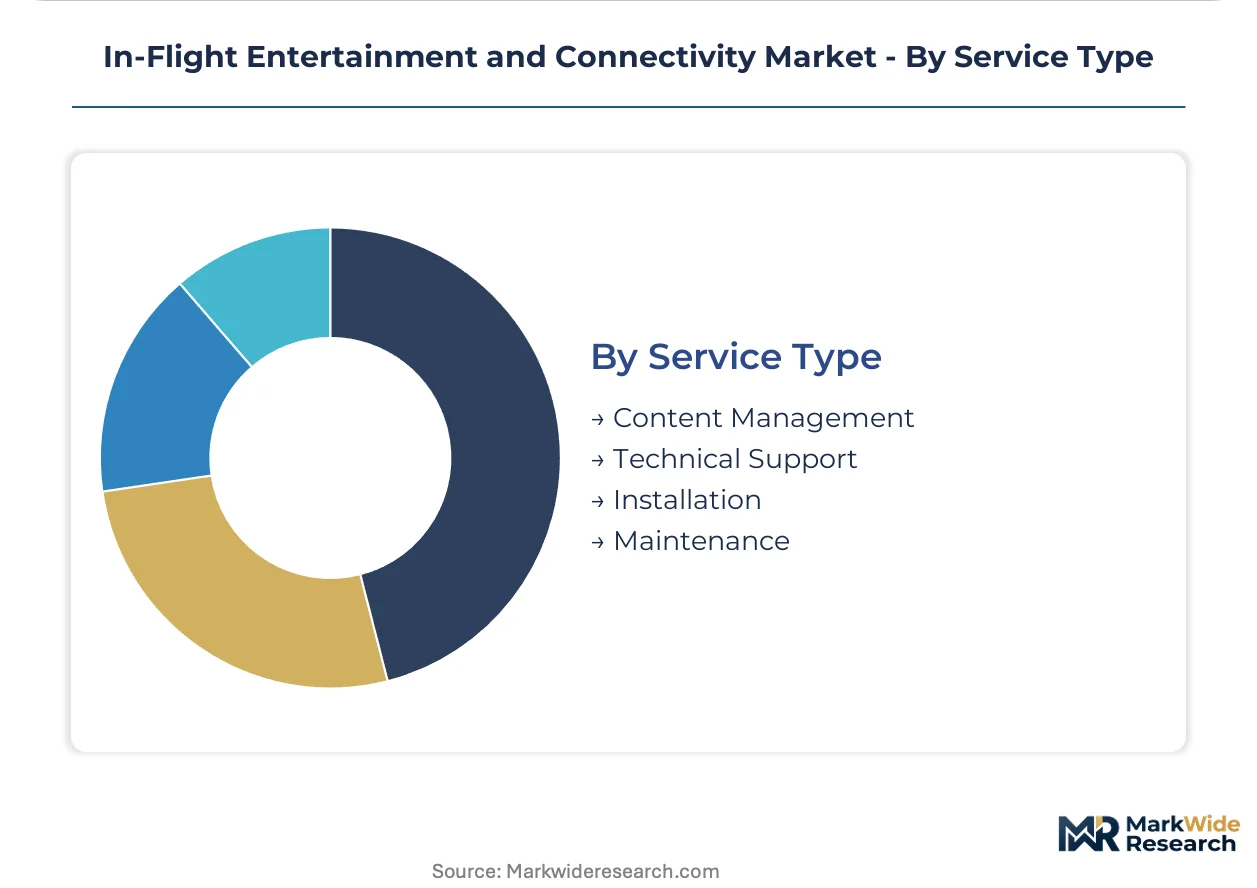
Service Type:
Service revenue models are unbundling from hardware-centric contracts toward recurring and outcome-based arrangements that align vendor compensation with system uptime.
- Content Management:Licensing, curation, and cloud delivery of entertainment libraries represents a growing revenue stream as airlines outsource library maintenance and rights negotiation.
- Maintenance:Predictive maintenance contracts leveraging AI-driven antenna health monitoring are automating failure anticipation and reducing ground-time penalties for connectivity-related technical diversions.
- Installation:Line-fit and retrofit deployment services carry certification risk and schedule coordination complexity, particularly for mixed fleet environments.
- Technical Support:24/7 operational support desks and field engineering response address real-time connectivity failures that impact passenger satisfaction metrics.
Maintenance services capture the largest recurring revenue pool, with Content Management gaining share fastest as streaming architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The in-flight entertainment and connectivity industry traces its commercial origins to the United States, where early satellite-based systems achieved FAA certification for commercial aviation in the 1990s. This regulatory foundation established the technical standards that subsequent markets adopted.
United States
Domestic carriers drive narrowbody retrofit demand as they migrate from seatback hardware to streaming-centric architectures. The FAA's updated airworthiness criteria for Ku- and Ka-band satellite antenna installations compress certification timelines for qualified vendors. Seattle-Tacoma and Dallas-Fort Worth anchor major airline procurement decision centers where connectivity upgrade programs concentrate.
China
Full-service carriers accelerate connected cabin deployments across narrowbody fleets serving high-traffic domestic routes. The CAAC aligns with international certification standards while MIIT governs spectrum allocation for inflight connectivity services. Shanghai and Beijing host the headquarters of domestic carriers executing the region's most aggressive fleet modernization schedules.
Germany
Lufthansa Group's procurement patterns influence European retrofit standards for widebody long-haul configurations. EASA continued airworthiness directives for electromagnetic interference shape hardware testing protocols that extend product development cycles. Hamburg and Munich concentrate airline engineering centers and MRO facilities specialized in connectivity system integration.
United Kingdom
Low-cost carriers headquartered in London drive unbundled service procurement models that separate hardware, bandwidth, and content licensing. The CAA coordinates with EASA on cybersecurity disclosure alignment ahead of EU Cyber Resilience Act implementation. Crawley and London Gatwick cluster airline operational headquarters where connectivity vendor selection decisions concentrate.
Japan
ANA and JAL retrofit programs prioritize passenger experience differentiation on transpacific routes through premium connectivity tiers. METI coordinates spectrum policy for satellite and potential air-to-ground 5G deployment. Tokyo-Narita and Osaka-Kansai anchor airline hub operations where connectivity system performance directly impacts competitive positioning.
In-Flight Entertainment and Connectivity Market Key Industry Players
The competitive structure tilts toward vertically integrated system integrators with established certification pathways. Incumbent vendors concentrate around three archetypes: satellite terminal specialists with antenna-to-screen ecosystems, avionics OEMs leveraging factory-installed relationships, and modular service providers unbundling hardware from bandwidth contracts. Strategic moves center on M&A to secure certification talent and geographic expansion to capture Asia-Pacific retrofit cycles.
Among the integrated system tier, Panasonic Avionics Corporation and Thales Group exemplify archetypes with vertically controlled supply chains spanning antenna manufacturing through content delivery platforms. Collins Aerospace occupies a position anchored in Boeing and Airbus line-fit relationships. These three entities represent the certification-concentrated core where FAA and EASA qualification pathways concentrate scarce avionics engineering expertise.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Thales Group |
| Collins Aerospace |
| Anuvu |
| Astronics Corporation |
| Viasat Inc. |
| Gogo LLC |
| Burrana Pty Ltd |
| Lufthansa Systems GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Full-service carrier procurement offices in Seattle-Tacoma, Dallas-Fort Worth, and Shanghai anchor demand concentration, locking in long-term bundled contracts that separate hardware, bandwidth, and content licensing into modular pricing tiers with volume-scaled discounts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates connectivity service procurement, with differentiation anchored in bandwidth allocation, latency guarantees, and content library depth. Certification tier—FAA airworthiness qualification versus baseline regulatory compliance—commands material premiums on hardware. Cost compression in satellite terminal manufacturing is intensifying because LEO constellation deployment expands supplier options beyond legacy geostationary vendors. Low-cost carriers exhibit highest price sensitivity, demanding unbundled contracts that match spending to passenger uptake, while private aviation operators accept premium positioning for rapid certification timelines.
Supply Chain Analysis
Air freight costs for certified radome assemblies and antenna terminals concentrate supply chain leverage with integrators maintaining captive manufacturing in France, United States, and Japan. Critical component dependencies include gallium nitride semiconductors, carbon fiber composite enclosures, and precision-machined waveguide assemblies. Single-source vulnerability in FAA-qualified avionics engineering talent concentrates certification risk among incumbent vendors. Distribution runs through airline procurement centers and MRO facilities at major hub airports, with line-fit installation channels controlled by Boeing and Airbus factory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as narrowbody fleet retrofit cycles compress across Asia-Pacific, generating recurring hardware and service revenue streams that extend mean contract durations.
For Market Incumbents: Deepen backward integration into antenna manufacturing and sovereign certification pathways to defend against modular service providers unbundling hardware from bandwidth. Lock in CAAC-aligned qualification pipelines in China before domestic competitors achieve certification parity. Prioritize AI-driven predictive maintenance capabilities to extend mean-time-between-failures and reduce customer churn. For New Entrants and Emerging Players: Regional MRO networks represent the most accessible channel partner type for penetrating mixed fleet environments where legacy seatback systems complicate maintenance logistics. Target charter services and fractional ownership operators in North America with portable connectivity solutions that bypass lengthy airline procurement cycles. Lead with cybersecurity-by-design architectures that preempt EU Cyber Resilience Act compliance costs for European carriers. For Investors and Strategic Acquirers: Satellite operators and terrestrial telecom providers are the most active acquirer in this space, seeking vertical control over bandwidth-to-terminal value chains. Acquisition targets with established FAA-EASA dual certification and narrowbody retrofit program traction offer strongest long-term viability. Watch FCC spectrum allocation proceedings for inflight 5G as the signal indicating potential terrestrial substitution threat to satellite economics on domestic routes.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Talent Acquisition | FAA-qualified avionics engineers concentrate among three vendors, creating scarcity-driven M&A premiums. |
| LEO Constellation Partnership | Low-earth orbit bandwidth agreements reduce latency constraints that previously disadvantaged satellite against terrestrial alternatives. |
| CSRD-Aligned Cybersecurity Certification | Early EU Cyber Resilience Act compliance positions vendors for streamlined market access across European carrier procurement. |
| Streaming Platform Unbundling | Software-defined content delivery separates hardware capital expenditure from recurring service revenue tiers. |
| China Narrowbody Retrofit Capture | CAAC-aligned qualification pipelines secure multi-year fleet upgrade contracts with domestic carriers. |
Research Approach
Multiple input streams — procurement director interviews at full-service and low-cost carriers, MRO facility operational assessments, and satellite operator bandwidth contract analysis — were reconciled against FAA certification databases, EASA continued airworthiness directives, and customs records for avionics component trade flows. Primary discussions with airline engineering heads, connectivity system integrators, and avionics certification specialists were cross-validated through bottom-up fleet retrofit tracking and top-down service revenue modeling.
Historical installation rates across Ku-band, Ka-band, and LEO terminal deployments were cross-referenced against panel-based carrier capex intention surveys to build the analytical framework. Segmentation dimensions modeled include product type, end user archetype, technology spectrum, and service revenue model across the projection horizon. CAGRs were derived from carrier fleet plan disclosures and satellite constellation deployment schedules, with sensitivity analysis applied to regulatory timeline variations and air-to-ground substitution scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC spectrum allocation decisions, LEO constellation completion rates, and divergence between Washington and Brussels on cybersecurity disclosure requirements. Forecasts reflect documented assumptions about carrier retrofit prioritization and satellite bandwidth pricing trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive & Transportation
Radar and Lidar Technology for Railways Application Market
Automotive & Transportation
Automotive Multi-Layer Display Market
Automotive & Transportation
Automotive Human Interface System Market
Automotive & Transportation
Europe Wireless Electric Vehicle Charging Market
Automotive & Transportation
Automotive Speedometer Market
Automotive & Transportation
Morocco Passenger Vehicles Lubricants Market
Automotive & Transportation
Freight and Logistics Market
Automotive & Transportation
Global Automotive Stampings Market
Automotive & Transportation
Colombia Automotive Lubricants Market
Automotive & Transportation
Transport Data Logger Market
Automotive & Transportation
Trailer Terminal Tractor Market
Automotive & Transportation
TPMS Battery Market
Automotive & Transportation
Heavy-Truck Composite Component Market
Automotive & Transportation
Sanitation Vehicle Market
Automotive & Transportation
Automotive Tailgate Market
Automotive & Transportation
Half-Shaft Assemblies Market