
 Automotive Fuse Block Market | 2026-2036
Automotive Fuse Block Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuse Block Market Outlook
Aftermarket service revenue is tilting toward integrated fuse block replacement programs as vehicle electrical complexity rises. Littelfuse, Inc. leverages its broad blade fuse portfolio to anchor North American supply relationships. Eaton Corporation dominates industrial-grade fuse block manufacturing with captive supply of ceramic housings. MERSEN specializes in high-amperage solutions for commercial vehicle platforms.
An automotive fuse block is a molded housing assembly that terminates multiple fuses to protect parallel circuits, typically rated from 5A to 60A with thermoplastic or ceramic bases and tin-plated brass terminals. Its primary purpose is to consolidate overcurrent protection into a single serviceable point within a vehicle's power distribution architecture. Blade fuse blocks lead volume production for passenger car applications where standardization reduces tooling costs. Relay fuse blocks represent the fastest-growing product category as electric vehicles integrate more power-distribution functions. Mini fuse blocks occupy the premium compact segment in hybrid vehicle engine bays where packaging density commands margin.
NHTSA Federal Motor Vehicle Safety Standards and EPA emissions compliance protocols shape fuse block durability and fire-resistance specifications in the United States. ISO 8820 and IEC 60269 provide international baseline testing for breaking capacity and temperature rise. Stakeholders must monitor how 800V electric vehicle architectures force redesigns of fuse block isolation spacing and arc-quenching materials.
Market Dynamics
The transition to 800V electric vehicle architectures is forcing fuse block manufacturers to redesign isolation spacing and arc-quenching materials across their product portfolios. This voltage escalation compresses design cycles and raises qualification barriers for incumbent suppliers.
Growth Catalysts
- EPA emissions compliance protocols:Tightening vehicle safety mandates in the United States require enhanced circuit protection durability, expanding fuse block specifications across passenger and commercial platforms.
- High-voltage battery systems:Electric vehicle manufacturers are expanding fuse block procurement as 800V architectures proliferate in premium and mass-market EV segments.
- Germany:Automotive OEMs in this manufacturing cluster source advanced fuse block systems for next-generation vehicle platforms, concentrating demand for relay-integrated designs.
Market Restraints
- Ceramic housing supply concentration:Captive production of high-grade ceramic substrates limits independent fuse block manufacturers' access to critical housing materials.
- Copper and tin price volatility:Terminal plating costs fluctuate with base metal markets, squeezing margin on standard blade fuse block production.
- ISO 8820 certification timelines:Extended testing protocols for breaking capacity and temperature rise delay new product introductions by 12-18 months.
Strategic Opportunities
- Commercial vehicle electrification:High-amperage fuse block demand in bus and truck platforms remains underpenetrated relative to passenger car saturation.
- Aftermarket integrated replacement programs:Service networks are consolidating fuse block replacement with diagnostic services, creating bundled revenue streams.
- REACH-compliant material transitions:EU regulatory pressure on flame-retardant thermoplastics is opening substitution windows for bio-based housing compounds.
Industry Challenges
- High-voltage safety engineering talent:Shortage of specialists in arc-quenching design and creepage distance optimization limits R&D throughput.
- Legacy 12V system integration:Fuse block architectures must maintain backward compatibility while accommodating 48V mild-hybrid and 800V full-electric circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuse Block Market |
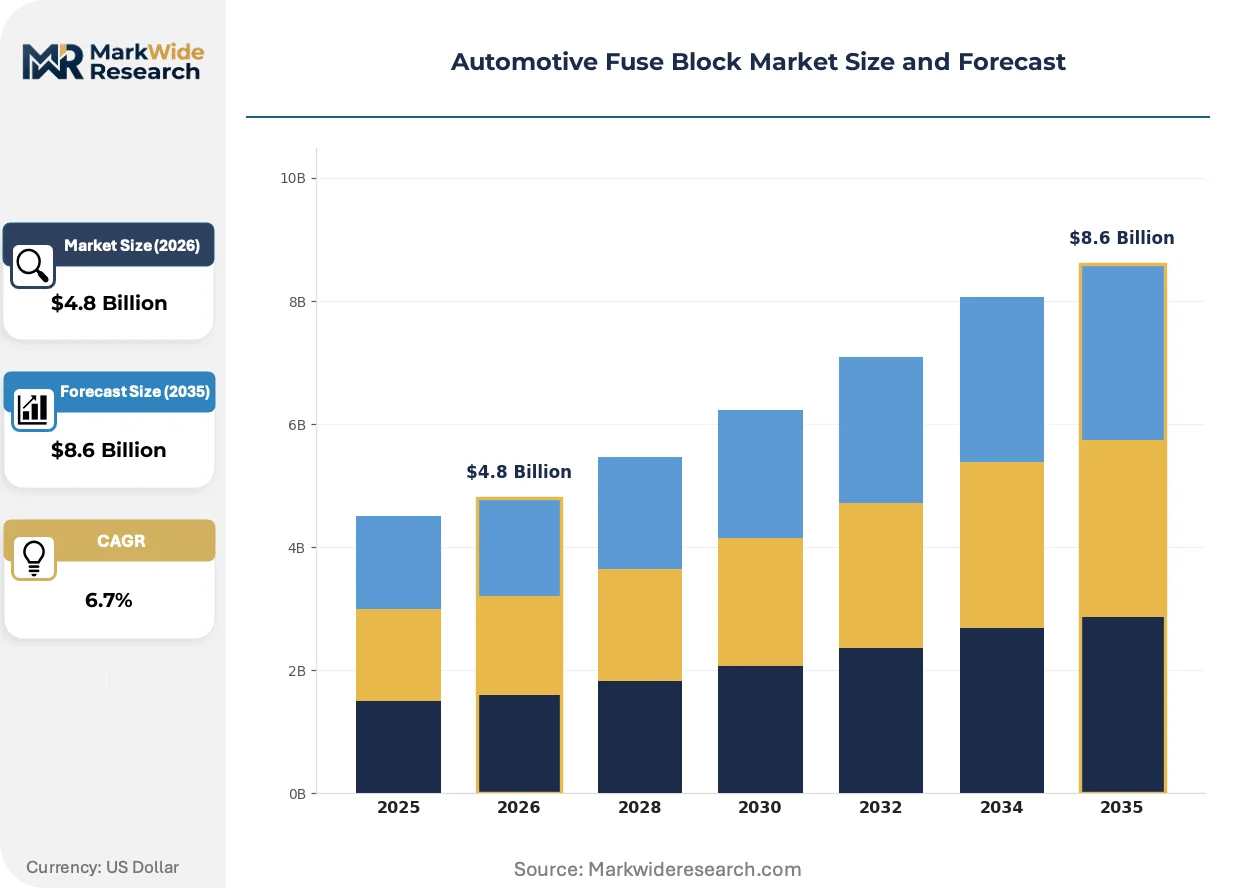
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Fuse Block, Mini Fuse Block, Maxi Fuse Block, Relay Fuse Block Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Fixing Type: Panel Mounted, Surface Mounted, Flush Mounted, Clip-In |
| Companies Covered | MERSEN, HELLA New Zealand Limited, Littelfuse, Inc., LEONI Bordnetz-Systeme GmbH, MTA S.p.A., Eaton Corporation, Sensata Technologies, Inc., OptiFuse, SCHURTER Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuse Block Market Strategic Shifts
Electrification is compressing fuse block design cycles while expanding functional requirements beyond simple overcurrent protection. Manufacturers now embed sensing, relay control, and communication capabilities into formerly passive housing assemblies.
Smart fuse blocks with integrated current sensing and diagnostic feedback are hybridizing traditional protection hardware with power distribution electronics. Tier 1 suppliers serving European electric vehicle platforms are adopting these designs at accelerated qualification paces. The technology is hybridizing procurement categories, forcing buyers to evaluate fuse blocks alongside power electronics rather than as discrete commodity components.
REACH and RoHS amendments in the European Union are restricting halogenated flame retardants in thermoplastic fuse block housings. Compounders serving the automotive supply chain are reformulating glass-filled polyamides with phosphorus-based alternatives. Relay fuse blocks for electric vehicle applications face the steepest reformulation costs due to their larger housing mass and thermal management requirements.
Fleet operators and commercial vehicle buyers are consolidating fuse block procurement through long-term service agreements rather than spot component purchases. Independent distributors serving the North American aftermarket are losing share to authorized service networks with diagnostic-linked replacement programs. This pattern is most visible in Germany, where OEM-captive service operations dominate commercial vehicle maintenance channels.
Automotive Fuse Block Market Segmentation
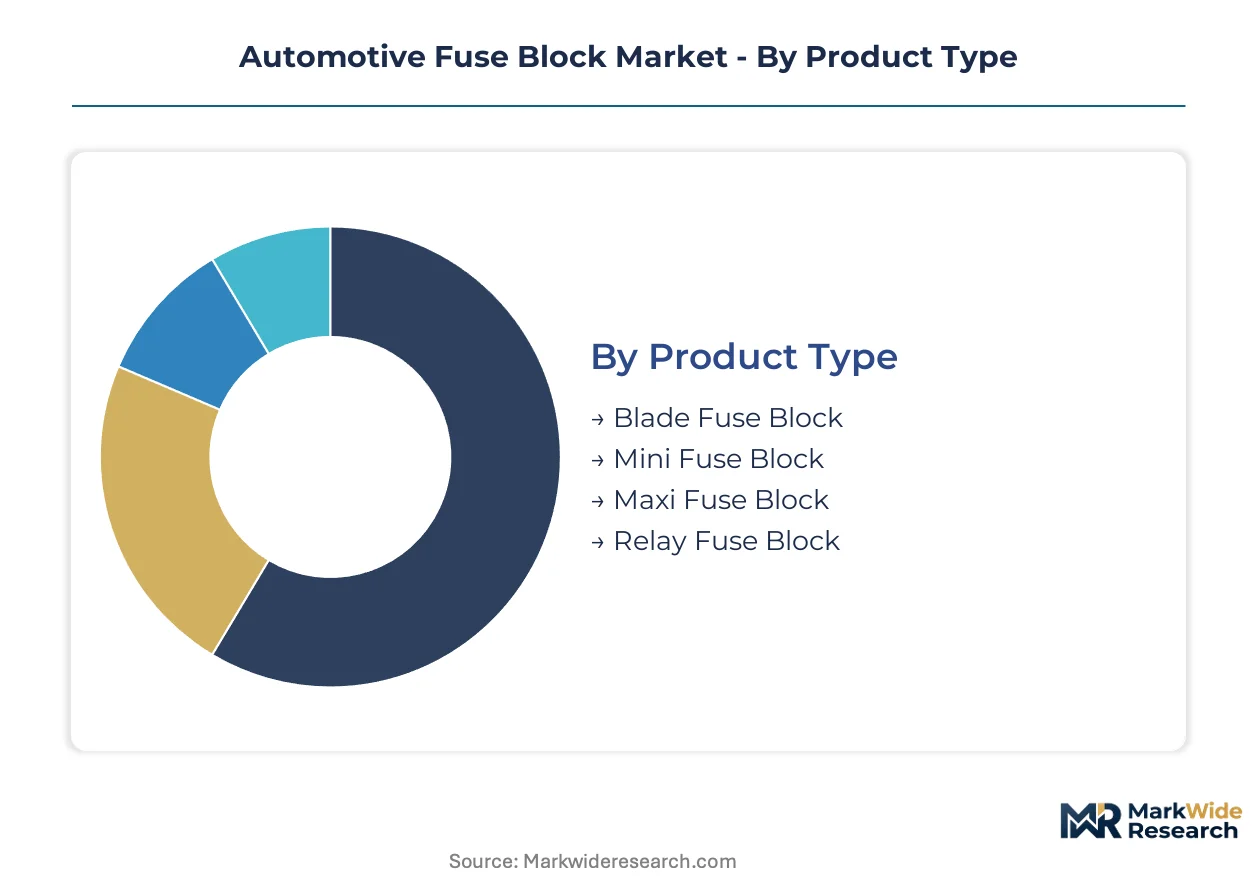
Segmentation in automotive fuse blocks reveals how procurement cycles and technical requirements diverge across vehicle electrification tiers. Product refresh rates vary dramatically between legacy 12V architectures and emerging 800V platforms.
Product Type:
Blade fuse blocks turn over fastest in high-volume passenger car programs, while relay fuse blocks face extended qualification cycles tied to electric vehicle platform launches.
- Blade Fuse Block:Standardized thermoplastic housings with tin-plated brass terminals dominate passenger car power distribution architectures. Procurement concentrates with German automotive OEMs sourcing for next-generation compact vehicle platforms where tooling cost reduction remains critical.
- Relay Fuse Block:These integrated assemblies combine overcurrent protection with switching functions in single molded housings. Electric vehicle manufacturers in Germany are expanding procurement fastest as 800V architectures proliferate and power distribution electronics consolidate.
- Mini Fuse Block:Compact thermoplastic designs serve hybrid vehicle engine bays where packaging density commands premium positioning.
- Maxi Fuse Block:High-amperage ceramic-based variants protect commercial vehicle battery and starter circuits against severe fault currents.
Blade fuse blocks dominate installed base. Relay fuse blocks are where expansion concentrates.
Vehicle Type:
Passenger car programs drive volume procurement with compressed design cycles, while commercial vehicle electrification extends development timelines and amperage requirements.
- Passenger Cars:High-volume production lines in Germany source standardized blade and mini fuse blocks with 12-18 month ISO 8820 certification timelines. NHTSA Federal Motor Vehicle Safety Standards shape fire-resistance specifications for US-bound vehicle exports.
- Electric Vehicles:Battery electric platforms demand redesigned isolation spacing and arc-quenching materials as 800V architectures displace 400V systems. Procurement is expanding fastest among premium and mass-market EV segments.
- Commercial Vehicles:Bus and truck platforms require high-amperage fuse block solutions that remain underpenetrated relative to passenger car saturation.
- Hybrid Vehicles:Dual-voltage architectures necessitate fuse blocks maintaining backward compatibility with 12V systems while accommodating 48V mild-hybrid circuits.
Passenger cars anchor current revenue. Electric vehicles are climbing the fastest.
End User:
OEM captive procurement operates on multi-year platform cycles, while aftermarket service networks are consolidating fuse block replacement with diagnostic-linked programs.
- OEMs:Volkswagen, BMW, and Mercedes-Benz parent entities in Germany source advanced fuse block systems through long-term supply agreements with relay-integrated design specifications.
- Aftermarket Providers:Independent distributors in North America are losing share to authorized service networks bundling fuse block replacement with diagnostic capabilities.
- Tier-1 Suppliers:These intermediaries face compressed design cycles as electric vehicle architectures force simultaneous qualification of smart fuse blocks with embedded sensing.
- Vehicle Assemblers:Contract manufacturing operations in Eastern Europe procure standardized blade fuse blocks for volume passenger car production.
OEMs control specification authority. Aftermarket providers are gaining share fastest through integrated replacement programs.
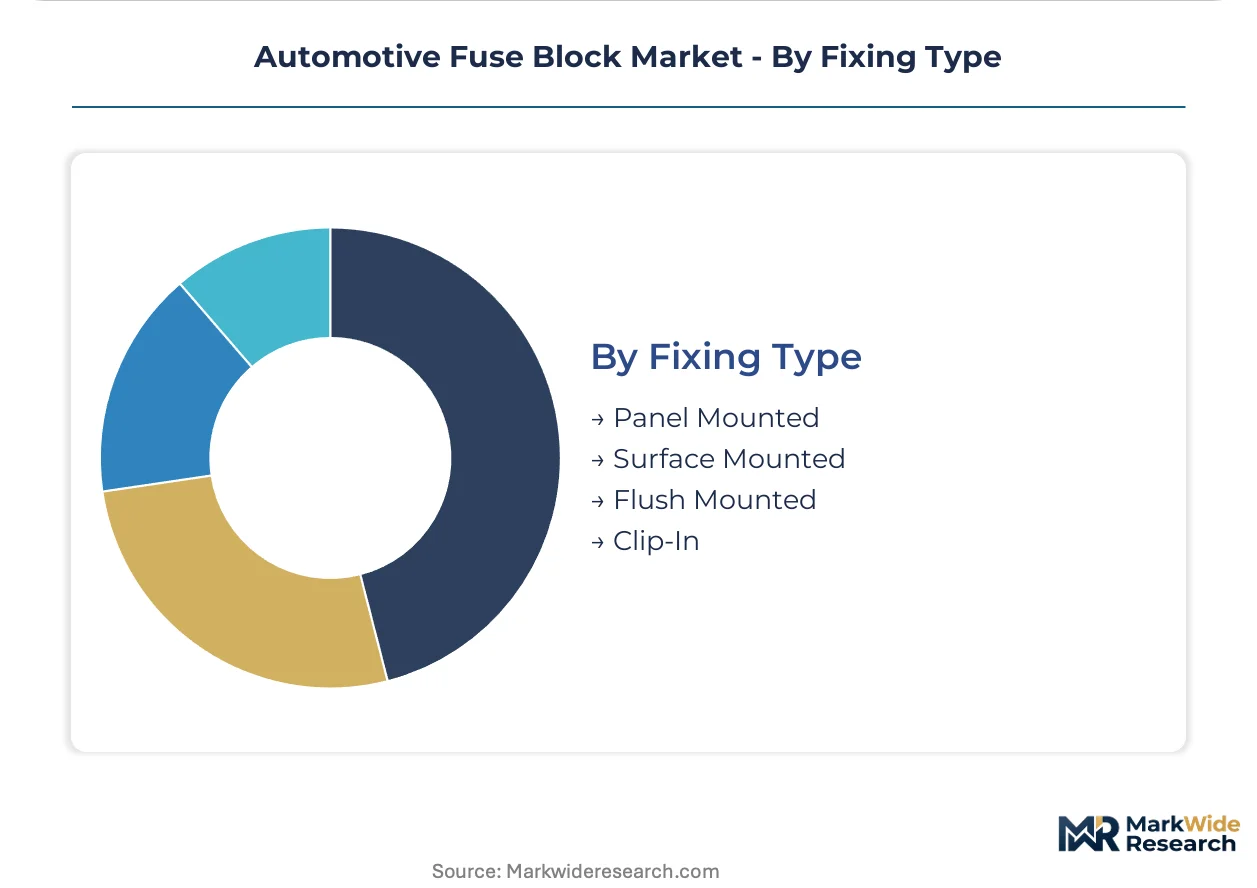
Fixing Type:
Panel mounted variants serve established vehicle architectures with stable tooling, while clip-in designs are expanding with modular electric vehicle platform strategies.
- Panel Mounted:Bolt-secured housings with threaded brass inserts dominate commercial vehicle engine compartments where vibration resistance is mandatory.
- Clip-In:Snap-fit retention systems enable rapid assembly line integration for electric vehicle battery pack fuse blocks requiring service accessibility.
- Surface Mounted:Low-profile housings attach directly to sheet metal substrates in passenger car interior fuse compartments.
- Flush Mounted:Recessed installations protect fuse blocks in exposed underhood environments from mechanical damage and fluid ingress.
Panel mounted designs retain installed base dominance. Clip-in configurations are where platform modularity investments concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes fuse blocks through relay-integrated designs for 800V EV platforms, while the United States prioritizes NHTSA-compliant fire-resistant variants for legacy 12V architectures. China sources high-volume blade fuse blocks for domestic passenger car production. This consumption-mix differential reflects divergent electrification timelines and regulatory enforcement intensity.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate enhanced fire-resistance specifications for passenger and commercial vehicle fuse blocks. EPA emissions compliance protocols tighten circuit protection durability requirements across platforms. Detroit-area automotive OEMs source standardized blade fuse blocks for high-volume production lines serving domestic and export markets.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg procure advanced relay fuse block systems for next-generation electric vehicle platforms. REACH and RoHS amendments restrict halogenated flame retardants in thermoplastic housings, forcing material reformulation. Stuttgart and Munich manufacturing clusters concentrate demand for 800V-compatible designs with expanded isolation spacing.
China
Domestic EV manufacturers accelerate procurement of high-voltage fuse blocks as 800V battery systems proliferate in premium and mass-market segments. MIIT vehicle safety regulations align with international breaking capacity standards while adding domestic certification requirements. Yangtze River Delta automotive suppliers scale blade fuse block production for both local OEMs and export assembly operations.
Japan
METI industrial policy supports fuse block manufacturers developing arc-quenching materials for next-generation electric vehicle architectures. JIS standards provide baseline testing protocols that domestic suppliers leverage for regional qualification efficiency. Nagoya-area Tier-1 suppliers integrate smart fuse blocks with embedded sensing for hybrid vehicle power distribution systems.
South Korea
Battery electric vehicle platforms from Seoul-headquartered OEMs drive demand for redesigned fuse block isolation systems. MFDS-aligned safety frameworks influence material selection for high-voltage applications. Busan-Ulsan manufacturing corridors concentrate relay fuse block procurement for commercial vehicle electrification programs.
Automotive Fuse Block Market Competitive Environment
Capability concentration sits with specialists mastering arc-quenching design and creepage distance optimization; scale advantage sits with diversified electrical component manufacturers with captive material supply. The market structures around three tiers: integrated power electronics suppliers, dedicated fuse block manufacturers, and automotive Tier-1 systems integrators. Dominant competitive moves include backward integration into ceramic housing production and strategic partnerships with electric vehicle platform developers.
Within the specialist tier, MERSEN and Littelfuse, Inc. exemplify contrasting geographic and structural positioning. MERSEN, a French S.A., anchors high-amperage solutions for commercial vehicle electrification. Littelfuse, Inc., a US-based corporation, occupies a position in blade fuse portfolio breadth for North American passenger car supply relationships. Eaton Corporation, a diversified industrial manufacturer, represents the integrated tier with in-house ceramic housing capabilities.
| Leading Market Players |
|---|
| MERSEN |
| HELLA New Zealand Limited |
| Littelfuse, Inc. |
| LEONI Bordnetz-Systeme GmbH |
| MTA S.p.A. |
| Eaton Corporation |
| Sensata Technologies, Inc. |
| OptiFuse |
| SCHURTER Inc. |
| Others |
Value Chain & Pricing Dynamics
Copper and tin price volatility determines both pricing tier spreads and supply chain shape across automotive fuse block manufacturing. Terminal plating costs fluctuate with base metal markets, squeezing margin on standard blade fuse block production while forcing buyers toward long-term offtake contracts with ceramic housing suppliers.
Pricing Analysis
Long-term offtake agreements dominate procurement between German OEMs and relay fuse block manufacturers, insulating against raw material swings while spot transactions persist for aftermarket blade fuse replacement. Price differentiation separates ISO 8820-certified premium tiers from uncertified economy alternatives, with certification timelines adding 12-18 months to qualification. Pricing pressure stems from REACH-compliant material reformulation costs in European supply chains. Fleet operators demonstrate lowest price sensitivity through bundled service agreements, while independent distributors face acute margin compression.
Supply Chain Analysis
Contract manufacturing concentration sits with LEONI Bordnetz-Systeme GmbH and MTA S.p.A. holding capacity for molded thermoplastic housings across European and Asian production networks. Supply draws from Germany, China, and Mexico for ceramic substrates, copper terminals, and glass-filled polyamide compounds. Single-source vulnerability concentrates in captive ceramic housing production controlled by diversified industrial manufacturers. Distribution runs through OEM-captive service networks in Germany and authorized aftermarket channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation into long-term service agreements has shifted procurement leverage toward buyers with diagnostic-linked replacement programs. This concentration fragments independent distributor margins while rewarding integrated supply relationships.
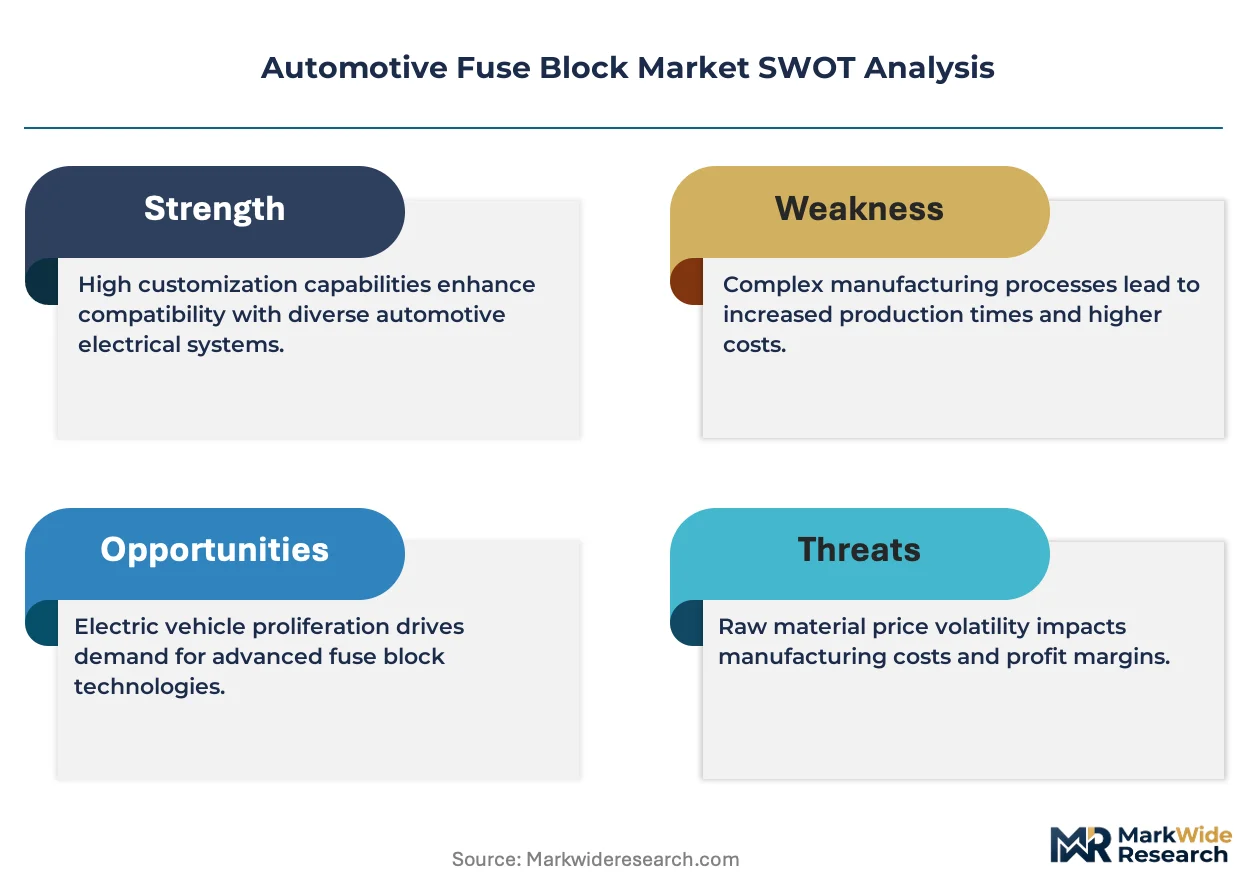
For Market Incumbents: Harden ceramic housing supply positions through backward integration or exclusive offtake arrangements with specialized compounders. Secure arc-quenching engineering talent pools before 800V platform launches accelerate, as capability scarcity threatens R&D throughput for relay-integrated designs. Prioritize REACH-compliant material transitions ahead of regulatory enforcement windows.
For New Entrants and Emerging Players: Commercial vehicle electrification in South Korean and Chinese bus manufacturing corridors offers white-space entry with less entrenched incumbent relationships. Target high-amperage maxi fuse block segments where MERSEN's concentration leaves pricing elasticity for qualified challengers. Pursue joint development agreements with battery pack integrators seeking clip-in service accessibility features.
For Investors and Strategic Acquirers: NHTSA Federal Motor Vehicle Safety Standards tightening reshapes the acquisition landscape toward fire-resistant specification capabilities. Five-to-ten year viability favors specialists with embedded sensing integration and smart fuse block qualification momentum. Monitor Tier-1 supplier consolidation into power electronics categories as the signal for category-blurring inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Housing Backward Integration | Eaton Corporation's captive supply model demonstrates margin defense against substrate scarcity. |
| Smart Fuse Block Platform Launch | Sensata Technologies embeds current sensing to hybridize protection with power distribution electronics. |
| 800V Architecture Qualification | Littelfuse leverages blade fuse breadth to anchor North American EV supply relationships. |
| REACH-Compliant Material Transition | HELLA New Zealand reformulates glass-filled polyamides with phosphorus-based flame retardants. |
| Commercial Vehicle Electrification Partnership | MERSEN anchors high-amperage solutions for bus and truck platform electrification programs. |
Study Parameters
Operator-level perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and ceramic housing compounder technical directors anchored the qualitative base. These primary interviews combined with vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed component manufacturers, and NHTSA safety standard documentation. Bottom-up segment sizing triangulated against top-down market aggregation across product type, vehicle architecture, and regional production cluster dimensions.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning propulsion architecture, content per vehicle, amperage tier, and OEM supply tier. CAGRs derived from installed base turnover rates, platform launch timelines, and electrification penetration curves. Forecast inputs incorporated 800V architecture adoption trajectories, REACH amendment implementation schedules, and fleet operator consolidation patterns into service network structures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery pack integrators verticalizing fuse block production would shift outcomes. Quarterly review of OEM platform engineering headcount allocations, ceramic housing spot pricing, and smart fuse block qualification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market