
 Automotive NFC Market | 2026-2036
Automotive NFC Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive NFC Market Intelligence
Buyer concentration among premium vehicle manufacturers is pivoting toward integrated digital key ecosystems that bundle access, payment, and identity functions. NXP Semiconductors anchors this transition through its dominance in secure element and automotive NFC controller portfolios. Qualcomm Technologies leverages its Snapdragon Digital Chassis to extend NFC capabilities into broader vehicle connectivity platforms. Samsung Semiconductors competes by specializing in high-volume embedded NFC chip production for mass-market OEM programs.
Automotive NFC encompasses short-range wireless communication hardware operating at 13.56 MHz, enabling encrypted data exchange between vehicles, mobile devices, and infrastructure access points across distances up to 10 centimeters. The technology serves primary commercial purposes in secure vehicle access, contactless payment authentication, and driver identity verification within connected car architectures. NFC controllers and secure elements capture the dominant margin pools due to cryptographic certification requirements and automotive-grade reliability standards. Peer-to-peer communication protocols represent the fastest-expanding technology segment as OEMs architect bidirectional smartphone-to-vehicle data tunnels. Keyless entry applications retain the largest volume footprint, though in-vehicle payments are emerging as the highest-growth application category with fintech integration.
The EU Cybersecurity Regulation and UNECE WP.29 R155 framework mandate secure-by-design communication protocols that directly elevate demand for certified NFC secure elements in European vehicle programs. The FCC in the United States governs spectrum allocation and emission standards for near-field communication devices integrated into automotive systems. Stakeholders must monitor how cybersecurity certification timelines in Europe and spectrum policy evolution in North America reshape supplier qualification requirements and procurement specifications.
Market Dynamics
The EU Cybersecurity Regulation and UNECE WP.29 R155 framework are forcing automotive OEMs to redesign connected car architectures around certified secure elements, compressing supplier qualification timelines and elevating procurement specifications for cryptographic hardware.
Growth Catalysts
- Digital Key Ecosystem Integration:Premium vehicle manufacturers are bundling NFC-based access, payment, and identity verification into unified smartphone-to-vehicle platforms. This convergence is expanding addressable hardware content per vehicle program.
- EU Regulatory Mandates:The EU Cybersecurity Regulation requires secure-by-design communication protocols in all new vehicle types, directly mandating certified NFC secure element deployment in European automotive production.
- Fintech-Automotive Partnerships:Contactless in-vehicle payment authentication is attracting payment processor investment, creating dedicated hardware demand for fueling, tolling, and parking transactions.
Market Restraints
- Semiconductor Supply Concentration:Automotive-grade NFC controller and secure element production concentrates among a limited set of European and East Asian foundries, exposing OEM programs to single-source qualification risk.
- Cryptographic Certification Friction:Common Criteria and EMVCo certification timelines for automotive NFC secure elements extend 18-24 months, delaying platform launches and freezing supplier switching.
- Bluetooth Low Energy Substitution:BLE-based digital key protocols are capturing mid-market vehicle programs where NFC's 10-centimeter range constraint limits user experience flexibility.
Strategic Opportunities
- Mass-Market Vehicle Penetration:Japanese and South Korean OEMs are architecting NFC digital key platforms for compact vehicle segments previously limited to premium price tiers.
- Vehicle-to-Grid Authentication:Bidirectional NFC data tunnels are enabling encrypted EV charging authorization and utility billing integration, opening energy-sector hardware demand.
- India Automotive Production:The country's PLI scheme for advanced automotive technology manufacturing is attracting NFC module assembly investment for domestic and export vehicle programs.
Industry Challenges
- Embedded Systems Security Engineering Talent:Automotive OEMs and Tier-1 suppliers face acute shortages of engineers with combined NFC protocol, secure element architecture, and functional safety expertise.
- Legacy Fleet Retrofit Complexity:Aftermarket NFC digital key installation requires physical secure element provisioning and smartphone app ecosystem integration that conflicts with older vehicle electrical architectures.
- Multi-Stakeholder Standard Alignment:CCC Digital Key, ISO 21434, and EMVCo specifications are evolving on mismatched cadences, forcing suppliers to maintain parallel certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive NFC Market |
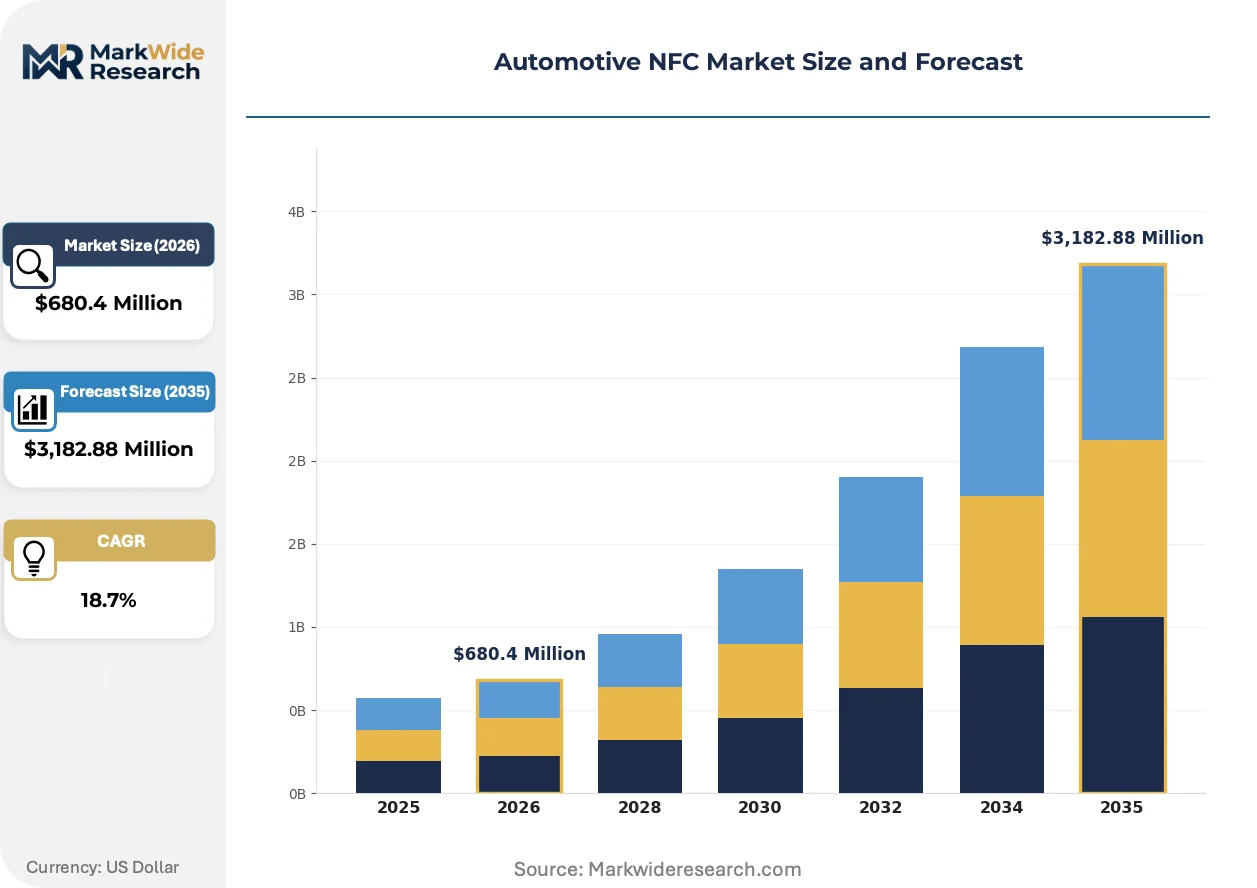
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $3,182.88 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded NFC Chips, NFC Tags, NFC Readers, NFC Controllers, Secure Elements Technology: Passive NFC, Active NFC, Peer-to-Peer, Card Emulation, Secure Communication Application: Keyless Entry, In-Vehicle Payments, Vehicle Tracking, Data Transfer, Driver Authentication End User: Vehicle Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Qualcomm Technologies, Inc., MediaTek Inc., NXP Semiconductors, Samsung Semiconductors Inc., Sony Corporation, Infineon Technologies AG, Renesas Electronics Corporation, Continental AG, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive NFC Market Strategic Shifts & Innovations
Automotive NFC technology is pivoting from standalone access control toward encrypted data tunneling infrastructure that bridges vehicle systems, mobile wallets, and energy networks. This architectural shift is reshaping supplier value capture and OEM platform roadmaps.
Peer-to-peer NFC communication protocols are expanding into bidirectional smartphone-to-vehicle data exchange beyond simple access authorization. German and Japanese OEMs are deploying these enhanced protocols for secure credential transfer and temporary key delegation. This capability expansion is compressing the boundary between digital key hardware and broader vehicle connectivity platforms.
The EU AI Act and delegated acts under the Cybersecurity Regulation are establishing conformity assessment requirements for AI-enabled biometric authentication in vehicle access systems. Automotive NFC suppliers must now integrate liveness detection and anti-spoofing hardware that satisfies both cybersecurity and AI safety frameworks. European premium vehicle programs are responding by consolidating vendor relationships with semiconductor houses holding dual certification competence.
Fleet operators and mobility service providers are unbundling NFC digital key provisioning from vehicle purchase, treating access credentials as subscription-managed service components. This procurement evolution is displacing traditional dealer-channel key distribution with direct OEM-to-fleet digital provisioning platforms. North American commercial vehicle and European corporate fleet segments are exhibiting the most pronounced adoption of this service-based access model.
Automotive NFC Market Segmentation
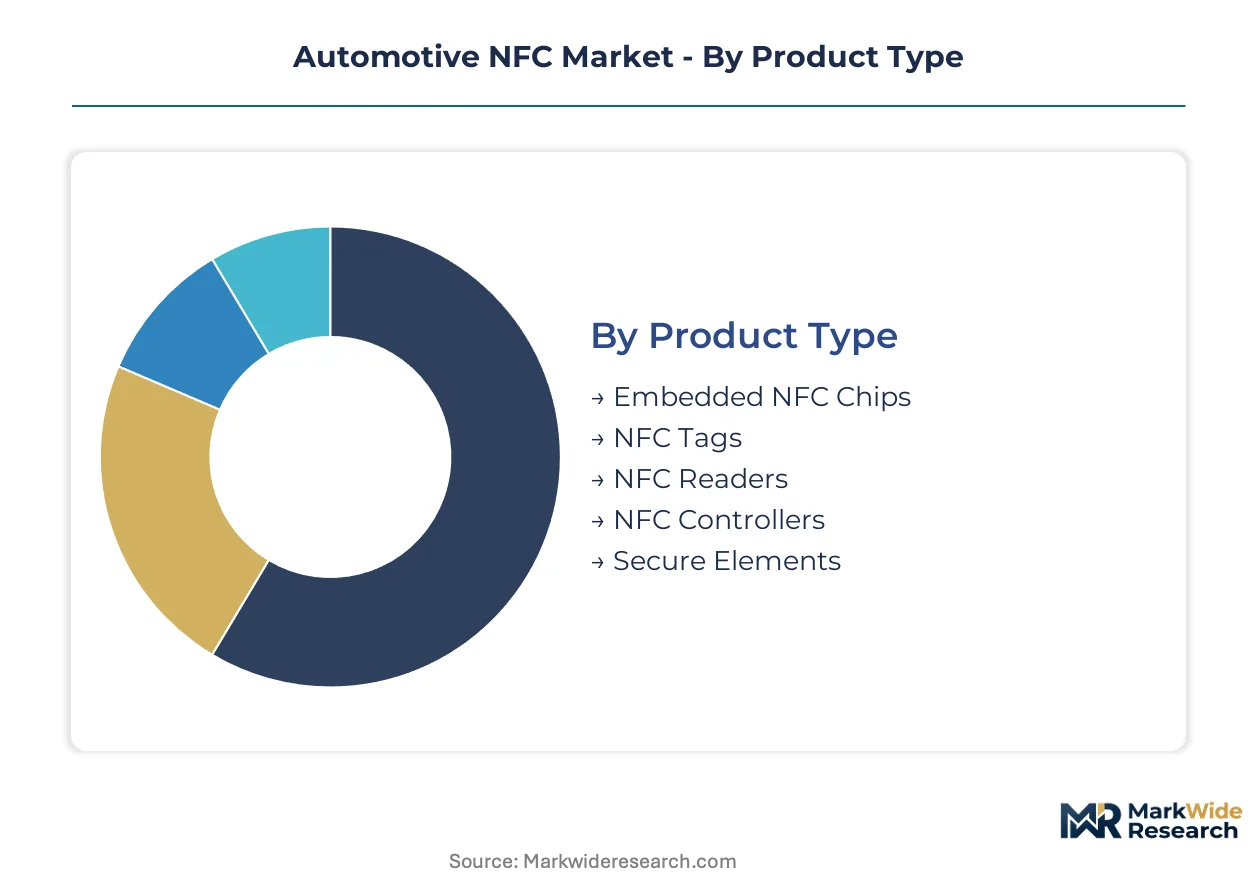
Automotive NFC segmentation reveals how hardware specifications, communication protocols, and deployment contexts fragment procurement requirements across vehicle programs. Suppliers must qualify across multiple certification tracks simultaneously while OEMs prioritize different performance tiers by application criticality.
Product Type:
Silicon integration level determines automotive qualification burden and margin capture potential.
- NFC Controllers:These integrated circuits manage RF field generation, protocol timing, and host interface communication at 13.56 MHz. German and Japanese OEMs concentrate procurement for digital key platforms here, driven by UNECE WP.29 R155 secure element pairing mandates that elevate controller-specification requirements.
- Secure Elements:Tamper-resistant hardware modules storing cryptographic keys and certified credentials for EMVCo and Common Criteria compliance. European vehicle programs anchor demand as EU Cybersecurity Regulation deadlines force secure-by-design architecture retrofits.
- Embedded NFC Chips:Discrete transceiver die for antenna-integrated modules.
- NFC Tags:Passive data storage devices for vehicle component traceability.
- NFC Readers:External interface hardware for infrastructure communication.
NFC Controllers lead on scale; Secure Elements lead on momentum.
Technology:
Power sourcing and communication directionality reshape system architecture tradeoffs between range, security, and battery impact.
- Peer-to-Peer:Bidirectional data exchange enabling smartphone-to-vehicle credential transfer and temporary key delegation. This protocol climbs fastest as German OEMs deploy enhanced digital key ecosystems requiring authenticated two-way tunnels rather than simple access authorization.
- Secure Communication:Encrypted channels with mutual authentication and replay attack protection. Fleet operators in North America prioritize this technology for subscription-managed access credential provisioning that displaces traditional dealer distribution.
- Passive NFC:Reader-powered operation for zero-battery applications.
- Active NFC:Self-powered transmission for extended range use cases.
- Card Emulation:Device mimics contactless smart card behavior for payment integration.
Passive NFC leads on installed base; Peer-to-Peer leads on expansion trajectory.
Application:
Use case criticality determines hardware grade requirements and certification depth.
- In-Vehicle Payments:Contactless authentication for fueling, tolling, and parking transactions through mobile wallet integration. Fintech-automotive partnerships in the United States and Japan are steepest expansion trajectory here as payment processors invest in dedicated automotive hardware programs.
- Keyless Entry:Smartphone-based vehicle access replacing physical fobs. This application retains largest volume footprint across premium and mass-market vehicle tiers despite BLE substitution pressure in mid-market segments.
- Vehicle Tracking:NFC-enabled logistics and theft recovery systems.
- Data Transfer:Localized vehicle diagnostics and personalization profile exchange.
- Driver Authentication:Biometric-linked credential verification for personalized settings.
Keyless Entry leads on unit volume; In-Vehicle Payments leads on value growth.
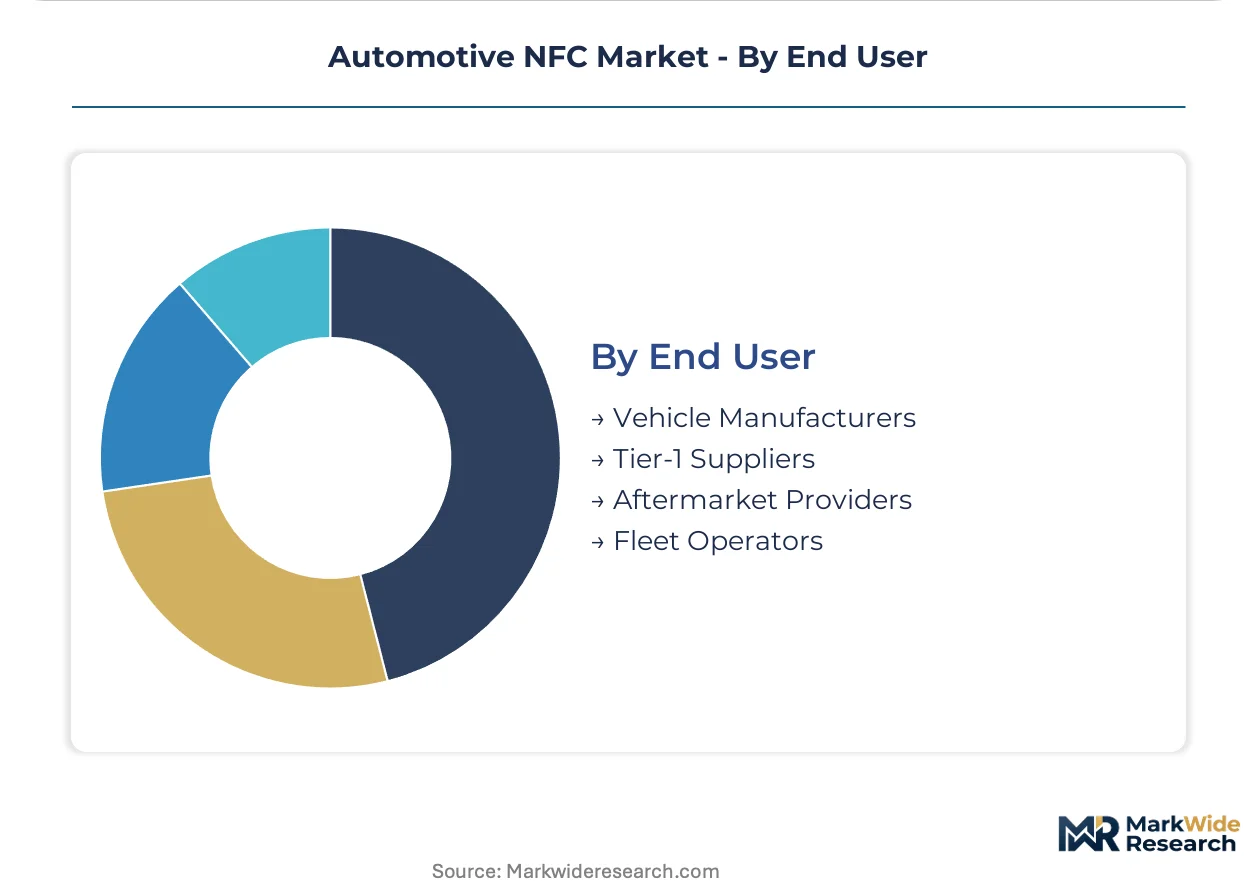
End User:
Procurement authority and integration depth segment qualification requirements and sales cycle length.
- Vehicle Manufacturers:OEMs specifying NFC architecture at platform design stage with multi-year supplier commitments. These stakeholders concentrate demand in Germany, Japan, and the United States where production scale justifies dedicated secure element qualification programs.
- Fleet Operators:Commercial and corporate mobility providers unbundling access credentials from vehicle purchase. European corporate fleet segments and North American commercial vehicle operators are gaining share fastest through subscription-managed provisioning platforms.
- Tier-1 Suppliers:System integrators assembling NFC modules for OEM programs.
- Aftermarket Providers:Retrofit installation channels facing legacy electrical architecture compatibility constraints.
Vehicle Manufacturers lead on procurement value; Fleet Operators lead on model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive NFC secure element demand through premium OEM platforms, while Japan anchors mass-market controller production for compact vehicle segments. Production scale and regulatory deadlines vary sharply across these manufacturing centers.
United States
Fintech-automotive partnerships in Michigan and California are accelerating in-vehicle payment authentication hardware demand. The FCC governs spectrum allocation for near-field communication devices integrated into automotive systems. Detroit-area OEMs and Silicon Valley mobility platforms are co-developing subscription-managed fleet access credentials.
Germany
Premium vehicle manufacturers in Bavaria and Baden-Württemberg are bundling NFC-based access, payment, and identity verification into unified smartphone-to-vehicle platforms. The EU Cybersecurity Regulation mandates secure-by-design communication protocols through certified secure element deployment. Stuttgart and Munich anchor OEM qualification programs for cryptographic hardware.
Japan
Compact vehicle OEMs in Aichi and Kanagawa prefectures are architecting NFC digital key platforms for mass-market segments previously limited to premium tiers. METI standards coordinate automotive-grade reliability requirements for semiconductor suppliers. Nagoya and Yokohama production clusters concentrate embedded NFC chip fabrication for high-volume programs.
South Korea
Hyundai Motor Group and Samsung affiliates in Seoul Capital Area and Busan-Ulsan are integrating NFC controllers into broader vehicle connectivity platforms. The MFDS framework intersects with automotive cybersecurity certification for biometric authentication hardware. Gyeonggi-do semiconductor foundries are expanding automotive-grade secure element capacity.
India
Maruti Suzuki and Tata Motors in Haryana and Maharashtra are evaluating NFC module assembly for domestic compact vehicle programs. The PLI scheme for advanced automotive technology manufacturing is attracting component investment for export vehicle production. Chennai and Pune automotive clusters are emerging as qualification sites for mass-market NFC deployment.
Automotive NFC Market Key Industry Players
Dutch and German producers anchor one tier; South Korean and Japanese specialists hold mass-market controller supply. The vendor base concentrates among semiconductor houses with dual automotive-grade and cryptographic certification competence. Three archetypes dominate: secure element specialists, integrated connectivity platform providers, and high-volume embedded chip fabricators. Strategic moves center on qualification timeline compression and fleet-operator direct provisioning partnerships.
Within the secure element tier, NXP Semiconductors and Infineon Technologies AG exemplify European cryptographic hardware leadership, while Qualcomm Technologies, Inc. occupies a position representing integrated connectivity platform architecture. Samsung Semiconductors Inc. anchors high-volume production archetypes for mass-market OEM programs. These three entities collectively illustrate how geographic origin and corporate structure map to competitive positioning across premium and standard vehicle tiers.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| MediaTek Inc. |
| NXP Semiconductors |
| Samsung Semiconductors Inc. |
| Sony Corporation |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| Continental AG |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
EU Cybersecurity Regulation mandates for certified secure elements are compressing supplier qualification timelines and forcing OEMs to absorb premium cryptographic hardware costs into platform architectures.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for automotive-grade NFC controllers while secure element premiums hold firm. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels dominates procurement. Cost compression in mass-market controller tiers is intensifying because Japanese OEMs are consolidating high-volume programs. Fleet operators exhibit highest price sensitivity due to subscription-managed provisioning models, while German premium OEMs prioritize certification depth over unit cost.
Supply Chain Analysis
Freight costs from East Asian semiconductor clusters to European assembly plants are elevating landed costs for cryptographic hardware modules. Manufacturing concentrates in Germany, South Korea, and Japan for secure elements and controllers. Silicon wafer supply draws from Taiwan and Japan; rare earth elements for antenna substrates rest on Chinese processing. Single-source vulnerability pervades automotive-grade secure element foundry capacity. Distribution runs through Tier-1 system integrators with direct OEM qualification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive NFC Market functions as a stable compounder anchored by regulatory mandates that embed hardware into vehicle architectures regardless of cyclical demand swings.
For Market Incumbents: Extend platform standardization efforts to compress certification timeline friction and defend against BLE substitution in mid-market digital key programs. Secure element specialists should deepen backward integration into wafer supply to mitigate foundry concentration risk. Incumbents must monitor CCC Digital Key specification evolution to maintain parallel certification competence. For New Entrants and Emerging Players: Biometric authentication hardware with liveness detection capabilities offers a technology-first wedge into European premium vehicle programs facing EU AI Act conformity deadlines. Mass-market controller supply for Indian domestic production represents the most penetrable geography. New entrants should pursue direct fleet-operator provisioning partnerships to bypass entrenched dealer-channel relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor houses holding dual automotive-grade and cryptographic certification competence. The five-to-ten year viability window favors secure element specialists with Common Criteria EAL4+ qualification depth. Watch for CCC Digital Key Release 3.0 specification finalization as an inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Certification Investment | Common Criteria EAL4+ qualification unlocks EU Cybersecurity Regulation-mandated procurement in Stuttgart and Munich OEM programs. |
| Biometric Authentication Hardware Development | Liveness detection modules satisfy EU AI Act delegated acts for AI-enabled vehicle access systems. |
| Fleet-Operator Direct Provisioning Partnership | Subscription-managed credential platforms displace dealer-channel distribution in North American commercial vehicle segments. |
| Mass-Market Controller Capacity Expansion | High-volume production for Japanese compact vehicle platforms captures share previously limited to premium tiers. |
| Vehicle-to-Grid Authentication Integration | Bidirectional NFC tunnels enable encrypted EV charging authorization with utility billing infrastructure. |
Research Approach
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, secure element certification specialists, and fleet operations managers grounded qualitative findings. Secondary validation drew from UNECE WP.29 documentation, EU Cybersecurity Regulation delegated acts, FCC spectrum allocation filings, and vehicle production databases. Bottom-up unit economics triangulated against top-down market sizing across segmentation dimensions.
Segmentation outputs across product type, technology protocol, application criticality, and end-user procurement authority structured the analytical framework. CAGRs derived from installed base penetration curves and content-per-vehicle expansion trajectories. Modeled inputs included OEM platform launch timelines, certification deadline compliance schedules, and fintech partnership formation rates.
The model holds under stable regulatory enforcement timelines; deviation in cybersecurity certification deadline extensions or spectrum policy shifts would shift supplier qualification pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Automotive Console Box Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market