
 Railway Digital Signal Axle Counters Market | 2026-2036
Railway Digital Signal Axle Counters Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Digital Signal Axle Counters Market Insights
The widening gap between premium integrated systems and basic standalone units is repositioning procurement strategies across rail networks. Siemens leverages its ERTMS ecosystem to bundle axle counters with signaling platforms, while Thales Group anchors its position through deep integration with traffic management systems. Frauscher Sensor Technology Group specializes in high-precision electromagnetic sensor arrays for extreme climate corridors.
Railway digital signal axle counters are trackside safety devices that detect train presence by counting wheelsets entering and exiting a track section, typically achieving detection accuracy within milliseconds through digital signal processing algorithms. These systems replace vulnerable track circuits in poor-ballast or wet-rail conditions, serving as critical inputs to interlocking and automatic train protection architectures. Integrated Systems command the dominant share of procurement budgets as infrastructure managers seek unified signaling platforms, while Wireless Counters represent the fastest-expanding technology segment where trenching costs or bridge retrofits prohibit cable runs. Optical Sensors carve out a defensible niche in high-electromagnetic-interference environments near traction power substations.
The EU's ERTMS deployment mandates and F-Gas Regulation for sustainable infrastructure are compelling European rail operators to specify interoperable digital axle counters with embedded cybersecurity protocols. India's CEA signaling standards and BIS electromagnetic compatibility certifications are shaping product design requirements for suppliers targeting the Dedicated Freight Corridor and metro markets. Stakeholders must weigh the total cost of ownership between retrofitting legacy track circuits and migrating to cloud-integrated axle counting architectures as network digitization accelerates.
Market Dynamics
The convergence of ERTMS-mandated signaling modernization and fiber-optic backhaul expansion is compressing procurement cycles for integrated axle counting platforms. Infrastructure managers now specify unified architectures rather than standalone devices, forcing vendors to bundle cybersecurity, remote diagnostics, and interlocking compatibility into base configurations.
Growth Catalysts
- EU F-Gas Regulation:The European framework for sustainable infrastructure compels rail operators to replace legacy track circuits with low-maintenance digital axle counters, accelerating tender volumes across German and French networks.
- India's Dedicated Freight Corridors:The Dedicated Freight Corridor Corporation of India mandates axle counting for 3,300 route-kilometers of new heavy-haul track, creating concentrated procurement of IP67-rated outdoor units.
- Optical wheel detection:Photoelectric sensor arrays eliminate electromagnetic interference near traction substations, opening deployment in high-voltage corridors previously restricted to track circuits.
Market Restraints
- Copper and rare-earth magnet costs:Sensor housings and electromagnetic cores face input price volatility from concentrated Chinese processing capacity, squeezing margins on mid-tier product lines.
- Legacy interlocking lock-in:British and Japanese networks maintain proprietary signaling protocols that fragment demand for standardized axle counter interfaces, extending sales cycles.
- Track circuit substitution in temperate climates:Well-drained ballast and dry rail conditions in Australian and South African networks sustain demand for cheaper impedance-based detection, capping axle counter penetration.
Strategic Opportunities
- Urban metro greenfield builds:Vietnam and Indonesia are tendering driverless metro lines requiring SIL 4-certified axle counting with integrated platform screen door interfaces, creating first-mover advantages for certified suppliers.
- Cloud-native diagnostic platforms:Edge computing architectures enable predictive maintenance algorithms that unbundle hardware sales from recurring software subscriptions, shifting revenue toward SaaS models.
- CEA signaling standard harmonization:India's Central Electricity Authority is consolidating state-level specifications, reducing certification duplication costs for suppliers targeting the Eastern and Western Dedicated Freight Corridors.
Industry Challenges
- SIL 4 functional safety engineering talent:The scarcity of certified safety architects extends product development timelines by 8-14 months for new entrants seeking TÜV or DEKRA certification.
- Legacy analog interlocking integration:Retrofit projects require custom protocol gateways to bridge 1980s-era relay logic with modern digital axle counters, inflating commissioning costs and failure modes.
- Cross-border electromagnetic compatibility testing:Divergent BIS, CE, and FCC emission standards force redundant certification campaigns for multi-region suppliers, compressing effective addressable markets per product variant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Digital Signal Axle Counters Market |
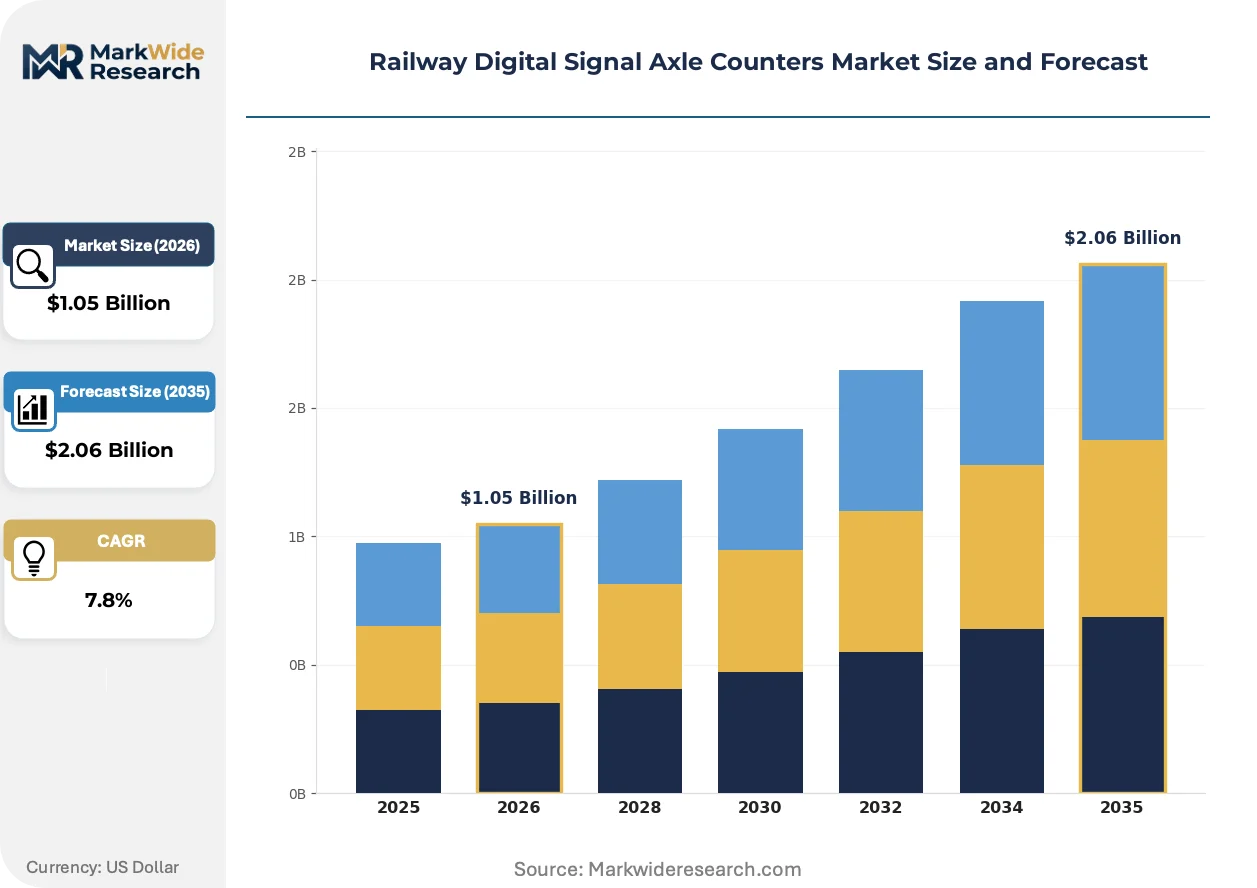
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Standalone Units, Wireless Counters, Advanced Signal Counters End User: Rail Operators, Maintenance Providers, Infrastructure Managers, Safety Authorities Technology: Electromagnetic Sensors, Optical Sensors, Digital Signal Processing, Cloud Integration Application: Passenger Trains, Freight Trains, Light Rail, Subways |
| Companies Covered | Siemens, Thales Group, Alstom, Frauscher Sensor Technology Group, Voestalpine AG, CLEARSY, Scheidt & Bachmann, Bombardier, Hitachi Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Digital Signal Axle Counters Market Trends and Innovations
Wireless telemetry and edge analytics are dissolving the traditional boundary between trackside hardware and central traffic management. Vendors now compete on data architecture rather than sensor precision alone.
Frauscher Advanced Counter FAdC architecture is decentralizing wheel detection processing by embedding digital signal processors directly at rail-mounted sensor heads. This eliminates copper multicore cables to centralized evaluation units. Deutsche Bahn and SNCF Réseau are piloting these distributed nodes on bridge approaches and tunnel sections where trenching costs exceed hardware premiums by factors of three to five. The shift is compressing maintenance windows and enabling granular section-by-section upgrades without corridor-wide shutdowns.
EU F-Gas Regulation mandates phase-down of sulfur hexafluoride in electrical infrastructure, indirectly accelerating axle counter deployment by disqualifying gas-insulated track circuit alternatives in new-build tenders. Infrastructure managers in Poland and Spain are specifying fully electronic detection to preempt compliance exposure. The regulation is reshaping competitive positioning toward vendors with integrated power-over-Ethernet designs that eliminate high-voltage switching gear.
Rail operators are unbundling long-term service contracts from initial hardware procurement, separating detection equipment sales from 15-year maintenance and software update obligations. Infrastructure managers in the Nordic countries and Netherlands are tendering these elements through distinct budget lines, forcing axle counter suppliers to establish local technical service subsidiaries or partner with regional rail maintenance firms. The practice is most visible in Sweden, where Trafikverket mandates Swedish-language support centers as a contract award criterion.
Railway Digital Signal Axle Counters Market Segmentation
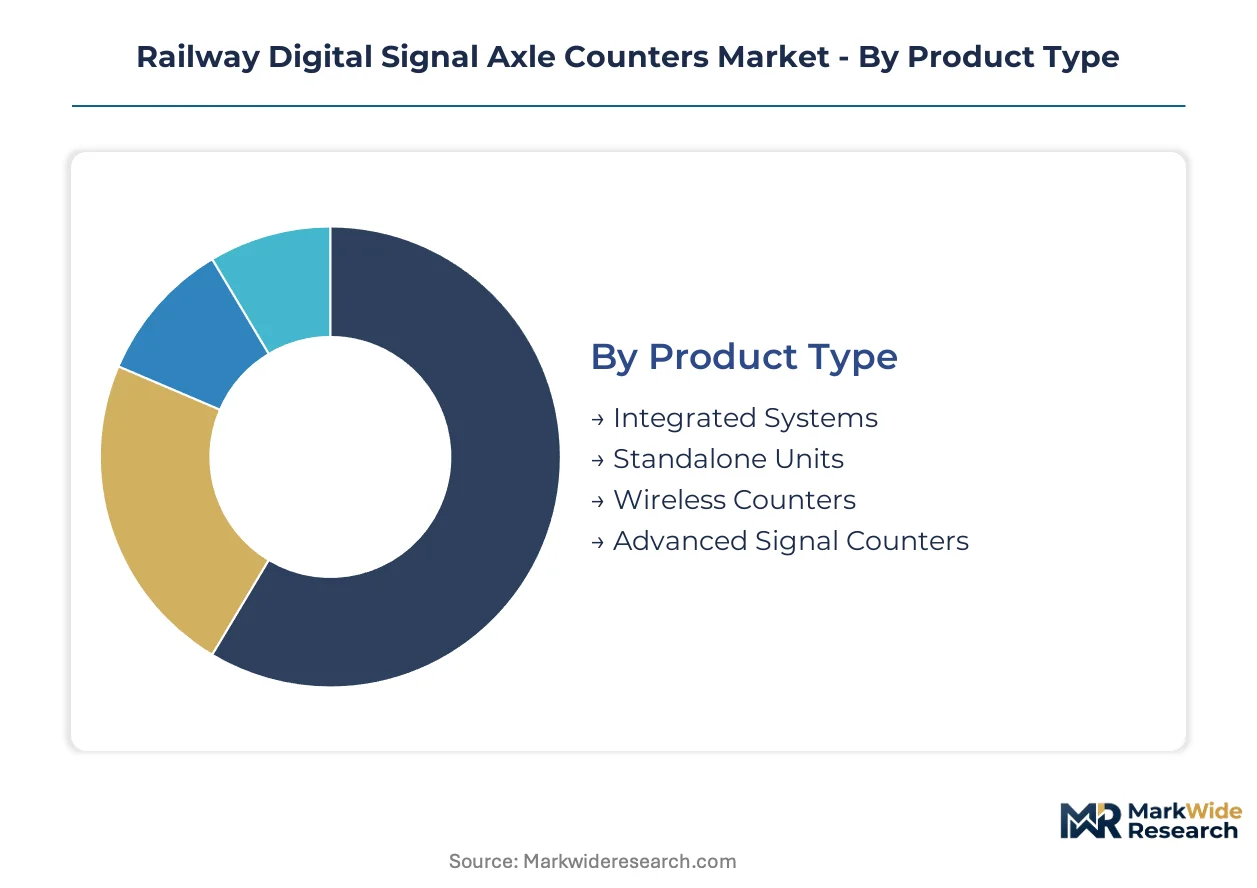
Axle counter procurement patterns diverge sharply between integrated platform buyers and standalone unit purchasers. Infrastructure managers weigh lifecycle costs against interoperability requirements when segmenting their signaling modernization budgets.
Product Type:
Supply concentration tilts toward vendors bundling hardware with signaling software ecosystems.
- Integrated Systems:Unified architectures combine wheel detection, interlocking interfaces, and remote diagnostics in single procurement packages. Deutsche Bahn and SNCF Réseau specify these for ERTMS corridor upgrades where protocol compatibility eliminates commissioning delays.
- Wireless Counters:Battery-powered radio units eliminate trenching on bridge approaches and tunnel sections. Deployment concentrates in Alpine corridors and Southeast Asian metro retrofits where civil works costs exceed hardware premiums.
- Standalone Units:Basic wheel detection for legacy interlocking retrofits.
- Advanced Signal Counters:Embedded edge computing for predictive maintenance algorithms.
Integrated Systems absorb the bulk of installed capacity; Wireless Counters are expanding most quickly.
End User:
Procurement authority fragmentation shapes vendor go-to-market strategies across the value chain.
- Infrastructure Managers:State-owned track authorities in Germany, France, and India hold concentrated budgets for corridor-wide signaling renewals. Their tenders specify SIL 4 certification and 25-year service life guarantees, consolidating demand among qualified suppliers.
- Rail Operators:Passenger and freight carriers purchase axle counters for depot automation and terminal capacity expansion. ÖBB and Indian Railways tender these separately from national infrastructure budgets, creating secondary demand pools.
- Maintenance Providers:Specialized contractors in Nordic markets bundle detection hardware with long-term service contracts.
- Safety Authorities:Regulatory bodies in Japan and Britain mandate specific electromagnetic compatibility standards that fragment procurement specifications.
Infrastructure Managers command the largest procurement volumes; Rail Operators show the steepest expansion trajectory as depot automation accelerates.
Technology:
Component sourcing geography influences technology selection for electromagnetic versus optical detection.
- Electromagnetic Sensors:Inductive wheel detection coils embedded between rails remain the dominant architecture. Manufacturing concentrates in German and Austrian supplier facilities where precision winding equipment and rare-earth magnet processing create captive supply advantages.
- Digital Signal Processing:FPGA-based algorithms filter rail vibration noise and wheel flat spots. Deployment concentrates in high-speed corridors where millisecond detection latency determines braking curve calculations.
- Optical Sensors:Photoelectric arrays eliminate electromagnetic interference near traction substations.
- Cloud Integration:Edge-to-cloud telemetry architectures enable predictive maintenance subscriptions.
Electromagnetic Sensors retain the dominant installed base; Digital Signal Processing is climbing the fastest as detection latency requirements tighten.
Application:
Traffic density and axle load specifications segment demand across rail modes.
- Freight Trains:Heavy-haul detection must accommodate 32.5-ton axle loads and distributed power configurations. India's Dedicated Freight Corridors specify IP67-rated outdoor units for 3,300 route-kilometers of new track, concentrating procurement among ruggedized product lines.
- Subways:Driverless metro lines require SIL 4-certified counting with platform screen door interfaces. Hanoi and Jakarta greenfield tenders specify these for unattended train operation, creating certification barriers for uncertified entrants.
- Passenger Trains:High-speed detection for 300+ km/h operation with minimal maintenance windows.
- Light Rail:Street-running tram detection with embedded pavement sensors.
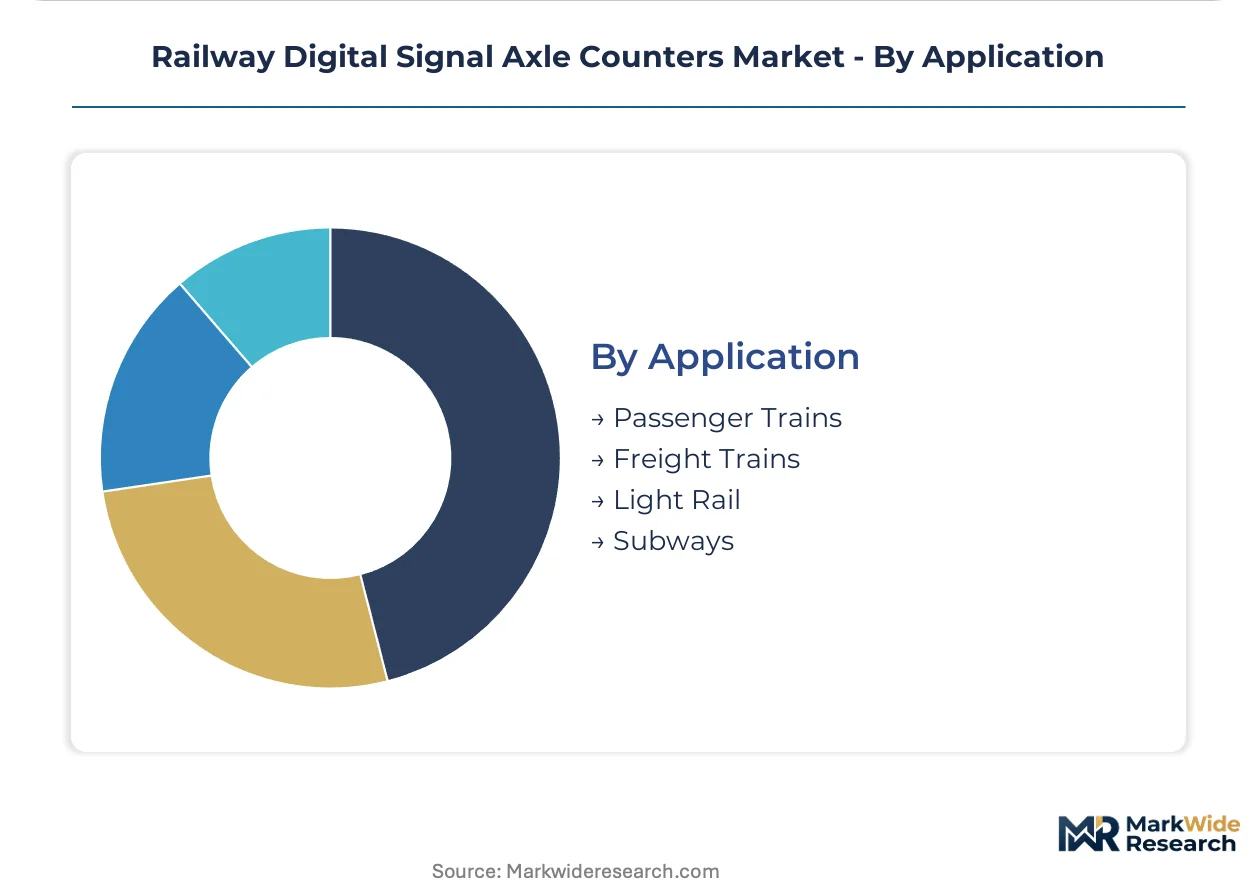
Freight Trains account for the majority of new-build detection capacity; Subways are gaining share fastest as Asian metro construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Pune industrial corridor concentrates India's axle counter procurement as Dedicated Freight Corridor Corporation accelerates signaling deployment across 3,300 route-kilometers of heavy-haul track. This corridor anchors Asia-Pacific demand alongside Germany's Ruhr industrial cluster and France's high-speed rail network.
India
The Eastern and Western Dedicated Freight Corridors mandate axle counting systems for 32.5-ton axle load operations. CEA signaling standards and BIS electromagnetic compatibility certifications shape product specifications for suppliers. Manufacturing concentrates in Pune and Chennai where rail component suppliers cluster around Indian Railways maintenance depots.
Germany
Deutsche Bahn's ERTMS corridor upgrades drive procurement of integrated axle counting platforms with embedded cybersecurity protocols. EU F-Gas Regulation disqualifies gas-insulated track circuits in new tenders. Production gravity centers on Munich and Nuremberg where precision sensor manufacturers supply Alpine corridor retrofits.
France
SNCF Réseau pilots distributed axle counter nodes on bridge approaches where trenching costs exceed hardware premiums. EU Green Deal infrastructure mandates accelerate replacement of legacy detection systems. Industrial activity clusters around Paris-Saclay and Lyon where rail technology suppliers coordinate with traffic management system integrators.
China
High-speed rail network expansion sustains demand for millisecond-latency wheel detection on 300+ km/h corridors. GB standards and MIIT rail equipment certifications govern procurement specifications. Manufacturing concentrates in Changzhou and Zhuzhou where electromagnetic sensor production serves domestic and export markets.
United States
Freight railroads deploy axle counters in poor-ballast territories where track circuits fail during wet-rail conditions. FRA safety regulations and AAR interoperability standards guide system specifications. Activity concentrates in Chicago rail hub and Texas freight corridors where BNSF and Union Pacific modernize detection infrastructure.
Railway Digital Signal Axle Counters Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the axle counter value chain, creating a tiered market structure where integrated platform vendors capture premium procurement while specialized sensor suppliers serve retrofit niches. The vendor base stratifies into three strategic archetypes: diversified signaling conglomerates bundling axle counters with interlocking ecosystems; precision sensor specialists focused on electromagnetic detection hardware; and regional system integrators serving national rail operators with customized protocol adaptations. Dominant competitive moves include backward integration into rare-earth magnet processing and strategic partnerships with cloud infrastructure providers for predictive maintenance platforms.
Within the diversified signaling tier, Siemens and Thales Group exemplify platform-centric positioning through their ERTMS ecosystem integration, while Frauscher Sensor Technology Group anchors the precision sensor specialist archetype with electromagnetic array manufacturing. These three entities represent contrasting strategic postures: the German conglomerate and French systems integrator compete on unified architecture breadth, whereas the Austrian specialist occupies defensible positioning in extreme-climate corridor applications where detection precision commands procurement priority.
| Leading Market Players |
|---|
| Siemens |
| Thales Group |
| Alstom |
| Frauscher Sensor Technology Group |
| Voestalpine AG |
| CLEARSY |
| Scheidt & Bachmann |
| Bombardier |
| Hitachi Rail |
| Others |
Pricing and Supply Chain Analysis
Certified SIL 4 safety architects concentrated in southern Germany and eastern Austria command wage premiums that widen spreads between premium integrated platforms and economy standalone units. Infrastructure managers absorb these labor-cost differentials through tiered procurement strategies that separate ERTMS-mandated corridor upgrades from legacy retrofit budgets.
Pricing Analysis
Uptime guarantees anchor value-based pricing for integrated axle counting platforms serving high-speed rail corridors. Pricing stratifies across premium, standard, and economy tiers based on SIL certification grade and bundled remote diagnostics scope. Cost compression in the mid-tier segment intensifies because Chinese rare-earth processing volatility squeezes electromagnetic sensor margins. Freight operators show the highest price sensitivity, prioritizing per-unit hardware costs over lifecycle service contracts, while infrastructure managers in Germany and France prioritize interoperability premiums.
Supply Chain Analysis
Freight costs from Austrian precision sensor manufacturers to Indian Dedicated Freight Corridor sites amplify landed costs for electromagnetic detection arrays. Manufacturing concentrates in Germany, Austria, and China, with rare-earth magnet processing and FPGA fabrication drawing from concentrated East Asian supply nodes. Single-source vulnerability in neodymium magnet supply chains exposes mid-tier vendors to input price shocks. Distribution runs through rail technology integrators who bundle hardware with commissioning services and 15-year maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU F-Gas Regulation and India's CEA signaling standards erect certification barriers that protect incumbent positions. The regulatory moat deepens as infrastructure managers specify embedded cybersecurity protocols and 25-year service guarantees that extend product development timelines for uncertified entrants.
For Market Incumbents: To counter margin erosion from rare-earth input volatility, pursue backward integration into magnet processing partnerships or captive sensor coil winding capacity in lower-cost European manufacturing zones. Prioritize cloud-native diagnostic platform investments that unbundle hardware sales from recurring SaaS revenue streams, reducing exposure to commodity-driven hardware pricing cycles. For New Entrants and Emerging Players: Launch via wireless counter retrofit packages targeting Southeast Asian metro greenfield builds in Vietnam and Indonesia, where trenching-prohibited bridge approaches create procurement flexibility outside ERTMS-mandated specifications. Penetrate the depot automation segment serving freight operators in the United States and Australia, where impedance-based track circuit substitution sustains demand for standalone units with lower certification burdens. For Investors and Strategic Acquirers: The window for entry favors precision sensor specialists with captive electromagnetic array manufacturing and existing TÜV or DEKRA safety certifications. Long-term viability hinges on consolidation plays that combine hardware manufacturing with predictive maintenance software capabilities. Monitor India's CEA signaling standard harmonization progress as the inflection signal for reduced certification duplication costs and expanded addressable market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Processing | Austrian and German manufacturers secure captive supply advantages against Chinese processing volatility. |
| Cloud-Native Diagnostic Platform Launch | Edge-to-cloud telemetry architectures enable predictive maintenance subscriptions for Nordic infrastructure managers. |
| SIL 4 Certification Investment | TÜV and DEKRA safety credentials unlock ERTMS corridor procurement in Germany and France. |
| Wireless Counter Product Line Expansion | Battery-powered radio units penetrate Alpine corridors and Southeast Asian metro retrofits with prohibitive trenching costs. |
| Regional Technical Service Subsidiary Establishment | Swedish-language support centers satisfy Trafikverket procurement mandates and 15-year maintenance contract requirements. |
Research Methodology
Regulatory filings from EU F-Gas implementation reports, Indian Railways tender documentation, and Deutsche Bahn infrastructure investment disclosures formed the secondary backbone for market sizing and procurement cycle analysis. Primary interviews with signaling system procurement officers at infrastructure managers, SIL certification engineers at TÜV and DEKRA, and maintenance directors at Nordic rail operators validated demand assumptions and technology adoption timelines. Bottom-up unit deployment estimates across Dedicated Freight Corridor segments and top-down infrastructure budget allocations were triangulated to anchor volume projections.
Bottom-up modeling segmented the market by product architecture, end-user procurement authority, detection technology, and rail application mode across the projection horizon. CAGRs were derived from tender pipeline analysis and replacement cycle assumptions for legacy track circuits, with ERTMS deployment mandates and F-Gas Regulation compliance deadlines serving as structural demand anchors. Forecast inputs incorporated rare-earth magnet price indices, electromagnetic compatibility certification timelines, and fiber-optic backhaul expansion rates in target corridors.
Input cost volatility in rare-earth processing, regulatory delays in CEA standard harmonization, and legacy interlocking protocol fragmentation are the dominant revision risks that could compress or extend procurement cycles. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Tugger Trains Market
Railway
Railway System Market
Railway
Gearbox for Rail Vehicles Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Trams Market
Railway
South Africa Rail Freight Transport Market
Railway
40-Foot Platform Wagons Market
Railway
Rail Glazing Market
Railway
Global Hyperloop Train Market
Railway
Train Suspension System Market
Railway
Check Rails Market
Railway
Solar Train Market
Railway
Road-Rail Vehicles Market
Railway
Global Train Lighting Market
Railway
Heritage Railways Trains Market
Railway
Train HVAC Market