
 Train HVAC Market | 2026-2036
Train HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Train HVAC Market Analytics
European rolling stock component manufacturers is repositioning capacity toward modular HVAC architectures for next-generation electric multiple units. Siemens Mobility leverages its cross-border project portfolio to sustain specification influence across Deutsche Bahn and SNCF networks. Alstom anchors European high-speed rail climate systems through integrated propulsion-thermal design. Knorr-Bremse competes on brake-thermal synergy, extending its platform into complementary HVAC control modules.
Train HVAC encompasses the engineered climate control systems—compressor-driven chillers, air handling units with HEPA filtration, and distributed fan coil arrays—that regulate temperature, humidity, and air quality within rolling stock carriages operating across variable ambient conditions from desert transit to subarctic freight corridors. These systems typically maintain cabin temperatures between 18°C and 24°C while managing latent loads from passenger density and door-cycle infiltration. Heat pumps now represent the fastest-growing product category as operators phase out legacy direct-expansion cooling tied to high-GWP refrigerants, while rolling stock manufacturers command the deepest specification influence by embedding HVAC requirements into original tender documents rather than retrofitting existing fleets. Control systems technology concentrates margin pools through software-defined predictive maintenance and energy optimization algorithms.
The EPA refrigerant phase-down under AIM Act provisions and the EU F-Gas Regulation jointly constrain hydrofluorocarbon selection for new train HVAC installations, pushing manufacturers toward CO2 and hydrocarbon alternatives. China's NMPA-aligned railway standards and Japan's METI energy-efficiency benchmarks for rail transport add compliance layers for multinational suppliers serving cross-border tenders. Stakeholders must monitor refrigerant transition timelines and regional certification reciprocity to avoid stranded engineering investments as thermal regulations diverge across major procurement jurisdictions.
Market Dynamics
The refrigerant transition mandated by the EPA AIM Act and EU F-Gas Regulation is restructuring supplier relationships as CO2 and hydrocarbon architectures displace legacy HFC systems across new rolling stock procurement.
Growth Catalysts
- Heat pump adoption:Rail operators in Germany and France are specifying reversible heat pumps for year-round thermal management, eliminating separate heating and cooling hardware stacks.
- China's NMPA railway standards:Stricter thermal efficiency benchmarks for high-speed corridors are forcing fleet renewals with climate-controlled carriages across CRRC supply chains.
- Desert corridor expansion:Saudi Arabia's Riyadh-Dammam line and UAE freight networks require HVAC systems engineered for 50°C ambient operation, opening specialized procurement channels.
Market Restraints
- Copper-aluminum price volatility:Heat exchanger materials account for substantial system cost, and LME price swings compress margin predictability for tier-two component fabricators.
- Compressor supply concentration:Scroll and screw compressor manufacturing clusters in Germany and Japan create single-source vulnerability for EMU builders outside those supply orbits.
- Refrigerant certification reciprocity gaps:China's GB standards and EU F-Gas testing protocols lack mutual recognition, forcing redundant validation spend for cross-border tenders.
Strategic Opportunities
- India's dedicated freight corridors:The Dedicated Freight Corridor Corporation's electrified routes lack climate infrastructure, creating first-mover positioning for HVAC-integrated locomotive cab systems.
- Predictive maintenance software:Sensor-embedded air handling units enable outcome-based service contracts that capture lifetime value beyond hardware margins.
- Japan's METI rail efficiency mandates:Energy consumption targets for the Shinkansen network are accelerating demand for regenerative thermal recovery systems in N700S series refits.
Industry Challenges
- Refrigerant technician scarcity:CO2 transcritical system servicing requires pressure-rated certification that existing rail maintenance depots rarely hold, slowing fleet commissioning.
- Legacy 400V electrical integration:New HVAC control architectures must interface with mid-life rolling stock using outdated power bus standards without triggering full carriage rewiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train HVAC Market |
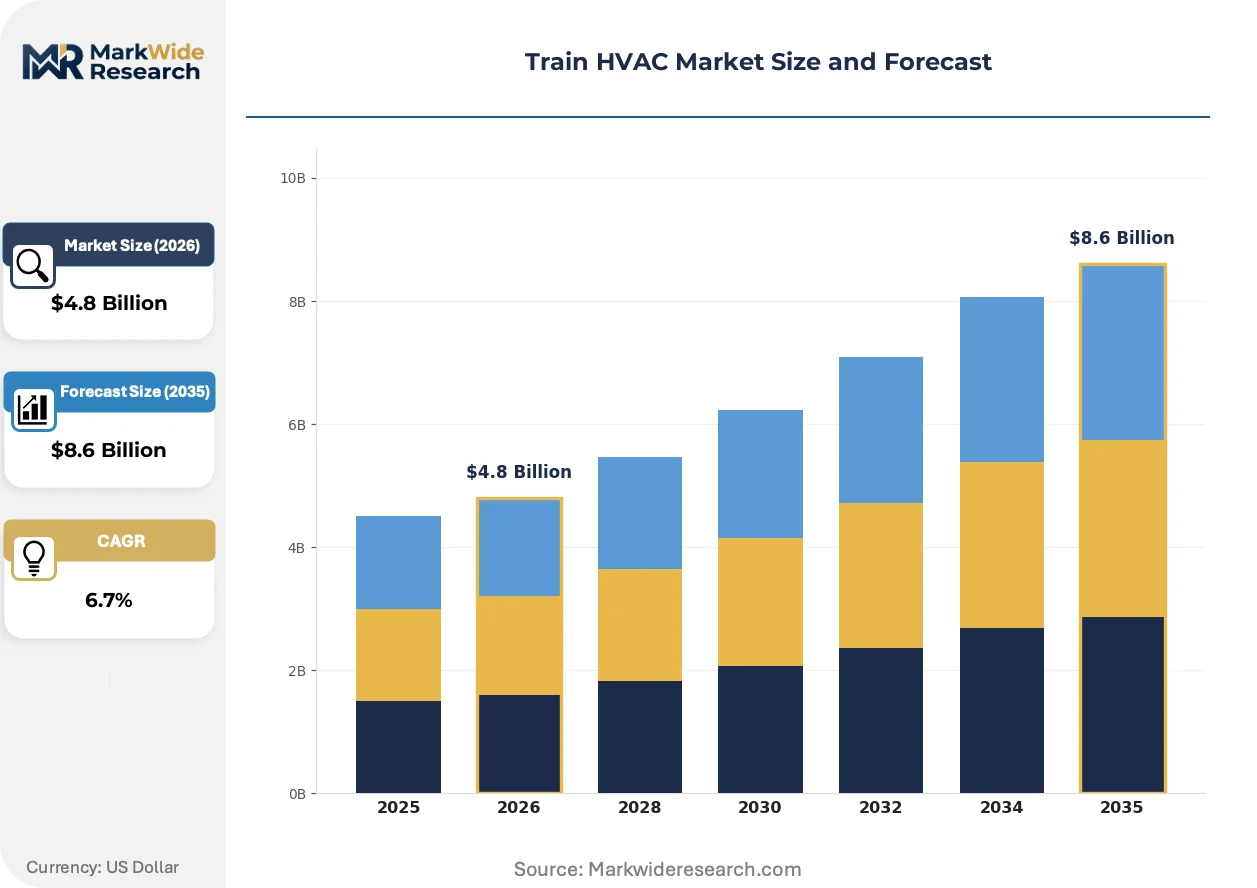
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Air Handling Units, Fan Coil Units, Heat Pumps End User: Rail Operators, Transport Authorities, Rolling Stock Manufacturers, Maintenance Providers Technology: Refrigeration, Ventilation, Thermal Management, Control Systems Application: Passenger Trains, Freight Trains, High-Speed Trains, Light Rail |
| Companies Covered | Hitachi Rail, Alstom, Knorr-Bremse, Thales, CRRC, Wabtec Corporation, Siemens Mobility, Schwitches, Faiveley Transport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train HVAC Market Evolving Landscape
Digitalization of thermal management is compressing maintenance cycles and enabling energy arbitrage across variable electricity tariffs, while refrigerant chemistry shifts force parallel hardware redesigns.
CO2 transcritical refrigeration is consolidating market share in European high-speed rail specifications as the EU F-Gas Regulation phases down HFC quotas. Deutsche Bahn and SNCF are embedding transcritical chillers into their 2025-2030 EMU tenders. The technology is consolidating supplier tiers by demanding in-house gas cooler fabrication capabilities that smaller HVAC houses cannot replicate.
The EPA's refrigerant phase-down under AIM Act provisions is compelling US commuter rail operators to abandon R-410A in favor of A2L-class alternatives. California's Air Resources Board has accelerated compliance timelines for state-funded projects. Transit agencies in the Northeast Corridor are responding by bundling HVAC upgrades with mid-life overhauls to avoid stranded asset risk.
Condition-based maintenance contracts are displacing scheduled parts replacement across Asian-Pacific fleet operators. Japanese and Australian rail asset managers now specify predictive algorithms for filter and compressor lifecycle management. This shift is most visible in Australia's interstate passenger networks, where remote monitoring infrastructure reduces trackside inspection frequency across the Nullarbor corridor.
Train HVAC Market Segmentation
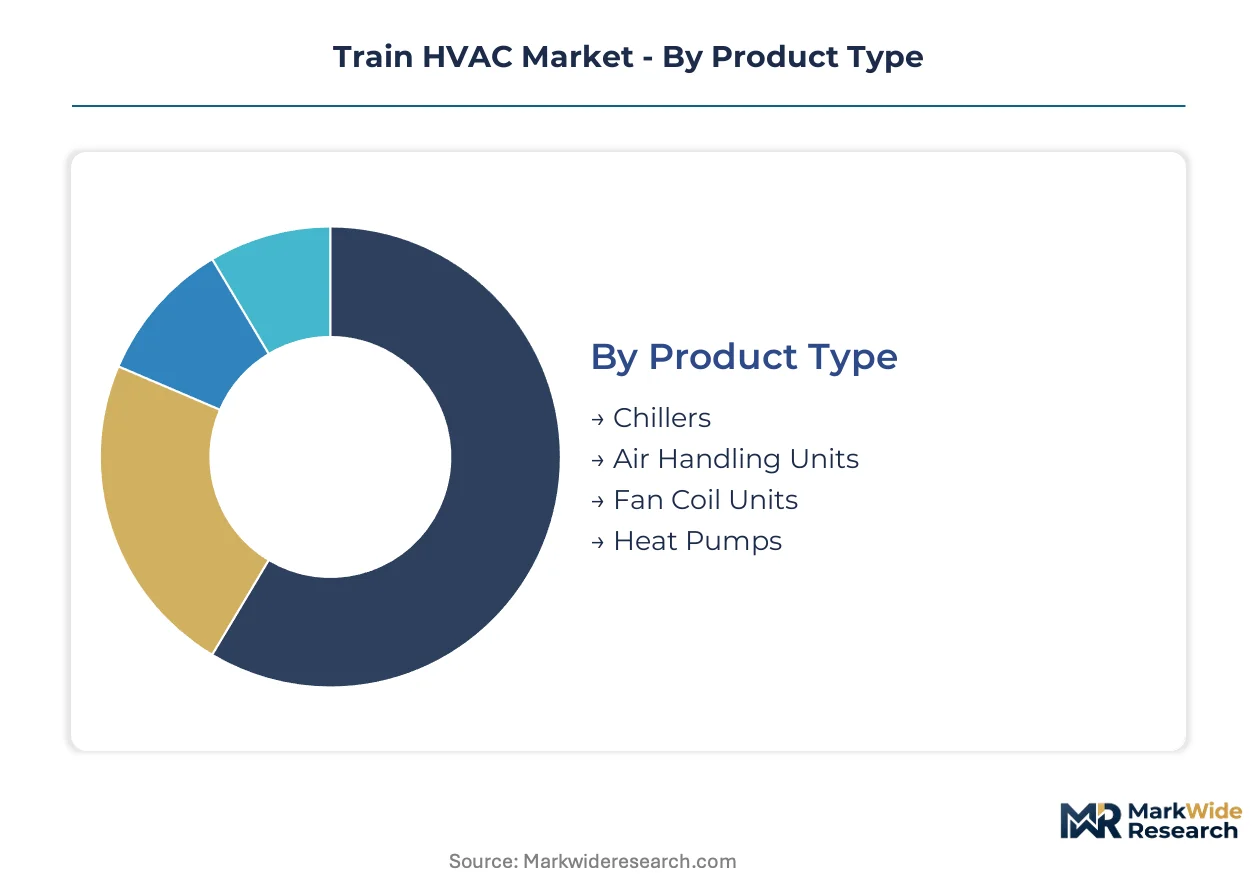
Train HVAC procurement divides across hardware specifications, operator types, and thermal technology architectures. Segment boundaries blur where rolling stock manufacturers embed climate systems into original tenders rather than allowing aftermarket selection.
Product Type:
Customization intensity varies from standardized fan coil arrays to bespoke chiller configurations engineered for extreme ambient corridors.
- Chillers:Compressor-driven refrigeration circuits with capacity ratings from 15kW to 80kW serve high-speed trainsets requiring centralized cooling distribution. CRRC's high-speed fleet orders in China specify variable-speed scroll compressors to meet NMPA thermal efficiency mandates for desert-to-subarctic route profiles.
- Heat Pumps:Reversible vapor-compression systems eliminate separate heating hardware stacks through coefficient-of-performance optimization. Deutsche Bahn and SNCF procurement in Germany and France prioritizes these units for year-round energy arbitrage across variable electricity tariffs.
- Air Handling Units:HEPA-integrated filtration modules manage latent loads from passenger density and door-cycle infiltration in commuter corridors.
- Fan Coil Units:Distributed terminal devices provide zonal temperature control for light rail and metro configurations with frequent stop intervals.
Most installed capacity flows through chillers. Expansion is steepest in heat pumps.
End User:
Specification authority concentrates with entities that control tender documentation and lifecycle asset management.
- Rolling Stock Manufacturers:Alstom, Siemens Mobility, and CRRC embed HVAC requirements into original design specifications, capturing decision rights before operators enter procurement. Their integrated propulsion-thermal designs for European high-speed EMUs constrain aftermarket supplier access.
- Rail Operators:Deutsche Bahn, SNCF, and JR East leverage fleet-scale purchasing to mandate CO2 transcritical architectures and predictive maintenance software in renewal tenders.
- Transport Authorities:California's Air Resources Board and India's Dedicated Freight Corridor Corporation fund infrastructure projects with embedded climate system requirements.
- Maintenance Providers:Knorr-Bremse and specialized depot operators service installed base under outcome-based contracts spanning filter replacement and compressor lifecycle management.
Specification power rests with rolling stock manufacturers. Direct procurement volume is climbing fastest among rail operators.
Technology:
Hardware-software integration intensity separates mature mechanical systems from digitally enabled thermal architectures.
- Refrigeration:Vapor-compression circuits using CO2 transcritical or hydrocarbon refrigerants displace legacy HFC systems under EPA AIM Act and EU F-Gas Regulation phase-down schedules. European high-speed specifications now mandate gas cooler fabrication capabilities that consolidate supplier tiers.
- Control Systems:Sensor-embedded algorithms for predictive maintenance and energy optimization capture margin pools beyond hardware sales. Australian interstate networks deploy remote monitoring to reduce Nullarbor corridor trackside inspection frequency.
- Ventilation:Air exchange systems with heat recovery wheels manage fresh air ratios and pressure differentials across tunnel and open-track segments.
- Thermal Management:Integrated heat rejection and distribution networks coordinate multiple cabin zones through centralized or distributed architectures.
Refrigeration commands the largest installed base. Control systems are expanding most quickly.
Application:
Operating environment severity—from ambient temperature extremes to door-cycle frequency—determines system specification intensity.
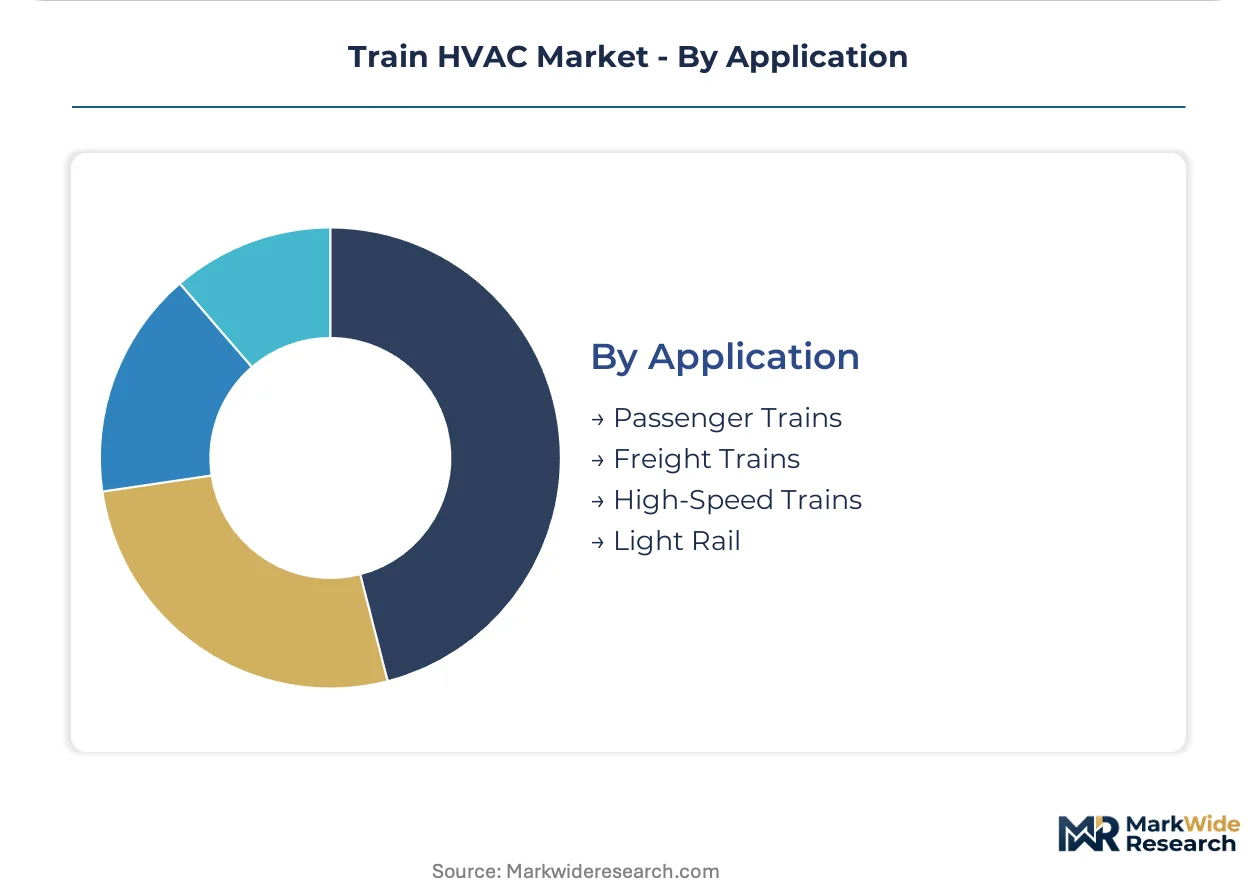
- High-Speed Trains:Aerodynamic sealing and continuous operation at 250km/h+ demand centralized chillers with 50°C ambient capability for Saudi Arabia's Riyadh-Dammam corridor and China's western high-speed network.
- Passenger Trains:Commuter and intercity services with frequent door cycles require latent load management through zonal fan coil arrays and humidity control.
- Light Rail:Stop-and-go operation with short headways prioritizes compact rooftop units with rapid compressor cycling tolerance.
- Freight Trains:Locomotive cab climate systems for India's electrified Dedicated Freight Corridor routes represent greenfield installation opportunity with minimal existing infrastructure.
High-speed trains absorb the dominant share of premium system value. Freight applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier footprints as manufacturers relocate fabrication capacity to jurisdictions with aligned certification reciprocity. Cost-of-compliance gaps between the EU F-Gas Regulation and China's GB standards are accelerating regional specialization in refrigerant system assembly.
China
CRRC's high-speed fleet renewals under NMPA thermal efficiency mandates are driving concentrated demand for variable-speed compressor architectures. The national railway regulator's stricter benchmarks for desert-to-subarctic route profiles are forcing climate-controlled carriage specifications across supply chains. Manufacturing clusters in Changchun and Qingdao are scaling CO2 transcritical chiller production for domestic and export tenders.
Germany
Deutsche Bahn's 2025-2030 EMU procurement prioritizes reversible heat pumps for year-round energy arbitrage across variable electricity tariffs. The KBA's integration with EU F-Gas compliance timelines is accelerating refrigerant transition investments. Siemens Mobility anchors specification influence from its Munich and Erlangen engineering centers, embedding HVAC requirements into cross-border tender documentation.
United States
Commuter rail operators in the Northeast Corridor are bundling HVAC upgrades with mid-life overhauls to avoid stranded asset risk under EPA AIM Act phase-down schedules. California's Air Resources Board has accelerated compliance timelines for state-funded projects. Transit agencies in Boston and New York Metro are responding with A2L-class refrigerant specifications in rolling stock renewal programs.
Japan
METI energy-efficiency benchmarks for the Shinkansen network are accelerating demand for regenerative thermal recovery systems in N700S series refits. JR East leverages fleet-scale purchasing to mandate predictive maintenance software in climate system tenders. Industrial concentration in Nagoya and Osaka supports integrated propulsion-thermal design capabilities for next-generation trainsets.
Saudi Arabia
The Riyadh-Dammam high-speed line requires HVAC systems engineered for 50°C ambient operation, opening specialized procurement channels for extreme-climate architectures. The national railway authority's thermal specifications are diverging from European templates. Engineering activity concentrates in Riyadh-based project offices coordinating with rolling stock manufacturers on gas cooler fabrication requirements.
Train HVAC Market Competitive Landscape
European producers anchor specification influence through integrated tender documentation; Chinese fabricators hold cost-optimized capacity for high-volume fleet orders. Market structure tilts toward consolidated tier-one positions where rolling stock manufacturers embed climate requirements into original designs. Three archetypes dominate: integrated system houses with propulsion-thermal bundling, specialized HVAC component fabricators, and control-software specialists capturing service contract value. Competitive intensity centers on refrigerant transition timing and cross-border certification reciprocity rather than price alone.
Among European-integrated system houses, Alstom and Siemens Mobility exemplify specification authority through embedded tender requirements. Knorr-Bremse occupies a position bridging brake-thermal synergy with complementary HVAC control module extension. These three represent distinct competitive vectors: Alstom anchors high-speed EMU climate integration; Siemens Mobility leverages cross-border project portfolios across Deutsche Bahn and SNCF networks; Knorr-Bremse extends platform adjacencies into thermal management software.
| Leading Market Players |
|---|
| Hitachi Rail |
| Alstom |
| Knorr-Bremse |
| Thales |
| CRRC |
| Wabtec Corporation |
| Siemens Mobility |
| Schwitches |
| Faiveley Transport |
| Others |
Value Network & Pricing Analysis
Rolling stock manufacturers in Europe and China command specification authority that compresses channel margins for tier-two component suppliers. Their embedded tender requirements eliminate aftermarket competition and force HVAC houses to absorb cost volatility from raw material markets.
Pricing Analysis
Direct-to-OEM contracting dominates, with rolling stock builders extracting volume discounts through consolidated fleet procurement. Price differentiation rests on refrigerant certification tier and predictive maintenance software bundling. Cost compression in scroll compressor assemblies is intensifying because copper-aluminum price volatility erodes fabricator margins. Freight operators in India and maintenance providers in Australia exhibit the sharpest price sensitivity, while European high-speed rail tenders prioritize energy efficiency over unit cost.
Supply Chain Analysis
EU F-Gas and EPA AIM Act certification requirements gate supplier access to European and North American tenders, forcing redundant validation spend. Manufacturing concentrates in Germany, China, and Japan. Heat exchanger fabrication draws from LME-traded copper and aluminum coil. Single-source vulnerability pervades scroll compressor supply from German and Japanese clusters. Distribution runs through rolling stock OEM specification teams rather than independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump adoption and refrigerant transition timelines create margin expansion through premium-tier CO2 transcritical system positioning. Control software bundling captures lifetime service value beyond hardware sales.
For Market Incumbents: Cement specification influence by embedding HVAC requirements into cross-border tender documentation before operators enter procurement. Deepen in-house gas cooler fabrication capabilities to meet EU F-Gas consolidation pressures. Acquire predictive maintenance software specialists to defend against control-system entrants.
For New Entrants and Emerging Players: India's Dedicated Freight Corridor Corporation represents an underserved buyer archetype with zero installed base and minimal legacy integration constraints. Target extreme-climate engineering for Saudi Arabia's Riyadh-Dammam corridor where European templates fail. Pursue outcome-based service contracts as the go-to-market angle to bypass hardware margin compression.
For Investors and Strategic Acquirers: Rolling stock OEMs are the most active acquirer in this space, seeking thermal management capabilities to complement propulsion integration. Long-term viability hinges on refrigerant transition execution and cross-border certification reciprocity. Monitor EPA AIM Act enforcement intensity and EU F-Gas quota auction prices as inflection indicators for stranded asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Chiller Platform Development | Positions suppliers for Deutsche Bahn and SNCF 2025-2030 EMU tenders under EU F-Gas phase-down. |
| Predictive Maintenance Software Acquisition | Enables outcome-based service contracts that capture lifetime value beyond hardware margins for JR East and Australian networks. |
| Extreme-Climate Engineering Partnership | Opens specialized procurement channels for Saudi Arabia's Riyadh-Dammam line requiring 50°C ambient capability. |
| Refrigerant Certification Reciprocity Investment | Reduces redundant validation spend for cross-border tenders spanning China's GB standards and EU F-Gas protocols. |
| Heat Pump Reversible Architecture Launch | Eliminates separate heating hardware stacks for German and French rail operators pursuing year-round energy arbitrage. |
Research Methodology
Coverage spans Asia-Pacific, Europe, North America, and Middle East corridors, with primary inputs from each. The analysis combines interviews with rolling stock procurement directors, HVAC engineering leads at tier-one suppliers, railway operator asset managers, and refrigerant regulatory specialists. Secondary validation draws from EPA AIM Act filings, EU F-Gas Regulation quota data, CRRC tender documentation, and METI efficiency benchmark disclosures. Bottom-up and top-down triangulation cross-checks component-level cost buildups against fleet-scale procurement values.
Granularity extends to product type, end user archetype, technology architecture, and application severity across the projection horizon. Segmentation models capture chiller capacity ratings, heat pump reversibility specifications, control system software intensity, and operating environment temperature bands. CAGRs derive from fitted growth curves anchored to fleet renewal cycles and regulatory compliance deadlines. Forecast inputs include CRRC high-speed order flows, Deutsche Bahn EMU procurement schedules, and refrigerant transition timelines.
Underlying measurement precision varies by segment; high-speed train applications carry tighter precision than freight locomotive cabs given tender documentation availability. Forecasts embed assumptions around NMPA thermal efficiency mandate enforcement and EU-China certification reciprocity progress. A model refresh is warranted upon material change in EPA refrigerant phase-down velocity or copper-aluminum LME price regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Asia Pacific Rail Freight Transport Market
Railway
Rail Brace Market
Railway
Automatic Train Supervision Market
Railway
Latin America Connected Rail Market
Railway
Solar Train Market
Railway
Railway Window Market
Railway
Locomotive Radiator Fan Market
Railway
Gearbox for Rail Vehicles Market
Railway
Hydrogen Trains Market
Railway
Rail Composites Market
Railway
Railroad Brake Shoe Market
Railway
Railway Axle Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Railway Pantograph Market
Railway
Freight Cars Market
Railway
Railway System Market