
 Automatic Train Supervision Market | 2026-2036
Automatic Train Supervision Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Train Supervision Market Analysis
Copper cabling in legacy signaling infrastructure is recalibrating product economics as fiber-optic and wireless communication layers replace traditional track circuits. Siemens leverages its European manufacturing footprint to sustain dominance in ETCS-compliant supervision systems. Hitachi anchors its position through deep integration with Japanese Shinkansen operations and export-oriented CBTC platforms.
Automatic Train Supervision constitutes a centralized control layer that monitors train location, regulates headways, and enforces timetable adherence through real-time data exchange with wayside and onboard equipment. The system processes position reports at sub-second intervals to maintain safe separation while optimizing line capacity. CBTC deployments occupy the fastest-expanding technology tier as urban rail operators pursue moving-block signaling to compress headways. Cloud-based and hybrid deployment models are gaining traction among transit authorities seeking to reduce capital intensity through subscription architectures. Maintenance and integration services capture disproportionate margin pools relative to pure software licensing.
The European Union Agency for Railways enforces ERTMS baseline specifications that shape product standards and lock non-compliant suppliers out of member-state procurement. China's NMPA and Ministry of Transport jointly certify signaling systems for domestic rail networks, creating a bifurcated compliance landscape for multinational vendors. India's CEA and Ministry of Railways impose localized testing protocols that extend market access timelines. Stakeholders must weigh certification reciprocity against the cost of maintaining parallel product variants across regulatory jurisdictions.
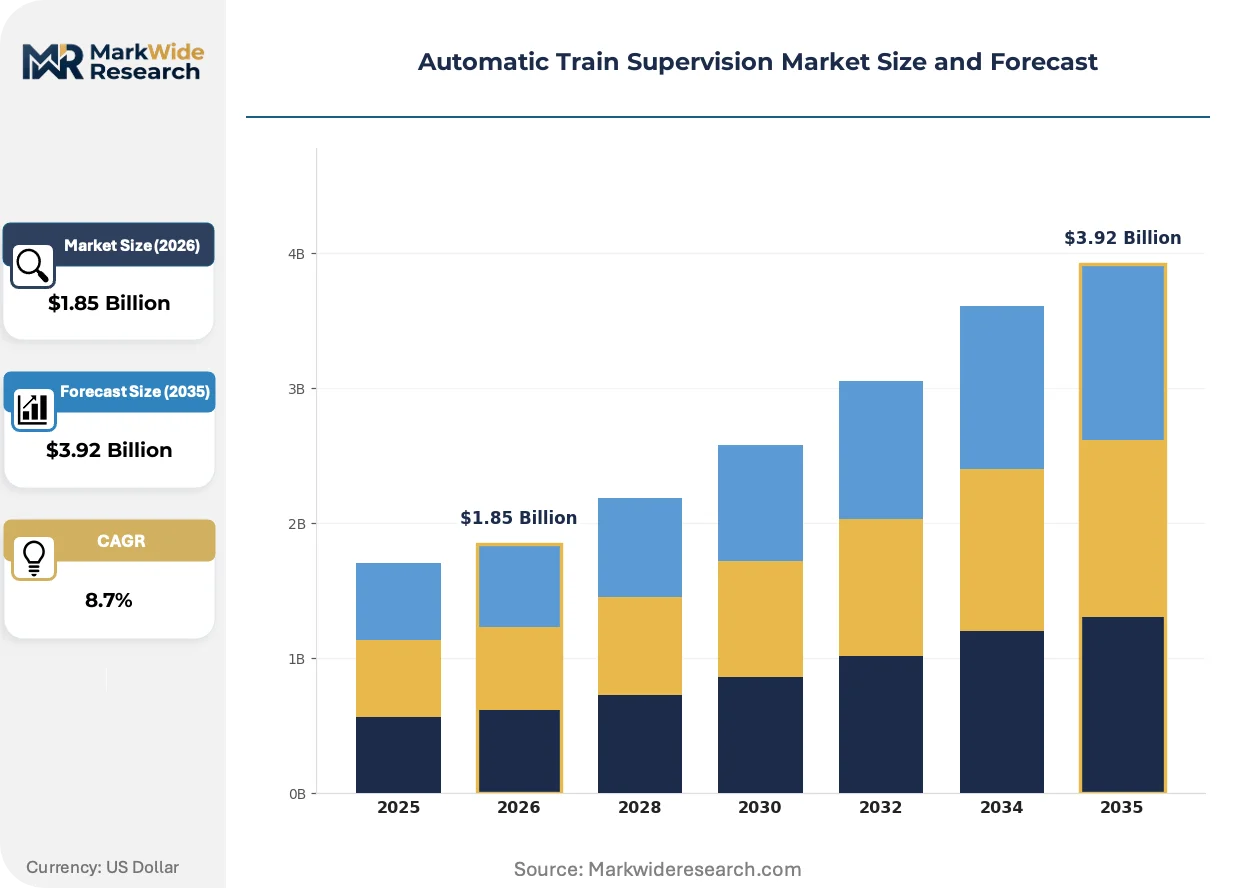
Market Dynamics
Copper-to-fiber infrastructure migration is compressing product economics and forcing vendors to recalibrate hardware portfolios around wireless communication layers. This physical-layer transition is redistributing margin pools from legacy track-circuit suppliers toward software-centric supervision platforms.
Growth Catalysts
- ERTMS Baseline 4 Mandate:The European Union Agency for Railways enforces upgraded specifications that compel cross-border operators to replace legacy signaling with ETCS-compliant supervision architectures.
- Moving-Block Signaling:Communications-Based Train Control technology enables urban metro operators to compress headways below 90 seconds, unlocking capacity on constrained corridors.
- Cloud-First Procurement:Transit authorities in Singapore and Dubai are piloting subscription-based deployment models that reduce upfront capital intensity for supervision software licensing.
Market Restraints
- Copper Cable Obsolescence:Legacy track circuits embedded in 40-year-old infrastructure require complete right-of-way excavation, inflating retrofit project costs by factors of three to five.
- Certification Reciprocity Gaps:China's NMPA and Ministry of Transport operate non-mutual recognition regimes with European notified bodies, forcing vendors to maintain parallel product variants.
- Specialized Engineering Talent:The intersection of rail safety protocols and real-time software engineering creates acute scarcity in functional safety certification expertise.
Strategic Opportunities
- Indian Metro Expansion:Mumbai, Delhi, and Bangalore construction programs represent underpenetrated demand for CBTC-integrated supervision systems requiring localized testing protocols.
- Hybrid Edge-Cloud Architectures:Convergence of 5G private networks and containerized supervision software enables distributed processing with centralized fleet analytics.
- Digital Twin Integration:Synthetic environment modeling of train movements allows operators to simulate timetable perturbations without disrupting live operations.
Industry Challenges
- Interoperability Testing Complexity:Multi-vendor CBTC deployments require exhaustive interface validation between onboard controllers, wayside equipment, and central supervision layers.
- Cybersecurity Certification Burden:IEC 62443 compliance for industrial control systems adds 18-24 months to product qualification timelines for European deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Train Supervision Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CBTC, ETCS, GPS, Signal-Based Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: Transit Authorities, Rail Operators, Government Agencies, Private Operators Service Type: Consulting, Integration, Maintenance, Support |
| Companies Covered | Siemens, Traffic Control Technology, Hitachi, Nippon Signal, CRSC, Thales, Toshiba, Kyosan, Alstom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Train Supervision Market Emerging Trajectories
Real-time data processing architectures are displacing batch-oriented supervision systems, enabling sub-second headway regulation and predictive maintenance integration. This computational shift is redefining competitive advantage around software latency rather than hardware reliability.
Artificial intelligence-based timetable optimization is automating conflict resolution between scheduled services and unplanned disruptions. Metro operators in Tokyo and London are deploying machine learning modules that resequence train movements within 200 milliseconds of detecting platform congestion. The technology is automating dispatcher workload reduction while compressing recovery times from service incidents.
The European Union's F-Gas Regulation is phasing out sulfur hexafluoride insulation in trackside electrical equipment, forcing supervision system vendors to redesign wayside power distribution. Railway operators must retrofit or replace gas-insulated switchgear by 2030. CBTC suppliers with solid-state power architectures capture preferential positioning in German and French procurement cycles.
Lifecycle service unbundling is separating hardware maintenance from software subscription renewals. Transit authorities in Australia and Canada now procure supervision capabilities through availability-based contracts where vendors guarantee system uptime percentages. This procurement evolution shifts risk allocation toward suppliers while creating recurring revenue concentration among integrated platform providers.
Automatic Train Supervision Market Segmentation
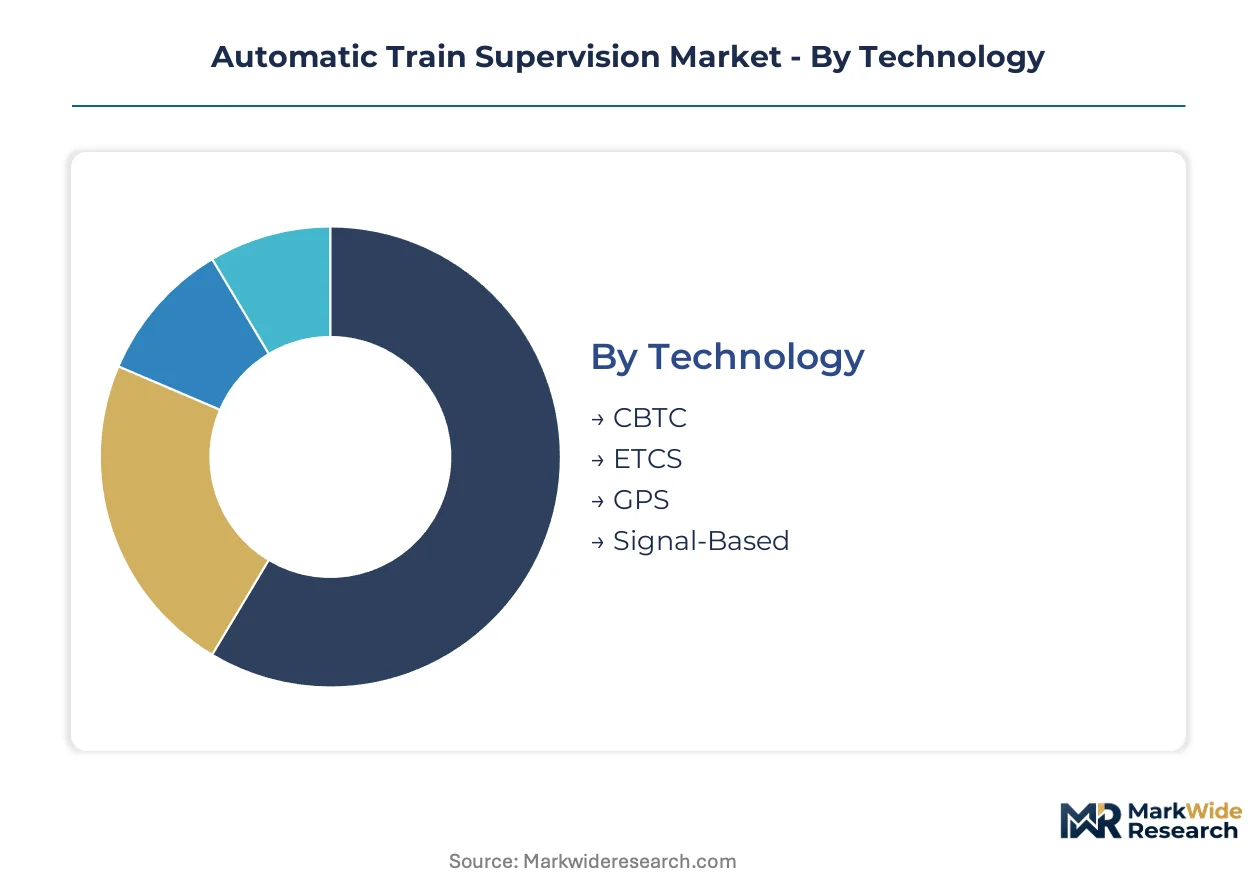
Technology choice dictates capital intensity, certification burden, and interoperability scope for supervision system buyers. Deployment architecture determines whether operators retain infrastructure risk or transfer it to vendors through subscription models. End-user procurement authority varies sharply between centralized transit authorities and fragmented private operators.
Technology:
Procurement committees weight baseline compliance against headway compression targets when selecting signaling platforms.
- CBTC:Communications-based architecture enables moving-block signaling with sub-90-second headways through continuous bidirectional train-to-wayside data exchange. Urban metro operators in Beijing, Shanghai, and Delhi deploy CBTC to maximize corridor throughput on constrained rights-of-way.
- ETCS:European Train Control System standardizes cross-border interoperability through unified speed supervision and braking curves mandated by the EU Agency for Railways. National rail operators in Germany, France, and Italy prioritize ETCS Baseline 4 compliance for international corridor access.
- GPS:Satellite-based positioning supplements supervision layers in low-density regional networks where track circuit installation proves uneconomical.
- Signal-Based:Legacy fixed-block architectures persist in heritage infrastructure where wholesale replacement faces budget or timeline constraints.
Volume sits with ETCS; growth tilts toward CBTC.
Deployment Model:
Capital availability and IT maturity separate buyers into risk-retention versus risk-transfer preferences.
- On-Premise:Perpetual licensing with captive hardware ownership dominates conservative procurement in Japan and Switzerland where data sovereignty concerns block external hosting.
- Cloud-Based:Fully hosted supervision platforms eliminate data center capital expenditure while exposing operators to recurring subscription obligations.
- Hybrid:Edge processing for safety-critical functions combined with cloud analytics for fleet optimization balances latency requirements against cost reduction.
- SaaS:Singapore Land Transport Authority and Dubai RTA pilot availability-based contracts where vendors guarantee uptime percentages.
Revenue concentrates in on-premise installations; subscription architectures gain share fastest.
End User:
Budget cycle alignment and technical staffing depth shape vendor engagement strategies across buyer types.
- Transit Authorities:Centralized procurement bodies in London, Tokyo, and New York bundle supervision systems with rolling stock and civil works into multi-billion-dollar program tenders.
- Rail Operators:Commercial freight and passenger carriers prioritize interoperability certification for network access over feature differentiation.
- Government Agencies:National ministries in India and China direct funding toward domestic technology transfer requirements.
- Private Operators:Airport express and mining rail concessionaires favor rapid deployment schedules over customization depth.
Contract value peaks with transit authorities; private operators expand most quickly.
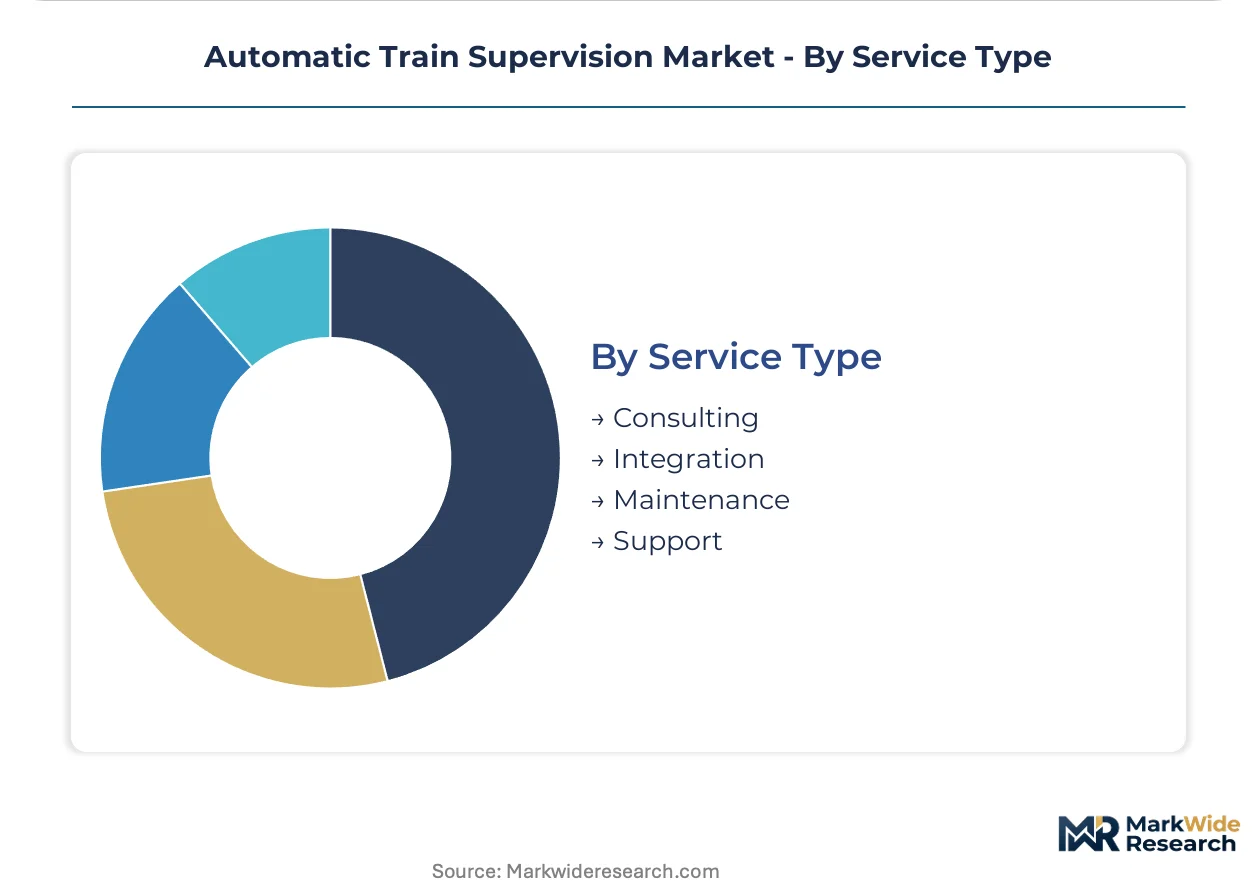
Service Type:
Margin capture shifts from hardware installation toward recurring software maintenance and integration complexity.
- Consulting:System architecture design and regulatory pathway navigation command premium billing rates given scarcity of functional safety certification expertise.
- Integration:Multi-vendor CBTC deployments require exhaustive interface validation between onboard controllers, wayside equipment, and central supervision layers.
- Maintenance:Lifecycle service contracts guarantee availability percentages and absorb obsolescence risk from transit authorities.
- Support:24/7 operational assistance desks resolve timetable perturbations through remote diagnostic access.
Integration captures the steepest margin expansion; maintenance delivers the most predictable recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Shanghai concentrate CBTC manufacturing capacity for metro expansion across Asia-Pacific. The EU's ERTMS deployment corridors and India's Dedicated Freight Corridor program anchor demand concentration in their respective jurisdictions.
China
Beijing and Shanghai metro authorities deploy CBTC-integrated supervision systems across 800+ kilometers of new urban rail annually. The Ministry of Transport and NMPA jointly certify signaling platforms under GB standards that bifurcate compliance from European notified bodies. CRSC anchors domestic supply chains through technology transfer partnerships with multinational vendors in the Yangtze River Delta manufacturing cluster.
Germany
Deutsche Bahn's ERTMS rollout on core corridors drives ETCS Baseline 4 procurement through 2030. The Federal Railway Authority enforces interoperability mandates that lock non-compliant suppliers out of cross-border freight and passenger services. Siemens leverages its Munich and Erlangen engineering centers to dominate supervision system integration for German and export markets.
India
Mumbai Metro, Delhi Metro, and Bangalore's Namma Metro represent underpenetrated demand for CBTC-integrated supervision architectures. The Central Electricity Authority and Ministry of Railways impose localized testing protocols that extend vendor market access timelines by 18-24 months. The Dedicated Freight Corridor Corporation anchors western and eastern corridor deployments with ETCS Level 2 specifications.
Japan
Tokyo Metro and JR East sustain replacement demand for Shinkansen-compatible supervision systems with sub-3-minute headway requirements. METI's railway safety standards and JIS certification protocols create non-mutual recognition with European ERTMS frameworks. Hitachi and Kyosan anchor the Kanto industrial cluster through captive relationships with domestic operators and selective export programs.
United States
New York MTA and Washington Metro pursue CBTC retrofit programs on aging infrastructure with 40-year-old fixed-block signaling. The Federal Railroad Administration's PTC mandate created baseline interoperability requirements that differ from ERTMS specifications. Chicago's Metra and Los Angeles Metro anchor procurement concentration for commuter and light rail supervision upgrades.
Automatic Train Supervision Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing recurring revenue pools while component suppliers compete on installation margins. The vendor base concentrates around three strategic tiers: European ETCS specialists with regulatory lock-in, Asian CBTC integrators with cost-optimized urban metro platforms, and regional maintenance contractors with localized service networks. Dominant competitive moves include certification reciprocity investments to bypass parallel product variants and availability-based contracting to transfer infrastructure risk toward suppliers.
Among European-headquartered platform providers, Siemens and Alstom exemplify the ETCS-specialist archetype with regulatory anchoring in EU member-state procurement. Hitachi occupies a distinct position bridging Japanese Shinkansen operations with export-oriented CBTC platforms for Asian metro authorities. Thales represents the diversified technology conglomerate model with supervision systems integrated across aerospace and defense portfolios. These three anchors illustrate how geographic regulatory alignment shapes sustainable competitive positioning more than feature differentiation alone.
| Leading Market Players |
|---|
| Siemens |
| Traffic Control Technology |
| Hitachi |
| Nippon Signal |
| CRSC |
| Thales |
| Toshiba |
| Kyosan |
| Alstom |
| Others |
Supply Flow & Price Mechanics
ETCS Baseline 4 certification tiers versus CBTC commodity platforms bifurcate vendor economics and sourcing footprints across European and Asian procurement theaters. Premium-tier suppliers command recurring software margins through regulatory lock-in, while cost-optimized integrators compete on installation velocity in metro construction programs.
Pricing Analysis
Volume concentrates in perpetual-licensed ETCS hardware installations; margin expansion flows toward SaaS-structured CBTC supervision subscriptions. Price differentiation rests on IEC 62443 cybersecurity certification grade and localized testing protocol completion. Pricing pressure stems from copper-to-fiber infrastructure migration compressing legacy track-circuit hardware values. Private airport express operators exhibit acute price sensitivity; national rail ministries prioritize compliance over cost.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's GB standards certification reshape component sourcing toward Yangtze River Delta and Shenzhen manufacturing clusters. Supply concentration centers on Germany, Japan, and China for wayside controllers, onboard processors, and fiber-optic communication layers. Raw material dependencies include high-purity copper for legacy retrofits, rare-earth magnets for traction systems, and specialized optical fiber for CBTC data backbones. Single-source vulnerability runs through ASIC chip fabrication for safety-critical controllers. Distribution feeds from systems integrators through transit authority procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
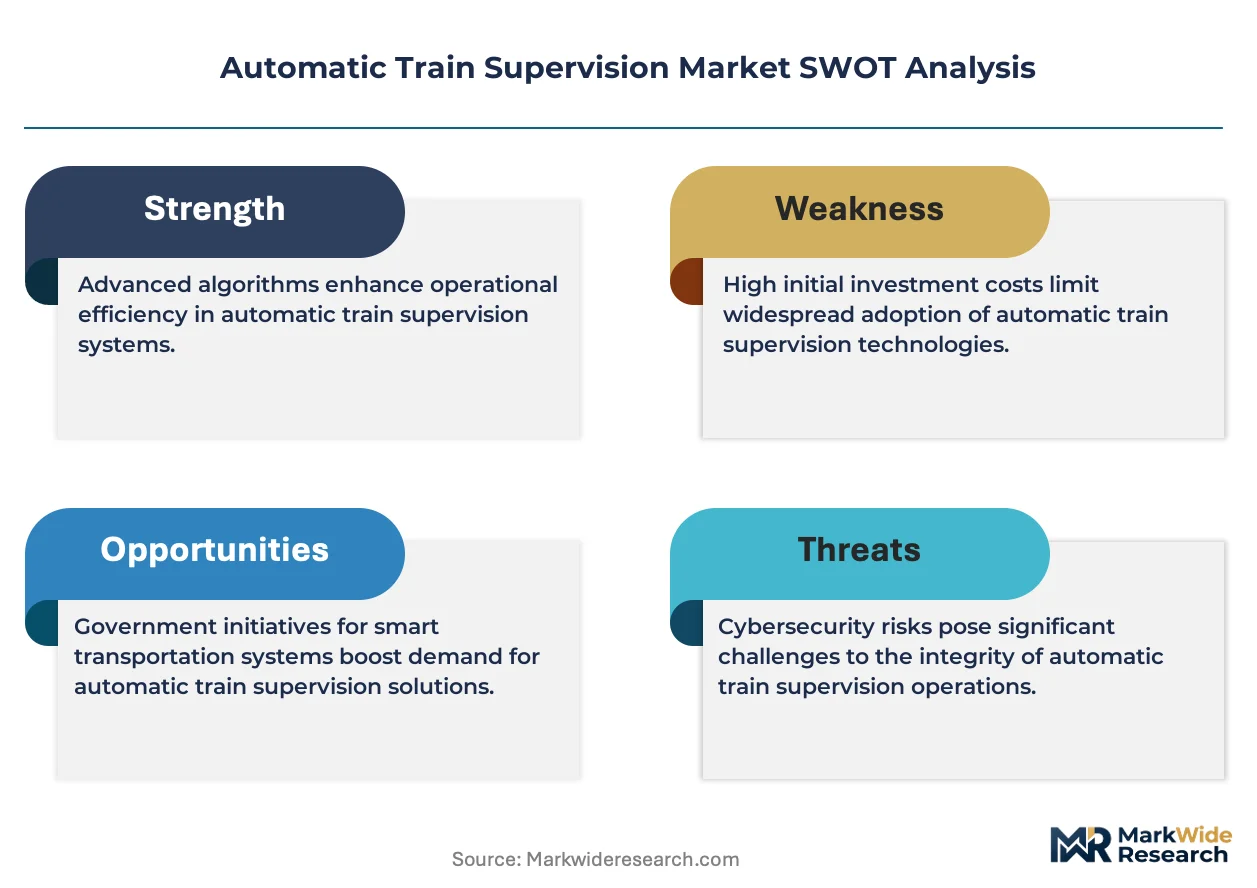
The Automatic Train Supervision Market sits in a technology-transition phase as communications-based train control displaces fixed-block signaling architectures. Fiber-optic and wireless layers replace copper track circuits, redistributing competitive advantage toward software-centric platforms.
For Market Incumbents: Cement regulatory anchoring through ERTMS Baseline 4 certification reciprocity investments to bypass parallel product variants for European and Asian markets. Deepen backward integration into solid-state power architectures ahead of EU F-Gas Regulation phase-out deadlines. Threats emerge from cloud-native entrants unburdened by legacy hardware portfolios.
For New Entrants and Emerging Players: Private 5G network operators for regional rail corridors represent an underserved buyer archetype with compressed procurement cycles and reduced certification burden. White-space targets include hybrid edge-cloud supervision deployments for Australian and Canadian transit authorities. Go-to-market through availability-based contracting transfers infrastructure risk and accelerates reference customer acquisition.
For Investors and Strategic Acquirers: Re-rating potential sits with functional safety certification specialists given acute scarcity in rail safety protocol expertise and IEC 62443 compliance engineering. Long-term viability favors vendors with recurring software revenue concentration and integrated platform architectures. Watch CBTC retrofit penetration rates in US legacy corridors as inflection signal for technology transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-First Platform Migration | Singapore Land Transport Authority pilots reduce capital intensity through subscription supervision licensing. |
| ERTMS Baseline 4 Certification | Deutsche Bahn corridor mandates lock non-compliant suppliers out of cross-border procurement. |
| Digital Twin Integration | Tokyo Metro synthetic environment modeling compresses recovery times from timetable perturbations. |
| Hybrid Edge-Cloud Architecture | 5G private networks enable distributed processing with centralized fleet analytics for Dubai RTA. |
| Lifecycle Service Unbundling | Australian availability-based contracts shift obsolescence risk toward integrated platform providers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with transit authority procurement directors, rail operator engineering leads, systems integration specialists, and functional safety certification consultants combined with secondary validation from EU Agency for Railways specifications, NMPA certification databases, and Ministry of Transport procurement disclosures. Bottom-up project pipeline triangulation against top-down infrastructure spending forecasts calibrated market sizing.
Granularity-level modeling distinguished CBTC from ETCS technology tiers, on-premise from cloud-based deployment architectures, and transit authority from private operator end-user segments across the projection horizon. CAGRs derived from fitted growth curves against metro construction program timelines and ERTMS mandate compliance deadlines. Industry-specific forecast inputs included copper cable replacement cycles and 5G private network deployment schedules.
Revisions become necessary when certification reciprocity agreements emerge between China's NMPA and European notified bodies, or when cybersecurity regulation timelines accelerate. Forecasts reflect documented assumptions around infrastructure spending continuity and technology transition rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Horn Market
Railway
Railway System Market
Railway
Tugger Trains Market
Railway
Trams Market
Railway
Global Hyperloop Train Market
Railway
Train Locomotive Suspension Market
Railway
Europe Intermodal Terminals Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Railroad Brake Shoe Market
Railway
Railway Automated Inspection Equipment Market
Railway
Freight Cars Market
Railway
Global Train Control and Management Systems Market
Railway
Railway Management System Market
Railway
Railcar Vehicle Toilet Market
Railway
Locomotive Radiator Fan Market
Railway
Check Rails Market