
 Traction Motors Market | 2026-2036
Traction Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Traction Motors Market Outlook
EPA Tier 4 locomotive emissions rules is rebalancing the cost-of-entry calculus for traction motor suppliers serving North American rail operators. ABB leverages its integrated powertrain portfolio to capture long-haul freight electrification contracts. Siemens anchors European railway modernization through localized motor manufacturing and digital twin integration. CRRC dominates domestic procurement in China's expanding high-speed and urban metro networks.
Traction motors convert electrical energy into mechanical torque for propulsion in rail vehicles, electric automobiles, and heavy industrial equipment, typically operating at voltage ranges from 600V to 25kV AC depending on application scale. Permanent magnet synchronous designs achieve efficiency ratings exceeding 96% in high-speed rail duty cycles, while induction motor architectures retain cost advantages for freight locomotives with variable load profiles. AC motor platforms currently occupy the largest installed base across railway applications, though permanent magnet motor adoption is accelerating fastest in electric vehicle powertrains where power density and thermal management determine competitive positioning. Digital control technology implementations are concentrating margin pools among suppliers offering integrated inverter-motor systems with real-time condition monitoring.
FRA safety mandates in the United States, REACH material compliance in Europe, and China's GB/T energy efficiency standards collectively dictate motor material selection, thermal class ratings, and supplier certification pathways across major demand centers. EPA and FERC frameworks in North America increasingly tie rail operator subsidies to verified traction system efficiency improvements, redirecting procurement toward digitally integrated motor platforms. Stakeholders must monitor evolving rare earth supply chain regulations and permanent magnet substitution research programs to anticipate technology transition timelines and sourcing risk exposures.
Market Dynamics
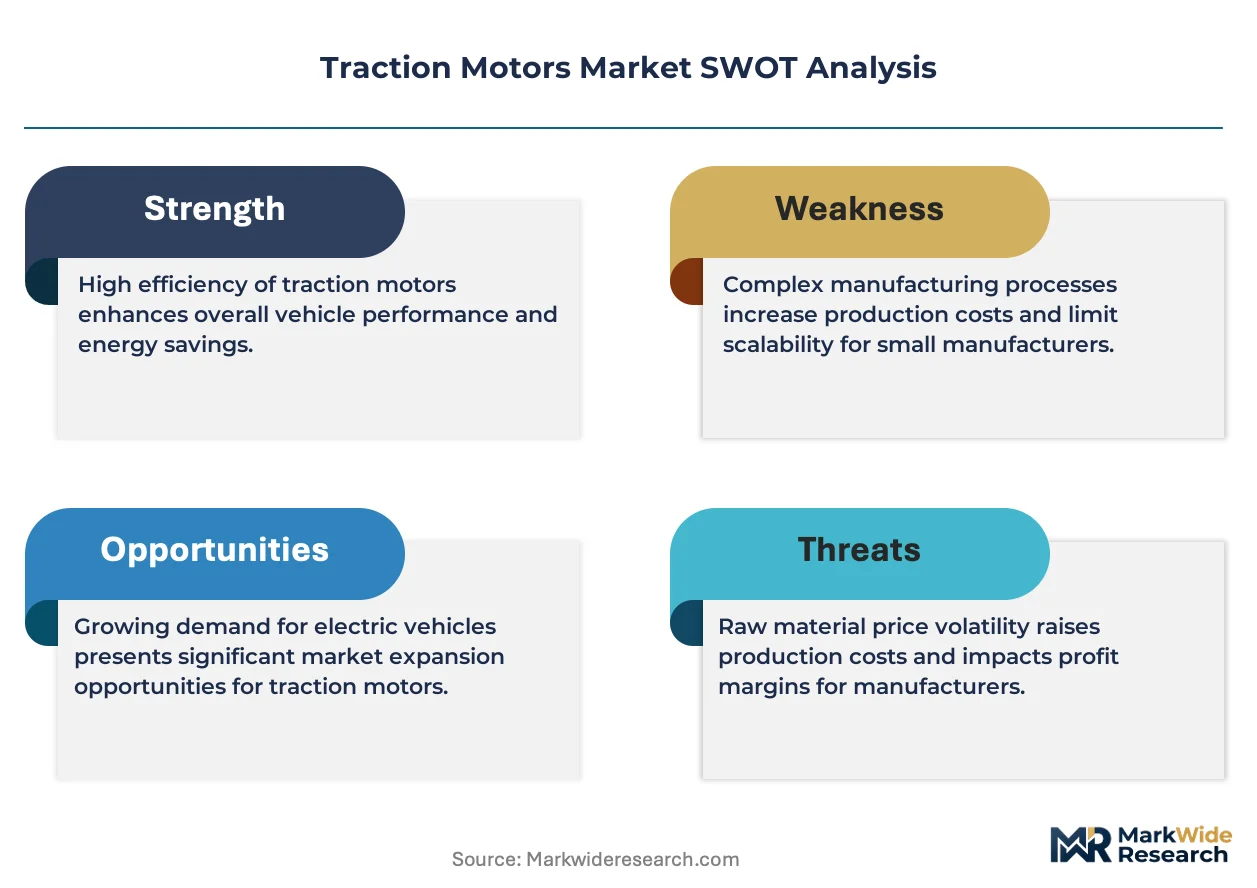
Permanent magnet motor architectures are compressing supplier margins as rare earth supply concentration forces dual-sourcing strategies and accelerated induction motor R&D programs.
Growth Catalysts
- High-speed rail electrification:China's GB/T energy efficiency standards mandate next-generation AC motor deployments across 40,000 kilometers of operational track, creating sustained procurement pipelines for domestic and foreign suppliers.
- EPA Tier 4 locomotive rules:Freight operators in the United States face emissions compliance deadlines that elevate motor efficiency benchmarks and disqualify legacy induction platforms from new-build contracts.
- Silicon carbide inverters:Wide-bandgap semiconductor integration enables 20-30% thermal performance gains in compact motor designs, accelerating adoption in electric bus powertrains.
Market Restraints
- Neodymium-dysprosium supply chokepoints:China's dominance in rare earth processing concentrates permanent magnet sourcing risk, exposing motor manufacturers to export quota volatility and price spikes.
- Copper winding cost exposure:LME copper price fluctuations directly compress margins on induction motor platforms that retain 35-40% material cost in conductor assemblies.
- REACH material compliance:European ECHA restrictions on hexavalent chromium coatings and specific insulation resins force reformulation of stator lamination treatments, extending qualification timelines.
Strategic Opportunities
- India's railway modernization:The Dedicated Freight Corridor and metro expansion programs create demand for 25kV AC traction systems with localized manufacturing requirements under Make in India procurement rules.
- Digital twin integration:Real-time motor health monitoring combined with predictive maintenance algorithms opens recurring revenue streams in fleet management contracts.
- Ferrite magnet substitution:Japanese METI-funded research programs on ferrite-based synchronous motors offer a rare-earth-free pathway for cost-sensitive urban transit applications.
Industry Challenges
- Electromagnetic compatibility certification:IEC 61000-4-x testing for 25kV railway environments requires specialized anechoic facilities that extend product launch timelines by 8-14 months.
- Thermal class H insulation expertise:Shortages of engineers trained in 180°C winding systems and vacuum pressure impregnation processes constrain production ramp rates for high-speed rail contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traction Motors Market |
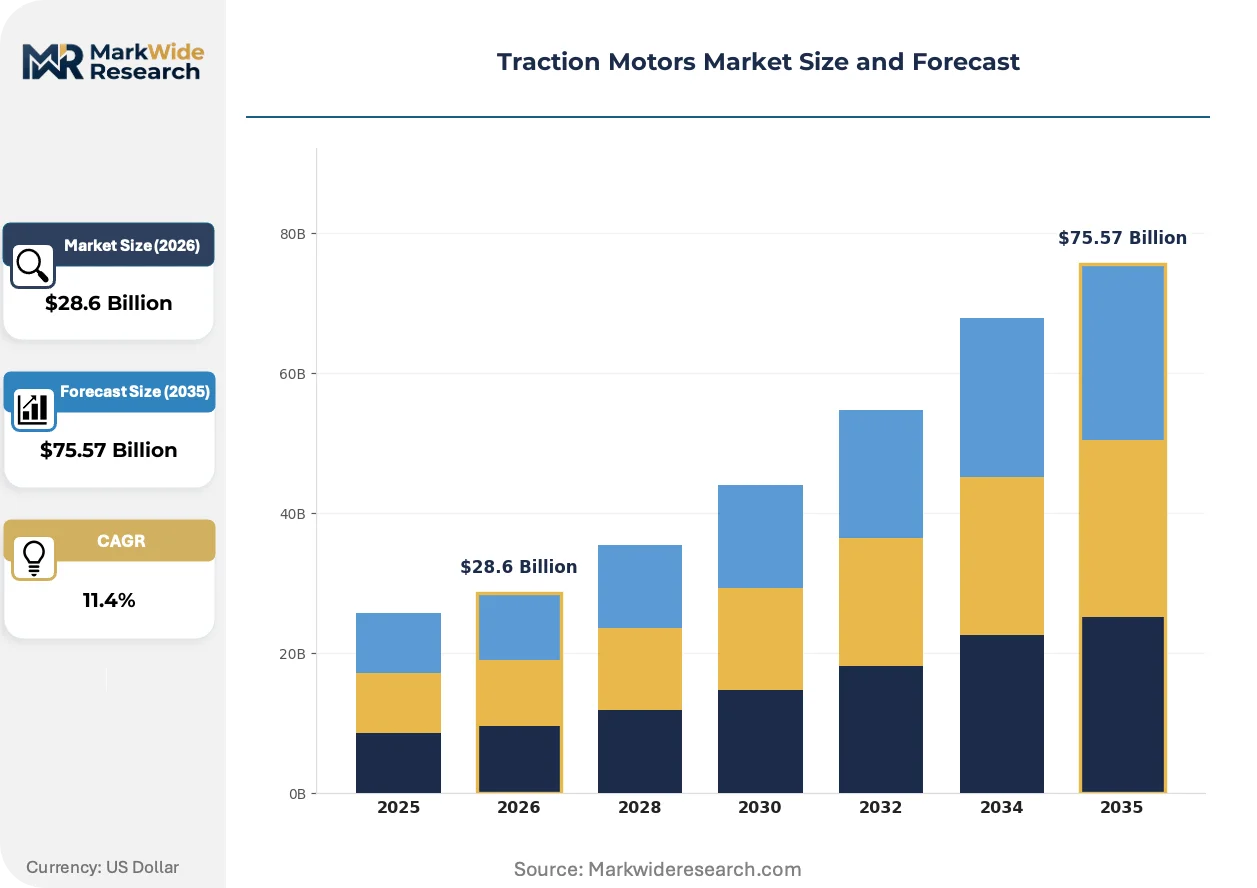
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Permanent Magnet Motors, Induction Motors Application: Railway, Electric Vehicles, Industrial Machinery, Aerospace End User: Manufacturers, Fleet Operators, Government, Transport Companies Technology: Brushless Technology, Synchronous Technology, Asynchronous Technology, Digital Control Technology |
| Companies Covered | ABB, Siemens, CRRC, Toshiba International, Hitachi, Mitsubishi Electric, Wabtec, Škoda Transportation, Nidec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traction Motors Market Strategic Shifts
Silicon carbide power electronics and permanent magnet substitution chemistry are compressing the performance gap between AC induction and synchronous motor architectures across rail and road applications.
Silicon carbide MOSFET-based inverters are integrating with high-speed permanent magnet motors to achieve switching frequencies above 20kHz, enabling liquid-cooled power density levels that displace forced-air designs in electric bus platforms. Tier-1 suppliers in Germany and Japan are qualifying these integrated drivetrains for 800V architectures. The technology is integrating motor and inverter thermal management into single-loop cooling systems that reduce package volume by 25%.
REACH authorization requirements for cobalt compounds and specific epoxy hardeners are forcing reformulation of insulation systems in European-sourced traction motors. The regulation compresses supplier qualification windows and elevates documentation burdens for non-EU manufacturers seeking CE marking. Rail operators in France and Germany now specify full material disclosure as a contract precondition, shifting procurement toward vertically integrated motor producers with in-house resin compounding capabilities.
Indian Railways is consolidating traction motor procurement under single-source framework agreements that bundle 15-year maintenance obligations with initial supply contracts. The model displaces spot purchasing and forces suppliers to establish regional service depots with localized spare part inventories. This concentration is most visible in the Mumbai-Ahmedabad high-speed corridor and Delhi-Meerut RRTS line, where CRRC and Alstom have established captive refurbishment facilities.
Traction Motors Market Segmentation
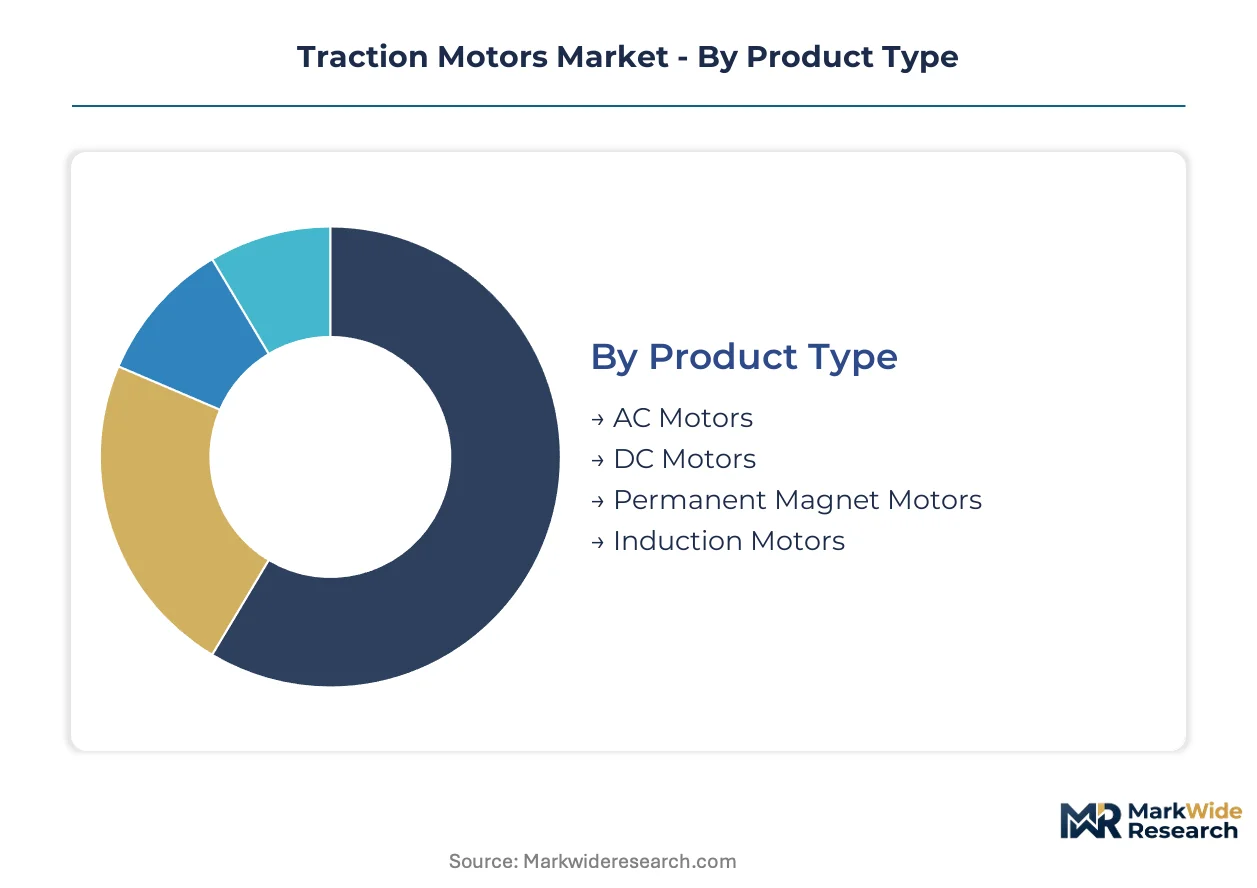
Traction motor segmentation reveals how supplier capabilities align with diverging performance requirements across rail electrification, electric mobility, and industrial automation. Each dimension—product architecture, application duty cycle, procurement authority, and control methodology—creates distinct margin structures and qualification barriers.
Product Type:
Supply concentration in rare earth processing and copper winding fabrication shapes competitive positioning across motor architectures.
- AC Motors:Polyphase alternating current designs dominate railway electrification systems operating at 15-25kV, with wound rotor configurations enabling regenerative braking efficiency above 90% in China's high-speed rail corridors. Demand concentrates in network modernization programs where GB/T efficiency standards mandate replacement of legacy DC traction systems.
- Permanent Magnet Motors:Neodymium-iron-boron rotor assemblies achieve power density exceeding 5kW/kg in compact electric bus powertrains, though China's export quota controls on dysprosium and terbium force dual-sourcing strategies among European and Japanese manufacturers.
- DC Motors:Series-wound and separately excited designs retain installed base in older metro fleets and mining haul trucks where simple speed control suffices.
- Induction Motors:Squirrel-cage rotor architectures offer cost advantages in freight locomotives with variable load profiles, though copper price volatility compresses margins on conductor-dominant bill-of-materials.
AC motors absorb the bulk of installed capacity; permanent magnet motors are expanding most quickly.
Application:
End-use differentiation separates high-volume standardized procurement from bespoke engineering contracts with extended qualification timelines.
- Railway:Mainline locomotives, multiple units, and metro rolling stock require IEC 61215 thermal class H insulation and 30-year design life, with FRA safety mandates in the United States and EN 50343 in Europe dictating electromagnetic compatibility test protocols.
- Electric Vehicles:Passenger cars, buses, and commercial vans demand 800V architectures with silicon carbide inverters, where liquid-cooled permanent magnet motors achieve 20-30% thermal performance gains over forced-air designs.
- Industrial Machinery:Mining equipment, marine propulsion, and material handling systems utilize robust induction motor platforms with IP55 enclosure ratings.
- Aerospace:More electric aircraft initiatives drive 270V DC starter-generator development for auxiliary power units and flight control actuation.
Railway applications command the deepest supplier relationships; electric vehicles are climbing the fastest.
End User:
Procurement authority concentration determines contract structure, from framework agreements with 15-year maintenance bundles to spot purchasing of replacement units.
- Manufacturers:OEMs like CRRC, Alstom, and Siemens integrate traction motors into complete powertrain assemblies, qualifying suppliers through multi-year platform development cycles with captive tooling investments.
- Fleet Operators:Freight railroads and urban transit authorities in India and Germany negotiate performance-based contracts linking payment to energy efficiency guarantees and availability metrics.
- Government:State railway administrations in China and Japan consolidate procurement under national electrification programs with localized content requirements.
- Transport Companies:Private bus operators and logistics fleets prioritize total cost of ownership over capital expenditure, favoring remanufactured motors with extended warranties.
Manufacturers absorb the bulk of installed capacity; fleet operators are expanding most quickly.
Technology:
Control methodology differentiation separates commodity motor producers from integrated drivetrain suppliers capturing inverter-motor system margins.
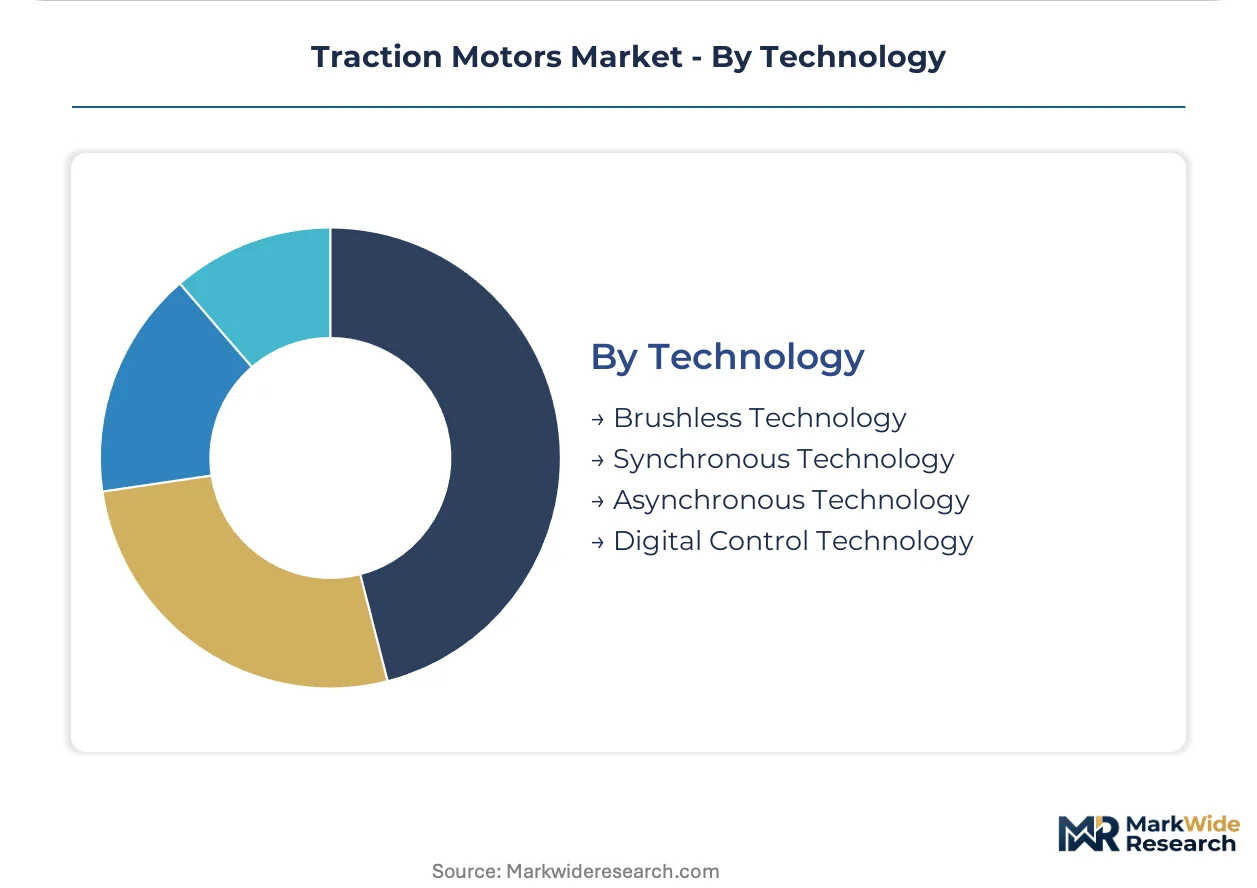
- Digital Control Technology:Field-oriented control algorithms with real-time condition monitoring enable predictive maintenance and 15% energy recovery improvements, concentrating demand among digitally integrated suppliers serving European and Japanese rail operators.
- Brushless Technology:Electronic commutation eliminates mechanical wear in high-speed permanent magnet motors for electric bus platforms, where 20kHz switching frequencies reduce acoustic noise.
- Synchronous Technology:Rotor speed locked to stator field frequency enables precise torque control in high-speed rail applications with minimal slip losses.
- Asynchronous Technology:Induction motor simplicity with inherent slip provides overload tolerance for freight locomotives experiencing traction load spikes.
Digital control technology absorbs the bulk of installed capacity; brushless technology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's high-speed rail manufacturing zones and India's Dedicated Freight Corridor attract supplier facility investments through accelerated depreciation schemes and import substitution mandates. Germany's railway modernization clusters concentrate R&D tax credits for digital traction systems. Japan's urban transit corridors drive ferrite magnet research through METI-funded consortia.
China
GB/T energy efficiency standards mandate AC motor replacements across 40,000 kilometers of electrified track. MIIT procurement rules require 70% domestic content in high-speed rail powertrains. Qingdao and Changchun manufacturing clusters host captive motor production for CRRC's expanding metro and intercity vehicle output.
Germany
Deutsche Bahn's fleet electrification program sustains demand for 25kV AC traction systems in freight and passenger corridors. KBA certification requirements for electromagnetic compatibility extend supplier qualification timelines. Munich and Nuremberg industrial zones concentrate Siemens and ABB motor assembly with integrated inverter manufacturing.
India
The Dedicated Freight Corridor and Delhi-Meerut RRTS generate procurement for 25kV AC traction motors with 15-year maintenance bundles. Make in India rules mandate localized manufacturing for railway tenders exceeding $50 million. Vadodara and Chennai production hubs host Alstom and CRRC captive refurbishment facilities.
Japan
Tokyo-Osaka high-speed corridor upgrades drive demand for permanent magnet motors with ferrite substitution research. METI funding targets rare-earth-free synchronous motor development by 2030. Nagoya and Osaka manufacturing zones concentrate Toshiba and Hitachi integrated powertrain assembly for domestic and export markets.
United States
EPA Tier 4 locomotive compliance deadlines disqualify legacy induction motors from new-build freight contracts. FRA safety mandates require IEC 61000-4-x electromagnetic testing for 25kV railway environments. Pennsylvania and Illinois industrial corridors host Wabtec motor production for Class I railroad electrification programs.
Traction Motors Market Competitive Environment
Chinese producers anchor volume manufacturing through state-backed railway procurement; German and Japanese specialists hold premium-tier positions in digital-integrated systems. The vendor structure concentrates around three strategic archetypes: state-affiliated rolling stock integrators with captive motor production, European-Japanese diversified industrials with powertrain portfolios, and specialized motor manufacturers supplying aftermarket refurbishment. Competitive moves center on framework agreements bundling long-term maintenance obligations and rare-earth supply chain partnerships securing magnet sourcing.
Among the state-affiliated tier, CRRC occupies a position exemplifying vertical integration from rare earth processing through final assembly. Siemens and ABB represent the diversified industrial archetype, anchoring European and North American procurement through localized manufacturing and digital twin integration. Wabtec sits within the specialized manufacturer category, concentrating on freight locomotive aftermarket and Tier 4 compliance retrofit markets.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| CRRC |
| Toshiba International |
| Hitachi |
| Mitsubishi Electric |
| Wabtec |
| Škoda Transportation |
| Nidec |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet feedstock flows from Chinese processing facilities through three distinct pricing tiers downstream, with dysprosium and terbium export quotas compressing margins on permanent magnet platforms while copper LME volatility shapes induction motor cost structures.
Pricing Analysis
Lead-time premiums separate procurement tiers in traction motor contracting, with spot inventory availability commanding standard pricing while custom-wound thermal class H systems for high-speed rail carry 15-20% premiums due to specialized vacuum pressure impregnation capacity constraints. Three-tier pricing structure across premium, standard, and economy levels aligns with IEC 61215 certification grades and FRA electromagnetic compatibility testing completion. Cost compression in induction motor platforms is intensifying because copper conductor assemblies constitute 35-40% of bill-of-materials. Fleet operators in India's Dedicated Freight Corridor exhibit highest price sensitivity, while Japanese high-speed rail procurement prioritizes ferrite substitution research over unit cost.
Supply Chain Analysis
Neodymium-iron-boron magnet supply rests on Chinese rare earth processing concentration, with secondary sourcing from Japanese and Australian mining operations. Copper winding fabrication draws from Chilean concentrate and Indonesian smelting capacity. Silicon carbide substrate production centers on Japanese and German wafer facilities. Single-source vulnerability in dysprosium terbium separation exposes European and North American motor manufacturers to export quota volatility. Distribution runs through OEM captive production in Qingdao and Changchun clusters, regional refurbishment depots in Vadodara and Chennai, and aftermarket service networks tied to 15-year maintenance bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 locomotive emissions rules have erected a compliance moat that disqualifies legacy suppliers from new-build freight contracts, concentrating procurement among digitally integrated motor platforms with verified efficiency benchmarking.
For Market Incumbents: Lock in rare earth supply partnerships through offtake agreements with Chinese processors and accelerated ferrite magnet R&D programs to hedge against export quota volatility. Expand captive refurbishment capacity in India's Dedicated Freight Corridor to capture 15-year maintenance bundle contracts. Vertical integration into silicon carbide inverter manufacturing secures margin pools from integrated drivetrain demand in electric bus platforms. For New Entrants and Emerging Players: Urban transit authorities in Southeast Asia represent an underserved buyer archetype with standardized procurement specifications and lower electromagnetic compatibility certification burdens than high-speed rail. Target remanufactured motor segments for private bus operators prioritizing total cost of ownership over capital expenditure. Partner with established inverter suppliers to bypass multi-year platform qualification cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized motor manufacturers with IEC 61000-4-x testing capabilities and established FRA safety certifications in the United States. Long-term viability hinges on positioning for permanent magnet substitution chemistry maturation and silicon carbide integration adoption curves. Watch Japanese METI-funded ferrite research program milestones as inflection indicators for rare-earth-free technology transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Partnership | Secures dysprosium and terbium offtake against Chinese export quota volatility. |
| Digital Twin Integration | Enables predictive maintenance revenue streams with Deutsche Bahn and JR East. |
| Ferrite Magnet R&D Investment | Positions for rare-earth-free synchronous motor demand in cost-sensitive urban transit. |
| Silicon Carbide Inverter Qualification | Captures 800V architecture margins in electric bus powertrain integration. |
| Regional Refurbishment Facility | Meets Make in India localized content mandates for railway framework agreements. |
Study Parameters
Document review covered railway operator procurement databases, EPA and FRA regulatory filings, and MIIT procurement rules, complemented by interviews with traction motor engineering directors, rolling stock OEM procurement teams, rare earth supply specialists, and thermal insulation system manufacturers. Secondary validation drew from IEC standards documentation, ECHA REACH authorization lists, and customs trade data. Bottom-up unit demand estimates triangulated against top-down electrification program budgets.
Installed base projections and replacement cycle timing across the analysis window reflect segmentation by motor architecture, application duty cycle, and control methodology. Modeled dimensions included voltage class, thermal insulation grade, and regional regulatory cluster. CAGRs were derived from infrastructure investment trajectories and efficiency mandate compliance deadlines. Key inputs comprised China's GB/T energy efficiency standard implementation timelines and India's Dedicated Freight Corridor procurement schedules.
Revisions become necessary when rare earth export quota regimes shift, silicon carbide substrate capacity expansions accelerate, or permanent magnet substitution chemistry achieves cost parity. Forecasts reflect documented assumptions regarding electrification program continuity and regulatory enforcement consistency. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Positive Displacement Motor Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Motor Gear Unit Market
Electric Motor
Electric AC Motors Market
Electric Motor
Electric Motorcycle Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Global EV Motor Controller Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Trolling Motor Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Global Hub Motors Market