
 Pen Injectors Market | 2026-2036
Pen Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Pen Injectors Market Analytics
The EU MDR is decoupling design validation from legacy 510(k) pathways, forcing new entrants to front-load clinical usability studies. Novo Nordisk A/S leverages its captive fill-finish network to compress device-drug development cycles. Eli Lilly and Company anchors its portfolio in connected pen platforms that pair with dose-tracking software. Sanofi competes through modular cartridge systems that reduce switching costs across therapy areas.
Pen injectors are spring-actuated drug delivery devices comprising a dose-setting mechanism, prefilled or user-loaded cartridge chamber, and subcutaneous needle interface, typically manufactured through precision injection molding of medical-grade polymers and stainless-steel stamping for spring assemblies. Their primary purpose is to enable accurate, repeatable self-administration of injectable therapies outside clinical settings. Disposable pen injectors dominate volume due to elimination of reprocessing liability, while combination devices capture expanding margin pools as pharmaceutical sponsors bundle delivery systems with biologic franchises. The homecare end-user segment leads absolute demand as payors push site-of-care migration, though specialty clinics sustain premium pricing for complex therapies requiring initial training.
The FDA human factors guidance, EU MDR Annex I general safety and performance requirements, and ISO 11608 needle-based injection systems standard collectively govern device-software integration, dose accuracy verification, and post-market surveillance obligations. These frameworks lengthen development timelines but raise barriers against low-cost generics lacking usability documentation. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify connected pen apps as regulated components.
Market Dynamics
The EU MDR's decoupling of design validation from legacy 510(k) pathways is compressing competitive timelines and forcing pharmaceutical sponsors to front-load clinical usability studies before device-drug pairing decisions.
Growth Catalysts
- Homecare site-of-care migration:Payors in the United States and Germany now mandate outpatient self-administration for chronic biologics, expanding addressable volume for disposable pen formats.
- FDA human factors engineering guidance:The 2016 guidance and subsequent updates embed iterative usability testing into premarket submissions, creating documentation barriers that favor established device-drug integrators.
- ISO 11608 harmonization:The needle-based injection systems standard provides cross-border technical equivalence, reducing re-certification costs for multi-territory launches.
Market Restraints
- Medical-grade polymer supply concentration:Cyclo-olefin polymer feedstock for transparent pen barrels concentrates among German and Japanese chemical specialists, exposing molders to input volatility.
- Spring assembly precision requirements:Sub-millimeter tolerance stamping for dose-actuation mechanisms limits viable supplier pools to Swiss and South Korean metal-forming specialists.
- Software-as-medical-device reclassification risk:Connected pen dose-tracking apps face evolving FDA and EU MDR scrutiny that could trigger additional clinical validation obligations.
Strategic Opportunities
- Underpenetrated autoimmune therapeutics:Rheumatoid arthritis and psoriasis biologics in India and Brazil remain predominantly clinic-administered, creating first-mover advantage for patient-training ecosystems.
- Modular cartridge interoperability:Standardized 3mL cartridge geometry across therapy areas would reduce switching costs for patients rotating between insulin and GLP-1 agonists.
- Japan PMDA connected device pathway:The Sakigake fast-track designation for digital therapeutics integration offers accelerated review for pen injectors with embedded adherence sensors.
Industry Challenges
- Human factors engineering talent scarcity:The intersection of clinical psychology, mechanical engineering, and regulatory documentation requires hybrid skill sets concentrated in Boston and Basel metro areas.
- Combination product quality agreement complexity:Pharmaceutical sponsors and device manufacturers must negotiate joint post-market surveillance obligations under FDA 21 CFR Part 4, lengthening partnership formation.
- Legacy pen platform software integration:Retrofitting Bluetooth connectivity into mechanical dose-counters requires firmware architectures that conflict with established sterilization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pen Injectors Market |
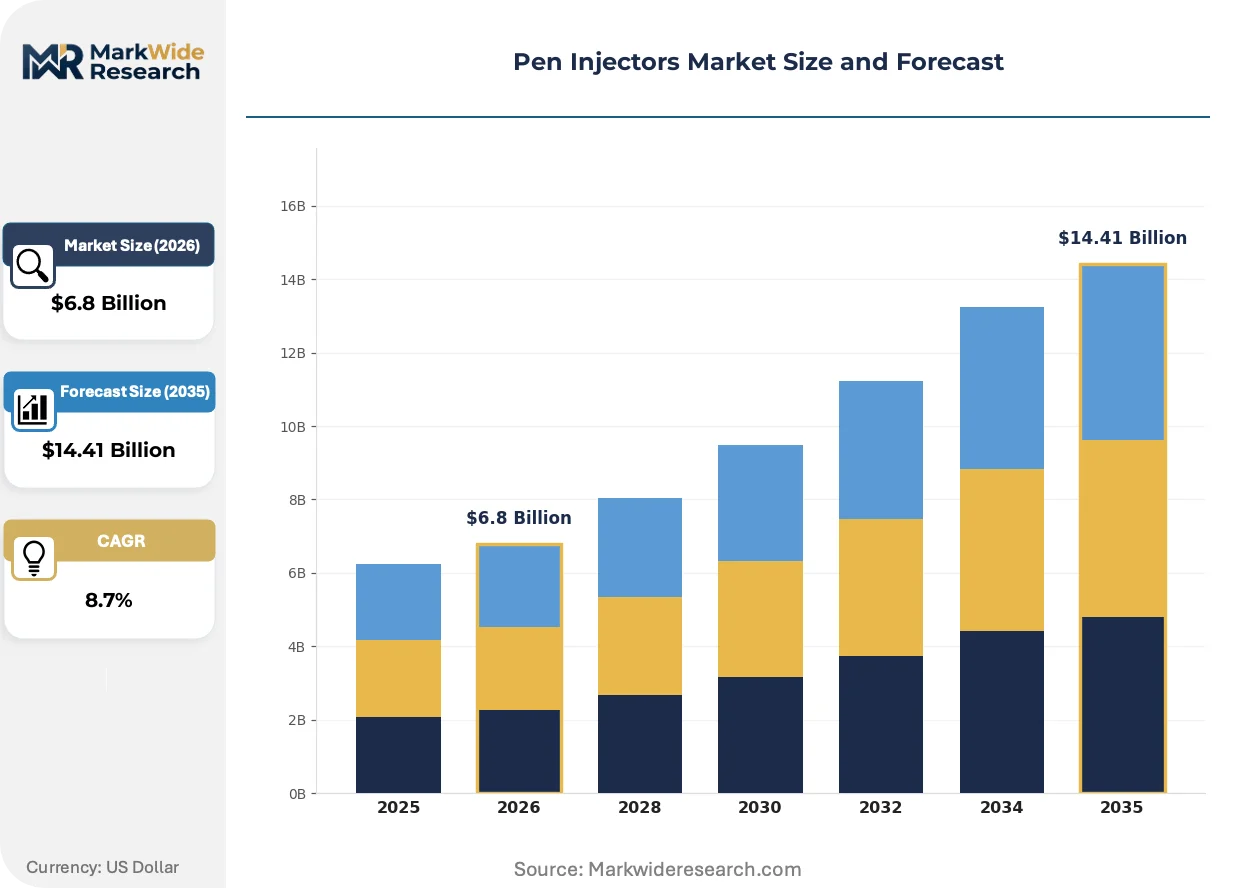
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Safety Devices, Combination Devices Delivery Mode: Subcutaneous, Intramuscular, Intravenous, Epidural End User: Homecare, Hospitals, Specialty Clinics, Pharmacies Therapy Area: Diabetes, Rheumatoid Arthritis, Multiple Sclerosis, Growth Hormone Deficiency |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, Ypsomed Holding AG, Becton Dickinson and Company, AstraZeneca, Pfizer Inc., Merck KGaA, Owen Mumford Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pen Injectors Market Evolving Landscape
Connectivity architectures and materials science advances are compressing development cycles while regulatory frameworks simultaneously extend validation timelines, creating divergent pressures on capital allocation.
Springless electromagnetic actuation is electrifying dose delivery mechanisms in next-generation pen prototypes. Early-stage developers in Switzerland and Massachusetts are piloting voice-coil linear motors that eliminate mechanical wear points. This architecture is electrifying competitive positioning by enabling real-time force-feedback dosing that mechanical springs cannot replicate.
The EU MDR Annex I general safety and performance requirements now mandate post-market clinical follow-up for all class IIa and above injection devices. Manufacturers must establish periodic safety update reports that bridge device and drug vigilance systems. German notified bodies are interpreting this most strictly, driving sponsors to consolidate European authorized representative functions with in-house regulatory affairs teams.
Hospital procurement consortia in the United States are unbundling device selection from drug formulary decisions, reversing decades of bundled contracting. Specialty pharmacy distributors now negotiate pen injector specifications separately from biologic pricing, fragmenting purchasing authority. This decoupling is most visible in the Midwest, where integrated delivery networks have established dedicated medical device value analysis committees distinct from pharmacy and therapeutics panels.
Pen Injectors Market Segmentation
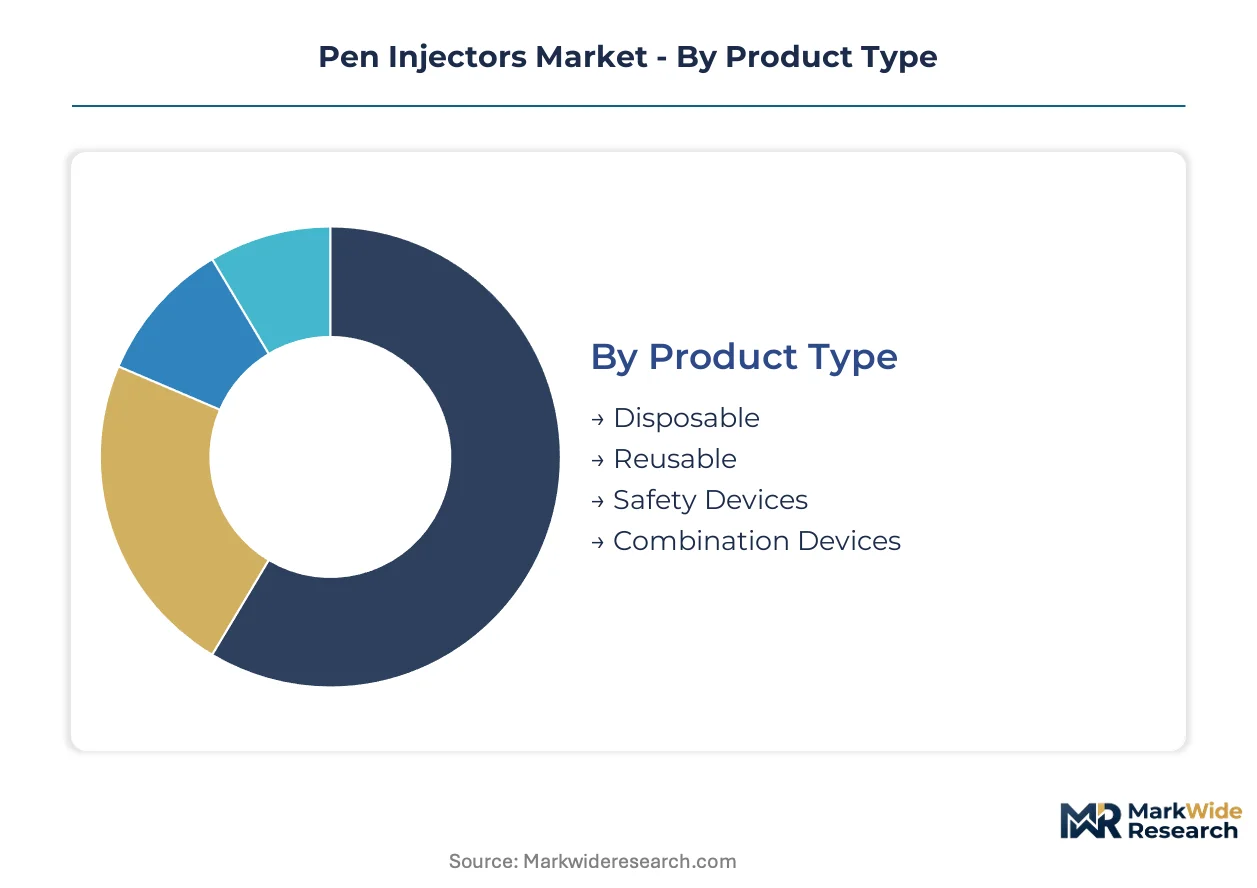
Pen injector segmentation reveals divergent margin structures across product formats and therapy areas. Disposable formats dominate volume while combination devices capture bundled pricing premiums with biologic franchises.
Product Type:
Disposable formats anchor volume shipments while reusable platforms concentrate in premium chronic therapy segments where patient training investment justifies device longevity.
- Disposable:Single-use pen injectors eliminate reprocessing liability and sterilization validation costs for pharmaceutical sponsors. Demand concentrates in United States homecare settings where payors mandate outpatient self-administration of insulin and GLP-1 therapies.
- Reusable:Durable pen chassis with replaceable cartridges reduce per-dose material costs for daily-injection regimens. Germany and Japan sustain premium positioning through refillable systems for growth hormone and autoimmune biologics where device familiarity improves adherence.
- Safety Devices:Needle-shielding mechanisms integrated into pen platforms address sharps injury prevention mandates.
- Combination Devices:Pre-integrated drug-device systems bundle delivery mechanisms with biologic franchises under single regulatory filings.
Today's leader: Disposable. Tomorrow's challenger: Combination Devices.
Delivery Mode:
Injection depth requirements segment manufacturing precision and regulatory validation pathways across therapy categories.
- Subcutaneous:Shallow tissue deposition dominates pen injector applications for insulin, GLP-1 agonists, and monoclonal antibodies. FDA human factors guidance for subcutaneous devices mandates dose confirmation feedback that shapes industrial design priorities in Massachusetts and Basel device clusters.
- Intramuscular:Deeper tissue penetration requires longer needle configurations and higher actuation force. Specialty clinics in Germany administer intramuscular depot formulations for long-acting antipsychotics and hormonal therapies where clinical supervision manages injection technique variance.
- Intravenous:Vascular access demands push pen format adaptation toward autoinjector hybrids with venous needle sets.
- Epidural:Neuraxial delivery applications concentrate in hospital-controlled settings with specialized training requirements.
Subcutaneous systems anchor current volume. Intramuscular platforms are expanding most quickly into long-acting formulations.
End User:
Site-of-care migration is fragmenting purchasing authority between pharmacy, procurement, and clinical stakeholders.
- Homecare:Patient self-administration outside clinical settings drives absolute demand growth for disposable pen formats. United States specialty pharmacy distributors now negotiate device specifications separately from biologic pricing, decoupling historical bundled contracting.
- Hospitals:Inpatient administration of acute therapies sustains demand for multi-dose pen systems with dose-tracking capabilities. Integrated delivery networks in the United States Midwest have established dedicated medical device value analysis committees distinct from pharmacy panels.
- Specialty Clinics:Initial training and complex therapy initiation concentrate in rheumatology and endocrinology practices.
- Pharmacies:Retail dispensing channels capture insulin pen distribution with direct-to-patient fulfillment models.
Homecare commands volume leadership. Specialty Clinics present the steepest expansion trajectory through patient-training ecosystem monetization.
Therapy Area:
Disease prevalence and biologic pipeline concentration determine addressable patient populations across geographic markets.
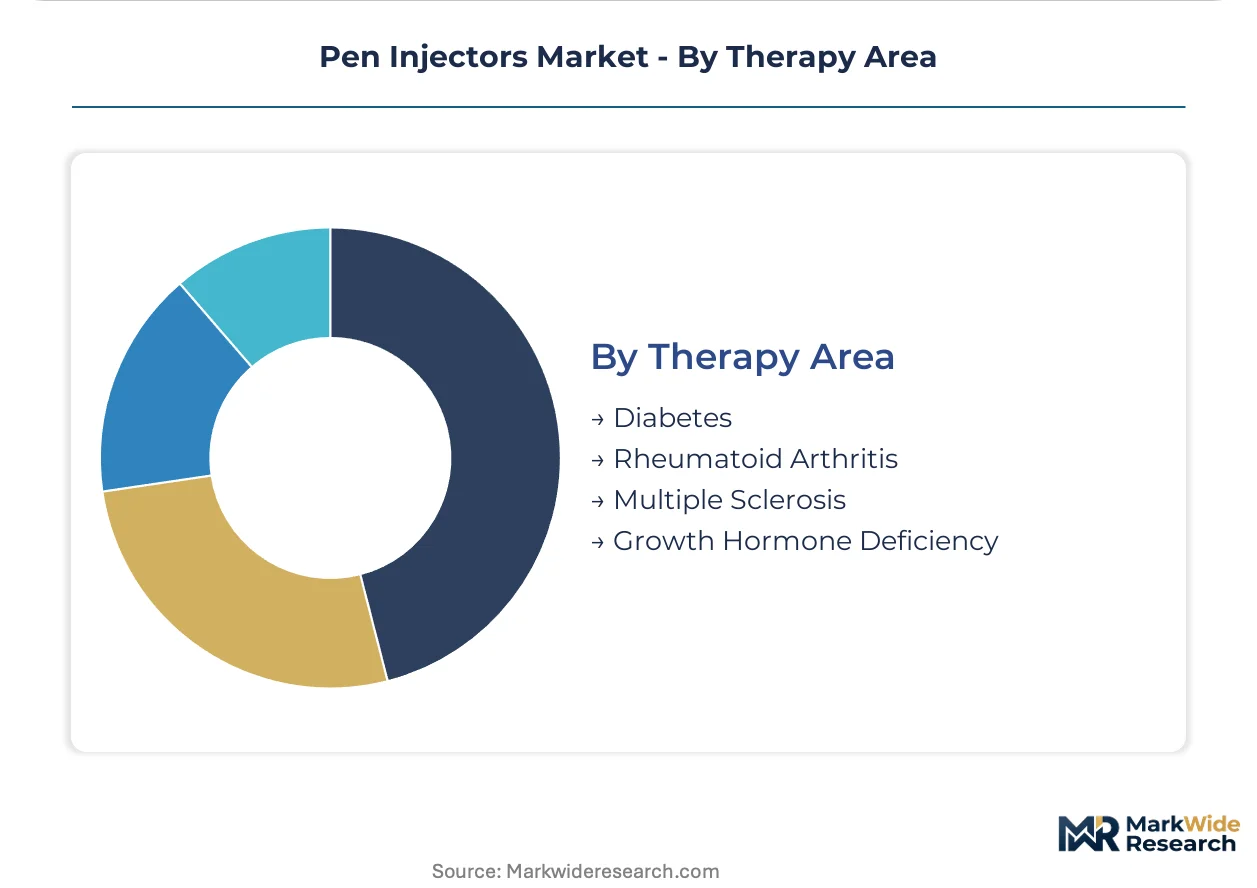
- Diabetes:Insulin and GLP-1 agonist delivery anchors pen injector volume with established reimbursement pathways. Novo Nordisk A/S and Eli Lilly and Company compete through connected pen platforms paired with dose-tracking software in United States and European markets.
- Rheumatoid Arthritis:Subcutaneous TNF-alpha inhibitors and IL-6 pathway biologics sustain premium reusable pen demand. Underpenetrated self-administration in India and Brazil creates first-mover advantage for patient-training ecosystem investments.
- Multiple Sclerosis:Interferon and monoclonal antibody regimens require precise dosing intervals that favor electronic dose-counters.
- Growth Hormone Deficiency:Pediatric and adult hormone replacement therapies concentrate in specialty endocrinology practices with high device training investment.
Diabetes maintains revenue concentration. Rheumatoid Arthritis offers the fastest share gain potential through geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Human factors engineering talent clusters in Basel, Boston, and Tokyo anchor device development capabilities. Regulatory divergence between FDA human factors guidance and EU MDR Annex I requirements fragments validation pathways. Manufacturing precision concentrates in Swiss metal-forming corridors and German polymer molding centers.
United States
Specialty pharmacy distributors now negotiate pen injector specifications separately from biologic pricing, decoupling historical bundled contracting. FDA human factors engineering guidance mandates iterative usability testing for premarket submissions. Massachusetts device clusters concentrate on connected pen platforms with dose-tracking software integration.
Germany
Refillable pen systems for growth hormone and autoimmune biologics sustain premium positioning through device familiarity effects. German notified bodies interpret EU MDR Annex I post-market clinical follow-up requirements most strictly for Class IIa injection devices. Cyclo-olefin polymer feedstock for transparent pen barrels concentrates among German chemical specialists in the Rhineland.
Japan
The PMDA Sakigake fast-track designation accelerates review for pen injectors with embedded adherence sensors. METI standards harmonization with ISO 11608 reduces re-certification costs for multi-territory launches. Tokyo-Yokohama medical device corridors concentrate spring-actuated mechanism suppliers serving domestic biologic franchises.
Switzerland
Sub-millimeter tolerance stamping for dose-actuation mechanisms limits viable supplier pools to Swiss metal-forming specialists. Swissmedic device-drug combination product oversight requires joint post-market surveillance agreements under 21 CFR Part 4 equivalence. Basel pharma-device integration clusters host captive fill-finish networks compressing development cycles.
India
Rheumatoid arthritis and psoriasis biologics remain predominantly clinic-administered, creating first-mover advantage for patient-training ecosystem investments. CDSCO medical device rules increasingly reference ISO 11608 for needle-based injection systems. Maharashtra pharmaceutical corridors concentrate on disposable pen assembly for export markets.
Pen Injectors Market Competitive Landscape
The competitive structure tilts toward pharmaceutical-device integrators with captive manufacturing networks. Tiered concentration separates multinational biologic sponsors with in-house pen platforms from independent device specialists serving second-source arrangements. Two strategic archetypes dominate: vertically integrated pharma-device hybrids and modular component specialists. Capacity consolidation and regulatory documentation partnerships constitute the dominant competitive moves.
Within the integrated pharma-device tier, Novo Nordisk A/S and Eli Lilly and Company exemplify archetypes of biologic sponsors controlling captive pen development. Ypsomed Holding AG occupies a specialist position serving multiple pharmaceutical clients through modular cartridge systems. These three entities represent the spectrum from full vertical integration to component specialization.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| Ypsomed Holding AG |
| Becton Dickinson and Company |
| AstraZeneca |
| Pfizer Inc. |
| Merck KGaA |
| Owen Mumford Ltd. |
| Others |
Value Network & Pricing Analysis
Cyclo-olefin polymer feedstock for transparent pen barrels flows from German and Japanese chemical specialists through precision molders to pharmaceutical sponsors, with material concentration upstream compressing margin pools at the device assembly tier while ISO 11608 certification requirements downstream sustain premium pricing for validated suppliers.
Pricing Analysis
Bundled device-drug contracting historically dominated pen injector procurement, though United States specialty pharmacy distributors and German hospital procurement consortia now unbundle device specifications from biologic pricing. Three-tier pricing structure across premium connected pens, standard disposable formats, and economy reusable chassis reflects FDA human factors documentation depth and Bluetooth connectivity integration. Pricing pressure stems from pharmaceutical sponsors internalizing device development to capture margin pools previously allocated to contract manufacturers. Small molecule generic sponsors exhibit highest price sensitivity, while biologic originators with captive fill-finish networks absorb premium positioning for combination devices.
Supply Chain Analysis
Dual-sourcing mandates from pharmaceutical sponsors require qualified secondary suppliers for dose-actuation spring assemblies, forcing device manufacturers to maintain relationships with both Swiss and South Korean metal-forming specialists. Manufacturing precision concentrates in Switzerland for sub-millimeter tolerance stamping, Germany for polymer molding, and Japan for electronic dose-counter integration. Raw material dependencies span medical-grade cyclo-olefin polymers, stainless steel for spring mechanisms, and lithium cells for connected platforms. Single-source vulnerability concentrates in German cyclo-olefin polymer feedstock. Distribution runs through pharmaceutical sponsor captive networks and contract manufacturing organizations with dedicated device value streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pen injectors market functions as a stable compounder anchored by irreversible site-of-care migration toward homecare self-administration, with chronic disease prevalence and biologic pipeline expansion sustaining replacement demand across decade-long patient regimens.
For Market Incumbents: Extend regulatory documentation moats by front-loading EU MDR clinical usability studies before device-drug pairing decisions, compressing competitive timelines for follow-on entrants. Deepen captive fill-finish integration to capture margin pools from contract manufacturers. Prioritize human factors engineering talent acquisition in Basel and Boston metro clusters where hybrid skill scarcity limits competitor replication.
For New Entrants and Emerging Players: Specialty rheumatology clinics in India and Brazil represent an underserved buyer archetype with predominantly clinic-administered biologics and minimal patient-training infrastructure. Target modular cartridge interoperability standards to reduce switching costs for patients rotating between insulin and GLP-1 therapies. Pursue Japan PMDA Sakigake fast-track designation for connected pen platforms with embedded adherence sensors as a differentiated regulatory pathway.
For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical sponsors seek to internalize device development capabilities previously outsourced to contract manufacturers. Five-to-ten year viability favors vertically integrated pharma-device hybrids with captive manufacturing networks over standalone component specialists vulnerable to sponsor insourcing. Monitor FDA software-as-medical-device reclassification proceedings for connected pen dose-tracking apps as an inflection signal for additional clinical validation obligations.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Annex I Compliance Pathway | German notified bodies' strict interpretation elevates documentation barriers against low-cost competitors lacking clinical usability studies. |
| Connected Device Platform Integration | Bluetooth-enabled dose-tracking paired with companion apps captures adherence data streams valued by United States payors. |
| Modular Cartridge Standardization | Interoperable 3mL geometry across therapy areas reduces patient switching costs between insulin and GLP-1 agonists. |
| Captive Fill-Finish Network Expansion | In-house production of device-drug combination products compresses development cycles and captures margin pools from contract manufacturers. |
| Japan PMDA Sakigake Designation | Fast-track review for digital therapeutics integration accelerates market entry for pen injectors with embedded adherence sensors. |
Research Methodology
Bottom-up homecare and specialty clinic modeling reconciled against top-down pharmaceutical sponsor device procurement tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors, hospital procurement managers, biomedical engineers at integrated delivery networks, and GPO contracts specialists combined with secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, ISO 11608 technical committee outputs, and pharmaceutical sponsor SEC disclosures. Triangulation across supply-side capacity announcements and demand-side formulary placement data ensures segment-level precision.
Historical trendline analysis of pen injector shipments by product format, therapy area, and geographic market established baseline growth patterns. Forecast outputs reflect modeled trajectories across disposable versus reusable platforms, subcutaneous versus intramuscular delivery modes, diabetes versus rheumatoid arthritis versus multiple sclerosis therapy areas, and United States versus Germany versus Japan versus India regulatory clusters. CAGRs derive from patient population epidemiology, biologic pipeline conversion rates, and site-of-care migration velocity. Human factors engineering talent availability and medical-grade polymer supply concentration function as industry-specific forecast inputs.
Underlying measurement precision varies by segment; established United States and European markets carry tighter precision than emerging Indian and Brazilian markets where patient-training infrastructure data remains sparse. Forecasts reflect documented assumptions regarding EU MDR implementation timelines, FDA software-as-medical-device classification evolution, and pharmaceutical sponsor vertical integration propensity. Deviation in regulatory reclassification of connected pen companion apps would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Syringe Filling Machine Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Pathology Devices Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Nephrostomy Catheters Market