
 Italy Contraceptive Devices Market | 2026-2036
Italy Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Contraceptive Devices Market Foresight
Italy is reconfiguring its contraceptive supply base through domestic pharmaceutical manufacturing investments and expanded sterilization capacity. Bayer AG leverages its hormonal IUD platform to sustain clinical channel dominance across Italian hospital networks. Pfizer Inc. competes through oral contraceptive formulations that anchor pharmacy shelf presence nationwide. Teva Pharmaceutical Industries Ltd. differentiates via generic hormone delivery systems that occupy price-sensitive segments in southern regions.
Contraceptive devices encompass barrier, hormonal, and intrauterine systems engineered from latex, silicone, copper, or synthetic progestin matrices to prevent conception through physical obstruction, chemical inhibition, or localized hormone release. Copper IUDs incorporate wire-wound polyethylene frames with surface areas calibrated for sustained spermicidal ion release over multi-year intervals. The IUD segment leads value generation due to extended replacement cycles and higher per-unit reimbursement rates, while condoms sustain volume throughput through supermarket and online retail channels. Clinic-administered delivery dominates margin capture, as provider-supervised insertion of long-acting devices commands premium positioning over self-administered alternatives.
Italy's AIFA sets pharmaceutical reimbursement tiers and contraceptive eligibility criteria that directly shape patient access patterns and manufacturer pricing negotiations. The Ministry of Health enforces CE-marked medical device standards under EU MDR transition timelines, compelling copper IUD and hormonal system suppliers to recertify technical documentation. Stakeholders must monitor regional health authority procurement centralization in Emilia-Romagna and Tuscany, where pooled purchasing agreements are consolidating vendor selection criteria.
Market Dynamics
Italy's contraceptive device sector is reorienting around AIFA reimbursement revisions that redirect patient flows toward clinic-administered long-acting reversible contraceptives, compressing pharmacy-dependent oral contraceptive volumes while elevating hospital procurement leverage.
Growth Catalysts
- AIFA Tier Realignment:Italy's pharmaceutical reimbursement authority has elevated hormonal intrauterine devices to higher coverage tiers, reducing out-of-pocket costs and accelerating clinic uptake across Lombardy and Veneto hospital networks.
- Metropolitan Pharmacy Density:Northern corridor cities including Milan and Turin maintain concentrated over-the-counter access points that sustain barrier method volumes through supermarket and online retail integration.
- Copper IUD Recertification:EU MDR transition timelines are compelling domestic sterilization capacity investments that strengthen local supply security for wire-wound polyethylene frame systems.
Market Restraints
- Silicone Raw Material Concentration:Hormonal IUD membrane suppliers face input cost volatility from concentrated Asian silicone polymer feedstock sources, pressuring domestic manufacturing margins.
- Southern Regional Access Disparities:Price-sensitive segments in Italy's southern regions exhibit lower clinic network penetration, limiting long-acting reversible contraceptive adoption outside reimbursed hospital channels.
- Progestin Matrix Technical Limitations:Synthetic hormone release calibration remains constrained by batch variability in synthetic progestin matrix production, complicating multi-year efficacy claims.
Strategic Opportunities
- Emilia-Romagna Pooled Purchasing:Regional health authority procurement centralization is consolidating vendor selection criteria, creating entry pathways for domestic sterilization capacity holders.
- Telehealth Channel Integration:Remote consultation platforms are emerging as prescription initiation points for self-administered hormonal methods, bypassing traditional gynecology clinic queues.
- Tuscany Sustainability Incentives:EU Green Deal alignment is channeling regional health investments toward reusable and biodegradable barrier method alternatives.
Industry Challenges
- CE-Marked Technical Documentation Recertification:EU MDR transition demands extensive clinical evidence resubmission for legacy copper IUD systems, stretching regulatory affairs capacity across Italian manufacturers.
- Gynecological Insertion Skill Pipeline:Clinic-administered device expansion requires trained provider networks that current residency programs are not scaling to match demand velocity in northern metropolitan corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Contraceptive Devices Market |
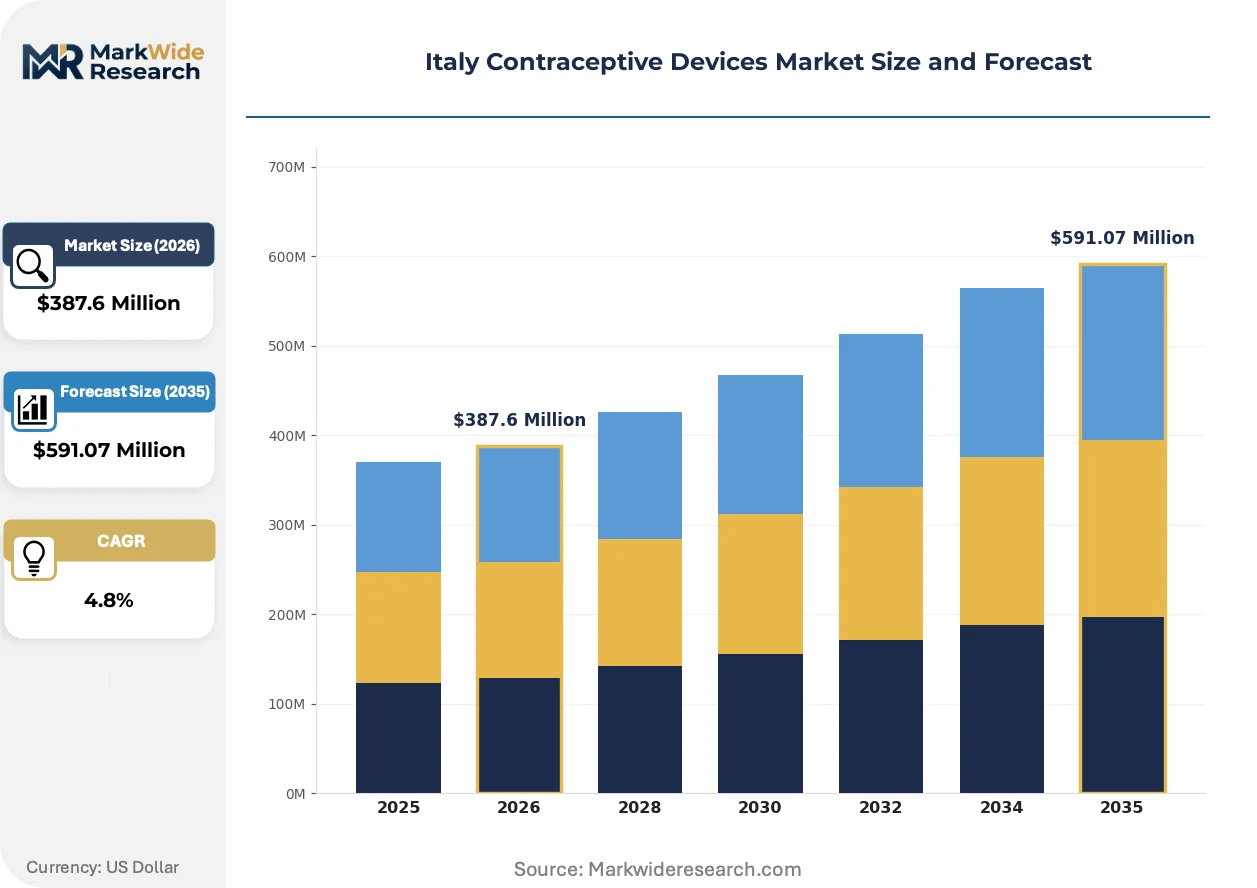
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condoms, IUDs, Pill, Patch End User: Individuals, Clinics, Hospitals, Pharmacies Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Customer Type: Teenagers, Adults, Married Couples, Single Individuals |
| Companies Covered | Bayer AG, Merck & Co. Inc., Pfizer Inc., AbbVie Inc., CooperSurgical Inc., Mylan Laboratories, Reckitt Benckiser, Teva Pharmaceutical Industries Ltd., HRA Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Contraceptive Devices Market Shifts & Advancements
Digital health infrastructure is virtualizing patient touchpoints across Italy's contraceptive access chain, compressing traditional clinic-dependent workflows while regulatory harmonization and procurement consolidation reshape competitive entry barriers.
Biodegradable polymer research is virtualizing the material foundation of barrier contraceptives, replacing conventional latex and silicone with plant-derived films that decompose post-use. Milan-based research consortia are piloting these formulations through pharmacy retail trials. The structural consequence is virtualizing sustainability credentials as a procurement differentiator in Tuscany and Emilia-Romagna regional tenders.
AIFA's reimbursement tier revisions are compressing oral contraceptive pharmacy margins while elevating hospital-administered long-acting systems to preferred status. The industrial consequence is vendor consolidation around clinical channel specialists capable of managing pooled purchasing negotiations. Hormonal IUD manufacturers with existing hospital network relationships are capturing disproportionate volume in Lombardy and Veneto procurement cycles.
Patient-initiated switching between contraceptive modalities is accelerating as telehealth platforms reduce consultation friction for method changes. Younger demographics in Turin and Milan are bypassing traditional six-month gynecology appointments through app-based prescription renewals. This behavioral shift is most visible in northern metropolitan corridors where pharmacy network density supports rapid product access following virtual consultations.
Italy Contraceptive Devices Market Segmentation
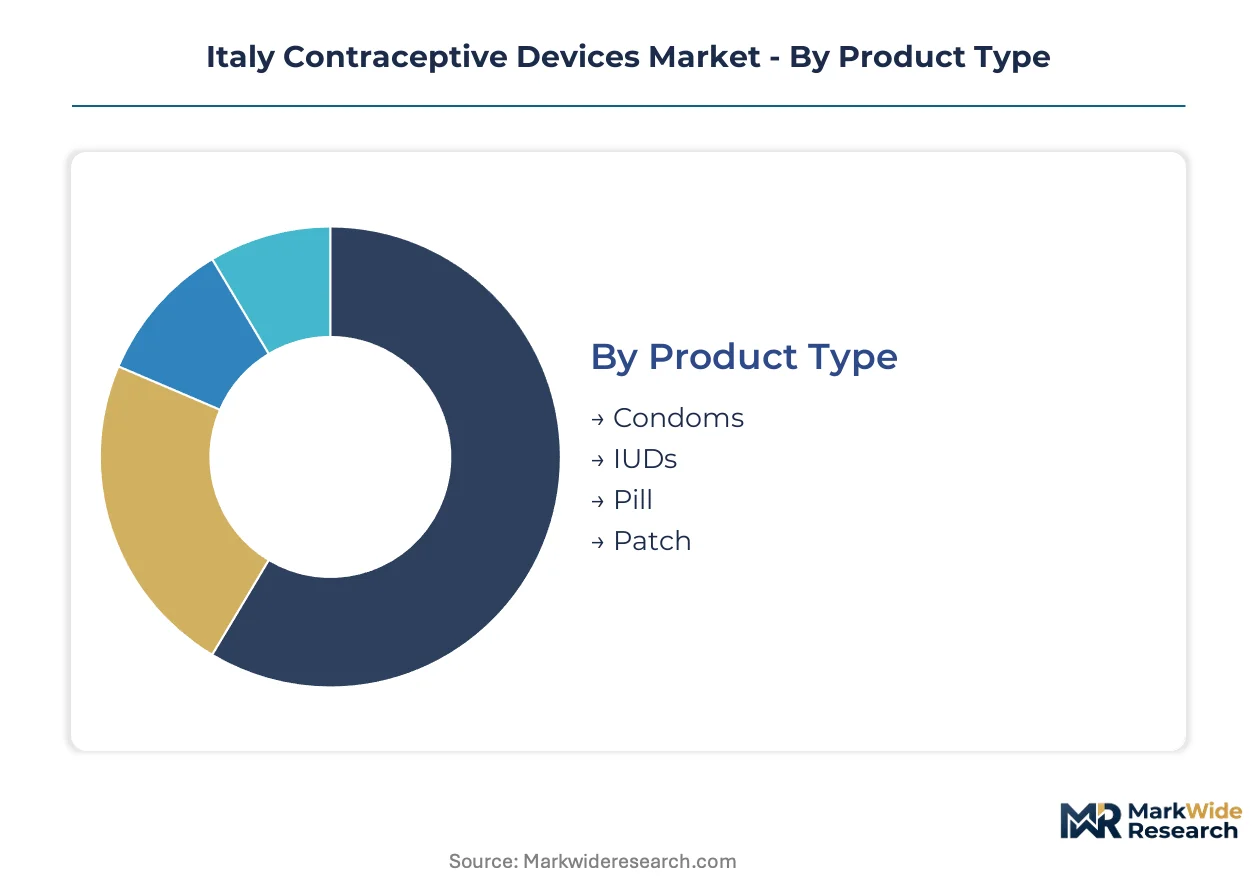
Segmentation in Italy's contraceptive devices market reveals how AIFA reimbursement tiers and regional procurement centralization allocate volume across competing access channels. Manufacturers must align product specifications with the technical and regulatory requirements of each segment to capture preferred vendor status in hospital networks and pharmacy retail.
Product Type:
Mature hormonal delivery systems coexist with emerging biodegradable alternatives across Italy's northern manufacturing corridor.
- IUDs:Copper wire-wound polyethylene frames and synthetic progestin matrix systems deliver multi-year contraception through spermicidal ion release or localized hormone diffusion. Lombardy and Veneto hospital procurement cycles favor these clinic-administered devices following AIFA tier elevation that reduced patient out-of-pocket exposure.
- Condoms:Latex and silicone barrier methods dominate over-the-counter volume through Milan and Turin pharmacy density, with biodegradable polymer variants entering Tuscany retail trials under EU Green Deal alignment.
- Pill:Oral hormonal formulations anchor pharmacy shelf presence nationwide, though AIFA reimbursement compression is redirecting patient flows toward long-acting alternatives.
- Patch:Transdermal hormone delivery occupies niche positioning for patients seeking self-administered alternatives to daily oral regimens.
IUDs handle the majority of throughput; biodegradable condom variants are expanding most quickly on share.
End User:
Cost tier stratification separates reimbursed institutional procurement from direct-pay individual access across Italy's regional health system.
- Hospitals:Institutional procurement in Lombardy and Veneto leverages pooled purchasing agreements to negotiate volume discounts on long-acting reversible contraceptives, with AIFA tier alignment accelerating hormonal IUD uptake.
- Clinics:Gynecology practices in northern metropolitan corridors manage insertion workflows for copper and hormonal IUD systems, though residency program output constraints limit provider network scaling.
- Pharmacies:Milan and Turin retail networks sustain barrier method and oral contraceptive volumes through high-density storefront coverage and supermarket integration.
- Individuals:Direct purchasing concentrates in price-sensitive southern regions where clinic network penetration remains lower and over-the-counter access substitutes for reimbursed channels.
Hospitals capture the dominant procurement volume; telehealth-integrated clinics are gaining share fastest through prescription initiation bypass.
Distribution Channel:
Geographic concentration in northern Italy shapes channel performance, with urban density favoring retail integration and rural access relying on direct delivery mechanisms.
- Online Retail:E-commerce platforms aggregate barrier method and oral contraceptive demand, particularly among younger demographics in Turin and Milan seeking discretion and rapid fulfillment.
- Supermarkets:Mass retail integration in northern corridor cities sustains condom volume through high-frequency purchase occasions and impulse placement strategies.
- Specialty Stores:Pharmacy networks maintain clinical credibility for hormone delivery consultations, though their contraceptive margin compression under AIFA revisions limits expansion investment.
- Direct Sales:Hospital and clinic procurement channels handle long-acting device distribution through centralized tender processes in Emilia-Romagna and Tuscany.
Supermarkets and online retail split the majority of barrier method throughput; telehealth-linked direct sales are climbing the fastest on prescription-initiated volume.
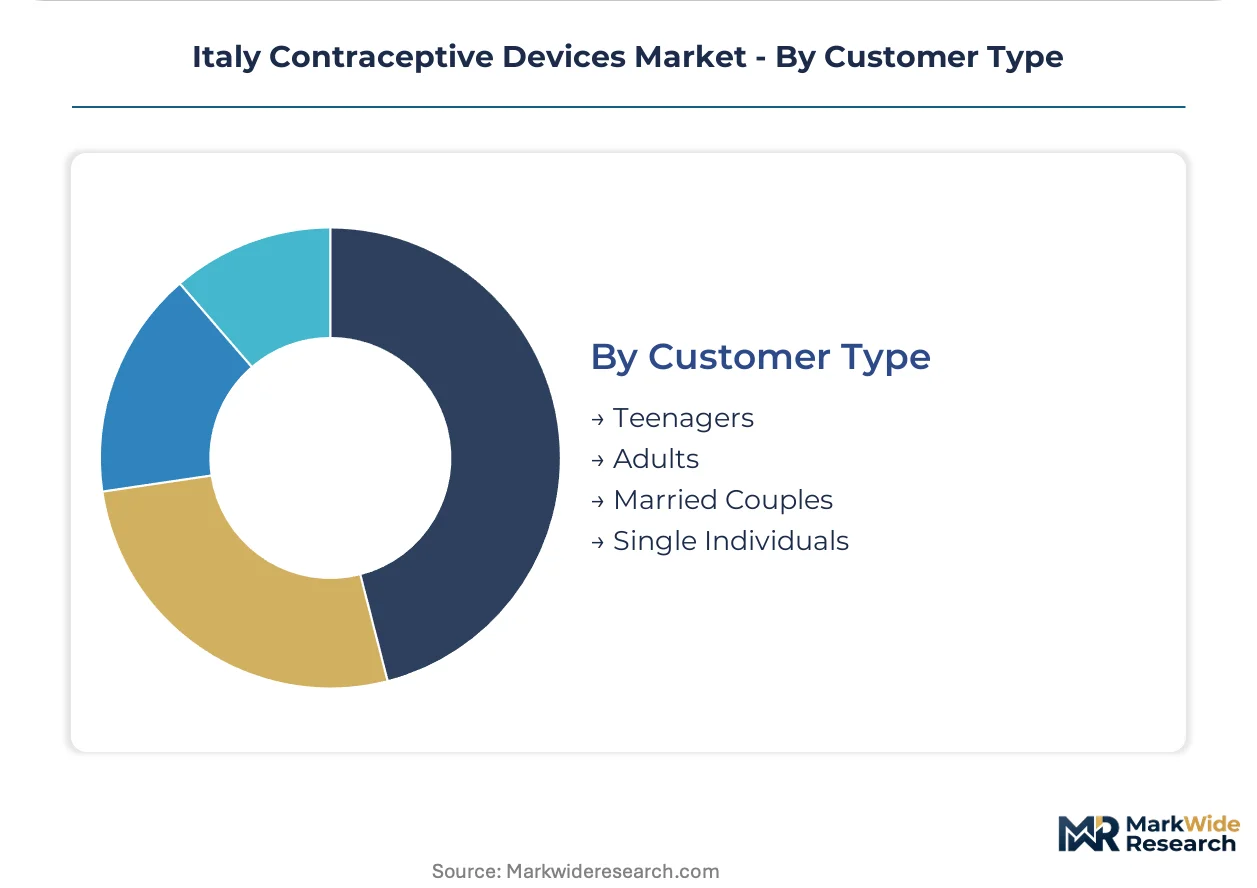
Customer Type:
Application context varies sharply between method-switching adults and first-time users, with marital status influencing reimbursement eligibility and access channel selection.
- Adults:Method-switching patients aged 25-40 dominate hormonal IUD uptake in reimbursed hospital channels across Lombardy and Veneto, driven by AIFA tier alignment reducing out-of-pocket costs.
- Single Individuals:Younger demographics in Milan and Turin metropolitan areas leverage app-based prescription renewals and pharmacy network density for rapid product access following virtual consultations.
- Married Couples:Joint decision-making patterns favor long-acting reversible methods with lower ongoing compliance requirements, aligning with hospital-administered IUD positioning.
- Teenagers:Access constraints through parental consent requirements and gynecology appointment friction limit independent procurement, channeling demand toward pharmacy-retail barrier methods.
Adults handle the majority of reimbursed device throughput; single individuals are expanding most quickly through telehealth-integrated access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's contraceptive device supply chain clusters in northern manufacturing corridors, with sterilization capacity and pharmaceutical formulation concentrated in Lombardy and Piedmont. AIFA reimbursement policy and regional health authority procurement centralization determine competitive access across sub-regional markets.
Lombardy
Milan anchors hospital procurement of hormonal intrauterine devices through dense clinic networks and AIFA-aligned reimbursement tiers. The region's sterilization infrastructure supports domestic manufacturing of copper IUD wire-wound polyethylene frames. Pooled purchasing agreements in Milan metropolitan hospitals consolidate vendor selection around clinical channel specialists.
Piedmont
Turin's pharmacy network density sustains over-the-counter barrier method volumes through supermarket and online retail integration. The regional health authority channels EU Green Deal investments toward biodegradable polymer research consortia. Manufacturing facilities in Turin corridor cities supply latex and silicone raw materials to northern retail distribution hubs.
Veneto
Padua and Verona hospital networks accelerate long-acting reversible contraceptive uptake following AIFA tier elevation that reduced patient out-of-pocket exposure. The region's gynecology residency programs face pipeline constraints limiting provider network scaling for IUD insertion workflows. Regional procurement centralization favors vendors with existing hospital network relationships.
Emilia-Romagna
Bologna-based pooled purchasing agreements consolidate vendor selection criteria for copper and hormonal IUD systems across public hospital networks. The regional health authority directs sustainability incentives toward reusable barrier method alternatives. Domestic sterilization capacity investments strengthen local supply security for clinic-administered devices.
Tuscany
Florence and Pisa retail trials pilot biodegradable polymer condom variants under EU Green Deal alignment. Regional health investments channel toward pharmacy-network sustainability credentials as procurement differentiators. Lower clinic network penetration in rural sub-regions limits long-acting reversible contraceptive adoption outside reimbursed channels.
Italy Contraceptive Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and sterilization services. Italy's contraceptive device sector exhibits tiered consolidation around multinational pharmaceutical manufacturers with hospital network relationships and domestic generic specialists occupying price-sensitive segments. Three archetypes dominate: hormonal delivery platform owners, barrier method mass-market suppliers, and regional generic manufacturers. Competitive moves concentrate on AIFA reimbursement tier positioning and regional procurement centralization capture.
Among multinational platform owners, Bayer AG and Pfizer Inc. exemplify divergent channel strategies—Bayer anchoring clinical administration through hormonal IUD hospital networks, Pfizer sustaining pharmacy shelf presence via oral contraceptive formulations. Teva Pharmaceutical Industries Ltd. occupies the generic specialist tier, representing price-competitive hormone delivery positioning in southern regional markets where clinic access disparities persist.
| Leading Market Players |
|---|
| Bayer AG |
| Merck & Co. Inc. |
| Pfizer Inc. |
| AbbVie Inc. |
| CooperSurgical Inc. |
| Mylan Laboratories |
| Reckitt Benckiser |
| Teva Pharmaceutical Industries Ltd. |
| HRA Pharma |
| Others |
Supply & Pricing Matrix
EU MDR recertification timelines expose Italian manufacturers to dual cost pressures that compress margins on legacy copper IUD systems while elevating pricing tiers for compliant hormonal platforms. This regulatory chokepoint widens spreads between hospital-procured clinic-administered devices and pharmacy-retail barrier methods, simultaneously accelerating sterilization capacity localization and silicone polymer feedstock diversification.
Pricing Analysis
AIFA reimbursement tier dictates the pricing tier structure across Italy's contraceptive device landscape, separating premium-positioned hormonal IUDs with elevated coverage from compressed-margin oral contraceptives facing pharmacy reimbursement cuts. Price differentiation hinges on CE-marking status under EU MDR and clinical administration requirement, with hospital-procured long-acting systems commanding favorable positioning over self-administered alternatives. Pricing pressure intensifies in southern regional markets where clinic network gaps limit reimbursed channel access. Price-sensitive individual purchasers in Sicily and Calabria exhibit highest sensitivity to out-of-pocket exposure, while Lombardy hospital systems leverage pooled purchasing for lowest net acquisition costs.
Supply Chain Analysis
Export-control scrutiny on medical-grade silicone polymers limits feedstock flows from concentrated Asian suppliers, compelling Italian manufacturers to diversify progestin matrix membrane sourcing. Production draws from Germany, the Netherlands, and domestic Lombardy sterilization facilities for copper IUD wire-wound frames. Raw material dependencies center on Malaysian silicone polymer feedstock, German precision extrusion equipment, and Belgian pharmaceutical-grade hormone suppliers. Single-source vulnerability in Asian silicone concentration threatens margin stability for hormonal IUD platforms. Distribution runs through centralized hospital procurement in northern regions, pharmacy retail networks in metropolitan corridors, and direct-to-patient telehealth channels for prescription-initiated methods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through regional health authority pooled purchasing agreements in Emilia-Romagna and Tuscany, fragmenting vendor pricing leverage while elevating scale requirements for preferred supplier status.
For Market Incumbents: Pre-empt generic erosion in southern price-sensitive segments by securing backward integration into domestic sterilization capacity for copper IUD polyethylene frames. Anchor hospital network relationships through AIFA tier alignment investments that sustain premium positioning against emerging biodegradable barrier alternatives. Channel control through gynecology clinic partnership density in Lombardy and Veneto remains the critical defensive lever. For New Entrants and Emerging Players: Build out telehealth-integrated prescription initiation platforms targeting single individuals in Milan and Turin metropolitan corridors, where app-based consultation bypasses traditional clinic queues. Southern regional markets present the most penetrable geography given clinic access disparities and unmet demand for reimbursed long-acting alternatives. A sustainability-credentialed go-to-market angle aligns with Tuscany and Emilia-Romagna Green Deal procurement preferences. For Investors and Strategic Acquirers: EU MDR recertification deadlines reshape the acquisition landscape by straining regulatory affairs capacity at mid-tier Italian manufacturers and creating distressed asset opportunities. Long-term viability favors platform owners with hospital procurement relationships and diversified silicone polymer sourcing. The signal to watch is AIFA reimbursement tier expansion beyond current Lombardy-Veneto pilot regions, which would revalue clinical channel specialists.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Recertification | EU MDR compliance secures hospital procurement eligibility for copper IUD systems in Lombardy networks. |
| Hospital System Partnership | Pooled purchasing agreements in Emilia-Romagna consolidate vendor selection around clinical channel specialists. |
| Backward Integration | Domestic sterilization capacity investments reduce silicone polymer feedstock dependency on Asian suppliers. |
| Reimbursement Strategy | AIFA tier elevation for hormonal IUDs redirects patient flows from pharmacy oral contraceptives. |
| Sustainability Repositioning | Biodegradable polymer research aligns with Tuscany EU Green Deal procurement preferences. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, gynecology clinic administrators, pharmaceutical regulatory affairs leads, and pharmacy retail category buyers, then refined against secondary validation from AIFA reimbursement databases, EU MDR technical documentation filings, and Italian regional health authority tender records. Bottom-up volume estimates from product-level hospital procurement cycles were triangulated with top-down market sizing from pharmaceutical trade flow data.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, end-user channel, distribution mechanism, and regional procurement cluster. CAGRs were derived from trend extrapolation of AIFA reimbursement tier expansion patterns and hospital procurement cycle velocity. Industry-specific forecast inputs included gynecology residency program output constraints and silicone polymer feedstock price volatility indices.
Practitioners should monitor AIFA tier geographic expansion, EU MDR enforcement variance across notified bodies, and Asian silicone supply disruption indicators for early signals of forecast deviation. Material shifts in reimbursement eligibility criteria or MDR recertification timeline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
SPG Microstimulator System Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Medical Face Shield Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Ear Tube Devices Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
Surgical Robot Accessories Market
Medical Devices
APAC AMH Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market