
 Radio Frequency Duplexer Market | 2026-2036
Radio Frequency Duplexer Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Duplexer Market Intelligence
FCC Part 27 spectrum reallocation is expanding the engineering burden for duplexer vendors serving North American carriers. Murata leverages its ceramic filter expertise to sustain pricing power in high-band cellular applications. Broadcom anchors its position through in-house BAW resonator production for premium smartphone sockets. Qualcomm competes by integrating duplexer functions into modem-RF front-end platforms, compressing board space for OEM customers.
A radio frequency duplexer is a three-port passive device that enables simultaneous transmission and reception over a single antenna path by providing high isolation between transmit and receive frequency bands, typically achieving 50-60 dB rejection at adjacent channel offsets. It consists of paired bandpass filters—commonly surface acoustic wave (SAW), bulk acoustic wave (BAW), or ceramic structures—joined at a common antenna node to prevent transmitter power from desensitizing the receiver front end. Channel duplexers dominate volume shipments due to their ubiquity in consumer mobile devices, while waveguide duplexers command premium margins in satellite ground stations and radar installations where power handling exceeds kilowatt thresholds. RF MEMS technology represents the fastest-evolving segment, though analog architectures still occupy the majority of active installed base across legacy telecommunications infrastructure.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct spurious emission and intermodulation standards that dictate duplexer passband ripple and stopband attenuation requirements for market access. REACH compliance in the European Union further constrains material selection for ceramic substrates and metallization layers, elevating qualification costs for non-European suppliers. Stakeholders must monitor spectrum auction timelines and corresponding band plan changes, as these regulatory shifts determine which frequency pairs require new duplexer designs and which existing platforms face technical obsolescence.
Market Dynamics
The RF duplexer market faces acute pressure from 5G sub-6 GHz deployment timelines, where carrier aggregation schemes demand steeper filter skirts and tighter isolation specifications than legacy LTE architectures permitted. Smartphone OEMs now specify duplexer modules as integrated RF front-end subsystems rather than discrete components, compressing vendor qualification cycles and elevating design-in barriers for second-tier suppliers.
Growth Catalysts
- FCC Part 27 spectrum reallocation:Mandates for 600 MHz and C-band refarming in the United States are forcing carrier infrastructure refresh cycles, creating immediate demand for new duplexer designs matched to reconfigured frequency pairs.
- BAW resonator fabrication advances:Improved thin-film deposition control is extending bulk acoustic wave filter performance into 3.5-6 GHz ranges previously dominated by ceramic and SAW alternatives.
- South Korean base station buildouts:Domestic 5G network densification programs are anchoring regional procurement volumes for high-isolation channel duplexers in sub-6 GHz macro and small cell deployments.
Market Restraints
- Aluminum nitride substrate supply concentration:High-purity AlN wafer production concentrates among Japanese and German specialty ceramic suppliers, exposing duplexer manufacturers to input cost volatility and allocation risk during demand surges.
- REACH substance restrictions:European Union regulations on nickel and cobalt compounds in metallization layers are forcing reformulation of electrode materials, extending qualification timelines for ceramic filter platforms.
- Module-level integration by modem vendors:RF front-end consolidation into modem-PA-filter assemblies threatens standalone duplexer socket availability in premium smartphone tiers.
Strategic Opportunities
- Open RAN architecture adoption:Disaggregation of base station radio units from baseband processing is creating procurement pathways for specialized duplexer vendors into carrier networks previously closed to non-integrated suppliers.
- RF MEMS tunable filter platforms:Micro-electromechanical resonator technology enables software-defined duplexing across multiple band configurations, reducing SKU proliferation for multi-region device variants.
- India PLI scheme for telecom equipment:Production-linked incentive frameworks are attracting contract manufacturing investment for RF components serving domestic 5G rollout and export markets.
Industry Challenges
- Acoustic resonator modeling expertise scarcity:Finite-element simulation of coupled-mode BAW and SAW devices requires specialized physics-domain talent that remains concentrated among legacy filter houses and university research programs.
- Carrier certification timeline compression:FCC and PTCRB approval cycles for new band combinations now overlap with product launch windows, compressing design validation and field trial phases.
- Legacy infrastructure interoperability:Backward compatibility requirements for 2G/3G voice fallback in emerging markets complicate tri-band and quad-band duplexer integration with modern transceiver architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Duplexer Market |
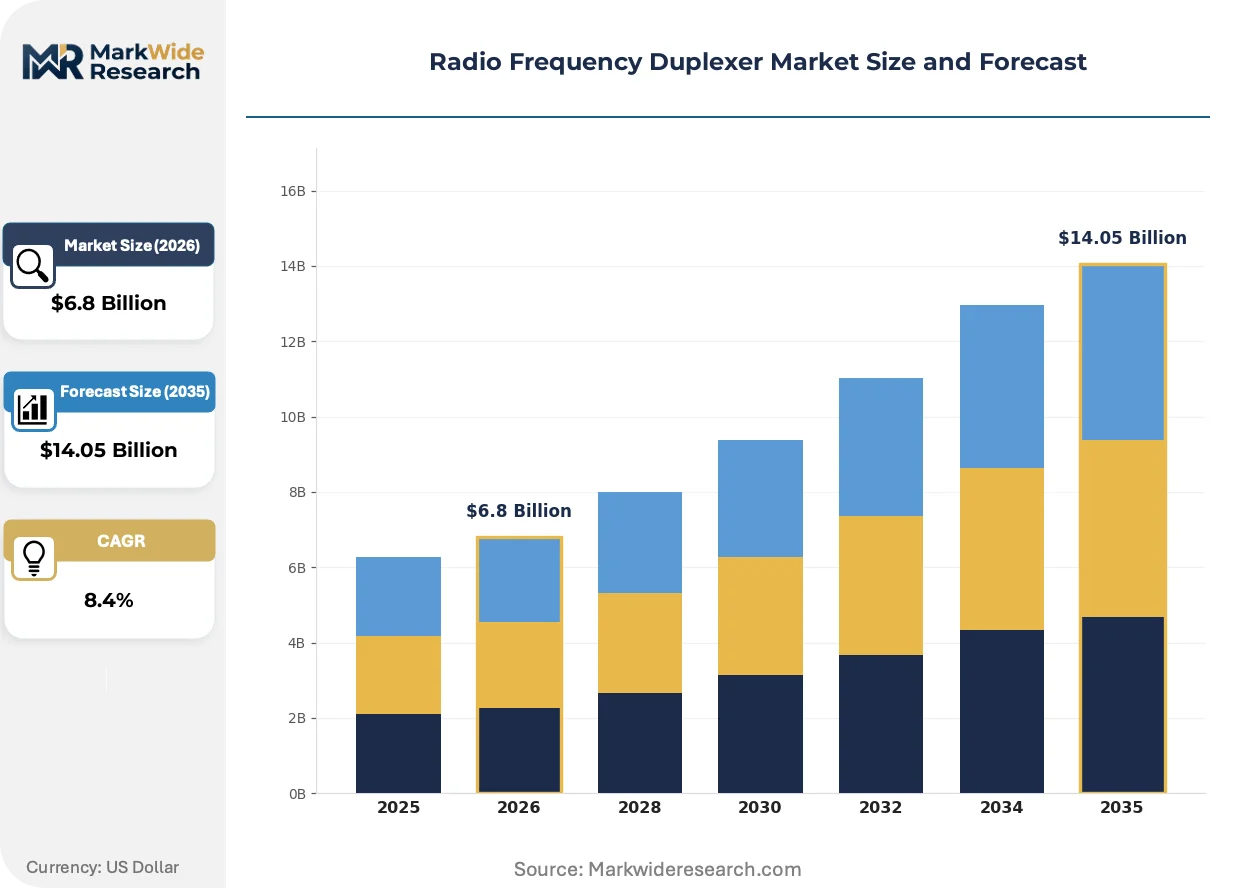
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Channel Duplexers, Coaxial Duplexers, Waveguide Duplexers, Microstrip Duplexers Technology: Analog, Digital, Hybrid, RF MEMS Application: Telecommunication, Broadcasting, Military, Aerospace End User: Telecom Operators, OEMs, Government Agencies, Research Institutions |
| Companies Covered | Murata, Taiyo Yuden, Broadcom, Samsung Electro-Mechanics, Qualcomm, Skyworks, TDK, Analog Devices, Qorvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Duplexer Market Strategic Shifts & Innovations
Filter technology trajectories are converging on acoustic-wave platforms that balance insertion loss against footprint constraints, while regulatory fragmentation across major economies is fragmenting product roadmaps. Procurement patterns are simultaneously shifting toward module-level sourcing that compresses the addressable market for discrete duplexer vendors.
BAW-SMR (solidly mounted resonator) technology is consolidating its position in mid-band cellular applications through improved quality factor and power handling relative to traditional FBAR constructions. Tier-one smartphone OEMs have standardized on BAW-SMR platforms for bands n77 and n78, displacing ceramic filter alternatives in sub-6 GHz carrier aggregation schemes. This consolidation is compressing the viable supplier base to vertically integrated resonator manufacturers with captive wafer fabrication.
ETSI harmonization efforts for 5G NR band plans are creating divergent compliance obligations across European member states despite nominal standardization. The F-Gas Regulation's phase-down of fluorinated greenhouse gases is constraining plasma etching chemistries used in BAW cavity formation, elevating process development costs for European-located fabrication. Filter vendors are responding by relocating critical etch processes to Asian foundry partners or investing in alternative dry-release techniques.
Carrier procurement of radio units now favors filter-integrated transmit-receive modules over discrete duplexer sourcing, compressing the commercial interface between duplexer specialists and network equipment OEMs. This transition is displacing traditional component distribution channels in favor of direct RF front-end platform supply agreements. The shift is most visible in North American carrier RFPs, where technical evaluation criteria now specify integrated module performance rather than individual filter specifications.
Radio Frequency Duplexer Market Segmentation
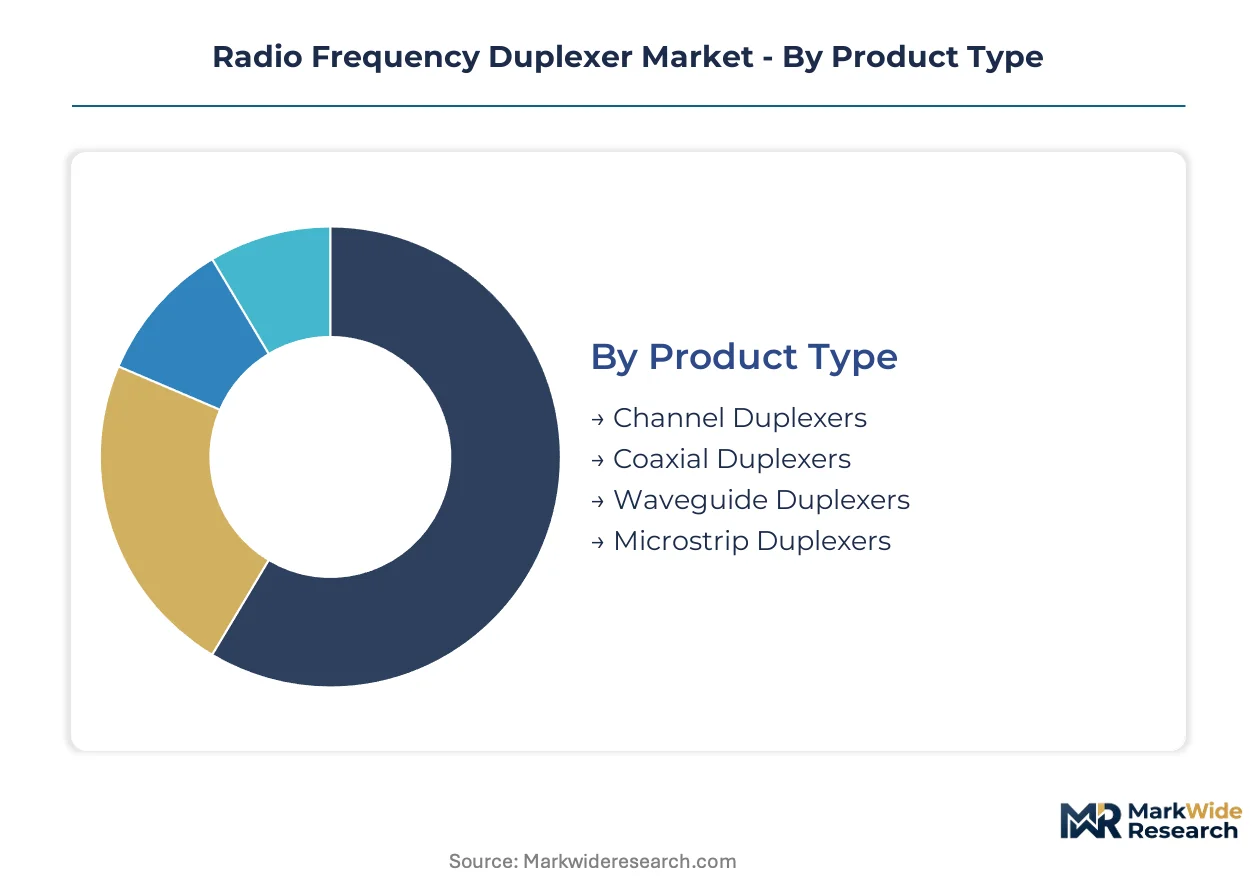
RF duplexer segmentation reflects divergent capital requirements across fabrication technologies and end-use reliability standards. Procurement patterns split between high-volume consumer electronics sockets and low-volume, high-margin defense-aerospace applications with radically different qualification protocols.
Product Type:
Capital intensity peaks with waveguide architectures requiring precision machining and specialized test chambers, while planar technologies leverage semiconductor fabrication economies.
- Channel Duplexers:Surface-mount acoustic-wave filters dominate smartphone RF front ends, with BAW-SMR constructions displacing ceramic alternatives in sub-6 GHz carrier aggregation schemes. South Korean OEM procurement concentrates demand for n77/n78 band modules.
- Waveguide Duplexers:Cavity-based architectures handle kilowatt-level power in satellite ground stations and radar installations. Japanese and German specialty suppliers command premium pricing through captive high-purity aluminum nitride substrate production.
- Coaxial Duplexers:Cylindrical resonator structures serve cellular base stations and test equipment requiring moderate isolation.
- Microstrip Duplexers:Printed circuit implementations address cost-sensitive IoT and industrial telemetry applications.
Channel duplexers absorb the bulk of installed capacity; waveguide duplexers are expanding most quickly in satellite ground infrastructure.
Technology:
Process maturity separates analog acoustic platforms from emerging digitally-assisted architectures, with hybrid approaches gaining traction in multi-band military systems.
- Analog:SAW and BAW resonator technologies constitute the active installed base across legacy telecommunications infrastructure. Murata and Broadcom maintain resonator fabrication dominance through thin-film deposition expertise.
- RF MEMS:Micro-electromechanical resonators enable software-defined duplexing with tunable center frequencies. Qualcomm integrates these structures into modem-RF platforms for multi-region smartphone variants.
- Digital:DSP-based interference cancellation reduces analog filter order requirements in cognitive radio applications.
- Hybrid:Combined acoustic-digital architectures address military systems requiring rapid band reconfiguration under jamming conditions.
Analog platforms retain manufacturing scale leadership; RF MEMS is climbing the fastest as smartphone OEMs consolidate front-end module sourcing.
Application:
Specification stringency escalates from commercial telecommunications through military-aerospace, with each tier imposing distinct reliability screening and documentation requirements.
- Telecommunication:5G sub-6 GHz deployment drives demand for high-isolation duplexers in carrier aggregation configurations. FCC Part 27 spectrum reallocation mandates fresh designs for 600 MHz and C-band frequency pairs.
- Military:Electronic warfare and secure communications require hermetic packaging and extended temperature operation. ETSI and national defense standards dictate spurious emission limits stricter than commercial equivalents.
- Broadcasting:Terrestrial television and radio transmitters utilize high-power handling duplexers with minimal insertion loss.
- Aerospace:Satellite payloads and avionics demand radiation-hardened components with qualification documentation traceable to mission-critical standards.
Telecommunication commands current volume leadership; military applications are gaining share fastest through classified program modernization cycles.
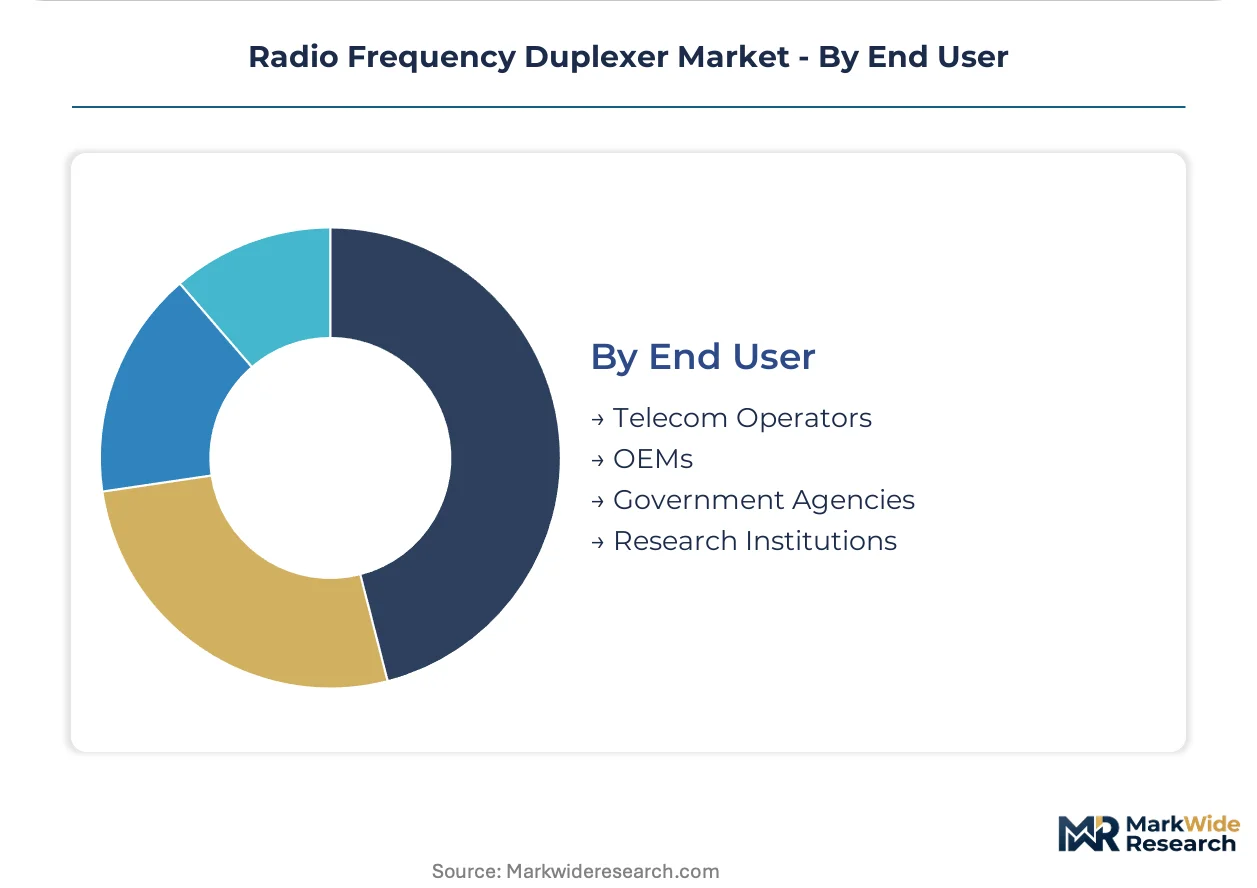
End User:
Procurement authority concentrates among integrated OEMs and government agencies, squeezing standalone component distribution channels.
- OEMs:Samsung Electro-Mechanics and vertically integrated smartphone manufacturers specify duplexer modules as RF front-end subsystems rather than discrete components. Direct platform supply agreements displace traditional distribution.
- Government Agencies:Defense procurement offices in the United States, South Korea, and European NATO members mandate domestic-source requirements and ITAR compliance for tactical communications programs.
- Telecom Operators:Carrier RFPs for Open RAN radio units now specify integrated filter-PA modules, compressing the commercial interface with duplexer specialists.
- Research Institutions:National laboratories and university programs drive early-stage RF MEMS and tunable filter development through sponsored research.
OEM procurement absorbs dominant manufacturing capacity; government agency demand is expanding most quickly through classified telecommunications modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea concentrate RF component manufacturing through tax incentives and infrastructure support. Domestic 5G network densification programs anchor regional procurement volumes. Government-backed semiconductor clusters accelerate technology transfer from research institutions to commercial production.
United States
FCC Part 27 spectrum reallocation mandates for 600 MHz and C-band refarming force carrier infrastructure refresh cycles. The FCC enforces spurious emission standards that dictate duplexer passband ripple requirements. Austin and Boston host RF design centers where engineering teams compress qualification timelines for new frequency pairs.
South Korea
Samsung Electro-Mechanics and domestic base station suppliers anchor regional supply agreements for high-isolation duplexers. The Ministry of Science and ICT funds 5G equipment localization programs through direct subsidies. Pangyo Techno Valley clusters fabless design houses with packaging and test facilities for front-end module integration.
Japan
METI promotes domestic production of high-purity aluminum nitride substrates through supply chain security initiatives. REACH-aligned material restrictions from European export markets constrain electrode formulations for ceramic filter platforms. Kyoto-Osaka industrial corridors concentrate thin-film deposition expertise for BAW resonator fabrication.
China
MIIT spectrum auctions for 5G sub-6 GHz bands drive base station deployment timelines requiring steeper filter skirts. GB standards for electromagnetic compatibility impose distinct intermodulation requirements separate from ETSI or FCC frameworks. Shenzhen and Dongguan manufacturing clusters integrate SAW filter production with smartphone assembly ecosystems.
Germany
ETSI harmonization efforts create compliance obligations for duplexers exported into European carrier networks. The F-Gas Regulation constrains plasma etching chemistries used in BAW cavity formation, elevating process development costs. Munich and Stuttgart host automotive-telecom convergence labs testing V2X duplexer modules for connected vehicle platforms.
Radio Frequency Duplexer Market Key Industry Players
Japanese producers anchor one tier through ceramic filter expertise and substrate supply control; American specialists hold another through modem-RF platform integration. The vendor base splits between vertically integrated resonator manufacturers and fabless design houses dependent on external foundry access. Three archetypes dominate: captive wafer fabricators with thin-film deposition control, module integrators compressing board space for OEMs, and specialty ceramic suppliers commanding premium pricing in high-power applications. Competitive moves concentrate on strategic partnerships for AlN substrate allocation and technology licensing for BAW-SMR process nodes.
Within the integrated platform tier, Qualcomm and Broadcom exemplify contrasting approaches to front-end consolidation. Murata represents the ceramic filter archetype with sustained pricing power in high-band cellular sockets. Samsung Electro-Mechanics occupies a position bridging component supply and captive smartphone demand.
| Leading Market Players |
|---|
| Murata |
| Taiyo Yuden |
| Broadcom |
| Samsung Electro-Mechanics |
| Qualcomm |
| Skyworks |
| TDK |
| Analog Devices |
| Qorvo |
| Others |
Cost & Logistics Intelligence
REACH substance restrictions on nickel and cobalt compounds gate both qualified European supply and premium-tier pricing access for ceramic filter platforms, forcing reformulation investments that stratify vendor tiers by compliance capability.
Pricing Analysis
Lead-time-driven pricing angles dominate RF duplexer procurement, with premium tiers commanding short-lead-time allocation and spot inventory trading at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in economy-tier SAW filters is intensifying because of Chinese foundry overcapacity. Smartphone OEMs exhibit highest price sensitivity, while satellite ground station operators absorb premium pricing for hermetic packaging.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale smartphone manufacturer demand, displacing traditional component distribution. High-purity aluminum nitride wafer production concentrates in Japan and Germany, with BAW resonator fabrication anchored in South Korea and the United States. Supply chains draw from specialty ceramic substrates, thin-film deposition equipment, and precision machining tools. Single-source vulnerability in AlN substrate allocation elevates procurement risk during demand surges. Distribution runs through integrated RF front-end platform agreements rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive resonator fabrication and in-house substrate production determine margin sustainability against module-level consolidation threats.
For Market Incumbents: Acquire thin-film deposition equipment and AlN substrate fabrication assets to defend resonator supply control against fabless design house encroachment. Secure long-term supply agreements with Japanese specialty ceramic suppliers before allocation constraints tighten. Prioritize BAW-SMR process node licensing to maintain performance differentiation in n77/n78 bands. For New Entrants and Emerging Players: Capture Open RAN radio unit procurement pathways previously closed to non-integrated suppliers by targeting disaggregated base station architectures. Focus on RF MEMS tunable filter platforms for multi-region smartphone variants where software-defined duplexing reduces SKU proliferation. Pursue direct RF front-end module partnerships with second-tier smartphone OEMs seeking alternative sourcing. For Investors and Strategic Acquirers: FCC Part 27 spectrum auction announcements are the leading indicator that fresh duplexer design cycles will accelerate infrastructure refresh spending. Over the medium-to-long term, vertically integrated resonator manufacturers with captive wafer fabrication present superior acquisition profiles against fabless competitors. Monitor PTCRB certification timeline compression as a signal of vendor qualification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| BAW Resonator Fabrication Scale-Up | Captive thin-film deposition control secures pricing power in sub-6 GHz carrier aggregation sockets. |
| Aluminum Nitride Substrate Backward Integration | In-house high-purity ceramic production mitigates allocation risk from Japanese and German suppliers. |
| RF MEMS Tunable Filter Platform Launch | Software-defined duplexing enables multi-band coverage with reduced SKU proliferation for smartphone OEMs. |
| Open RAN Radio Unit Partnership | Disaggregated base station architectures create procurement pathways beyond traditional integrated OEM supply. |
| REACH-Compliant Electrode Reformulation | Nickel and cobalt substitution maintains European market access under evolving material restrictions. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with RF front-end procurement managers, BAW resonator fabrication engineers, carrier network equipment planners, and ceramic substrate supply specialists. FCC Part 27 dockets, ETSI harmonization documents, MIIT spectrum auction disclosures, and REACH substance restriction updates provided regulatory trajectory inputs. Bottom-up smartphone shipment forecasts and top-down carrier capex projections were triangulated against resonator wafer production estimates.
Granularity-level modeling addressed product type, technology platform, application vertical, and end-user procurement authority across the analysis window. CAGRs were derived from segment-level volume and value trajectories, with BAW-SMR adoption curves and RF MEMS penetration rates serving as key technology transition inputs. Carrier aggregation scheme evolution and spectrum refarming timelines shaped regional demand projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AlN substrate supply concentration, module-level integration by modem vendors, and regulatory fragmentation across FCC, ETSI, and MIIT frameworks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Global Inductors Market
RF Components
RFID Antenna Market
RF Components
RF Gan Market
RF Components
RF Front End Module Market
RF Components
RF Passive Component Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Global RF Power Semiconductor Market
RF Components
Z-Wave Products Market
RF Components
Radio Frequency Front End Module Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
Microwave Devices Market
RF Components
Tunable Capacitors Market
RF Components
Low Noise Amplifier Market
RF Components
High Power RF Amplifier Module Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
Wireless Module Market