
 Cognitive Systems Spending Market | 2026-2036
Cognitive Systems Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Systems Spending Market Analysis
Specialized AI accelerators are displacing general-purpose CPUs in cognitive workloads, which is realigning hardware procurement economics across enterprise buyers. NVIDIA Corporation dominates high-performance training clusters with its GPU architecture and captive software ecosystem. IBM Corporation anchors mainframe-attached cognitive deployments through its Watson platform integration with hybrid cloud infrastructure. Intel Corporation competes in inference-optimized silicon with dedicated neural processing units targeting edge cognitive applications.
Cognitive systems spending encompasses enterprise investment in hardware, software, services, and support required to deploy artificial intelligence platforms capable of perception, reasoning, learning, and autonomous decision-making, typically operating on structured and unstructured data streams exceeding terabyte-scale throughput with sub-second inference latency. These systems serve industrial and commercial purposes spanning predictive maintenance, automated customer interaction, supply chain optimization, and real-time risk scoring. Services and support currently capture disproportionate margin pools due to implementation complexity and ongoing model retraining requirements, while cloud deployment models are expanding fastest as organizations migrate from capital-intensive on-premises cognitive infrastructure to consumption-based platforms. Hardware retains structural importance at the frontier, where training foundation models demands dedicated accelerator clusters.
The EU AI Act classifies cognitive systems by risk tier, mandating conformity assessments for high-risk applications in healthcare and finance that directly shape product roadmaps and market access conditions. In the United States, NIST AI Risk Management Framework and FDA guidance on software as a medical device create dual compliance pathways for cognitive health platforms. Stakeholders must monitor divergence between European ex-ante regulation and American sector-specific enforcement, as this regulatory fragmentation will determine which cognitive system architectures achieve cross-border deployability.
Market Dynamics
Specialized AI accelerators are absorbing capital budgets that previously flowed to general-purpose CPUs, compressing hardware refresh cycles and forcing enterprise buyers to renegotiate cloud contracts around GPU-hour pricing rather than vCPU-core metrics.
Growth Catalysts
- EU AI Act conformity requirements:High-risk cognitive system deployments in healthcare and finance now mandate third-party conformity assessments, creating captive demand for certified implementation partners and compliant platform architectures.
- Federal AI investment directives:United States defense modernization budgets are channeling procurement toward cognitive infrastructure with classified-data handling capabilities, accelerating secure enclave deployments.
- Foundation model training clusters:Terabyte-scale unstructured data processing requirements are pulling enterprise spending toward dedicated accelerator hardware with sub-second inference latency specifications.
Market Restraints
- Accelerator supply concentration:High-performance GPU fabrication depends on TSMC's advanced node capacity in Taiwan, exposing buyers to single-source geographic risk for training cluster procurement.
- Energy input cost volatility:Cognitive system operation at scale demands megawatt-class data center power draws, making electricity price spikes a direct margin pressure on cloud-hosted deployments.
- EU AI Act regulatory friction:Ex-ante compliance requirements for automated decision systems create product roadmap divergence that fragments cross-border deployability for unified cognitive platforms.
Strategic Opportunities
- India PLI scheme incentives:Production-linked incentive structures for semiconductor and electronics manufacturing are drawing cognitive hardware assembly capacity away from traditional East Asian concentration points.
- Edge inference convergence:Neural processing unit integration with 5G base stations and industrial IoT gateways is opening low-latency cognitive applications outside centralized cloud infrastructure.
- Clinical decision support underpenetration:FDA software-as-a-medical-device guidance pathways remain sparsely utilized for diagnostic cognitive systems, creating first-mover positioning for compliant platform vendors.
Industry Challenges
- Model retraining talent scarcity:Continuous fine-tuning of production cognitive systems demands specialized machine learning operations engineers, a function where certified expertise pools remain thin.
- Legacy mainframe integration complexity:IBM Watson hybrid cloud deployments require bridging decades-old transaction processing architectures with containerized cognitive microservices, extending implementation timelines.
- NIST AI Risk Management Framework certification timelines:Dual compliance with voluntary federal guidance and sector-specific enforcement creates documentation burdens that delay product releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Systems Spending Market |
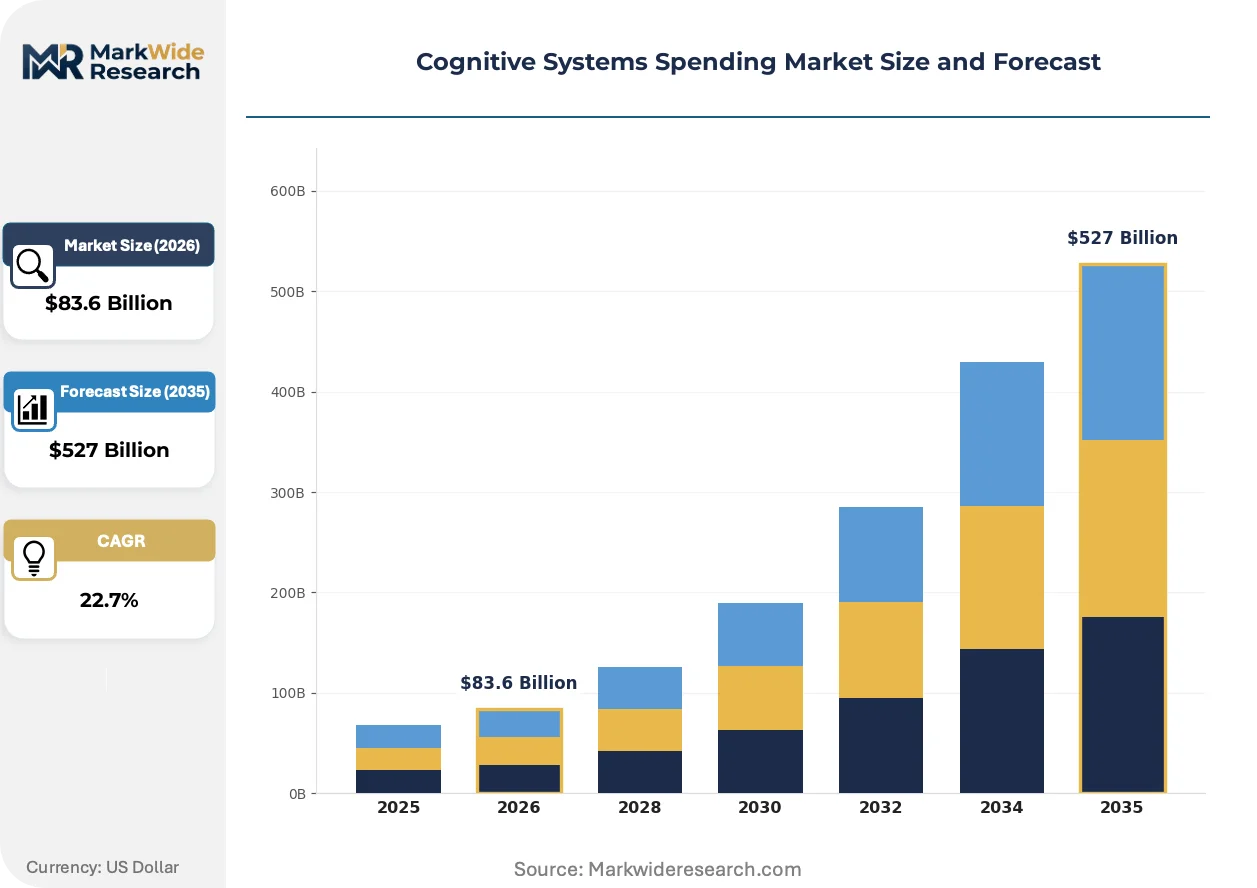
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $527 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Support End User: Healthcare, Finance, Retail, Manufacturing Deployment Model: On-Premises, Cloud, Hybrid, Edge Use Case: Data Analysis, Automation, Natural Language Processing, Decision Support |
| Companies Covered | IBM Corporation, Microsoft Corporation, Accenture plc, Intel Corporation, HP Inc., Wipro Limited, Oracle Corporation, SAP SE, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Systems Spending Market Emerging Trajectories
Neuromorphic silicon architectures and retrieval-augmented generation pipelines are compressing the boundary between training and inference workloads, forcing platform vendors to unify previously separate hardware roadmaps.
Neuromorphic computing chips that mimic biological neural network spiking patterns are absorbing edge-deployment budgets from conventional GPU inference accelerators. Automotive and industrial robotics buyers are piloting these devices for sub-milliwatt cognitive tasks. This absorption is compressing the addressable market for traditional neural processing units in battery-constrained applications.
The EU AI Act risk-tier classification system is mandating conformity assessments for high-risk cognitive applications in healthcare and finance. Product roadmaps must now incorporate ex-ante documentation and human-in-the-loop specifications before market access. German and French health technology vendors are responding by segregating EU-specific compliant architectures from lighter-weight global product variants.
Enterprise buyers are consolidating cognitive system procurement under centralized AI centers of excellence with direct cloud market platform negotiations. Systems integrators and value-added resellers are losing margin to self-service API consumption models. This concentration is most visible in United States financial services, where chief data officers now control foundation model access budgets previously dispersed across business line IT.
Cognitive Systems Spending Market Segmentation
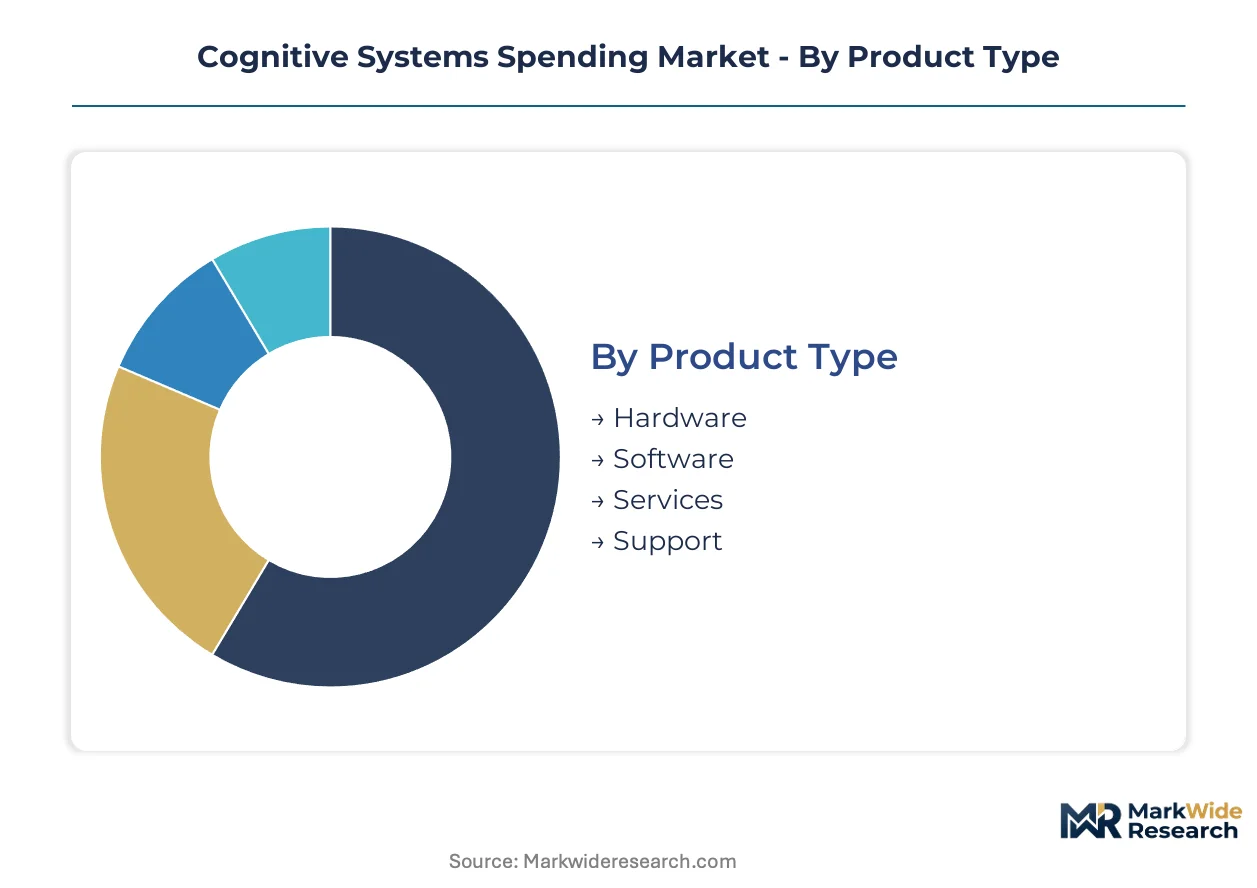
Cognitive systems spending fragments across four intersecting dimensions that determine procurement economics and margin capture. Product type governs capital intensity and recurring revenue mix. End user verticals impose divergent compliance architectures. Deployment models shift cost structures between fixed and variable. Use cases differentiate latency requirements and data throughput specifications.
Product Type:
Hardware commands premium pricing at the training frontier while services capture disproportionate margin from implementation complexity. Software and support occupy intermediate positions with diverging scalability profiles.
- Hardware:Dedicated AI accelerator clusters with GPU and neuromorphic architectures handle terabyte-scale unstructured data processing. United States defense modernization budgets are channeling procurement toward secure enclave deployments with classified-data handling capabilities. Supply concentration at TSMC's advanced nodes in Taiwan exposes buyers to single-source geographic risk.
- Services:Implementation partners deliver certified deployment architecture for EU AI Act conformity assessments in healthcare and finance. German and French health technology vendors are segregating EU-specific compliant architectures from lighter-weight global product variants. Talent scarcity for continuous model retraining extends engagement timelines and inflates hourly rates.
- Software:Cognitive platforms with perception, reasoning, and autonomous decision-making capabilities operate on structured and unstructured data streams.
- Support:Ongoing model retraining and system maintenance contracts with sub-second inference latency guarantees.
Mature deployment sits with support contracts attached to legacy mainframe integrations. Newer deployment is concentrated in hardware accelerator procurement for foundation model training clusters.
End User:
Healthcare and finance absorb the steepest compliance burdens while retail and manufacturing optimize for throughput economics. Each vertical imposes distinct latency, accuracy, and audit trail specifications.
- Healthcare:Clinical decision support systems with FDA software-as-a-medical-device guidance pathways remain sparsely utilized. United States healthcare providers are accelerating procurement of cognitive platforms for diagnostic and treatment recommendation workloads. EU AI Act high-risk classification mandates third-party conformity assessments and human-in-the-loop specifications.
- Finance:Real-time risk scoring and automated trading systems demand sub-second inference with full audit traceability. United States financial services chief data officers now control foundation model access budgets previously dispersed across business line IT. Dual compliance with NIST AI Risk Management Framework and sector-specific enforcement creates documentation burdens.
- Retail:Automated customer interaction and supply chain optimization with predictive demand forecasting.
- Manufacturing:Predictive maintenance and quality control with industrial IoT gateway integration.
Healthcare represents the most heavily regulated vertical with captive demand for certified architectures. Retail is expanding most quickly as self-service API consumption models displace systems integrator margins.
Deployment Model:
Cloud deployments are gaining share fastest as organizations abandon capital-intensive on-premises infrastructure. Edge and hybrid configurations serve latency-constrained and sovereignty-sensitive workloads respectively.
- Cloud:Consumption-based platforms with GPU-hour pricing models are compressing hardware refresh cycles. Enterprise buyers are consolidating procurement under centralized AI centers of excellence with direct cloud marketplace negotiations. Energy input cost volatility at megawatt-class data center power draws creates direct margin pressure.
- Edge:Neural processing unit integration with 5G base stations enables sub-milliwatt cognitive tasks for automotive and industrial robotics. India PLI scheme incentives are drawing cognitive hardware assembly capacity away from traditional East Asian concentration points. Neuromorphic silicon is absorbing budgets from conventional GPU inference accelerators in battery-constrained applications.
- On-Premises:Capital-intensive cognitive infrastructure with dedicated accelerator clusters for classified data handling.
- Hybrid:IBM Watson platform integration bridging decades-old transaction processing architectures with containerized cognitive microservices.
On-premises retains structural importance for classified-data workloads. Edge inference convergence is climbing the fastest as 5G infrastructure matures.
Use Case:
Automation and decision support concentrate enterprise spending while natural language processing and data analysis serve foundational enabling functions. Each use case imposes distinct throughput and accuracy specifications.
- Automation:Robotic process automation with cognitive document processing and workflow orchestration. Manufacturing predictive maintenance and retail supply chain optimization are pulling spending toward integrated platforms. Foundation model training clusters require dedicated hardware with terabyte-scale throughput.
- Decision Support:Clinical and financial recommendation engines with explainable output requirements. EU AI Act mandates human-in-the-loop specifications for high-risk automated decision systems. German health technology vendors are responding with segregated compliant architectures.
- Data Analysis:Pattern recognition and anomaly detection across structured and unstructured data lakes.
- Natural Language Processing:Retrieval-augmented generation pipelines compressing boundaries between training and inference workloads.
Data analysis represents the most mature use case with standardized tooling. Decision support is gaining share fastest as regulatory frameworks mature and clinical pathways open.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal procurement channels concentrate the heaviest cognitive systems investment, with defense modernization budgets and healthcare provider networks absorbing dedicated accelerator clusters and compliant platform architectures.
United States
Defense modernization budgets channel procurement toward secure enclave deployments with classified-data handling capabilities. NIST AI Risk Management Framework and FDA guidance on software as a medical device create dual compliance pathways for cognitive health platforms. Greater Boston and Pacific Northwest clusters host concentrated talent pools for machine learning operations engineering.
Germany
Automotive and industrial robotics buyers pilot neuromorphic silicon for sub-milliwatt cognitive tasks in battery-constrained applications. EU AI Act mandates third-party conformity assessments and human-in-the-loop specifications for high-risk automated decision systems. Bavaria anchors manufacturing-integrated cognitive deployments with predictive maintenance and quality control platforms.
China
MIIT industrial policy directives accelerate domestic AI accelerator fabrication capacity as hedge against TSMC supply concentration. Dual carbon goals and national semiconductor fund allocations shape cognitive hardware roadmap priorities. Yangtze River Delta clusters concentrate terabyte-scale foundation model training infrastructure.
India
PLI scheme incentives for semiconductor and electronics manufacturing draw cognitive hardware assembly capacity from traditional East Asian concentration points. CDSCO and central bank guidance on automated decision systems create compliance frameworks for financial and health applications. Karnataka and Telangana host expanding machine learning operations talent pools for continuous model retraining services.
United Kingdom
Financial services chief data officers consolidate foundation model access budgets under centralized AI centers of excellence with direct cloud marketplace negotiations. FCA guidance on algorithmic trading and automated decision-making creates sector-specific enforcement pathways. London anchors real-time risk scoring and automated trading system deployments with sub-second inference requirements.
Cognitive Systems Spending Market Vendor Landscape
Strategic partnerships dominate the current landscape as platform vendors align hardware roadmaps with cloud service providers and systems integrators. The vendor base organizes around three tiers: semiconductor fabricators with captive software ecosystems, IT services conglomerates with certified implementation capabilities, and enterprise software vendors with embedded cognitive modules. Two archetypes define competitive positioning: training-cluster specialists commanding premium GPU-hour pricing, and inference-optimization players targeting edge deployment economics. M&A activity concentrates on machine learning operations talent acquisition, while capacity expansion focuses on India-based assembly capacity under PLI incentives.
Within the semiconductor archetype, NVIDIA Corporation and Intel Corporation occupy positions at opposite ends of the workload spectrum, with the former anchoring high-performance training clusters and the latter targeting inference-optimized silicon with neural processing units. IBM Corporation represents the hybrid cloud integration tier, bridging legacy transaction processing architectures with containerized cognitive microservices through its Watson platform. Among IT services conglomerates, Accenture plc and Wipro Limited exemplify certified implementation partners delivering EU AI Act conformity assessments for healthcare and finance verticals.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Accenture plc |
| Intel Corporation |
| HP Inc. |
| Wipro Limited |
| Oracle Corporation |
| SAP SE |
| NVIDIA Corporation |
| Others |
Supply Flow & Price Mechanics
Machine learning operations engineer scarcity in Greater Boston and the Pacific Northwest widens pricing-tier spreads between certified implementation partners and commodity cloud resellers. Labor-cost differentials between these talent clusters and emerging Karnataka and Telangana pools compress margins for EU AI Act conformity assessments while inflating hourly rates for continuous model retraining services.
Pricing Analysis
Volume concentrates in GPU-hour cloud consumption while margin pools concentrate in certified implementation services. Three-tier pricing structure across premium accelerator clusters, standard inference-optimized silicon, and economy-grade edge neural processing units separates buyers by latency specification and compliance burden. Pricing pressure stems from TSMC advanced-node capacity constraints that extend training cluster lead times. Healthcare providers demonstrate lowest price sensitivity due to FDA software-as-a-medical-device pathway requirements, while retail automated customer interaction buyers migrate fastest to self-service API consumption.
Supply Chain Analysis
India PLI scheme local-content mandates are drawing cognitive hardware assembly capacity from traditional East Asian concentration points. Advanced node fabrication rests on Taiwan and South Korea, with packaging and testing operations expanding in Karnataka and Telangana under production-linked incentive structures. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized substrate materials. Single-source vulnerability at TSMC's Taiwan facilities exposes buyers to geographic concentration risk. Distribution runs through hyperscaler cloud marketplaces and certified systems integrator channels serving healthcare and finance verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cognitive systems spending is consolidating around accelerator supply scarcity and conformity assessment complexity, forcing undifferentiated cloud resellers toward acquisition or exit. EU AI Act compliance burdens and TSMC capacity constraints accelerate this rationalization.
For Market Incumbents: Lock in long-term TSMC allocation agreements to secure training cluster supply against emerging domestic Chinese accelerator competition. Expand India-based assembly capacity under PLI incentives to hedge geographic concentration. Deepen backward integration into neuromorphic silicon design to capture edge inference budgets from automotive and industrial robotics buyers.
For New Entrants and Emerging Players: Cloud service provider marketplaces offer the fastest path to foundation model access budgets now controlled by chief data officers in United States financial services. Target clinical decision support deployments where FDA software-as-a-medical-device guidance pathways remain sparsely utilized. Position as EU AI Act-certified implementation partners for German and French health technology vendors segregating compliant architectures.
For Investors and Strategic Acquirers: Re-rating potential sits with machine learning operations specialist firms given continuous model retraining talent scarcity. Long-term viability favors vertically integrated platforms bridging legacy mainframe architectures with containerized cognitive microservices. Watch for inflection where NIST AI Risk Management Framework certification timelines compress, signaling regulatory pathway maturation and accelerated healthcare procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator Supply Agreement | Long-term TSMC wafer commitments secure training cluster allocation against capacity constraints. |
| EU Conformity Certification | Third-party assessment capabilities unlock high-risk healthcare and finance deployment access. |
| India Assembly Expansion | PLI scheme incentives reduce geographic concentration risk for edge hardware production. |
| Neuromorphic Silicon Development | Sub-milliwatt architectures capture automotive and industrial robotics inference budgets. |
| Hybrid Cloud Integration | Watson-platform bridging extends legacy mainframe cognitive deployments for regulated verticals. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cognitive systems spending analysis. Primary interviews with machine learning operations engineers, chief data officers, hospital procurement committees, and certified systems integrators validated demand assumptions. FDA software-as-a-medical-device submissions, EU AI Act conformity assessment databases, and hyperscaler capex disclosures supplemented bottom-up triangulation against top-down macroeconomic indicators.
Granularity-level modeling deployed separate forecasts for hardware accelerator clusters, implementation services, cognitive platform software, and ongoing support contracts. End-use verticals, deployment models, and use case specifications segmented demand across healthcare, finance, retail, and manufacturing. CAGRs derived from regression analysis of procurement budget trajectories and regulatory compliance timeline assumptions. Foundation model training cluster requirements and edge inference convergence patterns informed hardware accelerator projections.
Caveats apply where TSMC capacity allocation disruptions or EU AI Act enforcement divergence could materially shift the outlook. Energy input cost volatility and machine learning operations talent scarcity represent additional revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market