

High-Volume RF Front-End Module Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
High-Volume RF Front-End Module Test Systems Market Insights
The EU F-Gas Regulation is repositioning capital equipment procurement criteria across European semiconductor test facilities, compelling suppliers to certify energy-efficient thermal management in RF test handlers. Advantest Corporation leverages its installed base in Japan and Taiwan to sustain service revenue streams around legacy tester platforms. Teradyne competes through parallel test site density in smartphone manufacturing lines, while Keysight Technologies differentiates via software-defined instrumentation that spans multiple wireless standards.
High-Volume RF Front-End Module Test Systems comprise automated measurement platforms that verify radio frequency performance of integrated front-end assemblies at throughput rates exceeding thousands of units per hour, typically operating across sub-6 GHz and mmWave bands with port counts ranging from 16 to 64 for parallel multi-DUT testing. These systems execute insertion loss, return loss, and harmonic distortion measurements to screen defective power amplifiers, filters, and switches before device integration. Signal analyzers and vector network analyzers dominate product type revenue due to their ubiquity in smartphone manufacturing lines, while spectrum analyzers capture margin pools in satellite communications applications where phase noise specifications tighten. CW testing technology anchors high-volume lines for its speed, though modulation analysis is gaining share in 5G infrastructure verification where envelope tracking and beamforming algorithms require complex waveform characterization.
The FCC in the United States governs electromagnetic emissions testing that RF front-end modules must pass before commercial deployment, while the EU AI Act and CE marking frameworks impose traceability requirements on automated test data in European manufacturing facilities. China's MIIT sets domestic 5G NR band allocations that dictate test system frequency coverage requirements for equipment sold into that market. Stakeholders must monitor spectrum reallocation proceedings across major economies, as new mid-band assignments will force test system refresh cycles regardless of existing capital depreciation schedules.
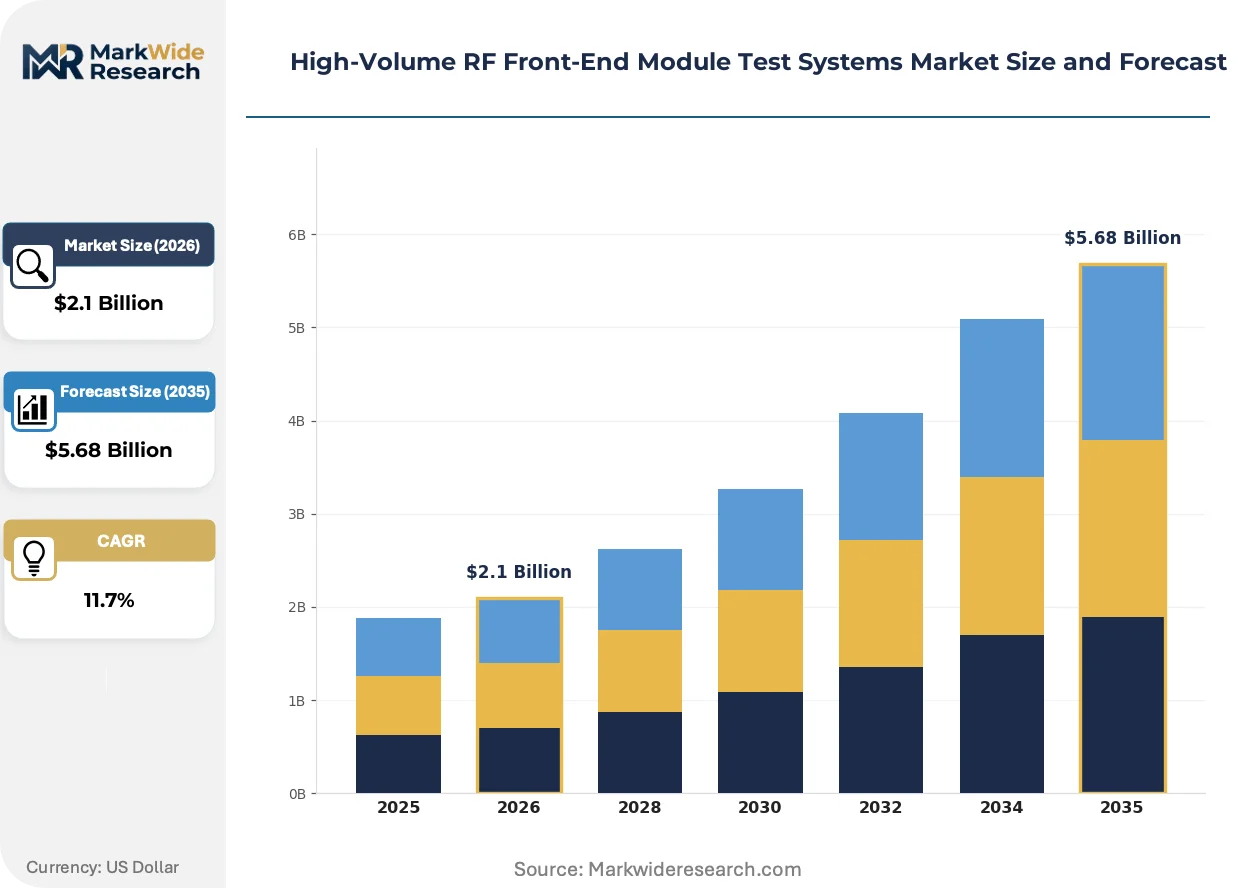
Market Dynamics
Smartphone manufacturers are expanding 5G mmWave test capacity while the EU F-Gas Regulation forces thermal management upgrades across European semiconductor fabrication facilities, creating simultaneous demand pull and compliance-driven equipment refresh cycles.
Growth Catalysts
- 5G mmWave Deployment:Smartphone OEMs in South Korea and Taiwan are commissioning parallel test sites for front-end modules operating at 28 GHz and 39 GHz bands. This drives demand for 64-port handlers capable of thousand-unit-per-hour throughput.
- EU F-Gas Regulation:The phasedown of conventional refrigerants in semiconductor cooling systems is elevating capital equipment procurement standards. Test handlers with energy-efficient thermal management now carry mandatory certification requirements for European facilities.
- Pyeongtaek Cluster Expansion:South Korea's concentrated semiconductor fabrication and adjacent test facility construction is creating localized demand spikes for high-volume RF test systems with sub-6 GHz and mmWave coverage.
Market Restraints
- Handler Cost Concentration:Precision thermal control systems and multi-port RF switching matrices dominate bill-of-materials costs. Input volatility in specialized ceramics and high-frequency connectors compresses system margins.
- Geographic Supply Concentration:Critical subcomponents including mmWave signal generators and vector network analyzer modules concentrate production in Japan and Taiwan. Single-source dependencies create vulnerability to regional disruption.
- Technical Bandwidth Limitation:Existing CW testing architectures face fundamental speed constraints when verifying complex 5G NR waveforms with envelope tracking and beamforming. Modulation analysis adds cycle time that conflicts with high-volume throughput targets.
Strategic Opportunities
- India Telecom Infrastructure:The country's 5G spectrum auctions and domestic manufacturing incentives under PLI schemes are creating greenfield demand for RF test capacity. Local assembly of front-end modules requires verification equipment with 3.5 GHz and 26 GHz coverage.
- Satellite Communications Integration:Low-earth orbit terminal manufacturers are adopting smartphone-derived front-end architectures. This opens adjacent demand for test systems with extended phase noise specifications and extended temperature range validation.
- Software-Defined Instrumentation Convergence:The merging of vector signal analysis with AI-driven defect classification is enabling single-platform coverage across multiple wireless standards. Test houses can consolidate equipment footprints while expanding protocol support.
Industry Challenges
- mmWave Calibration Expertise Gap:Technicians skilled in over-the-air test fixture design and thermal drift compensation for 28 GHz+ measurements remain scarce. Training pipelines have not kept pace with equipment deployment timelines.
- Legacy System Integration Friction:New software-defined analyzers must interface with existing handler mechanics and data management systems from prior capital generations. Protocol incompatibilities extend commissioning cycles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Volume RF Front-End Module Test Systems Market Trends and Innovations
Artificial intelligence is penetrating defect classification workflows while regulatory frameworks force thermal efficiency redesigns, and procurement patterns favor consolidated multi-standard platforms over single-protocol testers.
Machine learning-based anomaly detection is automating pass-fail decisions for harmonic distortion and intermodulation measurements. Contract manufacturers in Taiwan are deploying these systems at 24-hour cycle rates. The technology is automating operator-intensive screening steps that previously required manual waveform review.
The EU F-Gas Regulation is mandating refrigerant transitions in semiconductor process cooling. European test facilities must now specify handlers with closed-loop thermal management and certified low-global-warming-potential coolants. System suppliers are responding with redesigned thermal subsystems that maintain chamber stability across -40°C to 150°C test profiles.
Consolidated platform procurement is displacing single-standard tester acquisitions. Smartphone OEMs in South Korea now require equipment spanning 5G NR, Wi-Fi 6E, and UWB verification within unified software environments. This pattern is most visible in Pyeongtaek-adjacent test houses where floor space constraints and capital efficiency targets dominate vendor selection criteria.
High-Volume RF Front-End Module Test Systems Market Segmentation
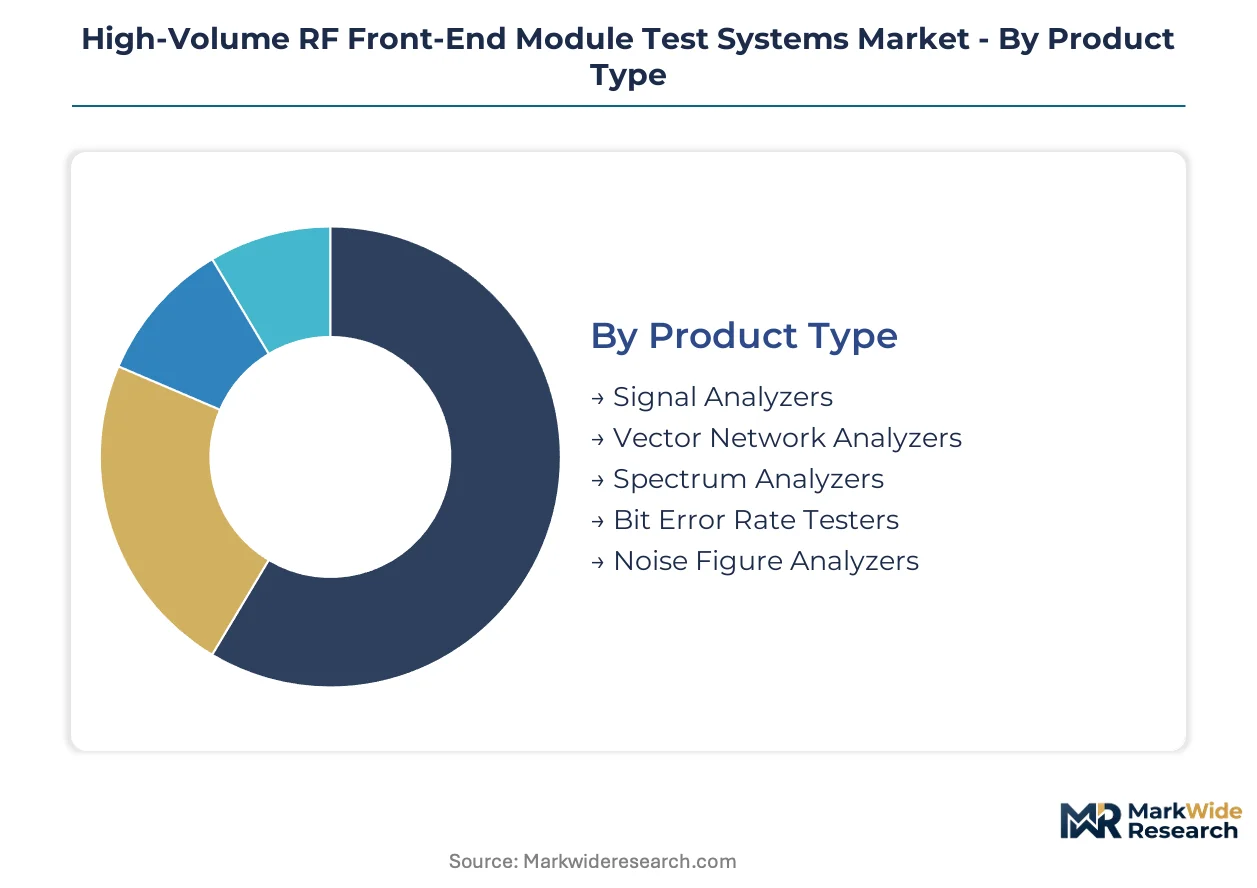
Segmentation in RF front-end test systems reveals how capital allocation priorities diverge across measurement architectures, verification protocols, and manufacturing tiers. Procurement patterns cluster around throughput requirements and frequency coverage rather than uniform platform specifications.
Product Type:
Capital intensity escalates with port density and frequency ceiling, creating tiered investment thresholds that separate high-volume smartphone lines from specialized satellite verification.
- Signal Analyzers:These platforms integrate vector signal analysis with multi-DUT parallel processing for sub-6 GHz and mmWave characterization. Demand concentrates in South Korean smartphone manufacturing lines where 64-port handlers verify power amplifier linearity at thousand-unit-per-hour rates. The FCC's electromagnetic emissions mandates drive refresh cycles regardless of depreciation schedules.
- Vector Network Analyzers:Precision S-parameter measurement engines dominate insertion loss and return loss verification for filter assemblies. Taiwan's contract manufacturers deploy these for 24-hour cycle production, though mmWave calibration expertise gaps extend commissioning timelines.
- Spectrum Analyzers:Phase noise specification tightening in satellite communications applications creates margin pools for specialized configurations.
- Bit Error Rate Testers:Digital modulation quality verification for 5G NR waveform conformance.
- Noise Figure Analyzers:Low-noise amplifier screening in receiver chain validation.
Most installed capacity flows through Signal Analyzers. Expansion is steepest in Vector Network Analyzers.
Technology:
Speed-versus-accuracy tradeoffs separate high-volume manufacturing from infrastructure verification, with cycle time penalties determining adoption thresholds.
- CW Testing:Continuous wave architectures anchor smartphone manufacturing lines with sub-millisecond measurement intervals. Pyeongtaek-adjacent test facilities specify CW-based systems for power amplifier gain compression screening at 28 GHz and 39 GHz bands.
- Modulation Analysis:Complex waveform characterization for envelope tracking and beamforming algorithms adds cycle time that conflicts with throughput targets. 5G infrastructure verification in India requires this capability for 3.5 GHz and 26 GHz band conformance.
- Time Domain Reflectometry:Impedance discontinuity detection in multi-layer RF substrates.
- Frequency Offset Measurement:Local oscillator stability verification in transceiver integration.
- Phase Noise Measurement:Critical for low-earth orbit terminal manufacturers adopting smartphone-derived architectures.
Procurement volume concentrates in CW Testing. Modulation Analysis is gaining share fastest where infrastructure validation requirements override speed constraints.
Application:
End-use diversification creates specification fragmentation, with smartphone manufacturing demanding highest throughput and satellite applications requiring extended environmental range.
- Smartphone Manufacturing:Parallel test site density requirements drive 64-port handler configurations with unified 5G NR, Wi-Fi 6E, and UWB coverage. South Korean OEMs commission these systems under floor space constraints that favor consolidated platforms.
- Satellite Communications:Low-earth orbit terminal production requires phase noise specifications and extended temperature range validation from -40°C to 150°C.
- IoT Device Verification:Narrowband IoT and LTE-M conformance testing for mass-market connectivity modules.
- 5G Infrastructure:Macro base station and small cell verification with beamforming algorithm validation.
- Wireless Networking:Wi-Fi 6E and emerging Wi-Fi 7 access point RF front-end screening.
Smartphone Manufacturing absorbs the majority of annual system shipments. Satellite Communications is expanding most quickly as terminal volumes scale.
End User:
Customer type determines procurement authority and technical specification influence, with component manufacturers driving initial requirements that cascade through contract manufacturing tiers.
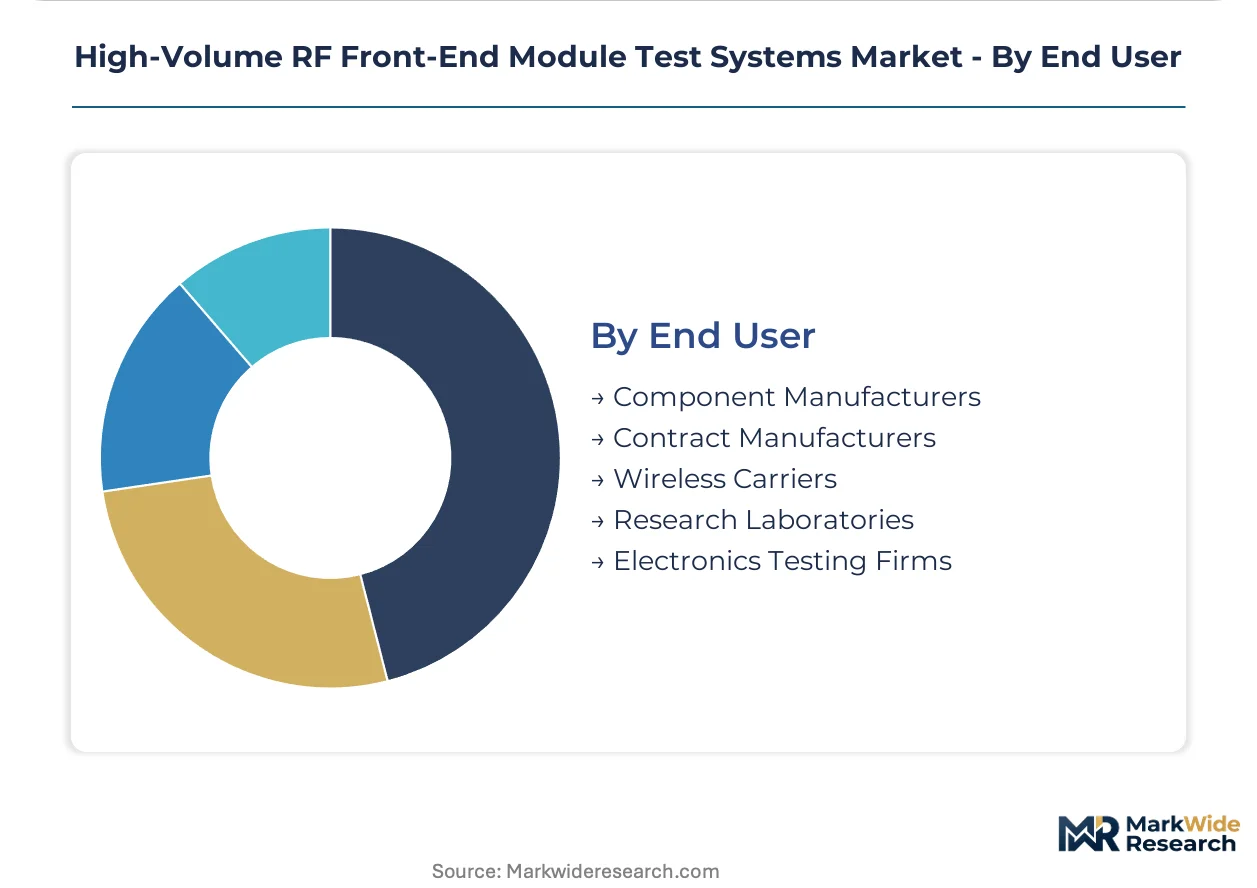
- Component Manufacturers:Power amplifier, filter, and switch suppliers specify test protocols that downstream partners must replicate. These firms maintain captive test capacity for design validation and failure analysis.
- Contract Manufacturers:Taiwan-based electronics manufacturing services providers operate 24-hour cycle facilities where AI-driven defect classification automates pass-fail decisions.
- Wireless Carriers:Network equipment acceptance testing and vendor qualification laboratories.
- Research Laboratories:Pre-commercial protocol development and emerging band characterization.
- Electronics Testing Firms:Third-party certification services for CE marking and FCC compliance.
Contract Manufacturers hold the largest installed base. Component Manufacturers are adding capacity fastest as vertical integration pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF front-end module test systems originated in Japanese precision instrumentation labs during the 1980s cellular expansion, then migrated to South Korean and Taiwanese manufacturing hubs as smartphone production scaled. Today demand concentrates in semiconductor fabrication corridors where 5G mmWave deployment and thermal compliance mandates intersect.
United States
The FCC governs electromagnetic emissions testing protocols that front-end modules must clear before commercial deployment. Domestic smartphone OEMs and defense contractors commission parallel test sites for 28 GHz and 39 GHz verification. Austin and Phoenix semiconductor corridors host concentrated handler deployment for sub-6 GHz and mmWave coverage.
South Korea
Pyeongtaek's semiconductor cluster anchors regional demand as Samsung and SK Hynix expand captive test capacity for 5G NR modules. The MFDS oversees equipment qualification standards that align with international thermal management certifications. Adjacent test facilities in Giheung and Icheon operate 64-port handlers at thousand-unit-per-hour throughput rates.
Taiwan
Contract manufacturers in Hsinchu Science Park and Taichung Precision Machinery Park deploy AI-driven defect classification systems for 24-hour cycle production. The National Communications Commission harmonizes 5G band allocations with MIIT specifications for equipment exported to mainland China. Tainan's emerging packaging hub is commissioning modulation analysis capability for infrastructure-grade verification.
China
MIIT sets domestic 5G NR band allocations at 3.5 GHz and 4.9 GHz that dictate test system frequency coverage requirements for locally sold equipment. Yangtze River Delta fabs in Shanghai and Suzhou are retrofitting thermal subsystems to meet EU-equivalent energy efficiency standards. Shenzhen's terminal assembly ecosystem drives demand for consolidated platforms spanning 5G, Wi-Fi 6E, and UWB.
Japan
METI coordinates industrial standards that influence thermal management specifications across Asian supply chains. Advantest Corporation leverages its installed base in Tokyo and Osaka to sustain service revenue around legacy tester platforms. Kyushu's silicon foundry corridor is adding mmWave calibration capacity as 28 GHz module volumes scale.
High-Volume RF Front-End Module Test Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the RF test systems landscape, creating a tiered structure where precision instrumentation heritage separates incumbent platforms from modular challengers. The market consolidates around three strategic archetypes: integrated measurement platform vendors, specialized handler mechanics suppliers, and software-defined instrumentation firms. Capacity expansion and strategic partnerships dominate competitive moves, with thermal subsystem redesigns and AI integration partnerships accelerating.
Among integrated platform vendors, Advantest Corporation and Teradyne occupy positions anchored in Asian manufacturing ecosystems, while Keysight Technologies exemplifies the software-defined instrumentation archetype with multi-standard coverage capabilities. Chroma ATE represents Taiwan-based test equipment specialization. These firms illustrate how geographic proximity to Pyeongtaek and Hsinchu clusters correlates with service revenue retention and handler deployment scale.
| Leading Market Players |
|---|
| Advantest Corporation |
| Teradyne |
| Keysight Technologies |
| Rohde & Schwarz |
| Cohu |
| Chroma ATE |
| National Instruments |
| FormFactor |
| Astronics |
| Others |
Pricing and Supply Chain Analysis
mmWave calibration expertise concentration in Japan and Taiwan creates labor-cost differentials that widen pricing-tier spreads between premium systems with certified thermal management and economy-grade handlers lacking EU F-Gas compliance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates equipment with 64-port parallel processing and AI-driven defect classification from base configurations. Price differentiation hinges on certification grade for EU F-Gas thermal compliance and volume scale of handler deployments. Pricing pressure stems from input volatility in specialized ceramics and high-frequency connectors compressing system margins. Contract manufacturers in Taiwan exhibit highest price sensitivity due to 24-hour cycle rate requirements, while component manufacturers prioritize specification adherence over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from South Korean smartphone manufacturers commissioning Pyeongtaek-adjacent test facilities. Production concentrates in Japan, Taiwan, and South Korea for critical subcomponents including mmWave signal generators and vector network analyzer modules. The supply chain draws from specialized ceramics, high-frequency connectors, and precision thermal control systems as core inputs. Single-source dependencies in Japanese and Taiwanese production create vulnerability to regional disruption. Distribution runs through captive procurement by component manufacturers and contract manufacturing services providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High-Volume RF Front-End Module Test Systems Market represents a late-cycle quality story as 5G mmWave deployment shifts procurement toward premium specifications with certified thermal management and multi-standard coverage.
For Market Incumbents: To counter emerging software-defined instrumentation challengers, deepen captive service revenue streams around legacy tester platforms in Japan and Taiwan while accelerating AI integration partnerships for defect classification automation. Add mmWave calibration capacity in Kyushu to address technician scarcity extending commissioning timelines.
For New Entrants and Emerging Players: Cloud-based test data analytics platforms offer lower customer acquisition costs for penetrating India's greenfield 5G infrastructure verification market under PLI scheme incentives. Target satellite communications terminal manufacturers adopting smartphone-derived front-end architectures with extended phase noise specifications as the most penetrable adjacent segment.
For Investors and Strategic Acquirers: Semiconductor test equipment specialists are the most active acquirer in this space, seeking handler mechanics suppliers with EU F-Gas-certified thermal subsystems. Long-term viability centers on consolidation plays for multi-standard platform capabilities. Monitor spectrum reallocation proceedings across major economies as the inflection indicator forcing test system refresh cycles independent of capital depreciation schedules.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Subsystem Redesign | EU F-Gas Regulation mandates closed-loop thermal management with low-global-warming-potential coolants for European facility certification. |
| AI Integration Partnership | Machine learning-based anomaly detection automates pass-fail decisions for harmonic distortion screening at Taiwan contract manufacturers. |
| mmWave Calibration Capacity Expansion | Kyushu's silicon foundry corridor addresses technician scarcity for 28 GHz+ over-the-air test fixture design and thermal drift compensation. |
| Multi-Standard Platform Convergence | Unified software environments spanning 5G NR, Wi-Fi 6E, and UWB respond to South Korean OEM floor space constraints in Pyeongtaek-adjacent test houses. |
| India Market Entry | Domestic manufacturing incentives under PLI schemes create greenfield demand for RF test capacity with 3.5 GHz and 26 GHz coverage. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with test equipment procurement managers, semiconductor fabrication facility engineers, RF front-end module design validation leads, and contract manufacturing operations directors with secondary validation from SEC filings, customs and trade data, FCC electromagnetic emissions regulatory filings, and EIA energy consumption disclosures. Bottom-up equipment shipment tallies and top-down semiconductor capital expenditure analysis provide triangulation.
Granularity-level modeling disaggregates volume and value outputs by product type, technology protocol, application end-use, and customer tier across the projection horizon. CAGRs derive from equipment replacement cycle analysis, spectrum allocation timelines, and thermal regulation compliance deadlines. Forecast inputs include 5G mmWave deployment trajectories in South Korea and Taiwan, EU F-Gas refrigerant phase-down schedules, and India PLI scheme manufacturing incentive uptake rates.
The model assumes a particular technology adoption path; alternative pathways for modulation analysis versus CW testing architectures would alter the outlook. Forecasts reflect documented assumptions regarding spectrum reallocation timing, thermal regulation enforcement consistency, and technician training pipeline scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.