
 Industrial Exhaust System Market | 2026-2036
Industrial Exhaust System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Exhaust System Market Foresight
The gap between premium engineered exhaust systems and commodity ducting is realigning around filtration efficiency and thermal tolerance specifications. Cummins Inc. leverages its engine-integration expertise to dominate exhaust-aftertreatment bundling for heavy manufacturing clients. Donaldson Company Inc. sustains leadership in high-performance filtration media through captive R&D facilities. Tenneco Inc. competes across multiple technology tiers with manufacturing scale that spans North American and European production bases.
Industrial exhaust systems channel contaminated air away from production zones through engineered ductwork, filtration units, and emission-control devices, typically constructed from corrosion-resistant alloys or coated carbon steel rated for continuous thermal cycling above 400°C. Their primary purpose is to capture particulates, neutralize acid gases, and maintain occupational exposure limits within enclosed industrial environments. Ducted configurations anchor the installed base in legacy power plants and heavy manufacturing halls where centralized air handling remains economically justified, while thermal oxidation technology leads margin pools by commanding premium pricing for volatile organic compound destruction in pharmaceutical and chemical processing facilities. Chemical filtration is displacing mechanical-only approaches in semiconductor and battery manufacturing cleanrooms where molecular contamination control has become non-negotiable.
EPA emission standards under the Clean Air Act, EU Green Deal industrial decarbonization benchmarks, and China's MEE air quality enforcement actions are collectively tightening allowable discharge thresholds and accelerating replacement cycles for outdated exhaust infrastructure. OSHA workplace exposure limits and REACH chemical authorization requirements in Europe further constrain material choices and filter media compositions available to system designers. Stakeholders must monitor how divergent regional compliance timelines reshape procurement priorities and supplier qualification criteria across multinational manufacturing footprints.
Market Dynamics
Steel mills and chemical processing facilities in Germany, Japan, and the United States are replacing legacy ventilation infrastructure to comply with tightened EPA, MEE, and EU Green Deal emission ceilings. This wave of regulatory-driven replacement is compressing procurement cycles and elevating filtration efficiency specifications above thermal tolerance as the primary selection criterion.
Growth Catalysts
- EPA Clean Air Act enforcement:Steel mills in the United States face accelerated replacement deadlines for electrostatic precipitators that fail to meet particulate matter thresholds, forcing capital deployment into baghouse and wet scrubber upgrades.
- Semiconductor cleanroom expansion:Chemical filtration systems are displacing mechanical-only approaches in Taiwan and South Korea fabrication facilities where molecular contamination control has become non-negotiable for advanced node production.
- East Asian manufacturing density:Industrial corridors across China's Yangtze River Delta and Japan's Kansai region concentrate demand where regulatory enforcement and production volume have tightened in parallel.
Market Restraints
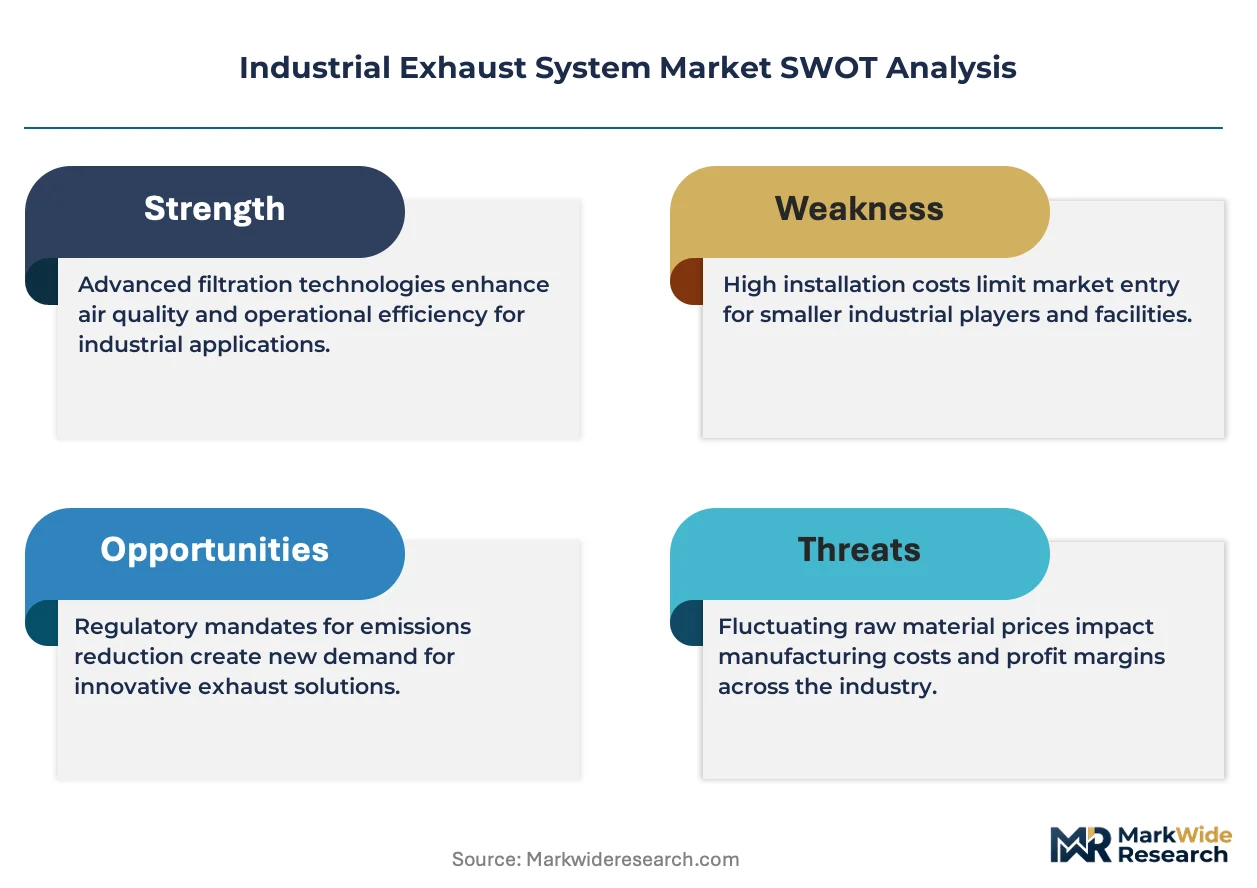
- Nickel and chromium price volatility:Corrosion-resistant alloy feedstock costs fluctuate with stainless steel market cycles, compressing margins for ducting fabricators locked into fixed-price maintenance contracts.
- European supplier concentration:High-performance filtration media production clusters in Germany and Switzerland create single-source dependencies for system integrators serving pharmaceutical cleanrooms.
- Electrochemical scrubbing limitations:Acid gas neutralization efficiency drops below acceptable thresholds for fluorinated compound streams in battery manufacturing exhaust, forcing hybrid system architectures that raise capital intensity.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Greenfield manufacturing parks in Gujarat and Maharashtra require turnkey exhaust infrastructure, creating first-mover advantages for integrators offering bundled filtration and thermal oxidation packages.
- Thermal oxidation-catalytic reduction convergence:Combined VOC destruction and NOx abatement systems command premium positioning in pharmaceutical batch processing where space constraints prohibit separate unit operations.
- EU Green Deal industrial decarbonization benchmarks:Carbon border adjustment mechanisms incentivize European process industries to upgrade exhaust heat recovery systems, opening retrofit markets for regenerative thermal oxidizer suppliers.
Industry Challenges
- Welding certification bottlenecks:ASME Section IX qualified welders for high-alloy duct fabrication face acute shortages in North American fabrication yards, extending delivery timelines for custom exhaust train projects.
- Legacy DCS integration complexity:New emission monitoring systems must interface with decades-old distributed control architectures in petrochemical complexes, requiring costly protocol translation and signal conditioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Exhaust System Market |
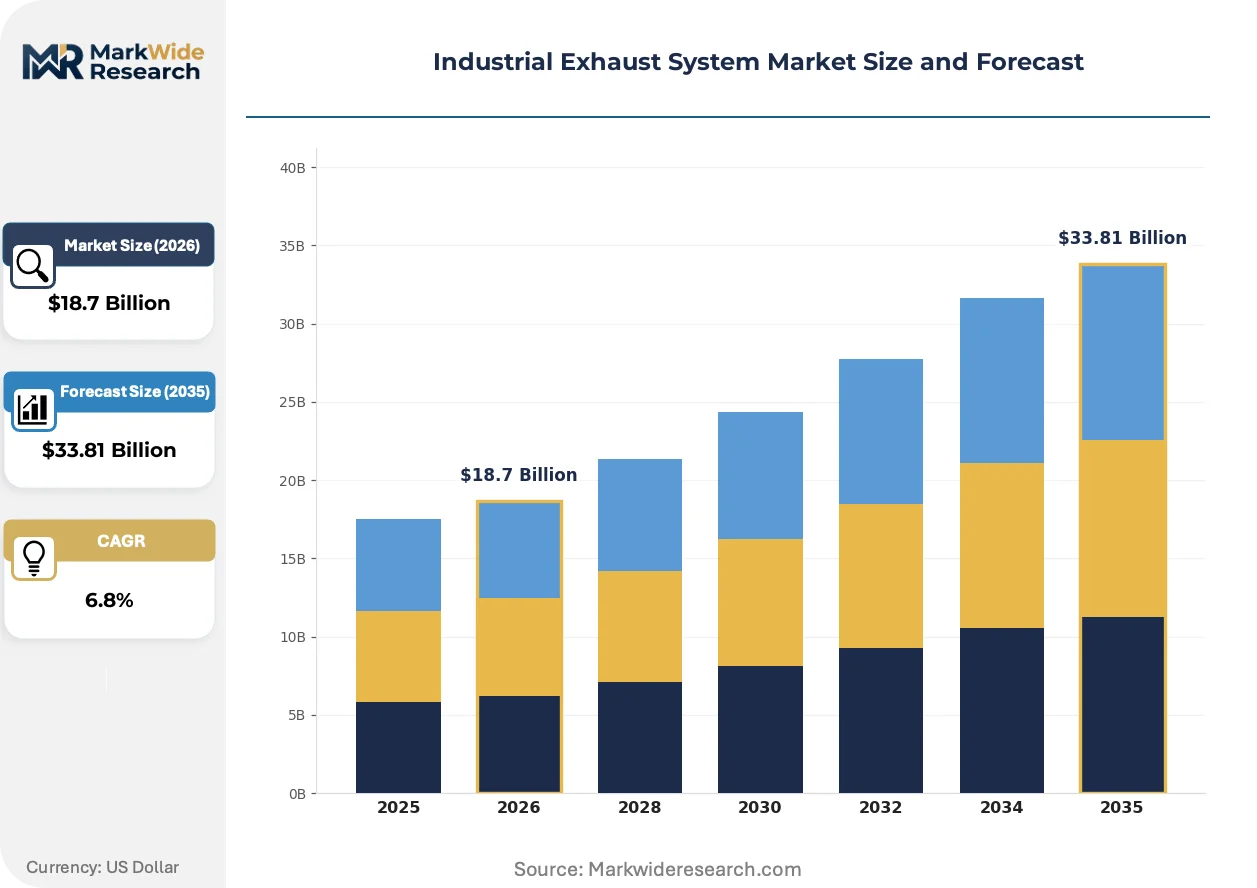
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
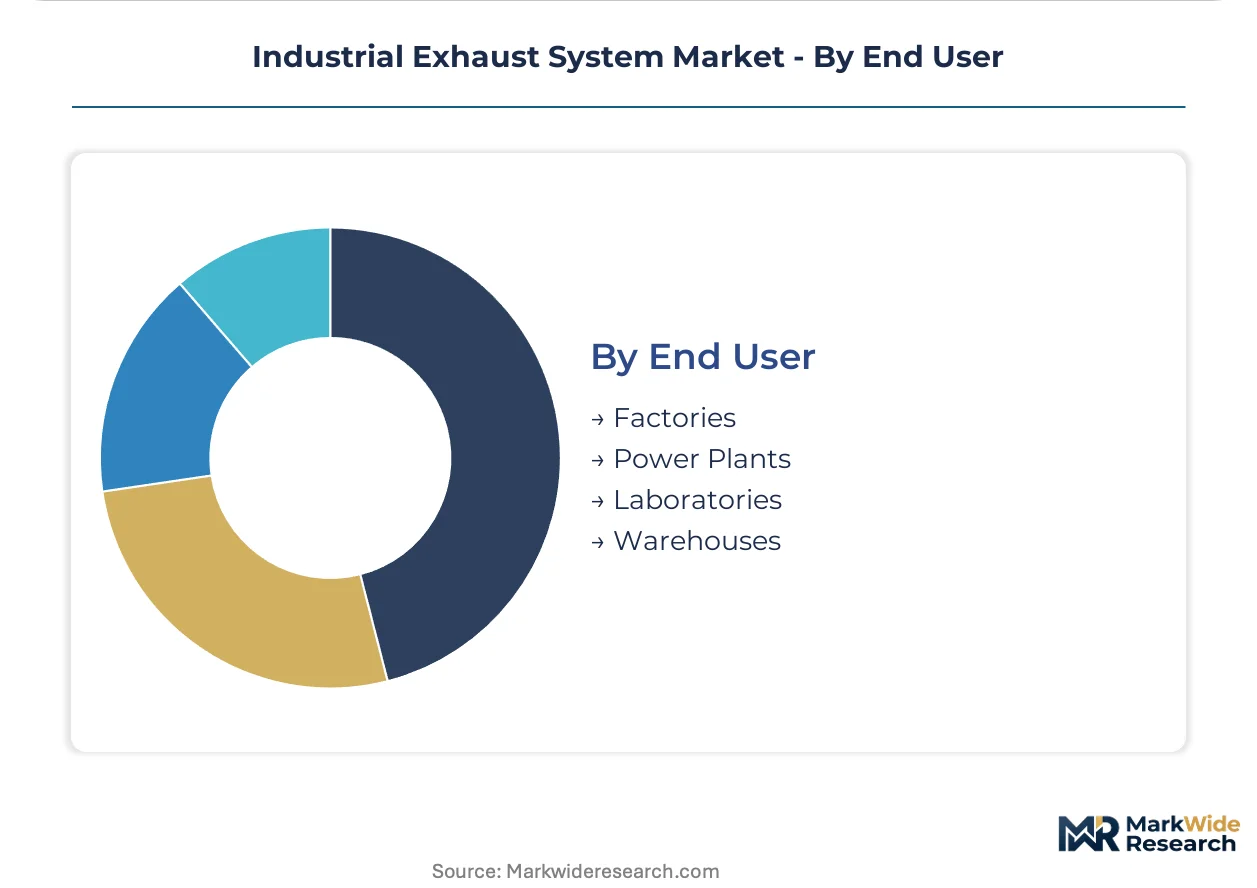
| Segmentation | Product Type: Ducted, Ductless, Packaged, Variable Air Volume Technology: Mechanical Filtration, Chemical Filtration, Electrostatic Precipitation, Thermal Oxidation Application: Manufacturing, Automotive, Pharmaceutical, Marine End User: Factories, Power Plants, Laboratories, Warehouses |
| Companies Covered | Cummins Inc., Caterpillar Inc., Perkins Engines Company Limited, Donaldson Company Inc., Johnson Matthey PLC, Tenneco Inc., Forvia, Eberspächer Group, Futaba Industrial Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Exhaust System Market Shifts & Advancements
Membrane-based gas separation and intelligent pressure-balancing controls are rewriting how exhaust systems manage energy recovery and contaminant capture. These advances compress operating costs while expanding the addressable market beyond traditional heavy manufacturing into precision process industries.
Ceramic membrane filtration is rewriting particulate capture economics in high-temperature exhaust streams above 600°C. Steel mini-mills in Japan and electric arc furnace operators in the United States are piloting silicon carbide membrane modules that eliminate cooling stages required by baghouse systems. This technology is rewriting capital deployment patterns by reducing footprint requirements and enabling heat recovery integration that was previously uneconomical.
REACH chemical authorization requirements in Europe are restricting filter media compositions containing per- and polyfluoroalkyl substances. Manufacturers of PTFE membrane media face reformulation deadlines that disrupt supply chains for semiconductor and pharmaceutical cleanroom applications. German process engineers are responding fastest, accelerating qualification of alternative fluorine-free surface treatments that maintain oleophobic performance without restricted substance content.
Lifecycle service contracts are displacing equipment-only procurement in chemical processing and food manufacturing verticals. Buyers in the Netherlands and Belgium now prioritize ten-year total cost of ownership guarantees over upfront capital expenditure minimization, forcing original equipment manufacturers to retain operational risk for filtration media replacement and energy performance. This pattern is most visible in agrochemical formulation plants where unplanned downtime costs exceed equipment depreciation by an order of magnitude.
Industrial Exhaust System Market Segmentation
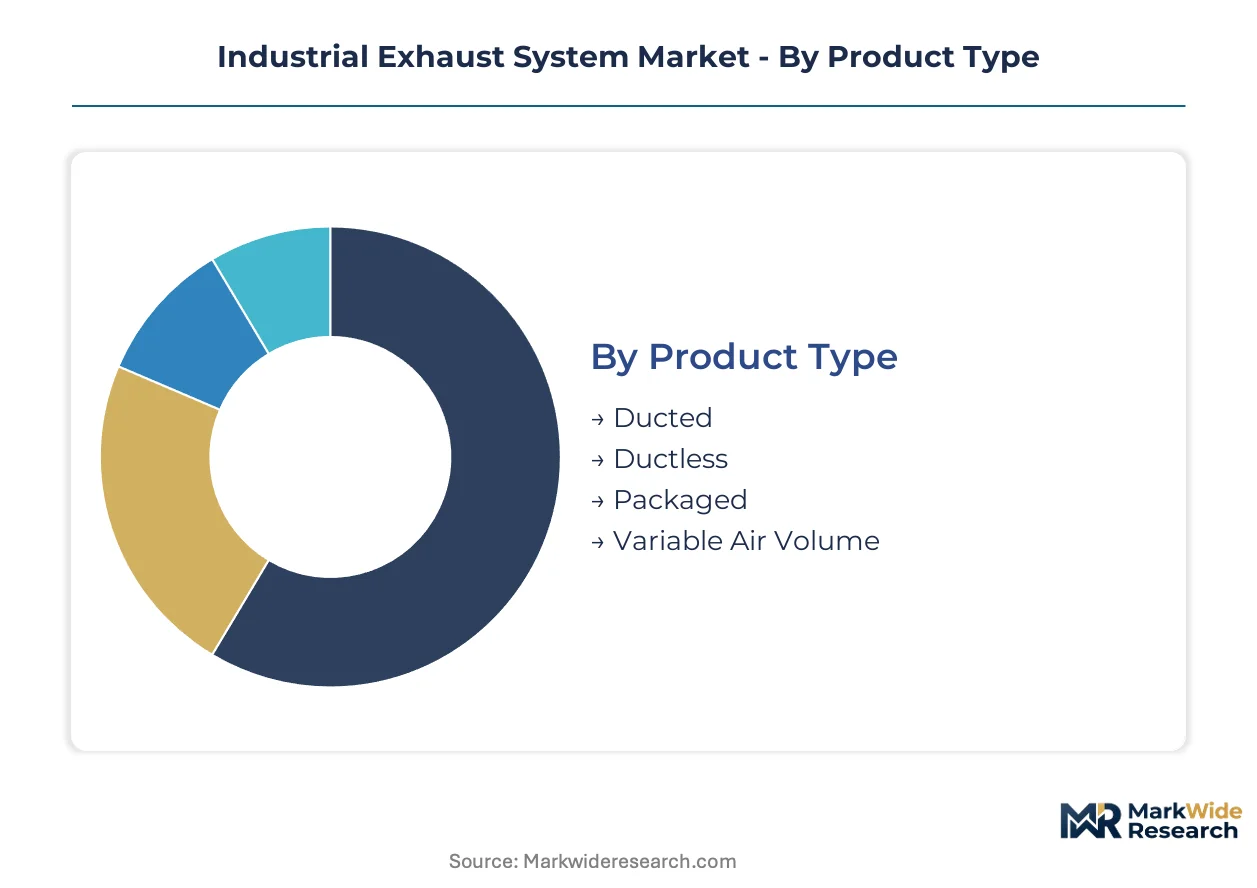
Exhaust system procurement divides sharply between legacy infrastructure replacement and greenfield precision manufacturing installations. Buyers select configurations based on thermal tolerance requirements, contamination control stringency, and integration complexity with existing building management systems.
Product Type:
Cost tier separates commodity ductwork from engineered systems with integrated controls and heat recovery.
- Ducted:Centralized ductwork networks constructed from coated carbon steel or corrosion-resistant alloys rated for continuous thermal cycling above 400°C. Steel mills in Germany and Japan dominate replacement demand as EPA and EU Green Deal emission ceilings force upgrades of legacy ventilation infrastructure.
- Ductless:Self-contained filtration units with localized capture arms or hoods, eliminating extensive duct runs. Pharmaceutical laboratories in Switzerland and Belgium prioritize these configurations where flexible equipment layouts and frequent process reconfiguration make fixed ductwork economically unjustified.
- Packaged:Factory-integrated exhaust trains combining filtration, fan assemblies, and emission monitoring in skid-mounted enclosures. Food manufacturing facilities in the Netherlands favor turnkey packages that compress installation timelines and reduce field welding requirements.
- Variable Air Volume:Demand-controlled systems modulating fan speed and damper positions based on real-time contaminant detection. Semiconductor cleanrooms in Taiwan and South Korea require these systems where molecular contamination control demands precise airflow balancing across production zones.
Ducted configurations lead volumes today; Variable Air Volume systems are gaining share fastest.
Technology:
Application severity determines whether mechanical capture suffices or chemical neutralization becomes mandatory.
- Mechanical Filtration:Baghouse and cartridge systems capturing particulates through fabric or pleated media. Legacy power plants in the United States deploy these for baseline particulate matter compliance under Clean Air Act enforcement.
- Chemical Filtration:Activated carbon and impregnated media beds adsorbing acid gases and volatile organic compounds. Battery manufacturing exhaust streams in China's Yangtze River Delta require hybrid chemical-mechanical architectures where fluorinated compound neutralization exceeds pure mechanical capability.
- Electrostatic Precipitation:Ionization-based particulate collection without filter media replacement. Steel mini-mills in Japan pilot ceramic membrane alternatives as REACH chemical authorization restrictions disrupt traditional PTFE membrane supply chains.
- Thermal Oxidation:High-temperature VOC destruction above 750°C with optional regenerative heat recovery. Pharmaceutical batch processing in Germany commands premium pricing for combined thermal oxidation-catalytic reduction systems where space constraints prohibit separate unit operations.
Mechanical Filtration retains the largest installed base; Thermal Oxidation commands the steepest expansion trajectory in high-margin pharmaceutical applications.
Application:
Regulatory enforcement intensity varies dramatically across end-use verticals, reshaping specification priorities.
- Manufacturing:Heavy industrial halls producing metals, chemicals, and processed materials. East Asian manufacturing corridors concentrate procurement where industrial density and MEE air quality enforcement have tightened in parallel.
- Automotive:Paint booths, welding stations, and battery assembly lines requiring combustible dust and solvent vapor control. Electric vehicle battery plants in the United States face accelerated EPA deadlines for electrostatic precipitator replacement.
- Pharmaceutical:Sterile formulation suites and API manufacturing suites demanding molecular-level contamination control. Cleanroom expansions in Taiwan and South Korea displace mechanical-only approaches with chemical filtration for advanced node semiconductor production.
- Marine:Engine room ventilation and cargo hold exhaust for commercial shipping. IMO emission regulations drive scrubber retrofits in European port clusters.
Manufacturing anchors current demand volumes; Pharmaceutical applications show the most rapid specification escalation.
End User:
Operational risk tolerance separates buyers who prioritize capital minimization from those accepting lifecycle service contracts.
- Factories:Discrete and process manufacturing facilities with continuous production schedules. Agrochemical formulation plants in Belgium now prioritize ten-year total cost of ownership guarantees over upfront capital expenditure minimization.
- Power Plants:Utility and captive generation facilities with decades-old distributed control architectures. New emission monitoring systems in United States petrochemical complexes require costly protocol translation for legacy DCS integration.
- Laboratories:R&D and quality control facilities with variable fume hood utilization patterns. Research institutes in Switzerland specify intelligent pressure-balancing controls that modulate exhaust based on sash position detection.
- Warehouses:Logistics and distribution centers with battery charging infrastructure and material handling equipment exhaust. E-commerce fulfillment centers in India's Gujarat and Maharashtra greenfield parks require turnkey exhaust infrastructure under PLI scheme incentives.
Factories represent the dominant procurement volume; Laboratories are shifting fastest toward outcome-based service contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welders certified to ASME Section IX standards concentrate in fabrication yards across Germany, Japan, and the United States, anchoring the geographic distribution of high-alloy exhaust system production.
United States
Steel mills in the Great Lakes region and electric vehicle battery plants in the Southeast drive replacement demand. EPA Clean Air Act enforcement accelerates electrostatic precipitator upgrades with compressed deadlines. Pittsburgh and Detroit fabrication clusters specialize in baghouse and wet scrubber installations for heavy manufacturing clients.
Germany
Pharmaceutical batch processing facilities and specialty chemical plants require combined thermal oxidation-catalytic reduction systems. EU Green Deal industrial decarbonization benchmarks tighten allowable discharge thresholds. The Ruhr industrial corridor and Bavarian chemical parks concentrate procurement for regenerative thermal oxidizer retrofits with heat recovery integration.
Japan
Steel mini-mills and semiconductor fabrication facilities pilot ceramic membrane filtration above 600°C. METI efficiency standards and carbon neutrality targets reshape capital deployment patterns. The Kansai region and Nagoya industrial zone lead adoption of silicon carbide membrane modules that eliminate cooling stages.
China
Battery manufacturing exhaust streams in the Yangtze River Delta require hybrid chemical-mechanical architectures for fluorinated compound neutralization. MEE air quality enforcement actions tighten parallel with industrial density expansion. Suzhou and Ningbo cleanroom clusters displace mechanical-only approaches with molecular contamination control systems.
India
Greenfield manufacturing parks in Gujarat and Maharashtra under the PLI scheme for specialty chemicals require turnkey exhaust infrastructure. Central pollution control mandates and state-level environmental clearances compress procurement timelines. The Delhi-Mumbai Industrial Corridor attracts first-mover integrators offering bundled filtration and thermal oxidation packages.
Industrial Exhaust System Market Competitive Landscape
Top-tier vendors anchor premium engineered systems with integrated controls and heat recovery, while mid-tier fabricators compete on ductwork commoditization and regional maintenance contracts. The market structures around filtration efficiency specialization, thermal tolerance engineering, and lifecycle service bundling. Three archetypes dominate: engine-integration specialists leveraging powertrain expertise, filtration media developers with captive R&D facilities, and diversified industrial conglomerates spanning multiple technology tiers. Consolidation pressure manifests through strategic partnerships for ceramic membrane qualification and geographic expansion into India's PLI-driven greenfield parks.
Among US-based industrial conglomerates, Cummins Inc. and Caterpillar Inc. exemplify engine-integration specialists that extend powertrain expertise into exhaust-aftertreatment bundling. Donaldson Company Inc. and Tenneco Inc. represent the filtration-focused archetype, with the former anchoring high-performance media development and the latter spanning manufacturing scale across North American and European production bases. Johnson Matthey PLC occupies a position within the catalytic systems tier, while Eberspächer Group and Forvia sit within European-based emission control integration. These named entities serve as reference points for competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Cummins Inc. |
| Caterpillar Inc. |
| Perkins Engines Company Limited |
| Donaldson Company Inc. |
| Johnson Matthey PLC |
| Tenneco Inc. |
| Forvia |
| Eberspächer Group |
| Futaba Industrial Co. Ltd. |
| Others |
Supply & Pricing Matrix
EU Green Deal industrial decarbonization benchmarks gate qualified supply and premium-tier pricing access. Buyers seeking regenerative thermal oxidizer retrofits with heat recovery integration must demonstrate compliance with carbon border adjustment mechanisms to access German and Swiss filtration media suppliers.
Pricing Analysis
The bundled-vs-unbundled service split separates lifecycle service contracts from equipment-only procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by filtration efficiency certification and thermal tolerance ratings. Cost compression in commodity ducting is intensifying because fixed-price maintenance contracts expose fabricators to nickel and chromium price volatility. Agrochemical formulation plants in Belgium represent the least price-sensitive buyers, prioritizing ten-year total cost of ownership guarantees over upfront capital expenditure.
Supply Chain Analysis
Workforce-availability constraints in Germany, Japan, and the United States concentrate high-alloy fabrication capacity. Corrosion-resistant alloy feedstock, PTFE membrane media, and ceramic membrane modules anchor component dependencies. Single-source vulnerability runs through German and Swiss high-performance filtration media production clusters. Distribution runs through system integrators serving multinational manufacturing footprints with bundled installation and commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play. India's PLI scheme for specialty chemicals offers cost advantages against EU Green Deal compliance costs for European process industries seeking greenfield expansion.
For Market Incumbents: Lock in welding certification pipelines to defend against ASME Section IX qualified welder shortages that extend delivery timelines. Deepen backward integration into ceramic membrane R&D to offset REACH chemical authorization disruptions affecting PTFE membrane supply chains. Capacity expansion in India's Gujarat and Maharashtra manufacturing corridors captures PLI-driven procurement acceleration. For New Entrants and Emerging Players: Capture first-mover positioning in India's greenfield manufacturing parks by offering bundled filtration and thermal oxidation packages. Semiconductor cleanroom expansion in Taiwan and South Korea presents the most penetrable application segment. Partner with local engineering procurement contractors to compress installation timelines and reduce field welding dependencies. For Investors and Strategic Acquirers: Roll-up economics work for regional ductwork fabricators with captive maintenance contract portfolios because lifecycle service bundling displaces equipment-only procurement in chemical processing and food manufacturing verticals. Target mid-tier integrators with established relationships in pharmaceutical cleanrooms. Watch for ceramic membrane qualification milestones as inflection indicators for technology substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Membrane Production | Captive silicon carbide module supply insulates against REACH restrictions disrupting PTFE media. |
| Long-term Service Contract Expansion | Ten-year total cost of ownership guarantees lock in agrochemical formulation plant relationships in Belgium. |
| Geographic Manufacturing Footprint Expansion | Gujarat and Maharashtra facilities capture PLI scheme incentives for specialty chemicals greenfield parks. |
| Joint Venture for Hybrid System Architectures | Combined thermal oxidation-catalytic reduction partnerships address pharmaceutical batch processing space constraints. |
| Technology Licensing for Intelligent Pressure-Balancing | Demand-controlled ventilation IP monetization targets semiconductor cleanrooms in Taiwan and South Korea. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors informed operational realities. Secondary validation drew from EPA enforcement databases, EU ETS transaction registries, customs trade data for corrosion-resistant alloys, and SEC filings of listed industrial conglomerates. Bottom-up installation tracking and top-down emissions compliance spending estimates were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to regulatory enforcement cycles and capital replacement waves. Segmentation modeling incorporated product type, technology tier, application severity, and end-user risk tolerance dimensions. CAGRs were derived from regression analysis against industrial production indices and emissions compliance expenditure patterns. Forecast inputs included MEE enforcement intensity trajectories and EU carbon border adjustment mechanism phase-in schedules.
Regulatory timeline slippage, feedstock cost volatility, and technology substitution acceleration are the dominant revision risks. Forecasts reflect documented assumptions about enforcement consistency and certification standard harmonization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Blowers Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market