
 HVAC Chillers Market | 2026-2036
HVAC Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Chillers Market Outlook
Premium chiller performance is decoupling from commodity specifications as efficiency thresholds tighten and lifecycle cost analysis replaces upfront price evaluation. Carrier Global Corporation leverages its compressor manufacturing depth to control component quality and delivery timelines. Daikin Industries, Ltd. anchors its position through refrigerant transition leadership and heat recovery integration. Trane Technologies plc differentiates via building automation system compatibility and predictive maintenance platforms.
HVAC chillers are vapor-compression or absorption-based refrigeration systems that produce chilled water for centralized cooling, typically operating with leaving water temperatures between 40°F and 45°F and capacities ranging from 20 tons to over 10,000 tons for industrial process loads. Centrifugal chillers dominate the large-capacity segment where efficiency ratings and part-load performance determine specification outcomes. Screw chillers occupy the mid-range commercial and industrial space where operational flexibility across variable loads creates margin pools. Absorption technology competes in district cooling networks and waste-heat recovery applications where thermal energy displacement reduces electrical demand charges.
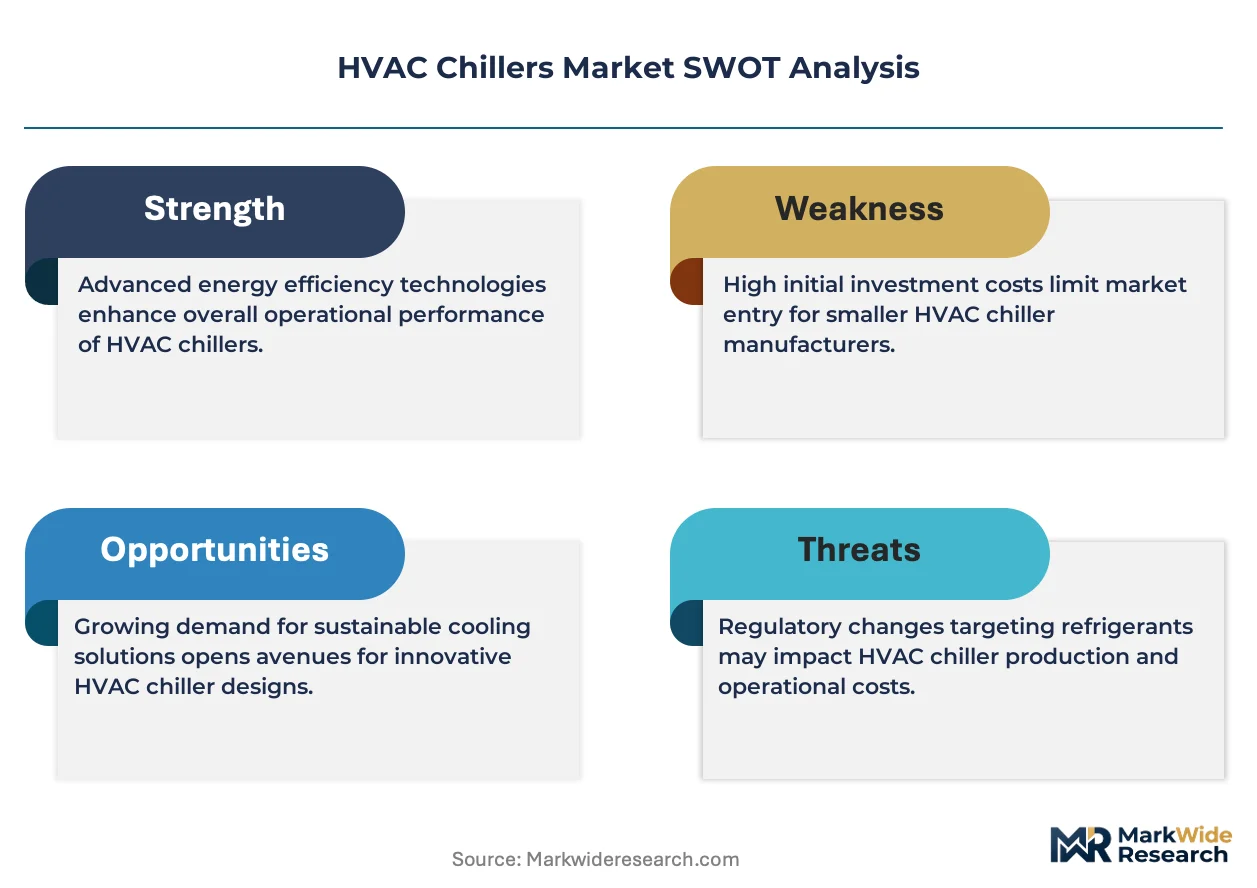
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that reset chiller performance baselines every five years, while the EPA's SNAP program governs refrigerant phase-down timelines that dictate equipment redesign cycles. ASHRAE Standard 90.1 and the International Energy Conservation Code progressively tighten Integrated Part Load Value requirements, forcing manufacturers to optimize at part-load conditions rather than design-point efficiency. Stakeholders must monitor refrigerant supply chain constraints and regional utility incentive structures to align procurement timing with total cost optimization.
Market Dynamics
The US Department of Energy's five-year efficiency standard resets under 10 CFR 431 are compressing equipment replacement cycles and forcing manufacturers to optimize part-load performance rather than design-point ratings. This regulatory cadence now dictates R&D allocation and factory retooling timelines across the supply base.
Growth Catalysts
- Hyperscale data center construction:Texas, Virginia, and Arizona are absorbing centrifugal chiller capacity at unprecedented scale as thermal loads per facility exceed 100 megawatts. Cooling infrastructure now represents 35-40% of data center capital expenditure.
- Refrigerant transition mandates:The EPA's SNAP program phase-down timelines for high-GWP refrigerants are accelerating equipment redesign cycles and creating upgrade demand from installed bases running legacy chemistries.
- Integrated Part Load Value optimization:ASHRAE Standard 90.1's progressive tightening is rewarding variable-speed compressor technology and intelligent control systems in commercial building specifications.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials constitute 25-30% of bill-of-materials costs, and commodity swings compress margin predictability for fixed-price project contracts.
- Specialized compressor foundry concentration:Precision casting capacity for high-speed centrifugal impellers concentrates in Germany, Japan, and select US facilities, creating bottleneck risk during demand surges.
- Absorption chiller efficiency ceiling:Single-effect absorption technology cannot match vapor-compression coefficients of performance, limiting addressable market to waste-heat recovery and district cooling applications where thermal energy displacement justifies the efficiency gap.
Strategic Opportunities
- Heat recovery integration:Simultaneous heating and cooling demand in healthcare and hospitality verticals creates margin pools for four-pipe chiller-heaters that displace separate boiler infrastructure.
- Predictive maintenance platforms:IoT-enabled condition monitoring is opening recurring revenue streams through performance guarantees and uptime contracts that shift buyer preference from capital purchase to operational expenditure models.
- India's commercial construction acceleration:Metro rail expansion and pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad are creating specification opportunities for mid-range screw chiller platforms.
Industry Challenges
- Refrigerant handling certification gaps:The transition to A2L mildly flammable refrigerants requires technician retraining that outpaces vocational program throughput, delaying field deployment of next-generation equipment.
- Legacy building automation integration:Proprietary communication protocols in existing Trane, Carrier, and Johnson Controls installed bases create friction for third-party chiller replacements, forcing costly gateway hardware or full BAS rip-and-replace scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Chillers Market |
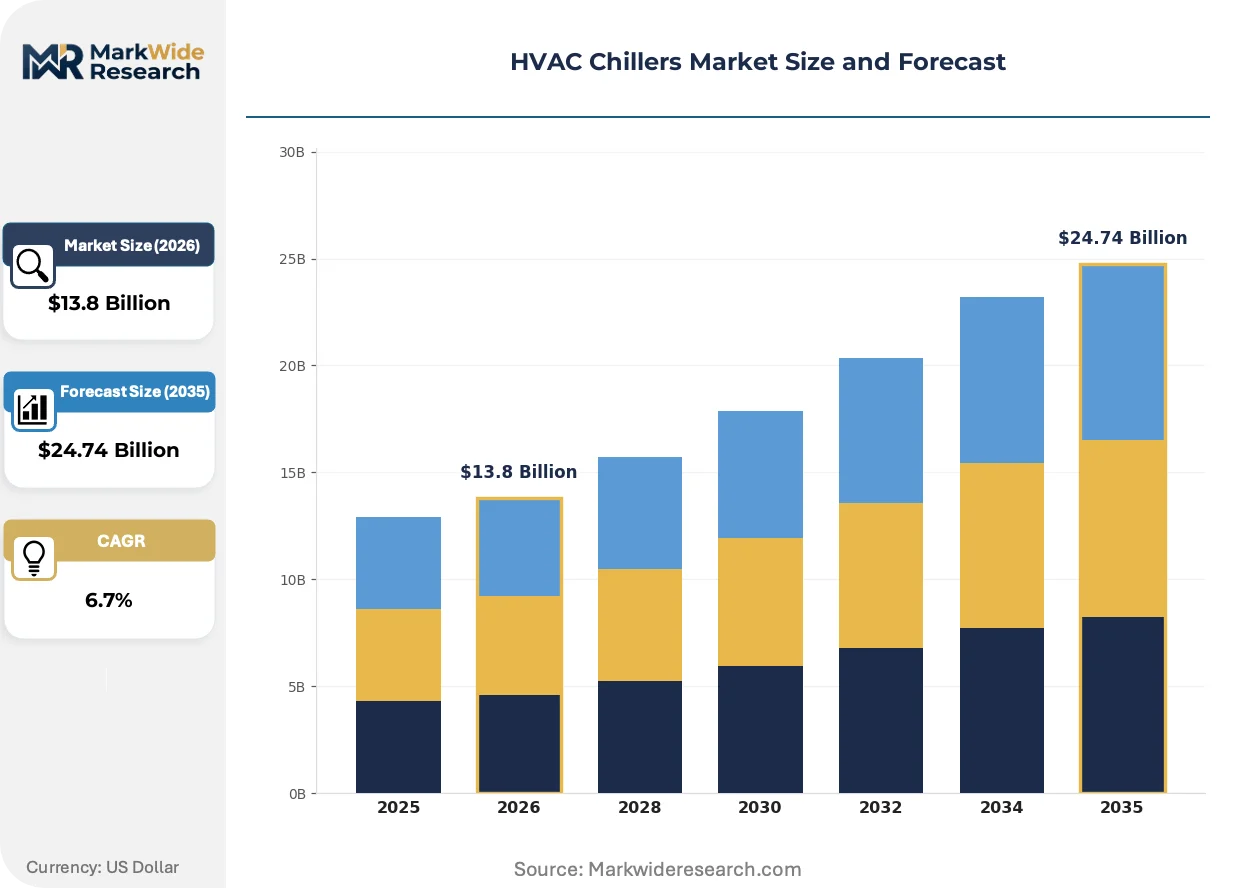
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.74 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Scroll, Screw, Absorption Technology: Vapor Compression, Vapor Absorption, Air-Cooled, Water-Cooled End User: Commercial, Industrial, Residential, Institutional Application: Cooling Systems, Process Cooling, District Cooling, Refrigeration |
| Companies Covered | Carrier Global Corporation, Daikin Industries, Ltd., Trane Technologies plc, Johnson Controls International plc, Mitsubishi Electric Corporation, LG Electronics, GEA Group Aktiengesellschaft, Dimplex Thermal Solutions, Thermax Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Chillers Market Strategic Shifts
Magnetic bearing compressor technology and refrigerant chemistry transitions are converging to reset efficiency benchmarks and maintenance paradigms simultaneously. Equipment specification criteria are migrating from first-cost evaluation to total lifecycle cost models.
Magnetic bearing centrifugal compressors eliminate oil lubrication systems entirely, cutting maintenance intervals from quarterly to annual and removing refrigerant contamination risk. Data center operators in Northern Virginia and Phoenix are specifying oil-free platforms exclusively for facilities above 2,000 tons. This technology is overtaking conventional centrifugal designs in the large-capacity segment within five years of mainstream availability.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbons is compressing equipment redesign cycles to 36-month intervals rather than historical 60-month platforms. Manufacturers must now validate new refrigerant blends across operating temperature ranges while maintaining ASHRAE 15 safety compliance. The commercial building segment across Germany and France is responding through accelerated replacement of R-134a and R-410A equipment ahead of regulatory deadlines.
Lifecycle cost analysis is displacing first-cost evaluation in institutional buyer procurement committees, particularly among university and hospital capital planners. Engineering firms are embedding 20-year energy and maintenance projections into specification documents, favoring premium-efficiency equipment with extended warranties. This behavioral shift is most visible in California and New York where utility incentive structures reward Integrated Energy Efficiency Ratio performance.
HVAC Chillers Market Segmentation
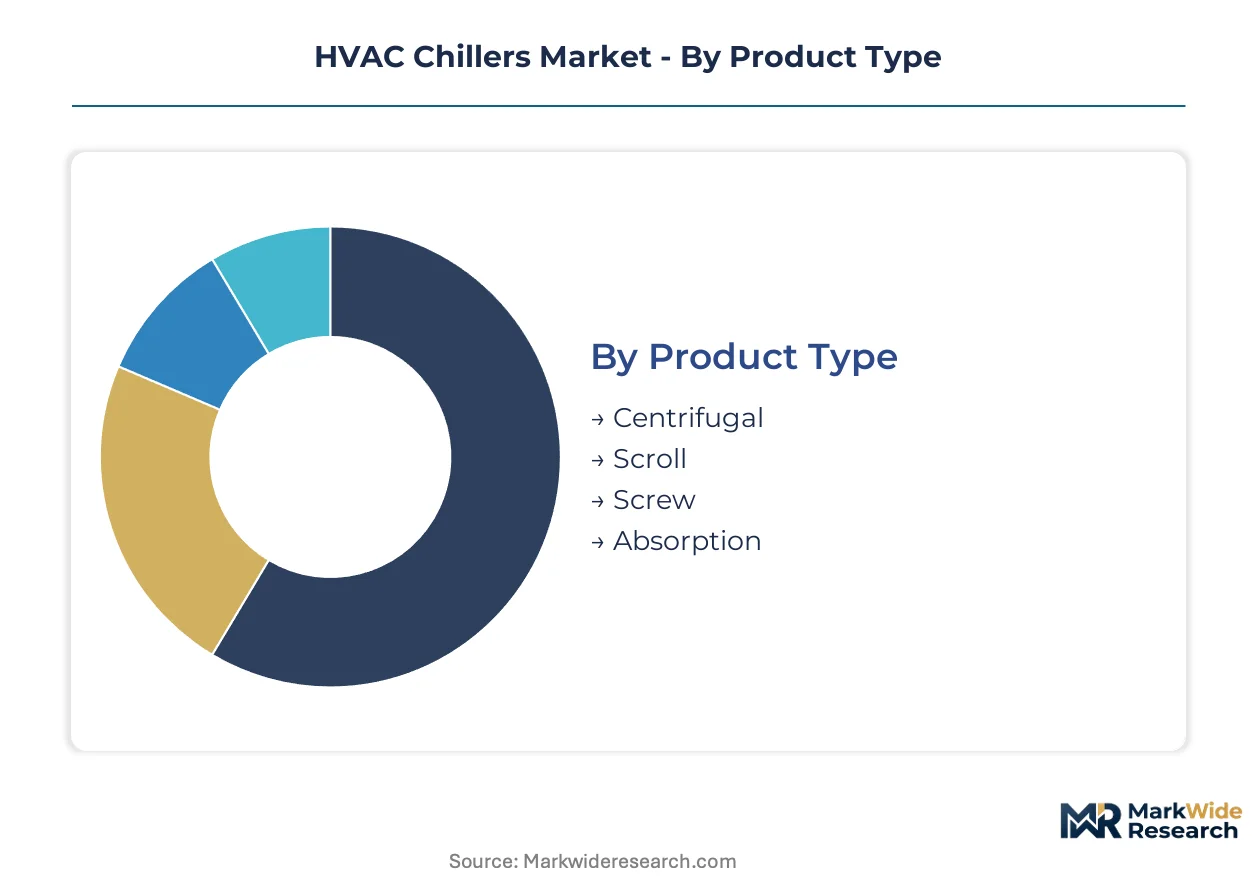
HVAC chiller specifications diverge sharply across deployment contexts, with efficiency mandates and thermal load profiles dictating technology selection. Procurement committees now weight lifecycle cost models against first-capital outlay, reshaping segment prioritization across institutional, industrial, and commercial verticals.
Product Type:
Certification burdens vary by compressor architecture: centrifugal and screw platforms face ASHRAE 90.1 efficiency validation and EPA SNAP refrigerant compliance, while absorption systems trigger thermal safety inspections under ASHRAE 15 and local boiler codes.
- Centrifugal:High-speed impeller designs achieve coefficients of performance above 6.0 at design conditions, with magnetic bearing variants eliminating oil management entirely. Demand concentrates in Northern Virginia and Phoenix hyperscale data centers where single-facility loads exceed 2,000 tons and uptime requirements justify premium specifications. The DOE's five-year efficiency standard resets under 10 CFR 431 force continuous redesign cycles for this segment.
- Screw:Twin-rotor positive displacement compressors deliver operational flexibility across 40-100% load ranges, suiting pharmaceutical manufacturing and hospital campuses with variable thermal profiles. Hyderabad and Ahmedabad metro rail projects in India are absorbing mid-range screw capacity for station cooling and tunnel ventilation systems.
- Scroll:Orbiting scroll compression serves distributed commercial applications below 200 tons, with lower capital thresholds and simplified maintenance protocols. Packaged rooftop units in California retail chains specify scroll platforms for compliance with Title 24 energy codes.
- Absorption:Lithium bromide or ammonia-water cycles operate on waste heat or natural gas combustion, displacing electrical demand in district cooling networks. District cooling operators in Dubai and Singapore deploy double-effect absorption where thermal energy costs undercut electricity tariffs.
Leading the category by volume: Centrifugal. Growing fastest: Screw platforms in Indian infrastructure buildouts.
Technology:
Cost tier separation drives technology selection: vapor compression commands premium pricing for efficiency leadership, while absorption occupies value-tier positioning where thermal fuel access trumps electrical performance.
- Vapor Compression:Mechanical refrigeration cycles using electric-driven compressors dominate installed capacity across all capacity ranges. Texas data center clusters specify water-cooled vapor compression exclusively for 100+ megawatt facilities.
- Vapor Absorption:Thermal-driven cycles leveraging heat source temperature differentials serve district cooling in Saudi Arabia's King Abdullah Financial District and Singapore's Marina Bay district where centralized plant economics favor thermal distribution.
- Air-Cooled:Condenser heat rejection to ambient air eliminates cooling tower infrastructure, reducing first cost and water consumption. Arizona desert facilities specify air-cooled platforms to circumvent water use restrictions under state drought contingency protocols.
- Water-Cooled:Shell-and-tube or plate heat exchanger condensers achieve superior efficiency through evaporative cooling tower integration. Virginia hyperscale campuses deploy water-cooled centrifugal trains to maximize ASHRAE 90.1 Integrated Part Load Value ratings.
Widest deployment: Vapor compression. Steepest efficiency gains: Water-cooled configurations in utility-incentive markets.
End User:
Application maturity determines specification sophistication: institutional buyers embed 20-year lifecycle models, while residential procurement remains first-cost driven with limited efficiency premium capture.
- Commercial:Office towers, retail chains, and hospitality properties specify chillers through engineering firm procurement channels. New York City Local Law 97 carbon intensity caps are accelerating replacement of aging commercial chiller fleets.
- Industrial:Process cooling for chemical, pharmaceutical, and food manufacturing demands precise temperature control and redundant capacity. German chemical clusters along the Rhine specify screw and centrifugal platforms with N+1 redundancy for batch process continuity.
- Residential:Distributed cooling for multi-family housing and luxury developments represents a narrow chiller application, typically served by packaged heat pumps or district connections. High-rise towers in Miami and Vancouver specify small-tonnage water-cooled units where central plant space constraints apply.
- Institutional:Universities, hospitals, and government facilities deploy lifecycle cost analysis and extended warranty requirements. California university capital planners specify magnetic bearing centrifugal platforms with 20-year energy performance guarantees.
Highest specification intensity: Institutional. Expanding most quickly: Industrial process cooling in pharmaceutical manufacturing.
Application:
Margin structure varies by application complexity: district cooling rewards scale economies and long-term service contracts, while discrete process cooling commands customization premiums.
- Cooling Systems:Centralized air conditioning for built environments represents the foundational chiller application, with efficiency standards tightening through ASHRAE 90.1 and IECC code cycles. Chicago commercial retrofits are replacing R-134a equipment ahead of EPA SNAP phase-down deadlines.
- Process Cooling:Industrial manufacturing thermal management requires precise setpoint control and rapid load following. Semiconductor fabrication plants in Taiwan and South Korea specify ultra-pure chilled water systems with sub-degree temperature stability.
- District Cooling:Centralized plant distribution to multiple buildings achieves scale economies in dense urban cores. Paris, Copenhagen, and Dubai district cooling networks operate absorption and electric chillers in hybrid configurations to optimize fuel switching.
- Refrigeration:Low-temperature chiller applications for cold storage and food processing extend below standard air conditioning temperature ranges. Midwest US cold chain logistics hubs deploy screw chillers with glycol brine loops for -10°F storage requirements.
Largest revenue pool: Cooling systems. Gaining share fastest: District cooling in Middle East and European urban densification projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's data center corridor absorbs centrifugal chiller capacity at unprecedented scale, with single-facility thermal loads exceeding 100 megawatts. Texas and Arizona follow as secondary concentration zones where hyperscale construction drives specification intensity.
United States
The US Department of Energy's five-year efficiency resets under 10 CFR 431 compress replacement cycles nationwide. Texas data center clusters in Dallas-Fort Worth and Austin specify water-cooled centrifugal trains exclusively for 100+ megawatt facilities. Arizona desert installations favor air-cooled platforms to circumvent state drought contingency water restrictions.
Germany
Chemical manufacturing clusters along the Rhine specify screw and centrifugal platforms with N+1 redundancy for batch process continuity. The EU F-Gas Regulation's hydrofluorocarbon phasedown accelerates R-134a equipment replacement ahead of 2030 deadlines. Frankfurt's financial district deploys magnetic bearing chillers for district cooling integration.
India
Metro rail expansion in Hyderabad and Ahmedabad creates specification opportunities for mid-range screw chiller platforms. The Bureau of Indian Standards enforces energy labeling under the Standards and Labeling Program for commercial cooling equipment. Pharmaceutical manufacturing clusters in Telangana and Gujarat absorb variable-load screw capacity for process cooling.
China
Semiconductor fabrication plants in Shanghai and Hefei specify ultra-pure chilled water systems with sub-degree temperature stability. The Ministry of Ecology and Environment enforces dual carbon goals that tighten industrial cooling efficiency mandates. Yangtze River Delta data center construction concentrates demand for large-capacity vapor compression systems.
Singapore
Marina Bay district cooling networks operate absorption and electric chillers in hybrid configurations to optimize fuel switching. The National Environment Agency enforces Green Mark standards that reward Integrated Part Load Value performance. Jurong Island petrochemical complexes deploy waste-heat recovery absorption for thermal energy displacement.
HVAC Chillers Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the chiller supply base, with integrated compressor manufacturers controlling component quality against contract assemblers dependent on external sourcing. The market structure concentrates around three strategic archetypes: full-system integrators with captive compressor production, refrigeration specialists leveraging heat pump expertise, and industrial process equipment diversifiers. Dominant competitive moves include backward integration into precision casting capacity and strategic partnerships for refrigerant chemistry validation.
Within the full-system integrator tier, Carrier Global Corporation and Daikin Industries, Ltd. exemplify capital-intensive positioning through in-house compressor manufacturing depth. Trane Technologies plc occupies a distinct position emphasizing building automation compatibility. These three entities anchor the premium specification segment where lifecycle cost analysis displaces first-cost evaluation in procurement committees.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Daikin Industries, Ltd. |
| Trane Technologies plc |
| Johnson Controls International plc |
| Mitsubishi Electric Corporation |
| LG Electronics |
| GEA Group Aktiengesellschaft |
| Dimplex Thermal Solutions |
| Thermax Limited |
| Others |
Value Chain & Pricing Dynamics
Lifecycle cost analysis in institutional procurement committees is compressing pricing power for commodity-grade equipment while rewarding premium platforms with extended performance guarantees. ASHRAE 90.1's Integrated Part Load Value mandates and EPA SNAP refrigerant timelines force manufacturers to absorb redesign costs or pass them through to price-sensitive commercial segments.
Pricing Analysis
Uptime guarantees and energy performance contracts anchor value-based pricing for magnetic bearing centrifugal platforms in hyperscale data center specifications. Three-tier pricing structure across premium, standard, and economy levels separates oil-free magnetic bearing systems from conventional centrifugal designs and refurbished legacy units. Pricing pressure stems from copper and aluminum commodity volatility in heat exchanger manufacturing, compressing margins on fixed-price project contracts. Institutional buyers in healthcare and education verticals exhibit lowest price sensitivity due to 20-year total cost of ownership evaluation frameworks.
Supply Chain Analysis
Precision casting capacity for high-speed centrifugal impellers rests on specialized foundries in Germany, Japan, and select US facilities. Raw material dependencies span copper and aluminum for heat exchangers, rare earth elements for magnetic bearing systems, and engineered refrigerant blends subject to EPA SNAP phase-down constraints. Single-source vulnerability concentrates in compressor impeller manufacturing where demand surges exceed foundry throughput. Distribution runs through OEM direct sales for large-capacity projects and authorized dealer networks for commercial retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressor manufacturing depth has become the decisive vertical-integration lever as precision casting bottlenecks and refrigerant chemistry validation cycles compress platform redesign windows.
For Market Incumbents: Anchor specification loyalty through predictive maintenance platform subscriptions that shift buyer preference from capital purchase to operational expenditure models. Deepen backward integration into magnetic bearing component production to secure supply continuity during demand surges in Northern Virginia and Phoenix data center corridors. Defend against emerging heat pump specialists by accelerating refrigerant transition roadmaps ahead of EPA SNAP enforcement milestones. For New Entrants and Emerging Players: The mid-range screw chiller price-point gap between premium European platforms and economy Asian imports creates specification opportunities in Indian metro rail and pharmaceutical manufacturing clusters. Target Hyderabad and Ahmedabad infrastructure buildouts where Bureau of Indian Standards energy labeling favors efficient variable-speed platforms. Pursue joint venture arrangements with established compressor foundries to circumvent capital barriers to precision casting capability. For Investors and Strategic Acquirers: The window for entry favors component specialists with captive magnetic bearing or advanced heat exchanger technology. Long-term viability hinges on refrigerant chemistry validation capabilities and aftermarket service network density. Watch for absorption chiller efficiency breakthroughs or district cooling contract awards in Middle Eastern urban densification projects as inflection indicators for thermal-driven technology repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive impeller production secures throughput priority during Texas and Virginia demand surges. |
| Predictive Maintenance Platform Launch | IoT-enabled condition monitoring opens recurring revenue streams through uptime performance contracts. |
| Refrigerant Chemistry Validation Partnership | Collaboration with chemical suppliers accelerates ASHRAE 15 compliance for A2L mildly flammable blends. |
| Heat Recovery System Integration | Four-pipe chiller-heater platforms displace separate boiler infrastructure in hospital and hospitality verticals. |
| Geographic Manufacturing Footprint Expansion | Indian production capacity captures metro rail and pharmaceutical cluster demand in Telangana and Gujarat. |
Study Parameters
Independent corroboration across plant engineering directors, OEM procurement teams, aftermarket service heads, and refrigerant supply specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with facility maintenance directors at hyperscale data center operators and thermal systems engineers at district cooling network operators. Secondary validation drew from US Department of Energy 10 CFR 431 efficiency standard filings, EPA SNAP program refrigerant phase-down schedules, ASHRAE Standard 90.1 compliance documentation, and utility incentive program databases. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure tracking across commercial construction and industrial process cooling verticals.
Rate-of-change decomposition across product type, technology configuration, end-use vertical, and application context structured the analytical framework over the projection horizon. Segmentation modeling incorporated compressor architecture, cooling capacity tier, refrigerant chemistry classification, and regional regulatory cluster dimensions. CAGRs derived from unit shipment trajectories weighted by average selling price evolution across premium and standard equipment tiers. Forecast inputs integrated DOE efficiency mandate compliance timelines, data center construction permitting data from primary markets, and refrigerant supply chain constraint assessments from chemical manufacturers.
Inputs from OEM order backlogs and foundry capacity utilization were available through the study window; gaps in real-time commodity price forecasting for copper and aluminum introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding EPA SNAP enforcement pacing and ASHRAE 90.1 code adoption cycles across state jurisdictions. Refrigerant handling certification throughput, legacy building automation protocol compatibility, and hyperscale data center construction permitting velocity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Global Heat Exchangers Market