
 Quantum Information Processing Market | 2026-2036
Quantum Information Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Information Processing Market Analytics
Defense and aerospace procurement is consolidating as the fastest-expanding demand channel for quantum information processing systems. IBM leverages its superconducting qubit roadmap to anchor government contract pipelines. Quantinuum sustains trapped-ion hardware leadership through specialized error-correction architectures. IonQ competes aggressively on cloud-accessible quantum processing capacity for enterprise developers.
Quantum information processing harnesses quantum mechanical phenomena—superposition, entanglement, and interference—to manipulate data in ways that classical binary systems cannot replicate, typically operating at cryogenic temperatures below 20 millikelvin for superconducting implementations. Its primary commercial purpose centers on solving combinatorial optimization, cryptographic, and molecular simulation problems that scale exponentially beyond classical computing limits. Superconducting qubits currently dominate hardware revenue due to mature fabrication compatibility with existing semiconductor foundries, while photonic systems represent the fastest-expanding technology segment because of room-temperature operability and fiber-optic integration potential. Quantum software captures concentrated margin pools as vendors bundle algorithm development tools with proprietary hardware access.
NIST quantum-resistant cryptography mandates and the EU AI Act's high-risk system classifications are reshaping compliance-driven procurement specifications for quantum hardware and software vendors. FDA and EMA regulatory frameworks for quantum-enhanced drug discovery platforms are establishing validation protocols that determine market access timelines for healthcare applications. Stakeholders must monitor standardization progress at ISO and IEC working groups to anticipate interoperability requirements that will dictate platform architecture decisions.
Market Dynamics
Superconducting qubit fabrication is consolidating around foundry partnerships that lock in capacity years ahead of deployment, compressing hardware procurement timelines for defense and financial services buyers.
Growth Catalysts
- NIST Post-Quantum Cryptography Standards:Federal procurement mandates across US defense and banking sectors are accelerating hardware replacement cycles for quantum-resistant infrastructure.
- Trapped-Ion Error Correction Architectures:Specialized error-correction protocols are extending coherent operation times, enabling deeper circuit execution for molecular simulation workloads.
- Federal Quantum Research Funding:Concentrated national laboratory infrastructure in the United States is creating clustered demand pools that anchor early commercial deployments.
Market Restraints
- Dilution Refrigerator Supply Concentration:Cryogenic cooling system manufacturing concentrates among three European and US suppliers, creating 18-24 month lead time bottlenecks for superconducting implementations.
- Helium-3 Isotope Scarcity:Trapped-ion systems require helium-3 for certain cooling stages, with supply constrained by nuclear non-proliferation treaty allocations.
- EU AI Act High-Risk System Classifications:Compliance documentation requirements for quantum-enhanced decision systems are extending sales cycles for European financial services deployments.
Strategic Opportunities
- Photonic Quantum Processors:Room-temperature operability and fiber-optic integration potential are opening distributed quantum networking applications that bypass cryogenic infrastructure constraints.
- FDA Quantum-Enhanced Drug Discovery Pathways:Emerging validation protocols for quantum molecular simulation are creating first-mover advantages for pharmaceutical platform vendors.
- Cloud-Accessible Quantum Processing:API-based access models are lowering trial barriers for enterprise developers without capital-intensive hardware commitments.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Millikelvin system design and operation expertise concentrates among fewer than 200 specialists globally, inflating compensation costs and project delays.
- ISO/IEC Standardization Fragmentation:Competing quantum computing performance metrics across working groups are complicating procurement specifications and interoperability claims.
- Legacy Cryptographic System Migration:Financial institutions face multi-year certificate authority reconfigurations to embed quantum-resistant algorithms without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Information Processing Market |
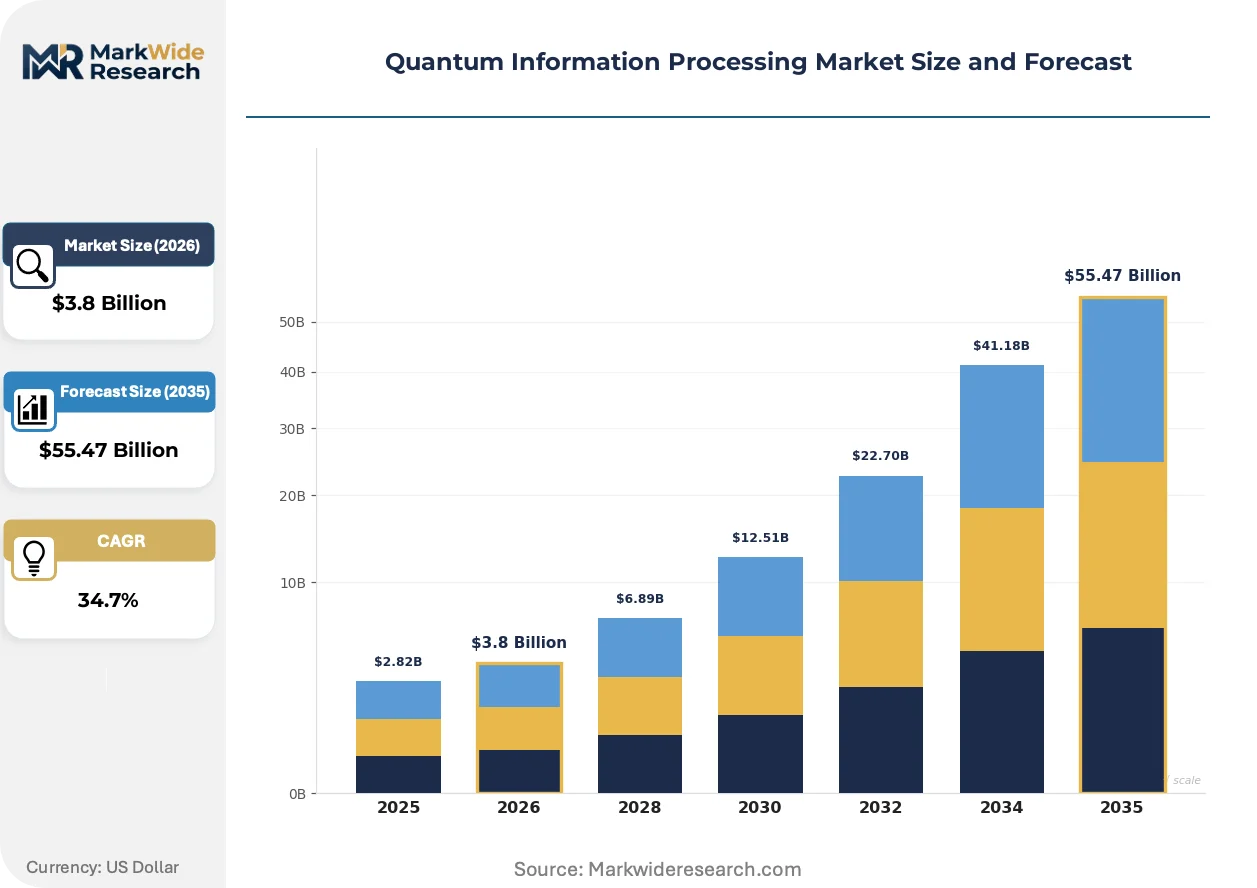
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $55.47 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quantum Computers, Quantum Processors, Quantum Software, Quantum Sensors Technology: Superconducting Qubits, Trapped Ions, Topological Qubits, Photonic Systems End User: Academia, Aerospace, Healthcare, Financial Services Application: Cryptography, Drug Discovery, Optimization, Material Science |
| Companies Covered | IBM, Microsoft, Amazon Web Services, Google, D-Wave Quantum Inc., Intel Corporation, IonQ, Quantinuum, Fujitsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Information Processing Market Evolving Landscape
Photonic interconnect architectures are displacing coaxial cabling in modular quantum systems, enabling room-temperature control electronics separation that reduces cryogenic footprint and operational cost structures.
Photonic qubit routing is decentralizing processor interconnect topologies. Superconducting and trapped-ion system designers are adopting fiber-based entanglement distribution to enable multi-chip modular scaling. Defense procurement specifications now prioritize photonic interconnect compatibility for future system expandability.
EU AI Act high-risk system classifications are mandating algorithmic audit trails for quantum-enhanced financial models. Compliance teams at European banks are embedding explainability requirements into vendor selection criteria. This regulatory pressure is accelerating development of intermediate representation standards for quantum circuit documentation.
Enterprise buyers are compressing evaluation cycles through cloud-based benchmarking subscriptions. Financial services firms now test algorithms across multiple hardware backends before committing to on-premise procurement. This behavior shift concentrates initial demand in United States and European cloud regions with lowest latency access to diverse quantum processing units.
Quantum Information Processing Market Segmentation
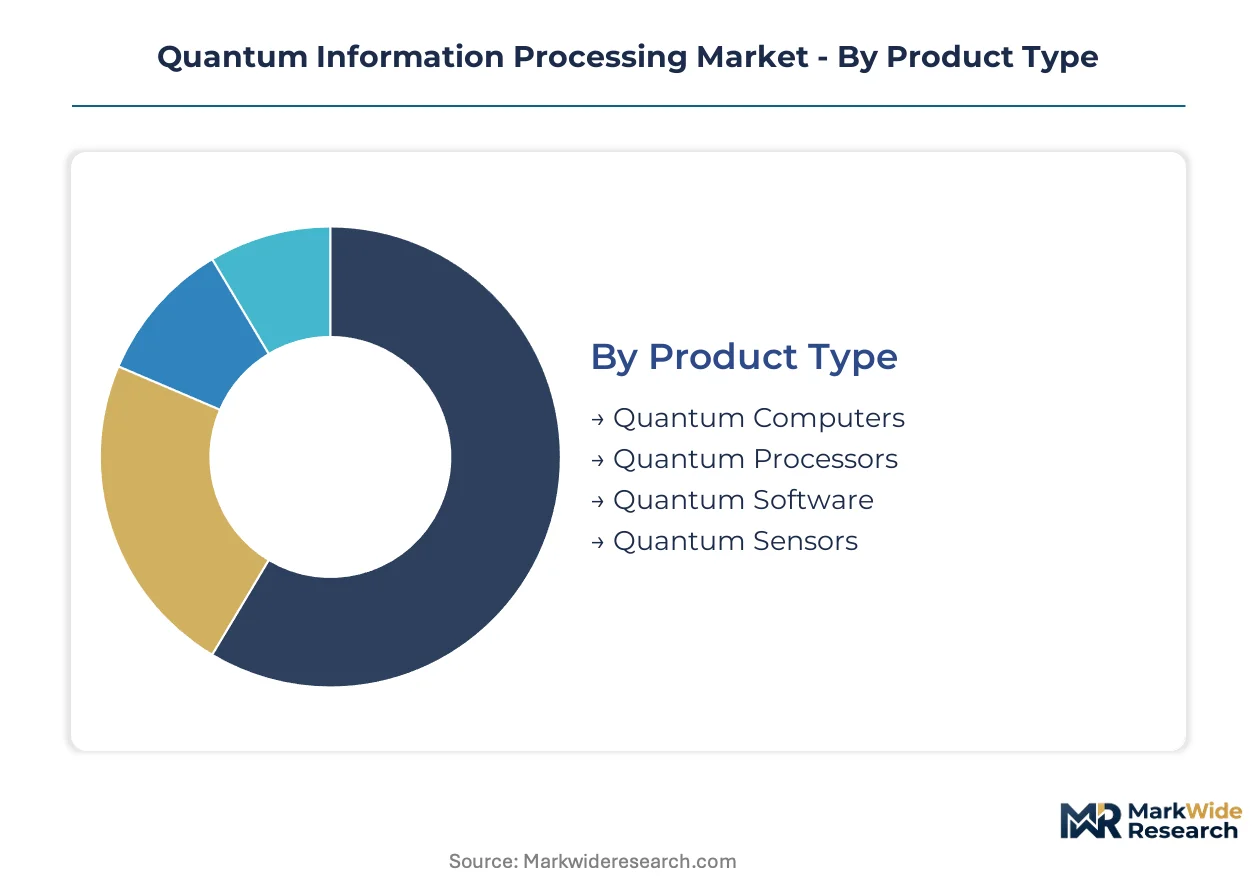
Quantum information processing vendors structure product portfolios around distinct capital-deployment profiles and technical maturity curves. Buyers match hardware investments to specific computational workloads, creating divergent procurement patterns across product categories.
Product Type:
Capital intensity varies dramatically across product categories, with full-stack quantum computers demanding eight-figure infrastructure commitments while software layers capture recurring revenue with minimal fixed asset requirements.
- Quantum Computers:Integrated cryogenic systems with dilution refrigerators and control electronics represent the heaviest capital deployment in the market. Defense agencies in the United States and Germany anchor procurement volumes through national laboratory infrastructure programs. Lead times extend 18-24 months due to European dilution refrigerator supply concentration.
- Quantum Software:Algorithm development platforms and circuit optimization tools operate at the lowest capital threshold, enabling rapid enterprise trial cycles. Financial services firms in New York and London subscribe to cloud-based benchmarking services before committing to hardware procurement.
- Quantum Processors:Modular chip-level components target system integrators building custom configurations. Foundry partnerships with Taiwan Semiconductor and GlobalFoundries lock in fabrication capacity years ahead of deployment.
- Quantum Sensors:Specialized measurement devices leverage quantum coherence for precision navigation and timing applications. Aerospace manufacturers in Toulouse and Hamburg integrate these into next-generation avionics platforms.
Most installed capacity flows through Quantum Computers. Expansion is steepest in Quantum Software.
Technology:
Technology selection determines operating temperature regimes, error correction overhead, and supply chain dependencies that shape total cost of ownership across deployment scales.
- Superconducting Qubits:Josephson junction-based circuits fabricated on silicon substrates leverage mature semiconductor foundry infrastructure. IBM and Google anchor development roadmaps through partnerships with Brookhaven National Laboratory and Oak Ridge National Laboratory. Cryogenic cooling requirements concentrate operational expertise among fewer than 200 specialists globally.
- Photonic Systems:Room-temperature operability eliminates dilution refrigerator dependencies, opening distributed quantum networking applications. Fiber-optic integration potential attracts telecommunications infrastructure investment in Singapore and the Netherlands. Chip-scale photonic integration draws on silicon photonics supply chains centered in Eindhoven and Santa Clara.
- Trapped Ions:Electromagnetic confinement of charged atoms enables high-fidelity gate operations with natural error resilience. Quantinuum maintains specialized error-correction architectures through partnerships with Honeywell. Helium-3 isotope scarcity constrains cooling stage deployment under nuclear non-proliferation treaty allocations.
- Topological Qubits:Exotic quasiparticle braiding promises inherent fault tolerance without massive error correction overhead. Microsoft pursues this architecture through partnerships with Purdue University and the Niels Bohr Institute. Fundamental physics challenges delay commercial readiness beyond competing approaches.
Superconducting Qubits dominate current revenue concentration. Photonic Systems are climbing the fastest.
End User:
End-user sophistication determines procurement modality, with defense and financial services driving hardware purchases while academia anchors cloud-accessible research consumption.
- Financial Services:Portfolio optimization and risk modeling applications justify premium hardware access fees. JPMorgan Chase and Goldman Sachs maintain dedicated quantum research groups testing algorithms across multiple cloud backends. NIST post-quantum cryptography mandates accelerate infrastructure replacement cycles.
- Aerospace:Navigation, communication, and materials simulation requirements align with quantum sensing and computing capabilities. Lockheed Martin and Airbus Defense and Space prioritize photonic interconnect compatibility in procurement specifications for future system expandability.
- Healthcare:Molecular simulation for drug discovery platforms faces emerging FDA and EMA validation protocol requirements. Roche and Novartis evaluate quantum-enhanced platforms through pilot programs with IBM and Google.
- Academia:National laboratory infrastructure in the United States, Germany, and Japan provides clustered demand pools for early commercial deployments. University researchers access cloud-based systems through NSF and EU Quantum Flagship funding mechanisms.
Financial Services command the highest per-seat spending. Healthcare is gaining share fastest.
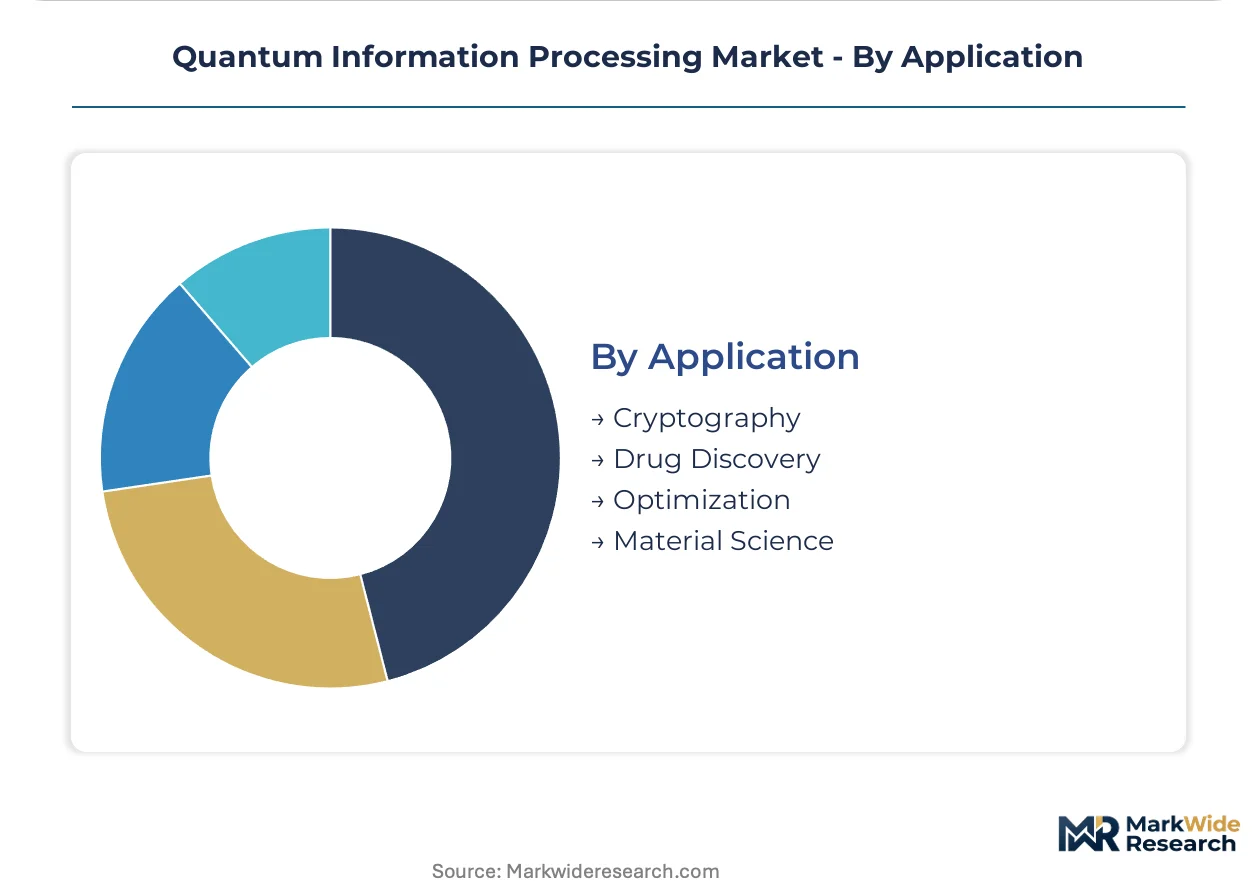
Application:
Application maturity determines algorithm development priorities, with cryptography and optimization offering nearer-term commercial viability than molecular simulation requiring deeper circuit depths.
- Cryptography:Quantum key distribution and post-quantum algorithm implementation address immediate security infrastructure threats. NIST standardization activities in Gaithersburg define procurement specifications for federal agencies and regulated financial institutions.
- Optimization:Combinatorial problems in logistics and portfolio management map efficiently to current noisy intermediate-scale quantum devices. D-Wave Systems and IBM target supply chain applications with hybrid classical-quantum solvers.
- Drug Discovery:Molecular simulation demands error-corrected systems beyond current hardware capabilities. Merck and Biogen participate in early validation protocol development with FDA to establish regulatory pathways for quantum-enhanced platforms.
- Material Science:Catalyst and battery chemistry simulation requires high-fidelity Hamiltonian simulation. BASF and Samsung Advanced Institute of Technology pursue partnerships with quantum hardware vendors for specialized access arrangements.
Optimization captures the largest current workload volume. Drug Discovery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting quantum hardware procurement toward jurisdictions with streamlined export controls and concentrated federal research funding. The United States, Germany, China, Japan, and the United Kingdom capture the bulk of infrastructure deployment as compliance cost differentials widen.
United States
NIST post-quantum cryptography mandates and Department of Energy national laboratory programs anchor procurement volumes. Federal quantum research funding through the National Quantum Initiative Act channels hardware acquisitions toward Brookhaven and Oak Ridge facilities. Defense contractors in Maryland and Virginia integrate superconducting systems into classified computing infrastructure.
Germany
Fraunhofer Institute quantum computing centers and BMW Group molecular simulation requirements drive trapped-ion system demand. EU AI Act high-risk system classifications extend sales cycles for financial services deployments in Frankfurt. Munich anchors photonics research clusters developing fiber-optic quantum interconnects for distributed networks.
China
MIIT quantum technology development plans and state-backed semiconductor foundry investments accelerate superconducting qubit fabrication capacity. National laboratory infrastructure in Hefei and Shanghai concentrates procurement for quantum communication backbone projects. Export control restrictions on cryogenic equipment compress hardware acquisition timelines.
Japan
METI quantum technology innovation strategy funds trapped-ion and photonic system development through Riken and Osaka University partnerships. Pharmaceutical manufacturers in Kansai evaluate quantum-enhanced drug discovery platforms under emerging PMDA validation protocols. Tokyo hosts concentrated cloud-accessible quantum processing demand from financial services firms.
United Kingdom
National Quantum Programme investments and UK Research and Innovation grants position Cambridge and Oxford as hardware development hubs. Financial services firms in the City of London subscribe to cloud-based benchmarking services before on-premise commitments. EMA regulatory frameworks for quantum-enhanced healthcare applications shape pharmaceutical procurement specifications.
Quantum Information Processing Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors secure foundry capacity and national laboratory access years ahead of deployment. The vendor base clusters around three tiers: integrated full-stack providers, specialized hardware component suppliers, and cloud-based software platforms. Superconducting qubit specialists and trapped-ion architects represent distinct strategic archetypes. Foundry partnerships and government contract pipelines constitute the primary competitive moves compressing procurement timelines.
Within the integrated full-stack tier, IBM and Quantinuum occupy positions exemplifying divergent hardware roadmaps—superconducting versus trapped-ion architectures—while IonQ represents the cloud-accessible specialist archetype targeting enterprise developer adoption without capital-intensive infrastructure commitments. These three entities anchor competitive positioning across government, financial services, and pharmaceutical verticals respectively.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Amazon Web Services |
| D-Wave Quantum Inc. |
| Intel Corporation |
| IonQ |
| Quantinuum |
| Fujitsu |
| Others |
Value Network & Pricing Analysis
Defense and national laboratory procurement clusters in the United States anchor pricing power for quantum information processing hardware, compressing vendor margins through multi-year volume commitments while software layers capture recurring SaaS premiums with minimal fixed asset exposure.
Pricing Analysis
Direct-to-government contract discounts dominate hardware transactions, with pricing stratifying across cryogenic system tiers, error-correction capability grades, and cloud-accessibility bundling. Cost compression in superconducting implementations intensifies because dilution refrigerator supply bottlenecks inflate operational overhead. Financial services firms exhibit highest price sensitivity due to evaluation-through-benchmarking behavior, while defense agencies accept premium pricing for security-cleared delivery.
Supply Chain Analysis
Domestic-content mandates in US federal procurement and EU strategic autonomy frameworks are reshaping sourcing toward onshore foundry partnerships. Hardware fabrication concentrates in the United States, Taiwan, and the Netherlands, with specialized cryogenic equipment sourcing from Finland and the United States. Helium-3 isotope scarcity and dilution refrigerator manufacturing bottlenecks create single-source vulnerability for trapped-ion cooling stages. Distribution runs through national laboratory procurement offices and cloud API marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum information processing offers margin expansion through software layer scaling and photonic system cost-down trajectories that bypass cryogenic infrastructure dependencies.
For Market Incumbents: Cement foundry partnership exclusivity through multi-year capacity reservations at Taiwan Semiconductor and GlobalFoundries to lock out emerging superconducting competitors. Deepen upstream control over dilution refrigerator supply chains through equity stakes in Bluefors or Janis Research, countering the threat of 18-24 month lead time extensions that disrupt government contract fulfillment. For New Entrants and Emerging Players: Launch via cloud-native API distribution to bypass capital-intensive hardware manufacturing and capture enterprise developer adoption in financial services benchmarking workflows. Target photonic quantum processor segments where room-temperature operability eliminates cryogenic engineering talent scarcity barriers, offering the most penetrable architecture for modular scaling. For Investors and Strategic Acquirers: Defense contractors and hyperscale cloud providers are the most active acquirer categories in this space, seeking captive quantum processing capabilities. Acquisition targets should display specialized error-correction IP or photonic interconnect architectures with multi-chip scaling potential. Watch NIST post-quantum cryptography procurement mandate timelines as the inflection signal for hardware replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Exclusivity | Locks fabrication capacity years ahead of deployment, securing government contract pipelines against supply-constrained competitors. |
| Photonic Interconnect Architecture | Enables room-temperature modular scaling that bypasses cryogenic talent scarcity and dilution refrigerator bottlenecks. |
| Cloud API Marketplace Integration | Lowers enterprise trial barriers through subscription access, concentrating initial demand in low-latency US and European regions. |
| Error-Correction IP Development | Extends coherent operation times for molecular simulation workloads, creating differentiation in pharmaceutical verticals. |
| NIST Compliance Certification | Accelerates federal procurement eligibility under post-quantum cryptography mandates reshaping defense and banking infrastructure. |
Research Methodology
Multiple input streams — quantum hardware vendor technical disclosures, national laboratory procurement records, and hyperscaler cloud platform documentation — were reconciled against primary interviews with cryogenic engineering specialists, quantum software platform architects, and defense procurement officers. Secondary validation drew from Department of Energy funding announcements, NIST standardization working group minutes, and EU Quantum Flagship progress reports. Bottom-up hardware shipment estimates and top-down federal budget allocation analysis were triangulated to anchor market sizing.
Data-stream reconciliation across the projection horizon employed segmented modeling by technology architecture, end-use vertical, and procurement modality. CAGRs were derived from installed capacity buildout curves and cloud-accessible processing unit deployment trajectories. Forecast inputs incorporated dilution refrigerator manufacturing capacity constraints, helium-3 isotope allocation schedules under nuclear non-proliferation treaties, and NIST post-quantum cryptography standardization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control expansion or breakthrough advances in topological qubit fault tolerance. Projections reflect assumptions regarding cryogenic engineering talent pipeline development and foundry partnership stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Poc Platform and Technology Market