
 Global Quantum Cryptography Solutions Market | 2026-2036
Global Quantum Cryptography Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Quantum Cryptography Solutions Market Foresight
European photonics foundries is pivoting toward cryogenic component fabrication for quantum key distribution hardware. ID Quantique leverages its Geneva-based manufacturing base to sustain dominance in discrete variable quantum systems. QuintessenceLabs anchors the Asia-Pacific supply pipeline through its Canberra engineering center. SandboxAQ competes by extending its AI-quantum hybrid software stack into financial transaction protection workflows.
Quantum cryptography solutions deploy quantum mechanical properties—principally photon polarization states and entanglement correlation—to generate theoretically unbreakable encryption keys, typically operating at wavelengths near 1550 nm for fiber compatibility and requiring single-photon detectors with dark count rates below 100 Hz. Quantum Key Distribution commands the largest installed base but Post-Quantum Cryptography software layers are capturing accelerating enterprise budgets as NIST standardization finalizes. Entanglement-Based Quantum systems retain premium pricing for defense communications while Measurement Device Independent protocols address emerging commercial scalability constraints.
The U.S. NIST post-quantum cryptography standards and the EU Cybersecurity Act's European Cybersecurity Certification Scheme for ICT products create dual compliance burdens that filter vendor eligibility. China's GB standards for quantum communication infrastructure and SAMR encryption export controls constrain technology transfer pathways. Stakeholders must monitor regulatory divergence between FIPS-validated and ETSI-certified implementation paths as procurement specifications crystallize across banking institutions and cloud service providers.
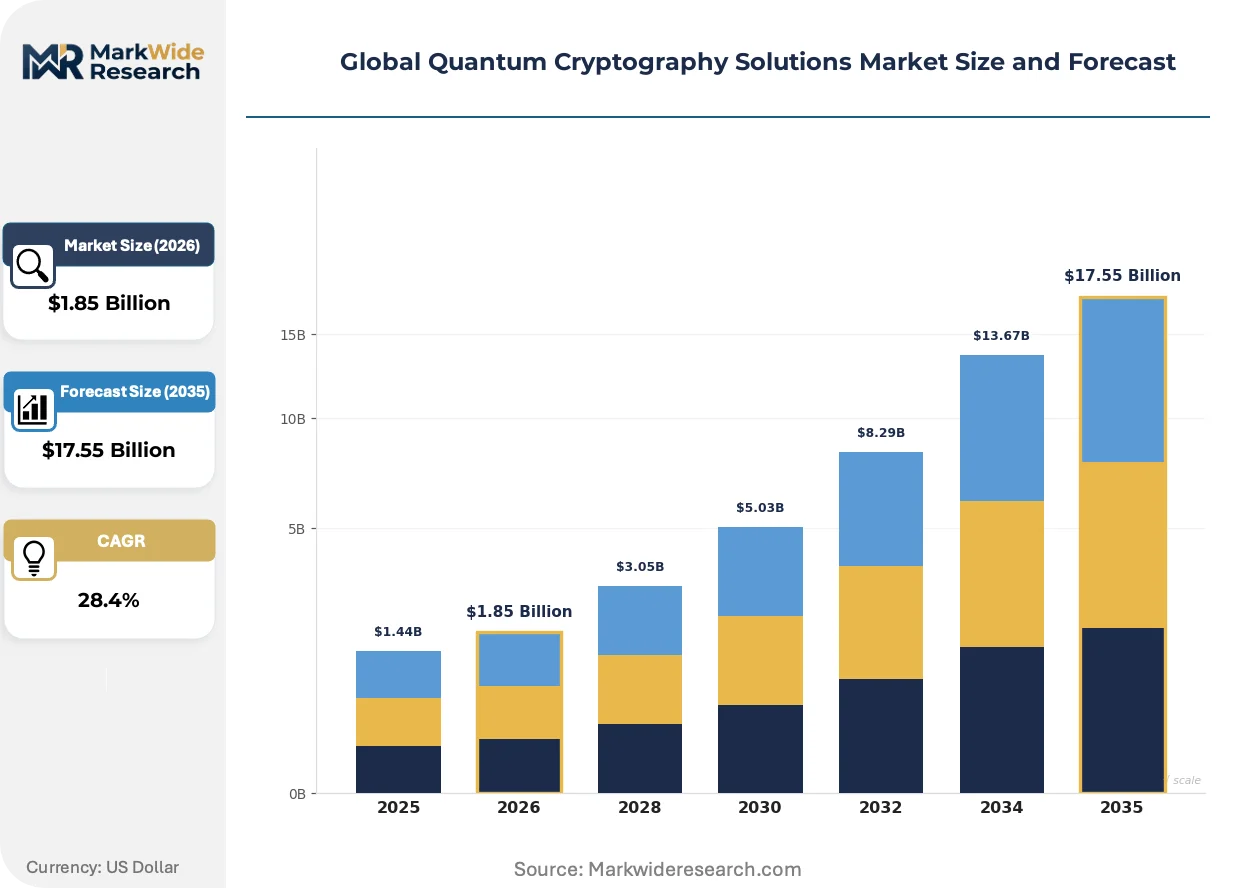
Market Dynamics
The transition from laboratory quantum key distribution to deployable enterprise infrastructure is compressing vendor certification timelines and forcing foundry partnerships for cryogenic photonic component fabrication.
Growth Catalysts
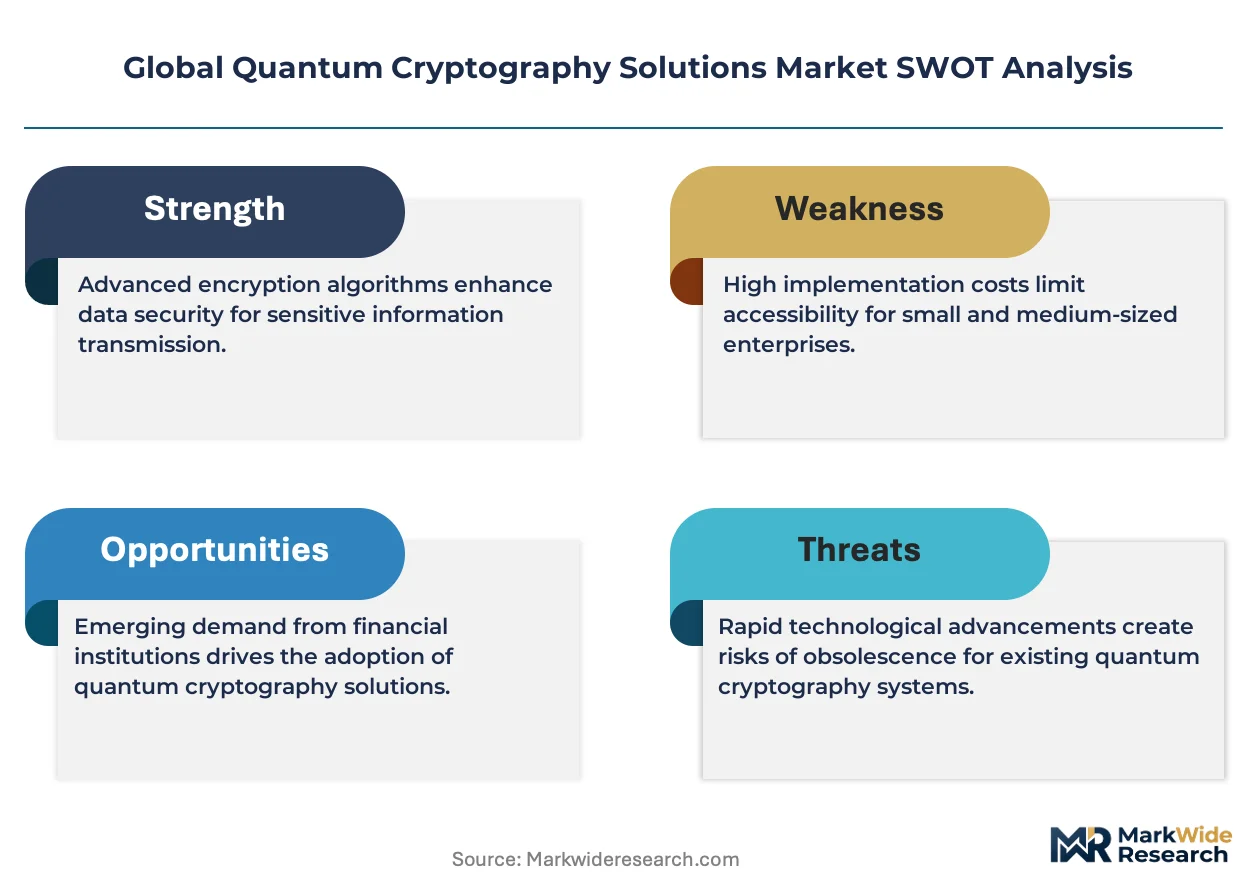
- EU Cybersecurity Act mandates:Post-quantum migration requirements for critical infrastructure operators are creating immediate procurement windows for certified quantum encryption systems across banking and energy networks.
- Defense communication modernization:NATO member state agencies are accelerating discrete variable quantum system deployments for classified satellite-to-ground links, prioritizing vendors with sovereign manufacturing bases.
- Photonics foundry specialization:European semiconductor fabrication facilities are adding cryogenic-compatible process nodes specifically for single-photon detector arrays, reducing hardware lead times for system integrators.
Market Restraints
- Single-photon detector supply concentration:Superconducting nanowire production relies on a limited number of cryogenic test facilities in Switzerland and Japan, creating chokepoints for scaling manufacturing.
- Dual compliance burden:Vendors must simultaneously satisfy US FIPS validation and EU ETSI certification paths, doubling engineering overhead for cryptographic module design.
- Classical encryption substitution:Advanced lattice-based post-quantum algorithms deployed via software updates compete for enterprise budgets against hardware-intensive quantum key distribution systems.
Strategic Opportunities
- Financial transaction protection:Real-time payment clearing networks in Singapore and Switzerland are piloting quantum-secured messaging for high-value settlement flows, opening recurring service revenue models.
- AI-quantum hybrid stacks:Convergence of machine learning-based threat detection with quantum random number generation is creating differentiated offerings for cloud security providers.
- Measurement Device Independent protocols:Commercial scalability constraints in metropolitan fiber networks are driving R&D investment into MDI-QKD architectures that eliminate detector side-channel vulnerabilities.
Industry Challenges
- Cryogenic engineering talent scarcity:System integrators face acute shortages of specialists capable of designing dilution refrigerator interfaces for deployed quantum hardware.
- Legacy network integration complexity:Enterprise IT departments struggle to overlay quantum key distribution onto existing MPLS and SD-WAN infrastructures without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Quantum Cryptography Solutions Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $17.55 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Quantum Key Distribution, Quantum Random Number Generator, Quantum Secure Communication, Post-Quantum Cryptography Technology: Continuous Variable Quantum, Discrete Variable Quantum, Entanglement-Based Quantum, Measurement Device Independent Quantum Application: Telecommunication Encryption, Government Communication, Financial Transaction Protection, Defense Communications, Data Center Security End User: Banking Institutions, Defense Agencies, Cloud Service Providers, Research Laboratories, Telecommunications Operators |
| Companies Covered | MagiQ Technologies, Crypto Quantique, ID Quantique, InfiniQuant, QuintessenceLabs, SandboxAQ, Arqit Quantum, SEALSQ Corp, QuantumCTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Quantum Cryptography Solutions Market Shifts & Advancements
Hardware miniaturization and software-defined key management are converging to reposition quantum cryptography from specialized defense applications toward mainstream enterprise security stacks.
Integrated photonic chips for quantum key distribution are expanding into metropolitan fiber networks by compressing transmitter footprints from rack-scale to pluggable modules. Telecommunication operators in Germany and the Netherlands are trialing these devices for data center interconnect security. The structural consequence is collapsing deployment costs for city-scale quantum networks.
The EU's Cybersecurity Certification Scheme for ICT products is mandating Common Criteria evaluation for quantum encryption modules sold to critical infrastructure operators. This regulatory layer is filtering vendor eligibility toward entities with established European engineering presence. Banking consortia are responding by pre-qualifying only ETSI-certified systems for procurement.
Enterprise buyers are consolidating vendor relationships around full-stack quantum security providers rather than point-product specialists. System integrators in the Asia-Pacific region are bundling key distribution hardware with managed key escrow services. This pattern is most visible in Australia's financial sector, where major banks have issued sole-source contracts to vertically integrated suppliers.
Global Quantum Cryptography Solutions Market Segmentation
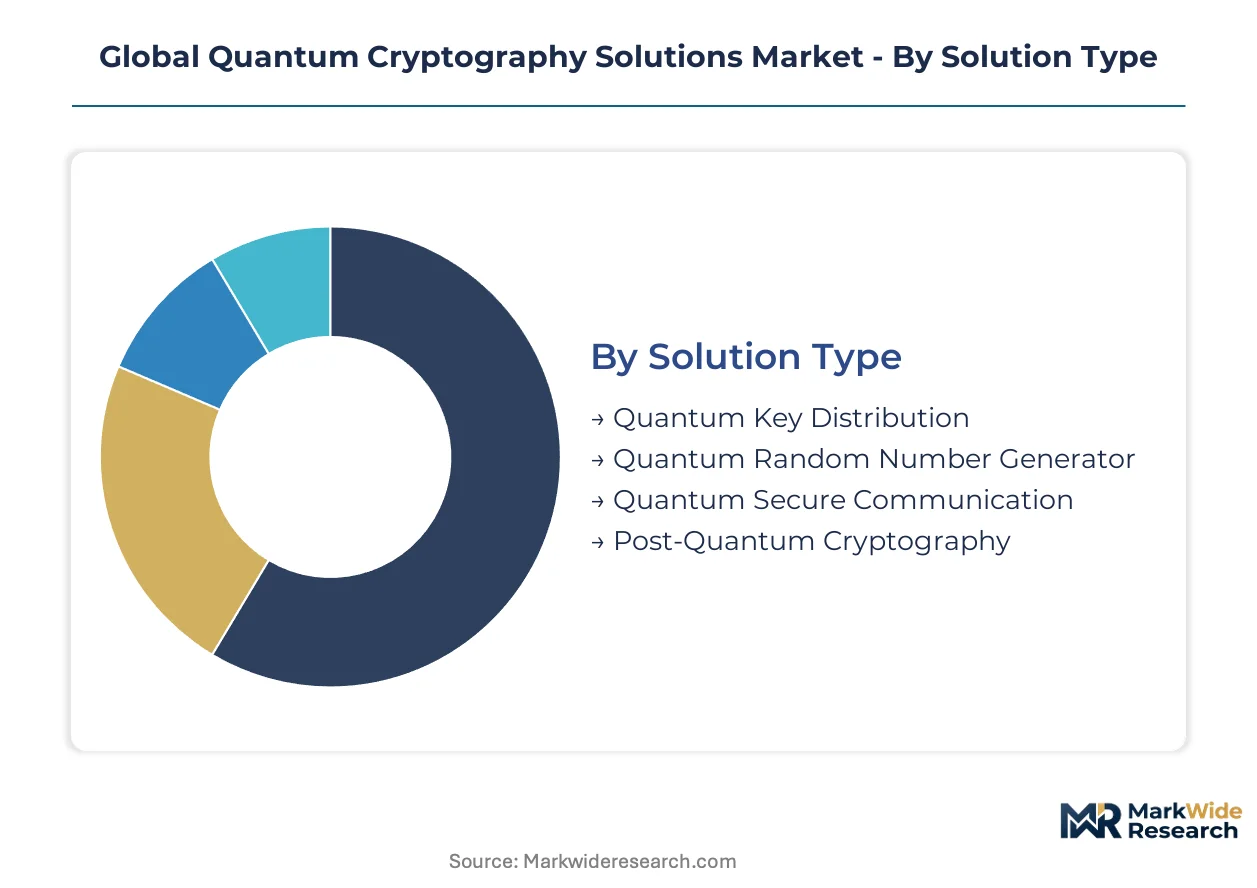
Quantum cryptography solutions fragment across four critical dimensions that determine procurement specifications and vendor selection criteria. Buyers prioritize solution type based on regulatory compliance mandates, while technology choice hinges on existing fiber infrastructure and threat model sophistication. Application and end-user segmentation reveals divergent budget cycles and certification requirements.
Solution Type:
Defense agencies and financial institutions drive purchasing decisions through divergent risk appetites for hardware versus software implementations.
- Quantum Key Distribution:Hardware systems exploiting photon polarization states generate theoretically unbreakable keys at 1550 nm wavelengths for fiber compatibility. NATO procurement for satellite-to-ground classified links concentrates demand in discrete variable systems manufactured at sovereign European foundries.
- Post-Quantum Cryptography:Lattice-based and hash-based algorithms deploy via software updates to existing infrastructure, capturing enterprise budgets as NIST standardization finalizes. Banking consortia in Singapore and Switzerland pilot these layers for high-value settlement flows where hardware deployment proves cost-prohibitive.
- Quantum Random Number Generator:True randomness extraction from quantum mechanical processes seeds cryptographic protocols for cloud security providers.
- Quantum Secure Communication:Integrated protocols combining key distribution with authentication mechanisms serve research laboratories requiring end-to-end protection.
Quantum Key Distribution leads on scale; Post-Quantum Cryptography leads on momentum.
Technology:
Foundry capabilities and cryogenic engineering talent availability constrain technology selection for system integrators.
- Discrete Variable Quantum:Polarization or phase-encoded single-photon states enable proven deployments with mature detector technology. ID Quantique's Geneva manufacturing base sustains dominance as EU Cybersecurity Act certification requirements filter vendor eligibility toward established European engineering presence.
- Measurement Device Independent Quantum:Protocols eliminating detector side-channel vulnerabilities address commercial scalability constraints in metropolitan fiber networks. Telecommunication operators in Germany and the Netherlands trial these architectures for data center interconnect security.
- Continuous Variable Quantum:Quadrature amplitude modulation of coherent states leverages standard telecom components for reduced hardware costs.
- Entanglement-Based Quantum:Photon pair correlation protocols retain premium pricing for defense communications requiring the highest assurance levels.
Discrete Variable Quantum commands installed base; Measurement Device Independent Quantum climbs the fastest.
Application:
Threat model severity and data classification levels determine budget allocation across protective use cases.
- Defense Communications:Classified satellite-to-ground and tactical battlefield links demand sovereign manufacturing bases and Common Criteria evaluation. NATO member state agencies accelerate procurement with strict nationality requirements for component sourcing.
- Financial Transaction Protection:Real-time payment clearing networks pilot quantum-secured messaging for high-value settlement flows. Australia's major banks issue sole-source contracts to vertically integrated suppliers bundling hardware with managed key escrow services.
- Telecommunication Encryption:Metropolitan fiber network protection drives pluggable module miniaturization for city-scale deployment.
- Government Communication:Critical infrastructure operator mandates under EU Cybersecurity Act create immediate procurement windows.
- Data Center Security:Hyperscale facility interconnects require seamless integration with existing MPLS and SD-WAN infrastructures.
Defense Communications dominates revenue concentration; Financial Transaction Protection gains share fastest.
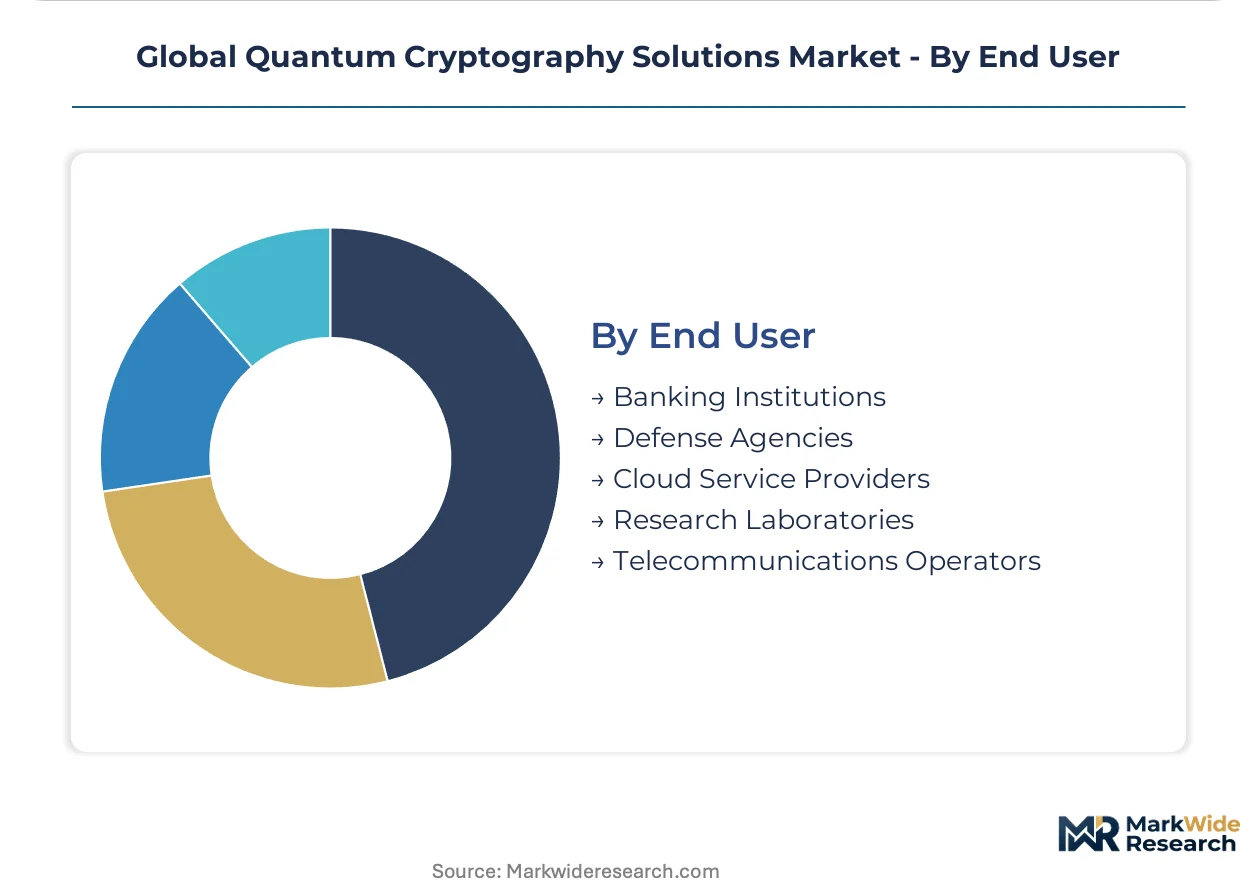
End User:
Procurement sophistication and compliance burden tolerance separate enterprise buyers across institutional categories.
- Defense Agencies:Classified program offices mandate sovereign supply chains and dual-use export control compliance. Superconducting nanowire detector supply concentration in Swiss and Japanese cryogenic test facilities creates procurement chokepoints these buyers navigate through long-term supply agreements.
- Banking Institutions:Risk committees balance hardware-intensive quantum key distribution against software-only post-quantum migration paths. ETSI-certified systems receive pre-qualification for procurement as the EU Cybersecurity Certification Scheme filters vendor eligibility.
- Cloud Service Providers:AI-quantum hybrid stacks integrating machine learning threat detection with quantum random number generation attract this segment.
- Telecommunications Operators:Integrated photonic chip trials compress transmitter footprints from rack-scale to pluggable modules for metropolitan deployment.
- Research Laboratories:Experimental protocol validation and academic consortium participation drive specialized component purchasing.
Defense Agencies anchor premium pricing; Banking Institutions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing quantum cryptography manufacturing capacity as vendors navigate divergent compliance costs between FIPS validation in the United States and ETSI certification in Europe. Sovereign manufacturing requirements in defense procurement are anchoring production in specific national jurisdictions despite higher operational expenses.
United States
NIST post-quantum cryptography standardization drives federal procurement specifications for quantum-resistant algorithms across banking and energy networks. The SEC and CFTC are advancing disclosure frameworks for quantum risk exposure among publicly traded financial institutions. Research concentration clusters around Boston and the San Francisco Bay Area, where venture capital flows into quantum security startups developing AI-hybrid encryption stacks.
Germany
The EU Cybersecurity Act mandates Common Criteria evaluation for quantum encryption modules sold to critical infrastructure operators, filtering vendor eligibility toward established European engineering presence. BSI federal certification requirements impose additional testing layers for cryptographic hardware deployed in government communications. Munich and Berlin anchor the quantum technology corridor where photonics foundries add cryogenic-compatible process nodes for single-photon detector arrays.
Switzerland
Swissmedic and federal data protection authorities coordinate quantum communication standards for pharmaceutical and financial data transmission. The country's neutrality status attracts defense-adjacent quantum research requiring sovereign supply chain guarantees. Geneva hosts specialized manufacturing for discrete variable quantum systems serving NATO classified satellite-to-ground link programs.
China
GB standards for quantum communication infrastructure and SAMR encryption export controls constrain technology transfer while directing domestic procurement toward indigenous suppliers. The national quantum laboratory network prioritizes entanglement-based systems for government and military applications. Hefei and Shanghai concentrate quantum satellite ground station deployment and metropolitan fiber network trials.
Australia
The Australian Signals Directorate issues quantum-safe migration timelines for critical infrastructure operators under the national cybersecurity strategy. TGA alignment with international medical device encryption standards creates procurement windows for quantum-secured health data transmission. Canberra anchors the Asia-Pacific supply pipeline through specialized engineering centers serving regional banking consortia.
Global Quantum Cryptography Solutions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-quantum hybrid software stacks and managed key escrow services. The vendor base stratifies across three tiers: sovereign-manufacturing defense specialists with Common Criteria certifications, software-centric post-quantum cryptography providers, and vertically integrated full-stack suppliers bundling hardware with recurring service revenue. Dominant competitive moves include foundry partnerships for cryogenic photonic component fabrication and strategic alliances with telecommunication operators for metropolitan fiber network trials.
Within the sovereign-manufacturing tier, ID Quantique leverages its Geneva-based engineering presence to sustain positioning in discrete variable quantum systems, while QuintessenceLabs anchors Asia-Pacific supply pipelines through its Canberra engineering center. SandboxAQ occupies the AI-quantum hybrid vector, extending software stacks into financial transaction protection workflows. These three exemplify divergent strategic archetypes: European hardware sovereignty, Asia-Pacific regional anchoring, and software-centric platform expansion.
| Leading Market Players |
|---|
| MagiQ Technologies |
| Crypto Quantique |
| ID Quantique |
| InfiniQuant |
| QuintessenceLabs |
| SandboxAQ |
| Arqit Quantum |
| SEALSQ Corp |
| QuantumCTek |
| Others |
Supply & Pricing Matrix
Sovereign-backed defense contractors and private-equity-rolled-up photonics specialists anchor supply-side ownership patterns, translating concentrated cryogenic foundry access into pricing discipline for quantum key distribution hardware while software-centric post-quantum cryptography providers compete on subscription economics.
Pricing Analysis
Distributor margins for quantum key distribution hardware compress at volume tiers above one hundred units, while direct-to-defense-agency contracts command premium pricing for sovereign-manufactured discrete variable systems with Common Criteria certification. Three-tier pricing structure across certified defense-grade, enterprise-validated, and pilot-program economy levels reflects ETSI certification overhead and cryogenic component scarcity. Pricing pressure stems from lattice-based post-quantum software alternatives that displace hardware budgets in financial services. Banking procurement committees exhibit highest price sensitivity; classified defense program offices demonstrate lowest sensitivity to unit cost.
Supply Chain Analysis
Refurbishment flows for superconducting nanowire single-photon detectors remain minimal given cryogenic degradation sensitivity, though detector array remanufacturing services are emerging in Swiss and Japanese test facilities. Manufacturing concentration centers on Switzerland for discrete variable quantum systems, Germany for cryogenic photonic component fabrication, and China for entanglement-based quantum satellite ground stations. Raw material dependencies include indium phosphide substrates, niobium nitride for superconducting films, and specialized optical fibers with ultra-low attenuation. Single-source vulnerability runs through Swiss cryogenic test facilities for detector validation. Distribution runs through system integrators bundling hardware with managed key escrow services for Asia-Pacific banking consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-layer post-quantum cryptography as NIST standardization eliminates certification fragmentation costs, while hardware providers capture premium tiers through sovereign manufacturing mandates.
For Market Incumbents: Deploy foundry partnership levers to secure cryogenic-compatible process node capacity ahead of EU Cybersecurity Act procurement windows. Lock in long-term supply agreements with Swiss and Japanese superconducting nanowire test facilities to defend against single-source chokepoint vulnerability. Accelerate Common Criteria pre-certification for quantum encryption modules targeting NATO defense agency satellite-to-ground link programs. For New Entrants and Emerging Players: Telecommunication operators in Germany and the Netherlands represent the most penetrable channel partner type for piloting measurement device independent quantum key distribution architectures in metropolitan fiber networks. White-space targets include AI-quantum hybrid software stacks for cloud security providers and managed key escrow services for Australia's financial sector. Go-to-market positioning should emphasize seamless MPLS and SD-WAN integration to reduce enterprise IT deployment friction. For Investors and Strategic Acquirers: Valuations sit cheapest among software-centric post-quantum cryptography providers lacking hardware certification overhead but possessing NIST-aligned algorithm portfolios. Long-term viability favors vertically integrated full-stack suppliers with sovereign manufacturing bases and recurring service revenue models. Monitor ETSI certification completion timelines as inflection indicators for vendor eligibility in EU critical infrastructure procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for Cryogenic Fabrication | Secures process node access for single-photon detector arrays at European photonics facilities. |
| ETSI Certification Completion | Unlocks procurement eligibility under EU Cybersecurity Act mandates for critical infrastructure operators. |
| AI-Quantum Hybrid Stack Development | Integrates machine learning threat detection with quantum random number generation for cloud providers. |
| Measurement Device Independent Protocol R&D | Eliminates detector side-channel vulnerabilities for commercial scalability in metropolitan fiber networks. |
| Managed Key Escrow Service Launch | Captures recurring revenue from Asia-Pacific banking consortia seeking vertically integrated security. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with quantum cryptography system integrators, defense procurement officers, banking risk committee members, photonics foundry engineering directors, and cloud security architects with secondary validation through NIST post-quantum standardization documents, EU Cybersecurity Act regulatory filings, ETSI certification registries, and customs trade data for cryogenic photonic component flows. Bottom-up vendor revenue triangulation against top-down addressable market sizing anchored segmentation-level projections.
Historical reference periods spanning laboratory-to-deployment transition phases informed the analytical framework across the analysis window, with segmentation modeling across solution type, technology protocol, application use case, and end-user institutional category. CAGRs derived from adoption curve analysis for post-quantum migration mandates and defense communication modernization programs, incorporating cryogenic engineering talent scarcity and dual compliance burden variables as drag coefficients.
Revisions become necessary when NIST standardization timelines shift, EU Cybersecurity Act certification requirements expand, or superconducting nanowire detector supply concentration triggers procurement bottlenecks. Practitioners should monitor ETSI pre-qualification announcements and NATO sovereign manufacturing requirement updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Nigeria Cybersecurity Market
Cybersecurity
Israel Cybersecurity Market
Cybersecurity
Global Zero-Trust Security Market
Cybersecurity
Information Security Products and Services Market
Cybersecurity
Saudi Arabia Cybersecurity Market
Cybersecurity
Vietnam Cybersecurity Market
Cybersecurity
Web Filtering Market
Cybersecurity
Hungary Cybersecurity Market
Cybersecurity
Network Security Market
Cybersecurity
Europe SOC As a Service Market
Cybersecurity
Anti-Malware Market
Cybersecurity
Japan Ransomware Protection Market
Cybersecurity
Retail Cybersecurity Market
Cybersecurity
Cloud Application Security Market
Cybersecurity
DNS Security Market
Cybersecurity
Asia Pacific Data Exfiltration Market