
 Quantum Cryptography Market | 2026-2036
Quantum Cryptography Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Cryptography Market Intelligence
Government procurement channels for classified communications infrastructure is reconfiguring as sovereign quantum networks replace legacy encryption backbones. Toshiba anchors Japanese supply through its fiber-based quantum key distribution systems for metropolitan networks. QuintessenceLabs leverages its Australian base to compete in Five Eyes alliance tenders for high-assurance cryptographic modules. ID Quantique specializes in chip-scale quantum random number generators that extend into European financial clearing systems.
Quantum cryptography employs quantum mechanical properties—principally photon polarization states and the no-cloning theorem—to generate theoretically unbreakable encryption keys, with commercial systems typically operating at 1550 nm wavelength over standard single-mode fiber at distances up to 150 kilometers. Quantum Key Distribution commands the installed base across financial services and government security applications, where transmission latency below 10 microseconds per node meets real-time trading and command-and-control requirements. Cloud service providers represent the fastest-growing end user category as managed quantum encryption services reduce capital barriers for enterprises without internal quantum expertise.
FCC spectrum rulings in the United States constrain free-space quantum links, while ETSI standardization frameworks in Europe and NIST post-quantum cryptographic guidelines shape product certification timelines across both jurisdictions. China's MIIT accelerates domestic quantum backbone deployment through national standard GB/T 38648, creating divergent compliance obligations for multinational equipment vendors. Stakeholders must monitor which regulatory bloc's certification regime achieves de facto interoperability acceptance first, as this will determine manufacturing scale economics and export market access for the next generation of quantum security hardware.
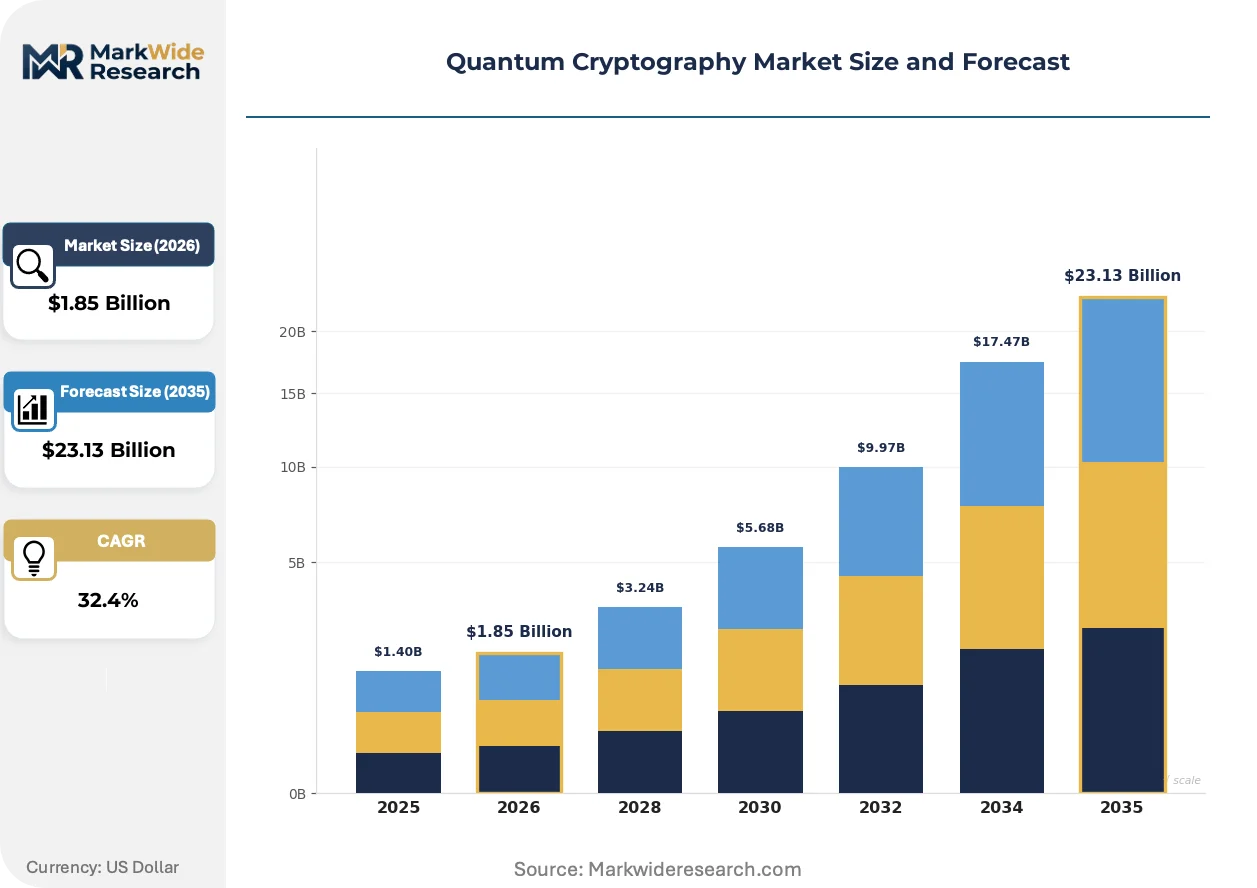
Market Dynamics
Sovereign quantum network mandates are compressing procurement timelines for defense and financial infrastructure, forcing equipment vendors to accelerate certification cycles across divergent national standards regimes.
Growth Catalysts
- Post-Quantum Cryptography Mandates:NIST's finalized post-quantum cryptographic standards are compelling federal agencies to budget for quantum-safe infrastructure upgrades. This creates immediate demand pull for interoperable QKD systems.
- Financial Clearing Modernization:Real-time gross settlement systems in major economies require sub-10 microsecond latency guarantees that quantum key distribution uniquely satisfies. Central banks are embedding QKD into critical payment rails.
- Photonic Integration Advances:Chip-scale quantum random number generators are reducing form factors and power requirements. This enables deployment in edge computing environments previously inaccessible to rack-mounted systems.
Market Restraints
- Single-Source Detector Dependency:Superconducting nanowire single-photon detectors rely on a concentrated supplier base in East Asian manufacturing clusters. Geopolitical friction threatens component availability.
- Fiber Infrastructure Requirements:QKD systems demand dedicated dark fiber or specialized wavelength allocation. Metropolitan areas with constrained fiber duct access face deployment barriers regardless of budget availability.
- Free-Space Atmospheric Limitations:Turbulence and weather variability degrade satellite-based quantum links. This restricts reliable operation to specific climatic zones and orbital windows.
Strategic Opportunities
- Cloud-Managed Encryption Services:Hyperscale providers are developing quantum encryption-as-a-service offerings. This removes capital barriers for mid-market enterprises lacking internal quantum expertise.
- EU Cybersecurity Act Certification:The European Union Agency for Cybersecurity is establishing QKD-specific certification schemes. First-mover accreditation creates preferential market access across member states.
- Healthcare Data Protection:HIPAA-covered entities managing genomic databases represent an underpenetrated vertical. Quantum-secured long-term archival addresses multi-decade confidentiality requirements.
Industry Challenges
- Quantum Engineering Talent Scarcity:The intersection of photonics, cryogenics, and cryptographic protocol design demands specialized expertise. Universities are struggling to scale graduate programs matching industry hiring velocity.
- Legacy PKI Integration Complexity:Hybrid deployments requiring seamless fallback to classical encryption demand extensive systems engineering. Implementation timelines often exceed customer expectations.
- Multi-Jurisdiction Certification Overlap:Vendors must simultaneously satisfy NIST, ETSI, and GB/T testing regimes. Divergent technical interpretations create redundant engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Cryptography Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $23.13 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Quantum Key Distribution, Quantum Teleportation, Quantum Secure Direct Communication, Quantum Digital Signatures Application: Financial Services, Government Security, Healthcare Data Protection, Telecommunications End User: Enterprises, Research Institutions, Defense Agencies, Cloud Service Providers Delivery Model: On-Premises, Cloud-Based Solutions, Hybrid Solutions, Managed Services |
| Companies Covered | NXP Semiconductors, IBM, Toshiba, QuantumCTek, QuintessenceLabs, Thales, IDEMIA, MagiQ Technologies, ID Quantique, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Cryptography Market Strategic Shifts & Innovations
Photonic integration and software-defined cryptographic orchestration are compressing deployment timelines while regulatory fragmentation is forcing modular certification architectures.
Discrete-variable QKD systems based on weak coherent pulse encoding are hybridizing with continuous-variable protocols in metropolitan network deployments. Financial services firms in London and Frankfurt are piloting dual-technology links that switch encoding schemes based on real-time channel conditions. This hybridizing approach is collapsing the traditional distinction between short-haul and long-haul system categories.
ETSI's GS QKD series of specifications is mandating standardized security proofs and interoperability testing for European procurement. Equipment vendors must now submit to common criteria evaluation against these frameworks before national agency tender participation. The German Federal Office for Information Security has positioned itself as the de facto certification gatekeeper, influencing adjacent member state requirements.
Enterprise buyers are consolidating vendor relationships around full-stack quantum security providers rather than component specialists. System integrators are responding by bundling QKD hardware with key management software and professional services. This preference shift is most pronounced in North American defense contracting, where prime contractors demand single-accountability structures for classified infrastructure builds.
Quantum Cryptography Market Segmentation
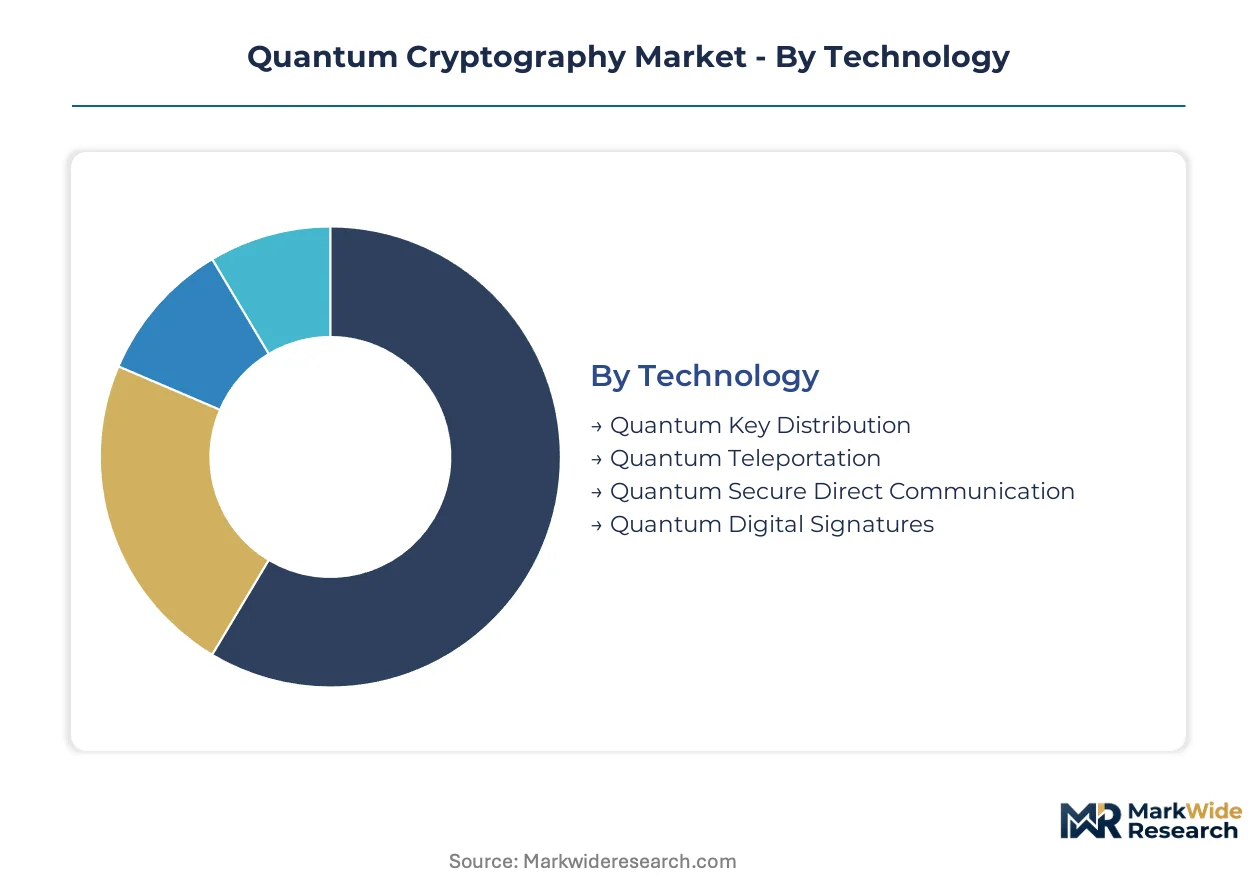
Technology heterogeneity in quantum cryptography demands precise segment mapping. Each dimension—protocol architecture, deployment context, buyer profile, and service model—carries distinct procurement rhythms and certification requirements that reshape vendor go-to-market strategies.
Technology:
Quantum mechanical implementations span discrete-variable encoding, entanglement-based transmission, and direct communication protocols, each commanding different hardware footprints and distance-performance tradeoffs.
- Quantum Key Distribution:Weak coherent pulse and entanglement-based systems generate shared secret keys through photon polarization states. Financial clearinghouses in Frankfurt and London deploy fiber-based QKD for sub-10 microsecond latency guarantees in real-time gross settlement systems.
- Quantum Teleportation:Entanglement-assisted state transfer enables quantum information routing across network nodes without physical transmission of quantum states. Research consortia in Munich's quantum cluster pilot metropolitan-scale teleportation links for distributed quantum computing architectures.
- Quantum Secure Direct Communication:Message transmission without prior key establishment eliminates key management infrastructure. China's MIIT-backed backbone deployments favor this protocol for administrative network segments requiring minimal latency overhead.
- Quantum Digital Signatures:Quantum one-way functions enable non-repudiable document authentication. German Federal Office for Information Security certification frameworks are accelerating pilot programs for classified document workflows.
Established volume favors Quantum Key Distribution; emerging adoption favors Quantum Teleportation.
Application:
End-use contexts impose divergent performance thresholds, from microsecond-latency trading infrastructure to multi-decade archival confidentiality.
- Financial Services:Real-time payment rails and high-frequency trading platforms demand cryptographic refresh cycles measured in microseconds. Central banks embed QKD into critical clearing infrastructure, with the ECB piloting cross-border quantum-secured settlement corridors.
- Government Security:Classified communications and sovereign network backbones require Common Criteria certification against national security profiles. NATO procurement channels specify ETSI GS QKD compliance for member state interoperability.
- Healthcare Data Protection:Genomic databases and longitudinal patient records face 50-year confidentiality horizons. HIPAA-covered entities in the United States evaluate quantum-secured archival for multi-generational data stewardship obligations.
- Telecommunications:Carrier-grade key distribution for 5G backhaul and satellite ground links. Japanese operators test free-space quantum links for island-to-island connectivity where fiber deployment proves uneconomical.
Defense procurement concentrates in Government Security; cloud-native deployment models are gaining share fastest in Telecommunications.
End User:
Buyer sophistication and capital availability segment the market across self-managed infrastructure and outsourced cryptographic services.
- Enterprises:Mid-market firms lacking internal quantum expertise favor managed encryption services. Capital constraints drive preference for subscription-based key distribution over hardware acquisition.
- Research Institutions:Academic and national laboratory users prioritize protocol flexibility and experimental access. Funding cycles align with grant-based procurement rather than operational budgets.
- Defense Agencies:Classified infrastructure mandates impose stringent supply chain provenance requirements. Five Eyes alliance tenders specify domestic manufacturing content for critical detector components.
- Cloud Service Providers:Hyperscale operators integrate quantum encryption into multi-tenant security portfolios. AWS, Azure, and Google Cloud platform teams are the steepest expansion trajectory in end-user demand.
Defense Agencies anchor near-term revenue concentration; Cloud Service Providers command the steepest expansion trajectory.
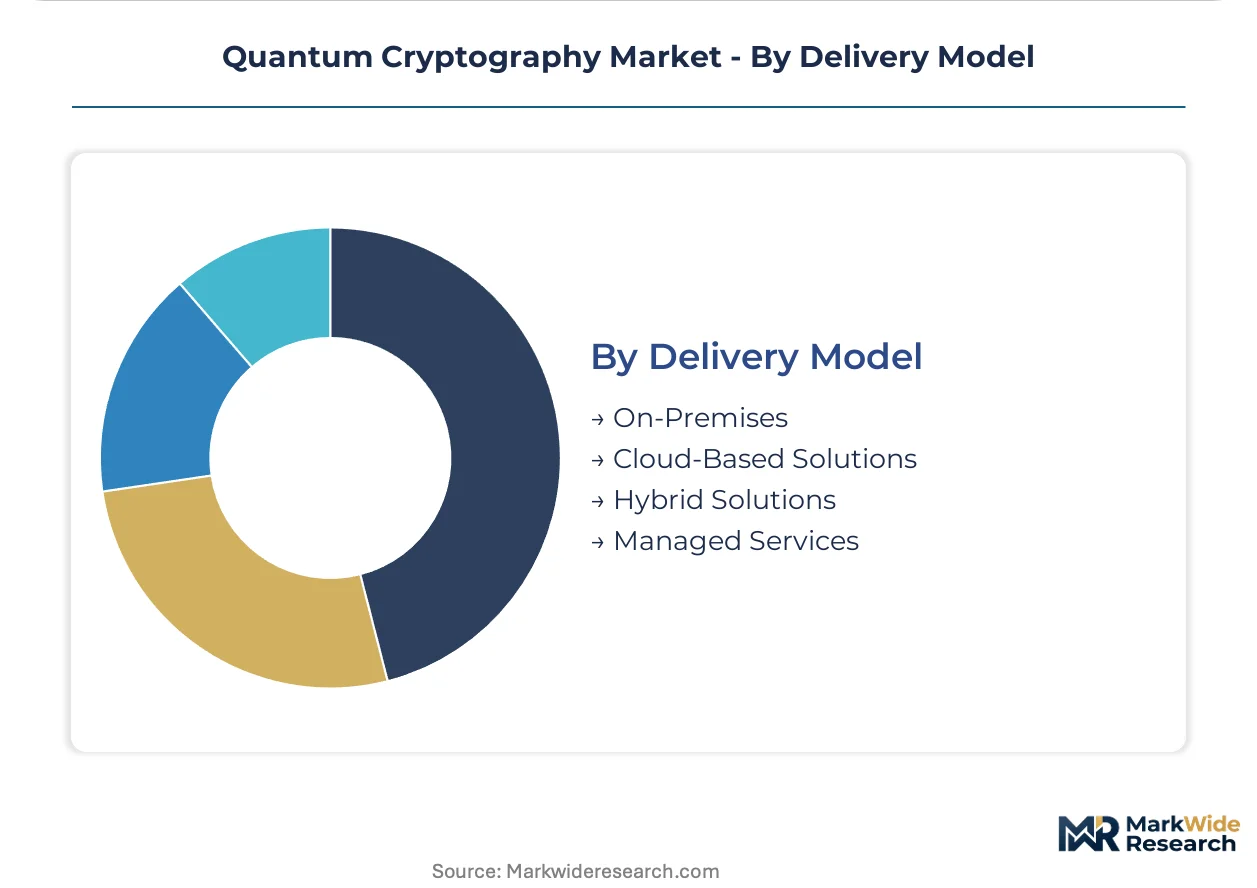
Delivery Model:
Deployment architecture determines capital intensity, operational control, and regulatory audit surface area for enterprise buyers.
- On-Premises:Dedicated QKD hardware within customer-controlled facilities satisfies air-gapped security requirements. Financial regulators in Germany mandate on-premises key generation for systemically important payment infrastructure.
- Cloud-Based Solutions:API-accessible quantum key distribution eliminates hardware procurement. Mid-market enterprises in the United States adopt cloud-native models to bypass quantum engineering talent scarcity.
- Hybrid Solutions:Combined on-premises and cloud key management enables workload-specific security tiering. Large enterprises pilot hybrid architectures for gradual post-quantum migration.
- Managed Services:Full-stack outsourcing covers hardware, software, and operational key lifecycle management. System integrators bundle managed QKD with professional services for defense contracting single-accountability structures.
On-Premises deployments dominate classified environments; Cloud-Based Solutions are climbing the fastest in commercial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fiber optic backbone connecting Frankfurt to Luxembourg anchors European quantum network architecture. Japan's metropolitan fiber rings support Toshiba's commercial QKD deployments. China's Beijing-Shanghai quantum backbone demonstrates sovereign network scale.
United States
NIST post-quantum cryptographic standards drive federal procurement for quantum-safe infrastructure upgrades. FCC spectrum rulings constrain free-space quantum link deployment across commercial bands. Boston's quantum research cluster hosts experimental fiber networks linking MIT and Harvard laboratories.
Germany
The German Federal Office for Information Security certifies QKD systems for federal agency tender participation. EU Cybersecurity Act mandates reshape procurement requirements across member state interoperability frameworks. Munich's quantum technology cluster concentrates Toshiba Europe and ID Quantique engineering operations.
China
MIIT accelerates domestic quantum backbone deployment through national standard GB/T 38648 compliance obligations. State-directed investment prioritizes quantum-secured administrative networks for government communications. Beijing hosts the national quantum laboratory coordinating metropolitan fiber link expansion.
Japan
METI funding programs support commercialization of fiber-based quantum key distribution for financial services. Metropolitan operators test free-space quantum links for island-to-island connectivity where fiber deployment proves uneconomical. Tokyo anchors Toshiba's quantum division headquarters and metropolitan network pilot programs.
Australia
Five Eyes alliance tenders for high-assurance cryptographic modules create demand pull for domestic quantum security vendors. National cybersecurity strategy prioritizes sovereign quantum capability development for defense communications. Canberra's defense technology precinct hosts QuintessenceLabs engineering and government contract execution.
Quantum Cryptography Market Key Industry Players
On the supply side, the industry is consolidating around full-stack quantum security providers rather than component specialists. Equipment vendors face compressed certification cycles across divergent national standards regimes. Three archetypes dominate: diversified technology conglomerates with quantum divisions, pure-play quantum cryptography specialists, and defense contractors integrating QKD into classified infrastructure builds. Strategic moves center on ETSI GS QKD certification acceleration and cloud-managed encryption service launches.
Among diversified technology conglomerates, Toshiba anchors Japanese supply through metropolitan fiber deployments. IBM occupies a position exemplifying research-to-commercialization pathways for enterprise quantum security services. Thales represents the defense contractor archetype, sitting within European procurement channels for NATO-aligned cryptographic infrastructure.
| Leading Market Players |
|---|
| NXP Semiconductors |
| IBM |
| Toshiba |
| QuantumCTek |
| QuintessenceLabs |
| Thales |
| IDEMIA |
| MagiQ Technologies |
| ID Quantique |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber cable routes linking Japan to the US West Coast concentrate freight costs for superconducting nanowire single-photon detectors, compressing margins on QKD hardware shipments while amplifying price differentiation between certified and uncertified system tiers.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations across defense and financial verticals. Three-tier pricing stratification separates Common Criteria-certified sovereign network systems from commercial-grade metropolitan deployments and experimental research configurations. Certification grade and volume scale drive price differentiation, with ETSI GS QKD-accredited hardware commanding substantial premiums over pre-certified alternatives. Cost compression in the mid-market tier intensifies as cloud-managed encryption services displace capital-intensive hardware sales. Mid-market enterprises lacking quantum engineering expertise exhibit highest price sensitivity, while defense agencies prioritize supply chain provenance over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for critical detector components. Manufacturing concentrates in Japan, South Korea, and specialized facilities within the Five Eyes alliance jurisdictions. Superconducting nanowire single-photon detectors, indium phosphide modulators, and cryogenic cooling systems constitute essential input dependencies. Single-source vulnerability in East Asian detector fabrication threatens component availability amid geopolitical friction. Distribution runs through prime defense contractors and system integrators bundling hardware with professional services for classified infrastructure builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
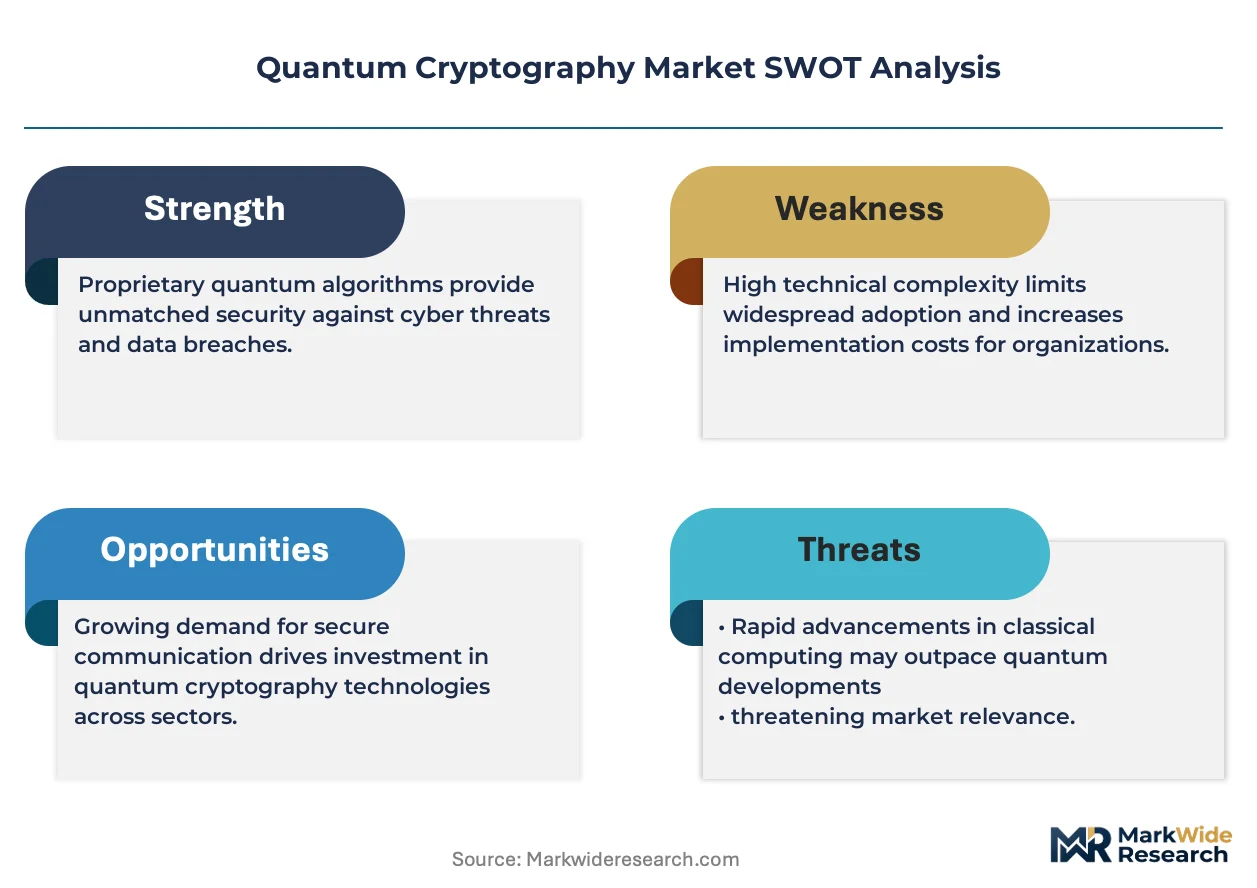
Post-quantum cryptographic algorithms represent an imminent substitution threat that QKD incumbents must navigate through hybrid certification strategies and latency-performance differentiation.
For Market Incumbents: Pre-empt algorithmic substitution by accelerating ETSI GS QKD certification timelines and embedding QKD hardware into sovereign network mandates before software-based post-quantum cryptography achieves deployment scale. Secure exclusive supply agreements for superconducting nanowire detectors from Japanese and South Korean sources. Vertical integration into cryogenic component manufacturing reduces exposure to East Asian supply concentration.
For New Entrants and Emerging Players: Mid-market healthcare data protection in the United States represents the most penetrable entry point for quantum-secured archival services targeting HIPAA-covered entities with multi-decade genomic database confidentiality obligations. Cloud-native managed encryption offerings bypass capital barriers and quantum engineering talent scarcity constraining enterprise self-deployment. Partner with hyperscale platform teams to embed quantum key distribution APIs into multi-tenant security portfolios.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates seeking to monetize non-core quantum divisions amid strategic portfolio rebalancing. Long-term viability hinges on first-mover certification accreditation and sovereign network procurement channel access rather than pure technology differentiation. Monitor ETSI GS QKD certification queue positioning as the inflection signal distinguishing scalable market access from marginalization.
| Strategic Initiative | Industry Significance |
|---|---|
| ETSI GS QKD Certification Acceleration | First-mover accreditation unlocks preferential access to EU member state procurement channels. |
| Cloud-Managed Encryption Service Launch | Subscription models bypass capital barriers for mid-market enterprises lacking internal quantum expertise. |
| Superconducting Detector Supply Agreement | Exclusive sourcing from Japanese and South Korean manufacturers mitigates single-source geopolitical risk. |
| Healthcare Vertical Partnership Program | HIPAA-covered entities with genomic databases require multi-decade confidentiality guarantees. |
| Sovereign Network Integration Partnership | Embedding QKD into national backbone deployments creates multi-year recurring revenue visibility. |
Research Approach
Operator-level perspectives from quantum engineering directors, defense procurement officers, financial infrastructure security leads, and cloud platform cryptography teams anchored the qualitative base. Primary interviews combined with secondary validation against ETSI specification documents, NIST post-quantum cryptographic standard filings, and national quantum backbone deployment disclosures. SEC 10-K filings from diversified technology conglomerates, EU Cybersecurity Act implementation guidance, and hyperscaler capex disclosures provided quantitative grounding. Bottom-up segment sizing and top-down macro constraint triangulation ensured internal consistency.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include protocol architecture, deployment context, buyer sophistication tier, and service delivery model. Technology adoption curves, regulatory certification timelines, and sovereign network procurement cycles constituted industry-specific forecast inputs. CAGRs derived from segment-level unit economics and pricing trajectory analysis rather than extrapolation.
Macroeconomic conditions sit as an overlay; deviation in federal defense budgets, central bank payment infrastructure investment cycles, or trans-Pacific trade friction would shift the trajectory. Forecasts reflect documented assumptions about standardization convergence and certification queue progression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cloud Application Security Market
Cybersecurity
Thailand IT and Security Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
AI in Cybersecurity Market
Cybersecurity
Hong Kong Cybersecurity Market
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
North America Data Exfiltration Market
Cybersecurity
Global Sensitive Data Discovery Market
Cybersecurity
Wireless Lan Security Market
Cybersecurity
Kuwait Cybersecurity Market
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
Poland Cybersecurity Market
Cybersecurity
Hungary Cybersecurity Market
Cybersecurity
Network Traffic Analysis Solutions Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Global IoT Digital Forensics Market