
 Network Traffic Analysis Solutions Market | 2026-2036
Network Traffic Analysis Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Network Traffic Analysis Solutions Market Outlook
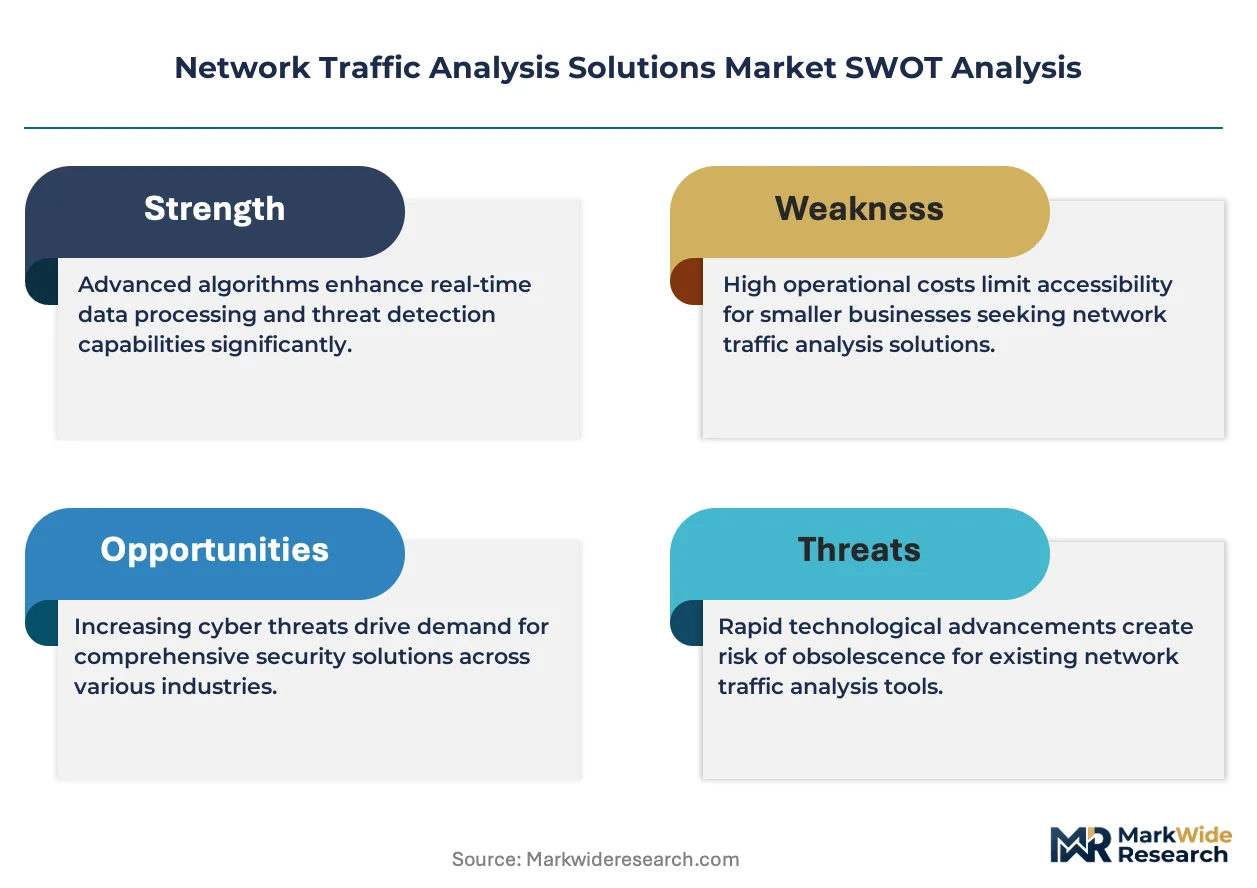
The certified cybersecurity analyst labor pool is collapsing across Western Europe and North America, forcing enterprises to automate traffic inspection rather than staff security operations centers manually. Cisco Systems leverages its entrenched switching footprint to embed analytics directly at the network edge, reducing separate appliance procurement. NETSCOUT Systems anchors its position through deep packet inspection hardware that sustains performance at carrier-scale throughput. Darktrace differentiates via self-learning algorithms that compete with signature-dependent rivals by detecting novel behavioral anomalies without prior training data.
Network traffic analysis solutions encompass software and hardware systems that capture, decode, and interpret data packets and flow records traversing enterprise and service provider infrastructure, typically operating at line rates from 1 Gbps to 400 Gbps with millisecond-level latency budgets to support real-time decisioning. Their primary commercial purpose is to expose covert threats, optimize application performance, and enforce policy compliance across distributed architectures. Threat detection solutions currently dominate value capture as ransomware and supply chain compromises intensify board-level scrutiny, while cloud-based deployment models represent the fastest-expanding configuration as multicloud sprawl complicates east-west visibility. Managed service delivery is maturing fastest among deployment options, with margin pools concentrating in providers that bundle tier-1 carrier telemetry with proprietary analytics engines.
The EU AI Act, NIS2 Directive, and GDPR collectively shape product roadmaps by mandating explainable anomaly detection, mandatory incident disclosure windows, and granular data handling audit trails for traffic metadata. The FCC in the United States reinforces parallel pressures through enhanced reporting obligations for communications service providers following major outages. Stakeholders must decide whether to build unified traffic intelligence stacks internally or accept dependency on platform vendors that increasingly control both ingestion and inference layers.
Market Dynamics
The collapse of certified cybersecurity analyst labor pools across Western Europe and North America is forcing enterprises to automate traffic inspection rather than staff security operations centers manually. This structural labor shortage is compressing deployment timelines and elevating platforms that embed intelligence directly into network infrastructure.
Growth Catalysts
- EU AI Act mandates:The regulation requires explainable anomaly detection for critical infrastructure operators, creating baseline demand for traffic analysis platforms that document decision logic.
- Automotive sector retrofitting:German industrial conglomerates are deploying unified visibility layers across legacy OT networks to secure manufacturing floors against lateral movement.
- Cloud-native architecture sprawl:Multicloud environments complicate east-west traffic visibility, accelerating procurement of solutions that aggregate telemetry across distributed workloads.
Market Restraints
- Deep packet inspection hardware costs:Carrier-scale throughput requirements demand specialized silicon, concentrating supply among semiconductor fabricators with extended lead times.
- GDPR metadata handling constraints:Granular audit trail requirements for traffic metadata increase engineering overhead and limit feature velocity for European deployments.
- Signature-dependent rival saturation:Established vendors with pattern-matching architectures create pricing pressure, compressing margins for behavioral analytics entrants.
Strategic Opportunities
- NIS2 Directive incident windows:Mandatory disclosure timelines for critical infrastructure operators create pull for platforms with automated reporting workflows.
- Managed service bundling:Providers integrating tier-1 carrier telemetry with proprietary analytics engines capture expanding margin pools as enterprises outsource monitoring.
- OT-IT convergence in industrial settings:Unified traffic visibility layers that bridge operational technology and information technology networks address underpenetrated manufacturing verticals.
Industry Challenges
- Millisecond latency engineering:Real-time decisioning at 400 Gbps line rates demands specialized optimization that scarce firmware developers struggle to deliver.
- Self-learning algorithm validation:Behavioral models that operate without prior training data face scrutiny from risk committees requiring deterministic explainability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Traffic Analysis Solutions Market |
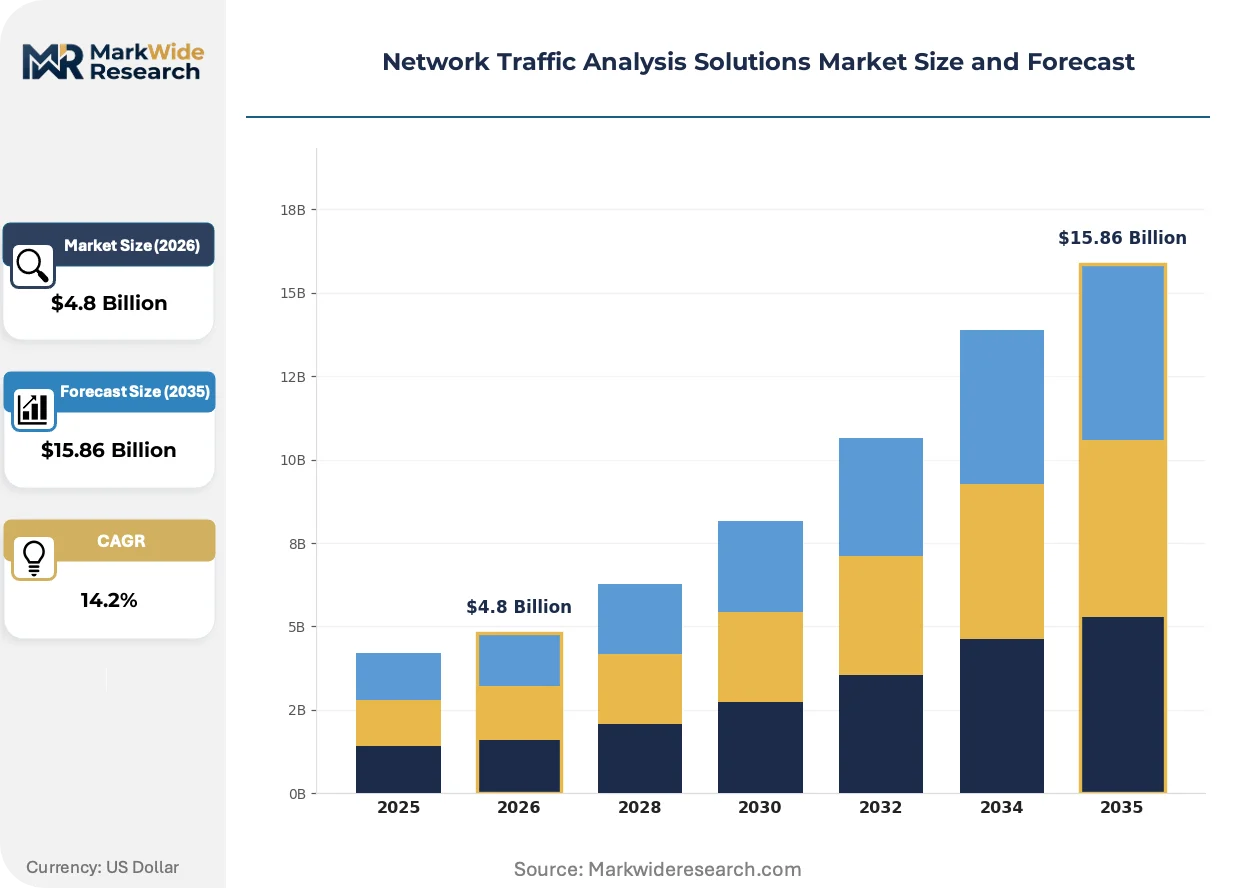
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Packet Analysis, Flow Monitoring, Network Performance, Threat Detection Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Telecommunications, BFSI, Government, Healthcare Feature: Real-Time Monitoring, Anomaly Detection, Reporting & Analytics, Alerts Generation |
| Companies Covered | Cisco Systems, NETSCOUT Systems, Broadcom, Palo Alto Networks, SolarWinds Worldwide, ExtraHop Networks, Darktrace, Arista Networks, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Traffic Analysis Solutions Market Strategic Shifts
Traffic analysis architectures are pivoting from standalone appliances toward embedded edge intelligence, compressing procurement cycles and reshaping vendor competitive moats. Three developments dominate this transition.
Self-learning behavioral algorithms are supplanting signature-dependent detection methods in financial services deployments. These systems detect novel anomalies without prior training data, enabling faster response to zero-day exploits. Board-level scrutiny of ransomware exposure is accelerating this displacement.
The FCC's enhanced reporting obligations for communications service providers following major outages are tightening telemetry retention requirements. Carriers must now maintain granular flow records for extended periods, expanding addressable demand for high-throughput inspection hardware. US-based service providers are prioritizing platforms with native compliance documentation.
Buyers are consolidating vendor relationships around platform providers that control both ingestion and inference layers. This pattern concentrates procurement authority with infrastructure teams rather than standalone security departments. Germany's automotive sector exhibits this concentration most visibly, with conglomerates retrofitting legacy networks through single-source contracts.
Network Traffic Analysis Solutions Market Segmentation
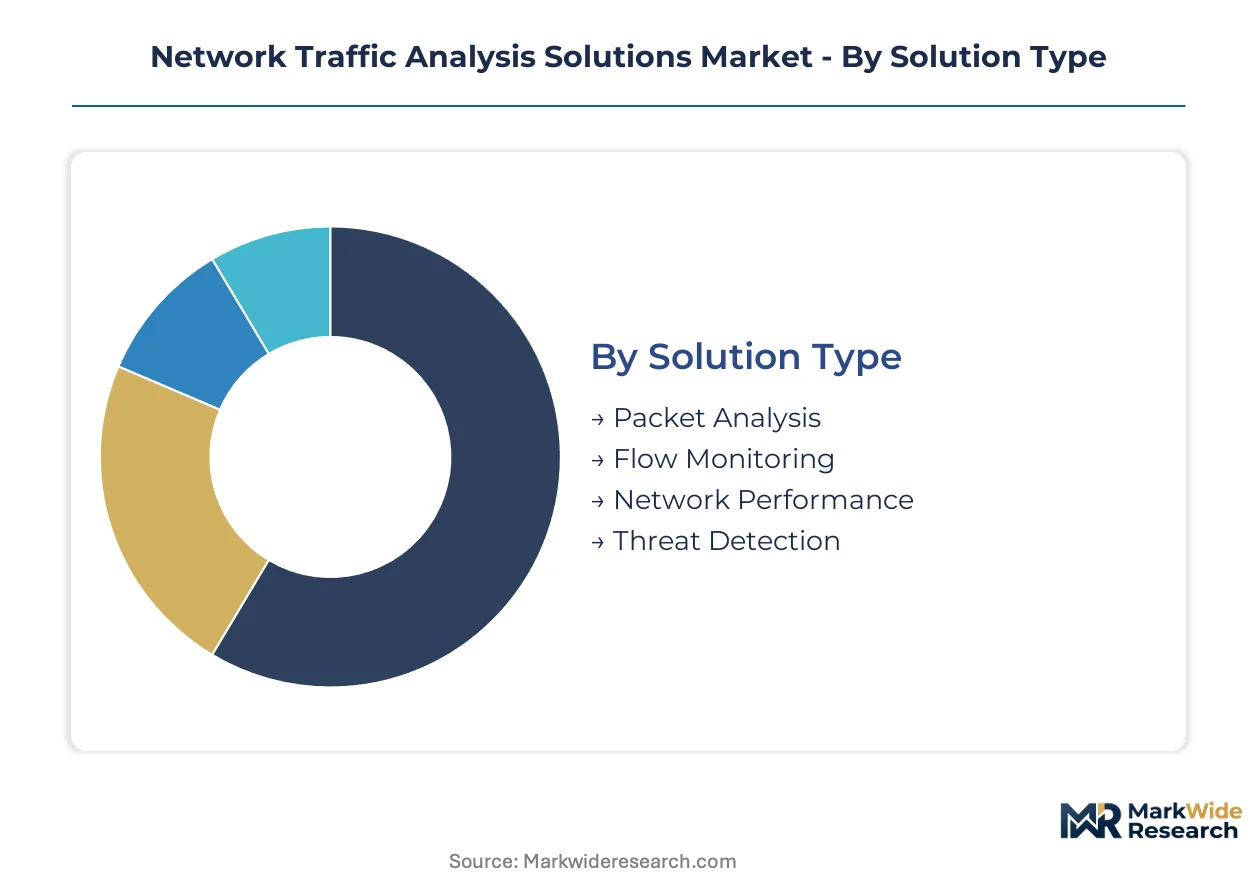
Traffic analysis procurement splits across four structural dimensions that determine architectural trade-offs. Each category carries distinct compliance burdens and performance thresholds that reshape vendor selection criteria.
Solution Type:
EU AI Act explainability mandates and NIS2 incident disclosure windows differentiate procurement requirements across functional categories.
- Packet Analysis:Deep inspection systems decode payload content at line rates up to 400 Gbps, sustaining deterministic latency for carrier-grade deployments. German automotive manufacturers retrofit legacy OT networks with these platforms to expose lateral movement across manufacturing floors.
- Threat Detection:Behavioral engines detect novel anomalies without signature dependencies, accelerating response to zero-day exploits. Financial services firms in Frankfurt and London prioritize these systems for payment corridor protection.
- Flow Monitoring:Aggregated metadata analysis reduces silicon requirements while maintaining visibility across distributed architectures.
- Network Performance:Application-layer optimization modules address east-west visibility gaps in multicloud environments.
Threat Detection handles the majority of throughput; Packet Analysis is the fastest mover on share.
Deployment Model:
Cost tier differentiation separates enterprise capital expenditure commitments from operational expenditure flexibility.
- Managed Service:Providers bundle tier-1 carrier telemetry with proprietary analytics engines, capturing expanding margin pools as Western European enterprises outsource monitoring functions. The FCC's enhanced reporting obligations for US communications providers accelerate demand for compliant telemetry retention.
- Cloud-Based:Native SaaS architectures aggregate telemetry across multicloud sprawl without hardware procurement cycles. GDPR metadata handling constraints increase engineering overhead for European deployments.
- On-Premises:Dedicated appliance stacks satisfy deterministic latency requirements for high-frequency trading infrastructure.
- Hybrid:Split architectures balance sensitive workload isolation with scalable analytics processing.
Managed Service captures the steepest expansion trajectory as labor shortages compress in-house staffing feasibility.
End User:
Application context determines throughput requirements and compliance stringency.
- BFSI:Payment processors and investment banks deploy behavioral analytics for real-time fraud detection across high-velocity transaction streams.
- Telecommunications:Carriers maintain granular flow records under extended retention mandates, expanding demand for high-throughput inspection hardware.
- Government:Critical infrastructure operators face mandatory disclosure timelines that pull automated reporting workflows.
- Healthcare:HIPAA audit trail requirements constrain traffic metadata handling architectures.
BFSI concentrates procurement volume; Telecommunications is expanding most quickly on regulatory pressure.
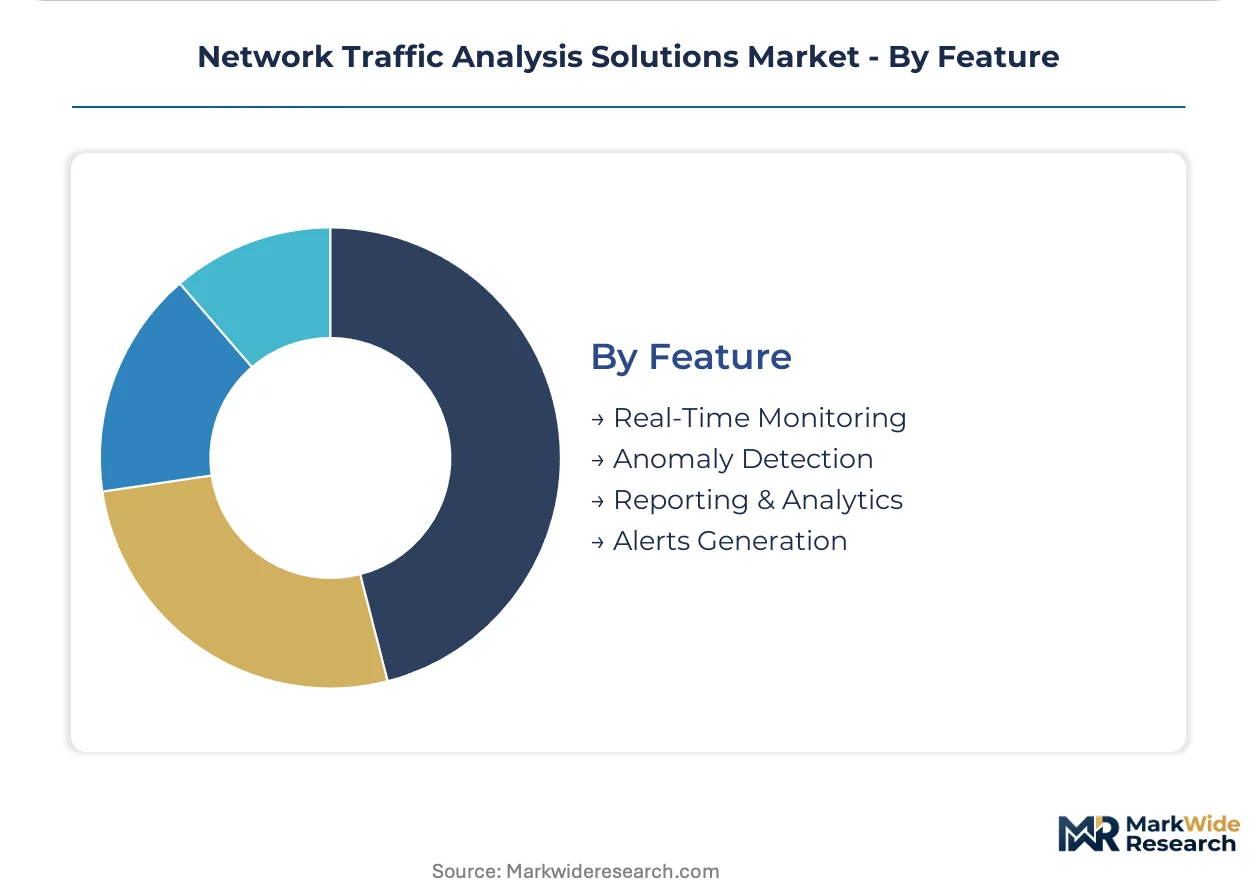
Feature:
Maturity gradients separate baseline functionality from premium intelligence layers.
- Real-Time Monitoring:Millisecond-level decisioning at carrier scale demands specialized firmware optimization that scarce developers struggle to deliver.
- Anomaly Detection:Self-learning algorithms face risk committee scrutiny requiring deterministic explainability for financial services deployments.
- Alerts Generation:Automated escalation workflows compress mean-time-to-response for security operations centers.
- Reporting & Analytics:Native compliance documentation capabilities satisfy FCC and EU directive audit requirements.
Real-Time Monitoring anchors platform pricing; Anomaly Detection is climbing the fastest on zero-day exposure concerns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive manufacturers deploy unified visibility layers for legacy OT retrofitting, while US financial services firms prioritize behavioral analytics for payment corridor protection. This consumption-mix differential reflects sector-specific threat models rather than uniform regional adoption patterns.
United States
Financial services firms in New York and Chicago accelerate behavioral analytics procurement for real-time fraud detection across high-velocity transaction streams. The FCC's enhanced reporting obligations for communications service providers mandate granular flow record retention, expanding demand for high-throughput inspection hardware. Silicon Valley cloud providers drive SaaS-native telemetry aggregation architectures.
Germany
Automotive and industrial conglomerates in Bavaria and Baden-Württemberg retrofit legacy OT networks with unified traffic visibility layers to secure manufacturing floors against lateral movement. The EU AI Act's explainable anomaly detection mandates create baseline procurement requirements for critical infrastructure operators. Frankfurt's financial services sector concentrates behavioral engine deployments for payment corridor protection.
United Kingdom
London-based investment banks and payment processors prioritize self-learning algorithms for zero-day exploit response without signature dependencies. GDPR metadata handling constraints increase engineering overhead for traffic audit trail architectures. The City of London's cybersecurity clusters concentrate managed service outsourcing as labor shortages compress in-house staffing feasibility.
France
Parisian critical infrastructure operators face NIS2 Directive mandatory disclosure timelines that pull automated reporting workflow platforms. The CNIL enforces granular data handling audit trails for traffic metadata, limiting feature velocity for domestic deployments. Île-de-France's telecommunications hubs sustain carrier-scale throughput demand for specialized deep packet inspection silicon.
Japan
Tokyo's financial institutions and Osaka's manufacturing conglomerates deploy millisecond-latency monitoring for high-frequency trading and industrial control systems. METI guidelines shape OT-IT convergence architectures across operational technology networks. The Kanto region's cloud service providers aggregate multicloud telemetry to address east-west visibility gaps.
Network Traffic Analysis Solutions Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with switching infrastructure vendors embedding analytics at the network edge and standalone security vendors competing on behavioral detection depth. The market structure compresses procurement cycles as infrastructure teams consolidate vendor relationships around platform providers controlling both ingestion and inference layers. Three archetypes dominate: entrenched networking vendors with embedded intelligence, carrier-scale deep packet inspection specialists, and self-learning behavioral analytics pure-plays. Competitive moves concentrate on strategic partnerships for telemetry bundling and portfolio diversification into managed service delivery.
Within the integrated networking tier, Cisco Systems and Arista Networks exemplify vendors leveraging entrenched switching footprints to embed analytics directly at the network edge. NETSCOUT Systems anchors the carrier-scale inspection segment through hardware sustaining deterministic latency at high throughput. Darktrace occupies a position representing the behavioral analytics pure-play archetype, competing with signature-dependent alternatives via self-learning algorithms that detect novel anomalies without prior training data.
| Leading Market Players |
|---|
| Cisco Systems |
| NETSCOUT Systems |
| Broadcom |
| Palo Alto Networks |
| SolarWinds Worldwide |
| ExtraHop Networks |
| Darktrace |
| Arista Networks |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Silicon substitution in deep packet inspection hardware is redrawing procurement economics as merchant silicon displaces custom ASICs, compressing lead times for carrier-grade equipment while eroding the pricing power of legacy semiconductor fabricators in Taiwan and South Korea.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement for carrier-scale deployments, though spot purchasing persists for mid-market SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels reflects throughput capacity and explainability certification tiers demanded by EU AI Act compliance. Price compression in the standard tier intensifies as signature-dependent vendors bundle basic analytics with switching hardware. Financial services firms in Frankfurt exhibit lowest price sensitivity due to regulatory penalty exposure, while mid-market manufacturers in Bavaria prioritize economy tiers with managed service overlays.
Supply Chain Analysis
Strategic stockpiling of specialized inspection silicon has replaced just-in-time procurement among tier-1 carriers facing extended lead times from Taiwan, South Korea, and Israel. Deep packet inspection hardware draws from merchant silicon foundries and custom ASIC designers, with FPGA modules serving as bridging components during supply gaps. Single-source vulnerability concentrates in 400 Gbps-capable semiconductor fabricators, exposing carriers to allocation rationing during demand surges. Distribution runs through direct OEM relationships for enterprise accounts and tier-1 systems integrators for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as multicloud sprawl fragments telemetry aggregation demand across specialized visibility layers rather than consolidated platforms.
For Market Incumbents: Fortify embedded analytics positions by deepening switching firmware integration and acquiring behavioral algorithm specialists before pure-plays scale carrier relationships. Cisco Systems and Arista Networks face displacement risk from self-learning entrants in financial services verticals. Priority investment rests on explainable AI documentation tools that satisfy EU AI Act audit requirements. For New Entrants and Emerging Players: Managed service bundling gaps in mid-market German manufacturing present the most penetrable white-space, where automotive conglomerates seek outsourced OT-IT convergence monitoring without capital-intensive appliance procurement. A channel partnership strategy with regional systems integrators in Baden-Württemberg accelerates footprint establishment against direct sales-dependent incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors behavioral analytics pure-plays with carrier-scale validation and managed service delivery capabilities. Long-term viability hinges on algorithmic differentiation surviving signature-dependent vendor price wars. Watch NIS2 Directive enforcement intensity as inflection indicator for automated reporting workflow demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding analytics into switching firmware compresses procurement cycles for infrastructure teams. |
| Managed Service Launch | Bundling tier-1 carrier telemetry with proprietary engines captures outsourced monitoring margin pools. |
| Acquisition of Behavioral Analytics Firm | Self-learning algorithms differentiate against signature-dependent rivals in financial services procurement. |
| Geographic Expansion into German Manufacturing | OT-IT convergence demand in Bavaria and Baden-Württemberg outpaces incumbent coverage. |
| Regulatory Compliance Certification | EU AI Act explainability documentation opens critical infrastructure operator procurement channels. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with CISOs at financial services firms, infrastructure architects at German automotive manufacturers, procurement leads at tier-1 telecommunications carriers, and managed service delivery heads. Secondary validation drew from FCC enforcement filings, EU NIS2 Directive implementation guidance, SEC 10-K disclosures from networking vendors, and hyperscaler capex telemetry. Bottom-up deployment estimates triangulated against top-down market sizing across solution type, deployment model, and end-user vertical dimensions.
Across the analysis window, forecasts modeled segmentation by solution type, deployment model, end-user vertical, and feature maturity tier. CAGRs derived from installation base growth rates, replacement cycle compression, and regulatory mandate timing. Industry-specific inputs included carrier-scale throughput upgrade schedules, EU AI Act enforcement phase-in patterns, and cybersecurity analyst labor pool contraction trajectories in Western Europe and North America.
Forecasts assume regulatory continuity in EU AI Act and NIS2 Directive implementation; material policy shifts would require re-modeling compliance-driven procurement acceleration. Revision becomes warranted when behavioral algorithm validation standards cross thresholds that disqualify self-learning systems from financial services deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Mobile Application Security Market
Cybersecurity
SSL VPN Market
Cybersecurity
Container-based Firewall Market
Cybersecurity
Australia Cybersecurity Market
Cybersecurity
Spain Cybersecurity Market
Cybersecurity
Europe Software Defined Perimeter Market
Cybersecurity
SOC As a Service Market
Cybersecurity
Application-Level Encryption Market
Cybersecurity
Poland Cybersecurity Market
Cybersecurity
Homomorphic Encryption Market
Cybersecurity
United States Cybersecurity Market
Cybersecurity
Corporate Web Security Market
Cybersecurity
Asia-Pacific Cloud DLP Market
Cybersecurity
Network Detection and Response Market
Cybersecurity
Bangladesh Cybersecurity Market
Cybersecurity
LAMEA Deception Technology Market