
 Hong Kong Cybersecurity Market | 2026-2036
Hong Kong Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Cybersecurity Market Foresight
Hong Kong's Personal Data (Privacy) Ordinance amendment regime is consolidating compliance-driven procurement across the territory's regulated sectors. Trend Micro leverages its threat intelligence footprint to anchor enterprise endpoint protection in local financial services. Palo Alto Networks competes through cloud-native security platforms designed for hybrid infrastructure. Ensign InfoSecurity dominates incident response and managed security services with deep presence in Hong Kong's critical infrastructure operators.
Cybersecurity encompasses hardware, software, and service layers engineered to protect networks, endpoints, and data assets from unauthorized access, disruption, or exfiltration, typically integrating encryption protocols, behavioral analytics, and automated threat detection operating at sub-millisecond response thresholds. Its primary commercial purpose is risk mitigation and operational continuity for organizations handling sensitive information or maintaining interconnected digital infrastructure. Managed security services and SIEM solutions capture expanding margin pools as organizations outsource monitoring complexity. Cloud-based deployment shows the fastest trajectory as Hong Kong's financial institutions migrate core systems. On-premises firewall and intrusion detection segments retain steady demand from government agencies with data sovereignty requirements.
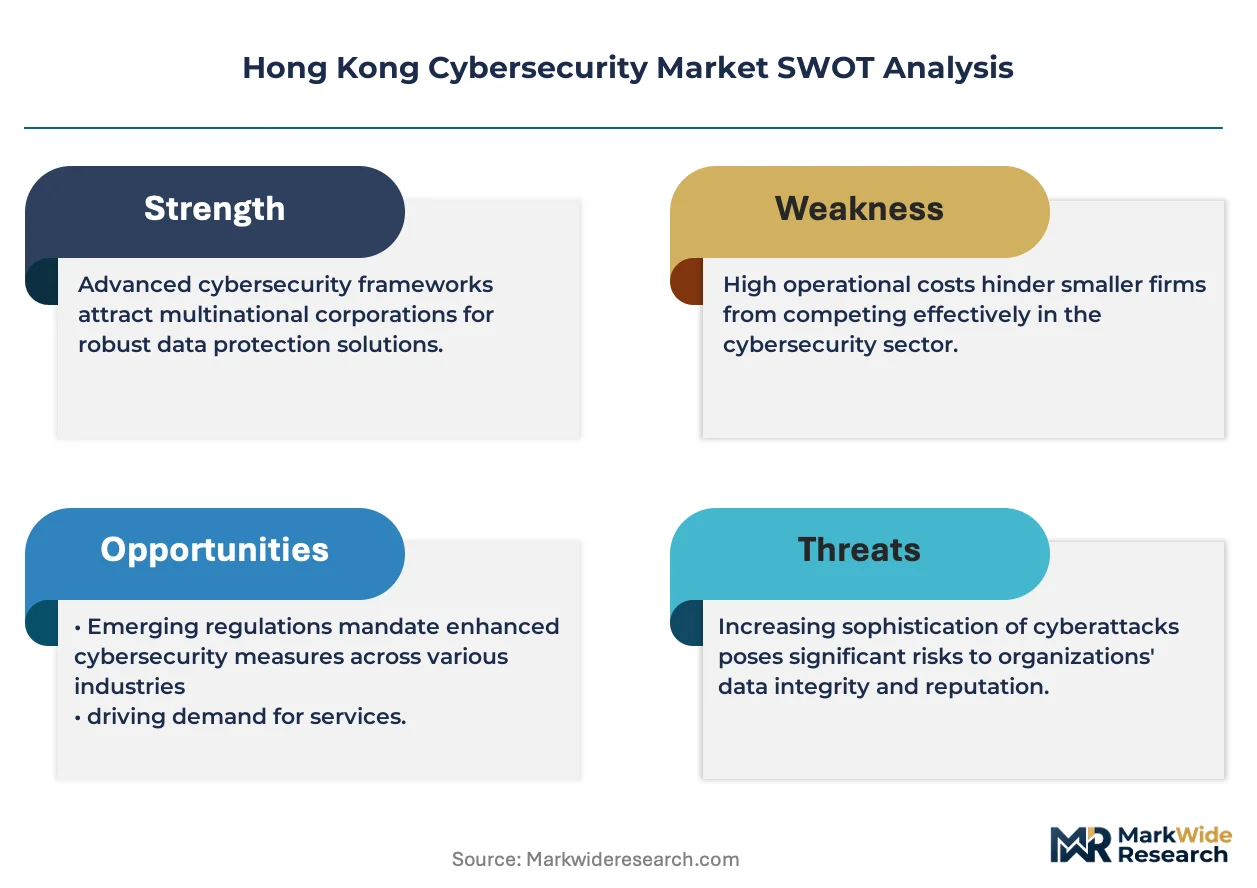
The Office of the Privacy Commissioner for Personal Data enforces compliance timelines that accelerate enterprise security refresh cycles, while the Hong Kong Monetary Authority's Cybersecurity Fortification Initiative mandates baseline controls across all authorized institutions. The National Security Law adds data localization and access-log retention requirements that reshape product specifications for vendors serving public-sector buyers. Stakeholders must monitor regulatory divergence between Hong Kong's evolving framework and mainland China's cybersecurity standards to anticipate certification and cross-border data flow requirements.
Market Dynamics
Financial institutions in Hong Kong are consolidating security procurement around cloud-native platforms as the Hong Kong Monetary Authority's Cybersecurity Fortification Initiative tightens baseline control mandates. This regulatory pressure is compressing vendor selection cycles and elevating managed service providers with local incident response capabilities.
Growth Catalysts
- Cybersecurity Fortification Initiative:The Hong Kong Monetary Authority mandates baseline security controls across all authorized institutions, forcing systematic procurement of endpoint detection and SIEM infrastructure.
- Cloud migration in banking:Hong Kong's financial institutions are relocating core systems to hybrid cloud environments, generating demand for cloud-native security platforms and zero-trust architecture.
- Personal Data Ordinance amendments:Enhanced penalties and breach notification requirements under Hong Kong's privacy law accelerate enterprise security refresh investments.
Market Restraints
- Cybersecurity talent scarcity:Hong Kong faces acute shortages of certified security architects and incident responders, inflating personnel costs for in-house security operations.
- Data sovereignty requirements:The National Security Law imposes data localization and access-log retention obligations that complicate cross-border security tool deployment.
- Legacy infrastructure debt:Many Hong Kong enterprises maintain decades-old core banking systems that resist integration with modern API-driven security platforms.
Strategic Opportunities
- Managed detection and response:Mid-market firms in Hong Kong's professional services sector remain underserved by 24/7 security monitoring, creating white space for localized MDR providers.
- Regulatory divergence arbitrage:Vendors capable of bridging Hong Kong's privacy framework with mainland China's cybersecurity standards capture procurement from multinationals operating across both jurisdictions.
- Quantum-safe cryptography:The Hong Kong Applied Science and Technology Research Institute's pilot programs create early-mover positioning for post-quantum encryption vendors targeting financial messaging infrastructure.
Industry Challenges
- Multi-cloud security orchestration:Hong Kong enterprises deploying across AWS, Azure, and Alibaba Cloud struggle with unified policy enforcement and consistent threat visibility.
- Third-party risk attestation:Banks must verify security postures of fintech partners under HKMA guidelines, but standardized assessment frameworks remain immature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Cybersecurity Market |
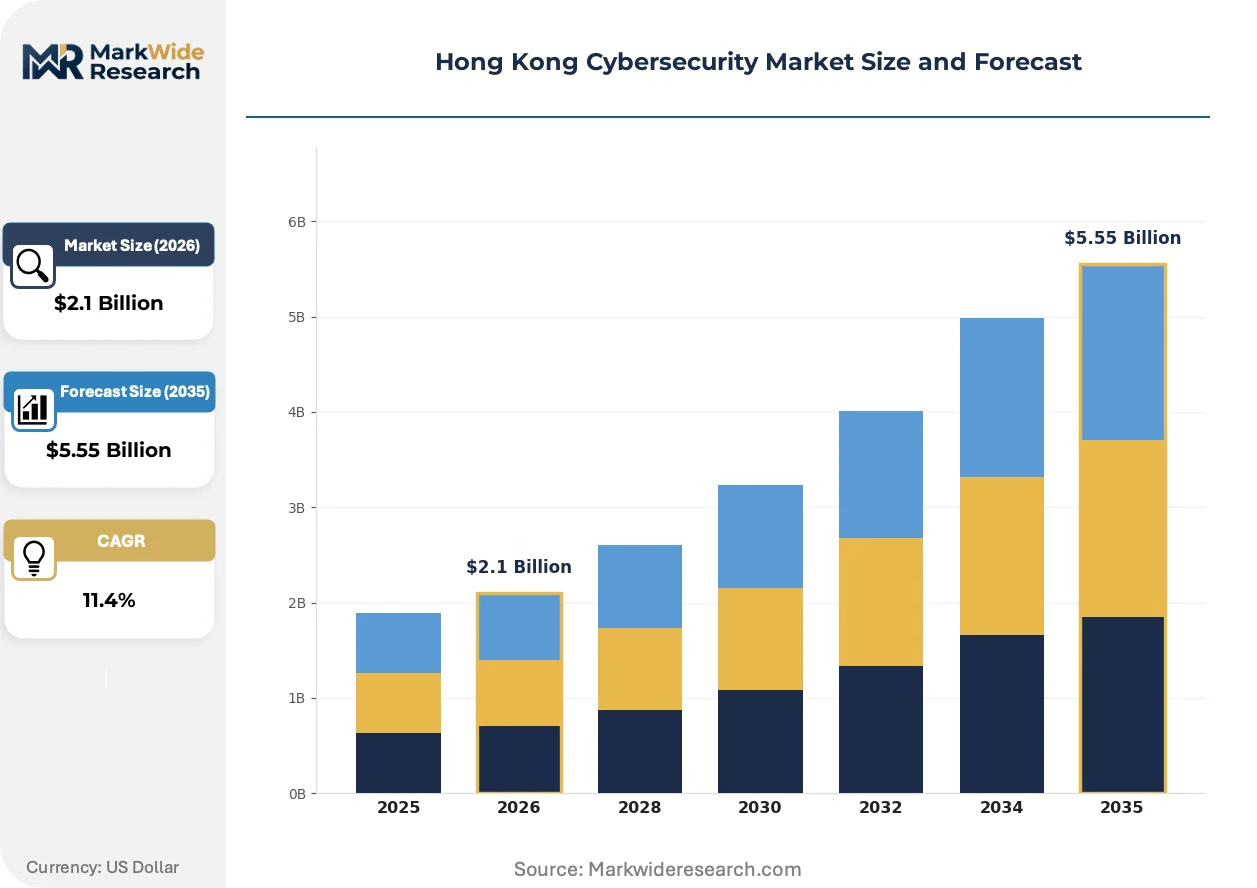
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Firewall, Intrusion Detection System, Antivirus Software, SIEM Service Type: Consulting, Compliance Management, Managed Security Services, Incident Response End User: Financial Institutions, Healthcare Providers, Retail Chains, Government Agencies Deployment: On-premises, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Trend Micro, Cisco Systems, Palo Alto Networks, Nexusguard, Edvance International Holdings Limited, Fortinet, IBM Corporation, Ensign InfoSecurity, Check Point Software Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Cybersecurity Market Shifts & Advancements
Security operations in Hong Kong are absorbing artificial intelligence at the detection layer while regulatory pressure compresses procurement cycles. These forces are reshaping how financial institutions evaluate vendors and structure security spending.
Extended detection and response platforms are absorbing behavioral analytics and automated remediation workflows into unified agent architectures. Tier-one banks in Hong Kong are deploying these tools to reduce mean-time-to-response below 15 minutes. The technology is absorbing budget previously fragmented across point solutions for endpoint, network, and identity security.
The National Security Law and Personal Data Ordinance amendments are converging to mandate granular access logging and data classification across critical infrastructure operators. Financial institutions must now demonstrate audit trails spanning three years with real-time retrieval capabilities. Hong Kong's virtual banks and digital insurers face the steepest compliance ramps given their cloud-native operating models.
Enterprise buyers are consolidating vendor relationships to reduce integration complexity and streamline incident response accountability. Hong Kong's family offices and asset managers are shifting from best-of-breed tool procurement to platform subscriptions with embedded managed services. This concentration is most visible among mid-cap financial institutions seeking to match the security posture of global systemically important banks without comparable internal resources.
Hong Kong Cybersecurity Market Segmentation
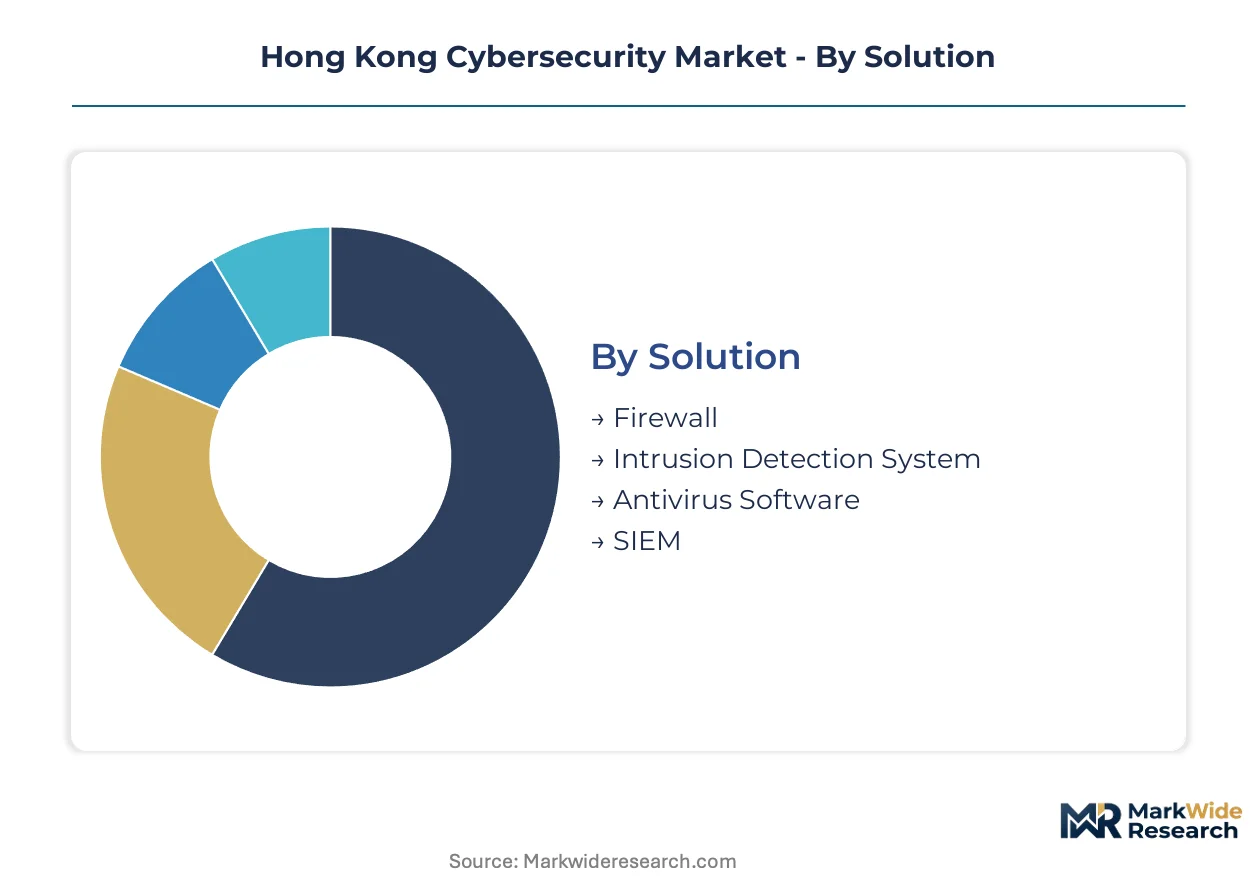
Hong Kong's cybersecurity procurement patterns diverge sharply across solution architectures and operational models. Regulatory mandates from the Hong Kong Monetary Authority and the Office of the Privacy Commissioner for Personal Data create distinct demand profiles that reshape how vendors structure product portfolios for this territory.
Solution:
Technical specifications define competitive positioning in Hong Kong's solution layer, with performance thresholds and integration capabilities separating procurement tiers.
- Firewall:Next-generation firewalls with deep packet inspection and application-layer control dominate Hong Kong banking infrastructure. Financial institutions mandate sub-millisecond latency and TLS decryption at scale for trading floor environments. Procurement concentrates among authorized institutions facing HKMA Cybersecurity Fortification Initiative deadlines.
- SIEM:Security information and event management platforms aggregate log streams across hybrid infrastructure with real-time correlation engines. Hong Kong's virtual banks and digital insurers deploy cloud-native SIEM to satisfy three-year audit trail requirements under amended Personal Data Ordinance provisions. Compliance-driven refresh cycles accelerate replacement of legacy log management tools.
- Intrusion Detection System:Network-based and host-based variants monitor traffic signatures and behavioral anomalies for critical infrastructure operators.
- Antivirus Software:Endpoint protection platforms with behavioral heuristics defend against commodity malware and targeted phishing campaigns.
Mature deployment sits with Firewall solutions anchoring perimeter defense in traditional banking. Newer deployment is concentrated in SIEM platforms absorbing budget from fragmented point tools.
Service Type:
Cost tier differentiation separates advisory engagements from retained operational support, with pricing reflecting personnel certification levels and response time commitments.
- Managed Security Services:24/7 security operations centers deliver continuous monitoring, threat hunting, and automated remediation for mid-market firms lacking internal security teams. Hong Kong's professional services sector and family offices outsource SOC functions to local providers with Cantonese-English bilingual analysts. Talent scarcity inflates in-house security operations costs, driving demand for predictable subscription pricing.
- Incident Response:Retainer-based emergency services provide breach containment, forensic investigation, and regulatory notification support within mandated timelines. Hong Kong's critical infrastructure operators and virtual banks maintain active retainers given stringent breach disclosure windows under privacy law amendments. Response capabilities with local presence command premium positioning.
- Consulting:Advisory engagements cover security architecture design, risk assessments, and compliance gap analysis for enterprise transformation programs.
- Compliance Management:Sustained engagements map control frameworks to HKMA, PDPO, and National Security Law requirements with audit documentation support.
Advisory-heavy procurement concentrates in Consulting for initial transformation design. Operational scale is expanding most quickly in Managed Security Services as firms abandon build-vs-buy calculations.
End User:
Application context dictates security architecture complexity, with regulated sectors facing steeper compliance ramps than commercial peers.
- Financial Institutions:Tier-one banks, virtual banks, insurers, and asset managers deploy zero-trust architectures with microsegmentation for trading systems. Hong Kong's status as a global financial center attracts advanced persistent threat campaigns targeting SWIFT infrastructure and wealth management platforms. HKMA mandates create synchronized procurement waves across the authorized institution population.
- Government Agencies:Public-sector buyers enforce data sovereignty with on-premises deployment and access-log retention specifications shaped by National Security Law requirements. Smart city initiatives and digital identity programs expand attack surfaces requiring specialized hardening. Procurement prioritizes vendors with local data center presence and government security clearances.
- Healthcare Providers:Hospital networks and digital health platforms protect patient records with encryption and access controls aligned to privacy law amendments.
- Retail Chains:Point-of-sale systems and e-commerce platforms face payment card industry compliance alongside territorial data protection obligations.
Volume concentration rests with Financial Institutions driving premium solution adoption. Steepest compliance trajectory is visible in Government Agencies navigating security law implementation.
Deployment:
Customer maturity and data sensitivity determine infrastructure location, with hybrid architectures bridging legacy constraints and cloud agility.
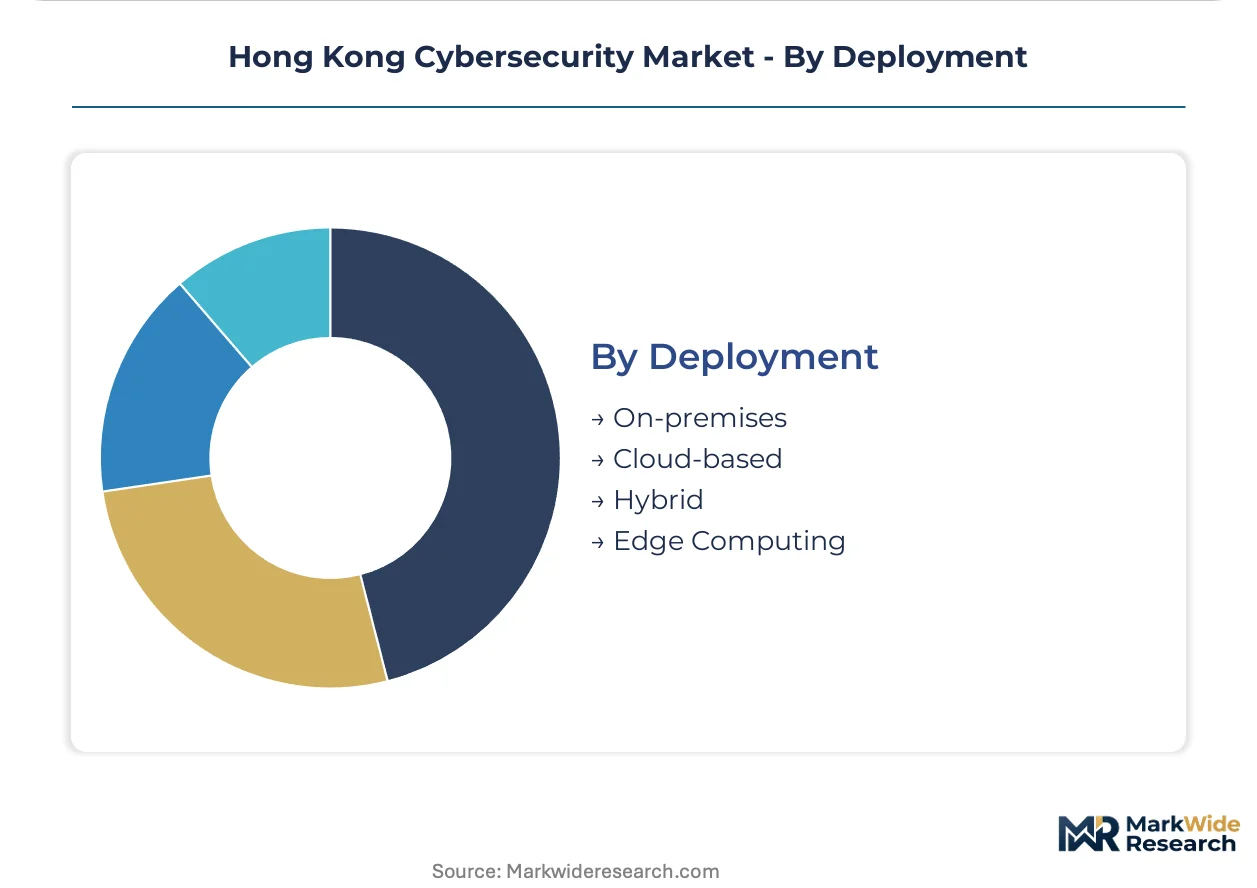
- Cloud-based:Native security controls and third-party cloud workload protection platforms secure AWS, Azure, and Alibaba Cloud deployments. Hong Kong's virtual banks and fintech startups build cloud-first with embedded security automation from inception. Multi-cloud complexity drives demand for unified policy orchestration across provider environments.
- Hybrid:Split architectures maintain sensitive workloads on-premises while bursting transactional systems to cloud infrastructure. Traditional banks in Hong Kong adopt hybrid models to preserve core banking system investments while modernizing customer-facing channels. Integration challenges between legacy and cloud-native security tools elevate platform consolidation priorities.
- On-premises:Air-gapped or data center-hosted solutions satisfy sovereignty requirements for government and critical infrastructure operators.
- Edge Computing:Distributed security enforcement protects IoT devices and branch office infrastructure with localized processing.
Established infrastructure favors On-premises deployment in government and legacy banking. Gaining share fastest is Cloud-based deployment among digital-native financial entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hong Kong's cybersecurity production concentrates in managed security services and cloud-native platforms, while consumption spreads across financial institutions, government agencies, and professional services firms responding to tightening regulatory mandates.
Hong Kong Island
Central's banking district drives premium cybersecurity procurement as tier-one financial institutions deploy zero-trust architectures. The Hong Kong Monetary Authority's Cybersecurity Fortification Initiative mandates baseline controls across authorized institutions headquartered here. Investment banks and asset managers in Admiralty and Wan Chai maintain active incident response retainers.
Kowloon
Tsim Sha Tsui's fintech cluster generates demand for cloud workload protection as virtual banks build security automation from inception. The Office of the Privacy Commissioner for Personal Data enforces breach notification timelines that accelerate security refresh investments. Cyberport and adjacent districts host managed security service providers serving mid-market professional services firms.
New Territories
Data center concentration in Tseung Kwan O and Sha Tin anchors on-premises and hybrid deployment for operators with data sovereignty obligations. The National Security Law imposes access-log retention requirements that reshape specifications for government and critical infrastructure buyers. Smart city initiatives in these districts expand attack surfaces requiring specialized hardening.
Greater Bay Area Integration Zone
Cross-border financial institutions operating between Hong Kong and mainland China face dual compliance frameworks. Regulatory divergence between Hong Kong's privacy ordinance and China's cybersecurity standards creates procurement complexity for multinationals. Shenzhen-adjacent operations demand vendors capable of bridging both jurisdictions.
Hong Kong Cybersecurity Market Competitive Landscape
The competitive structure tilts toward platform consolidation as financial institutions reduce vendor fragmentation. Tier-one banks favor integrated security suites over point solutions, compressing selection cycles. Two strategic archetypes dominate: multinational platform vendors with cloud-native portfolios, and regional specialists with localized incident response capabilities. Competitive moves center on managed service bundling and compliance certification alignment with HKMA and National Security Law requirements.
Among platform-focused vendors, Trend Micro and Palo Alto Networks exemplify the multinational archetype with threat intelligence and cloud-native positioning. Ensign InfoSecurity anchors the regional specialist tier with deep presence in critical infrastructure incident response. These three occupy positions across the procurement spectrum from enterprise endpoint protection through managed detection and response.
| Leading Market Players |
|---|
| Trend Micro |
| Cisco Systems |
| Palo Alto Networks |
| Nexusguard |
| Edvance International Holdings Limited |
| Fortinet |
| IBM Corporation |
| Ensign InfoSecurity |
| Check Point Software Technologies |
| Others |
Supply & Pricing Matrix
Global semiconductor price indices and cloud infrastructure cost benchmarks cascade through Hong Kong's cybersecurity supply chain, compressing margins for hardware-dependent vendors while elevating subscription-based software pricing tiers that bundle talent-scarce managed services.
Pricing Analysis
Outcome-based pricing tied to mean-time-to-response guarantees anchors premium tiers in Hong Kong's cybersecurity market. Three-tier pricing structure across premium, standard, and economy levels separates global platform vendors with local SOC presence from regional resellers and commodity tool distributors. Pricing pressure stems from talent scarcity inflating managed service delivery costs, particularly for Cantonese-English bilingual analysts. Mid-market professional services firms exhibit highest price sensitivity, while tier-one banks prioritize response-time SLAs over unit cost.
Supply Chain Analysis
Freight cost volatility and data center equipment lead times complicate hardware procurement for Hong Kong's on-premises security deployments. Supply concentrates in Taiwan for advanced semiconductors, mainland China for server assembly, and Singapore for regional distribution hubs. Component dependencies span specialized ASICs for deep packet inspection, encryption accelerators, and high-throughput network interface cards. Single-source vulnerability in next-generation firewall chipsets elevates procurement risk. Distribution runs through authorized value-added resellers with HKMA compliance certification and direct enterprise sales teams for large financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong's cybersecurity market represents a consolidation play as regulatory compliance timelines compress vendor selection cycles and force sub-scale competitors into exit or acquisition.
For Market Incumbents: Deploy threat intelligence integration as the primary lever to deepen platform stickiness among tier-one banks facing HKMA Cybersecurity Fortification Initiative deadlines. Acquire Cantonese-speaking incident response teams to defend against Ensign InfoSecurity's regional specialist positioning. Invest in quantum-safe cryptography R&D to capture Hong Kong Applied Science and Technology Research Institute pilot program procurement. For New Entrants and Emerging Players: Enter via managed detection and response services targeting family offices and mid-cap asset managers underserved by 24/7 monitoring. Capture white space in regulatory divergence arbitrage by bridging Hong Kong's Personal Data Ordinance with mainland China's cybersecurity standards for cross-border financial institutions. Pursue channel partnerships with Alibaba Cloud and Tencent Cloud for cloud-native security distribution. For Investors and Strategic Acquirers: The window for entry favors regional managed security service providers with established Hong Kong SOC operations and government security clearances. Long-term viability hinges on regulatory certification moats deepening through National Security Law implementation. Monitor HKMA enforcement action frequency as the inflection signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Security Service Expansion | Captures mid-market firms abandoning in-house SOC build-outs amid talent scarcity. |
| Regulatory Certification Investment | Deepens competitive moats against unlicensed competitors under HKMA and PDPO enforcement. |
| Cloud-Native Platform Integration | Aligns procurement patterns as virtual banks migrate core systems to hybrid infrastructure. |
| Quantum-Safe Cryptography Development | Positions vendors for Hong Kong Applied Science and Technology Research Institute financial messaging pilots. |
| Cross-Border Compliance Bridging | Captures multinational financial institutions navigating divergence between Hong Kong and mainland China standards. |
Research Methodology
Independent corroboration across primary interviews with CISOs at authorized financial institutions, procurement officers at virtual banks, and incident response directors at managed security service providers underwrites the qualitative findings. Secondary validation draws from Hong Kong Monetary Authority circulars, Office of the Privacy Commissioner for Personal Data enforcement notices, and cloud provider capex disclosures. Bottom-up segmentation modeling triangulates against top-down regulatory mandate timelines across solution, service type, end user, and deployment dimensions.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include solution architecture, service tier, regulated versus non-regulated end user, and infrastructure deployment mode. CAGRs derive from regulatory deadline clustering analysis and technology refresh cycle patterns. Forecast inputs incorporate HKMA Cybersecurity Fortification Initiative compliance wave timing and Personal Data Ordinance amendment enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under National Security Law implementation acceleration or mainland China regulatory harmonization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Philippines Cybersecurity Market
Cybersecurity
AI in Cybersecurity Market
Cybersecurity
North America Cyber Security Market
Cybersecurity
South Korea Ransomware Protection Market
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
Education Data Security Market
Cybersecurity
Cyber Security As a Service Market
Cybersecurity
Cloud Security Market
Cybersecurity
Peru Cybersecurity Market
Cybersecurity
Global Database Encryption Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Canada Ransomware Protection Market
Cybersecurity
North America IoT Security Market
Cybersecurity
Penetration Testing Market
Cybersecurity
Data Security Market
Cybersecurity
Wireless Network Security Market