
 Global Sensitive Data Discovery Market | 2026-2036
Global Sensitive Data Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sensitive Data Discovery Market Foresight
Israel's cybersecurity cluster is reconfiguring how discovery vendors architect real-time scanning engines for cloud-native environments. IBM Corporation leverages its Watson governance stack to anchor enterprise deployments across regulated industries. Microsoft Corporation competes through native integration with Azure Purview, embedding discovery into existing cloud workflows. Varonis Systems specializes in file analytics and permissions mapping, sustaining dominance in on-premises data stores.
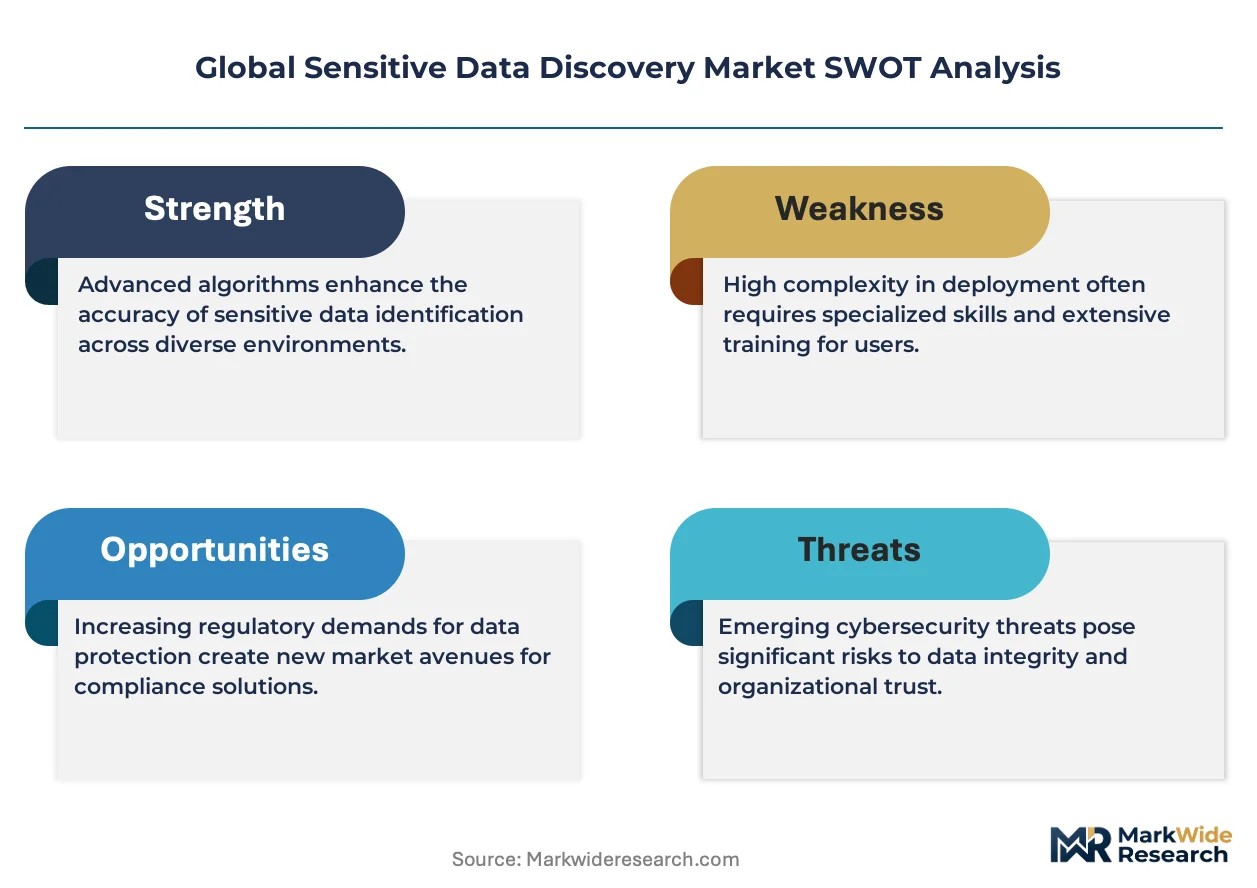
Sensitive data discovery encompasses automated identification, classification, and cataloging of structured and unstructured information assets using pattern matching, machine learning inference, and metadata correlation at petabyte scale. The technology serves to reduce breach exposure, enforce least-privilege access, and satisfy audit requirements for regulated data types. Cloud-based deployment is capturing the fastest expansion as organizations retire legacy data centers and adopt serverless architectures. Regulatory compliance applications command the deepest margin pools given mandatory breach notification laws and sector-specific retention rules. Financial institutions represent the most concentrated end-user segment due to PCI-DSS obligations and cross-border transaction monitoring.
The US SEC and HIPAA frameworks mandate demonstrable data inventory controls, compelling healthcare and capital markets buyers to maintain continuous discovery coverage. EU GDPR and the AI Act impose automated decision-making transparency requirements that feed directly into discovery platform roadmaps. India's DPDP Act and BIS cloud security guidelines are forcing multinational vendors to localize processing infrastructure. Stakeholders must weigh sovereign data requirements against the operational efficiency of centralized SaaS architectures.
Market Dynamics
EU GDPR enforcement and the AI Act are forcing discovery vendors to rebuild classification engines for automated decision-making transparency, compressing product development cycles while expanding addressable compliance spend.
Growth Catalysts
- PCI-DSS mandates:Financial institutions in the United States face continuous audit requirements for payment card data, sustaining procurement of real-time scanning infrastructure.
- India:The DPDP Act and BIS cloud security guidelines are compelling multinational vendors to localize processing nodes, creating captive demand for sovereign-compliant discovery architectures.
- Serverless architectures:Cloud-native workload expansion is collapsing the relevance of agent-based scanning, pulling investment toward API-first discovery platforms.
Market Restraints
- Compute cost volatility:Petabyte-scale pattern matching and ML inference consume GPU and storage resources at unpredictable rates, squeezing margins on fixed-price SaaS contracts.
- Data localization fragmentation:Divergent sovereignty requirements across Germany, India, and the United States prevent centralized infrastructure economics.
- False positive rates:Unstructured file analytics still generate classification noise exceeding 15% in healthcare and legal document repositories, requiring manual remediation.
Strategic Opportunities
- Healthcare:HIPAA breach notification rules and clinical data monetization are opening discovery budgets previously allocated to perimeter security.
- Convergence of data discovery and AI governance:EU AI Act Article 10 requirements for training data documentation are merging two previously separate procurement categories.
- Channel innovation:Managed security service providers are bundling discovery into broader data protection offerings, creating indirect routes to mid-market buyers.
Industry Challenges
- ML engineering scarcity:Vendors compete for talent capable of building low-latency classification models at billion-row scale.
- Legacy ERP integration:SAP and Oracle environments resist API-based discovery, forcing costly custom connector development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sensitive Data Discovery Market |
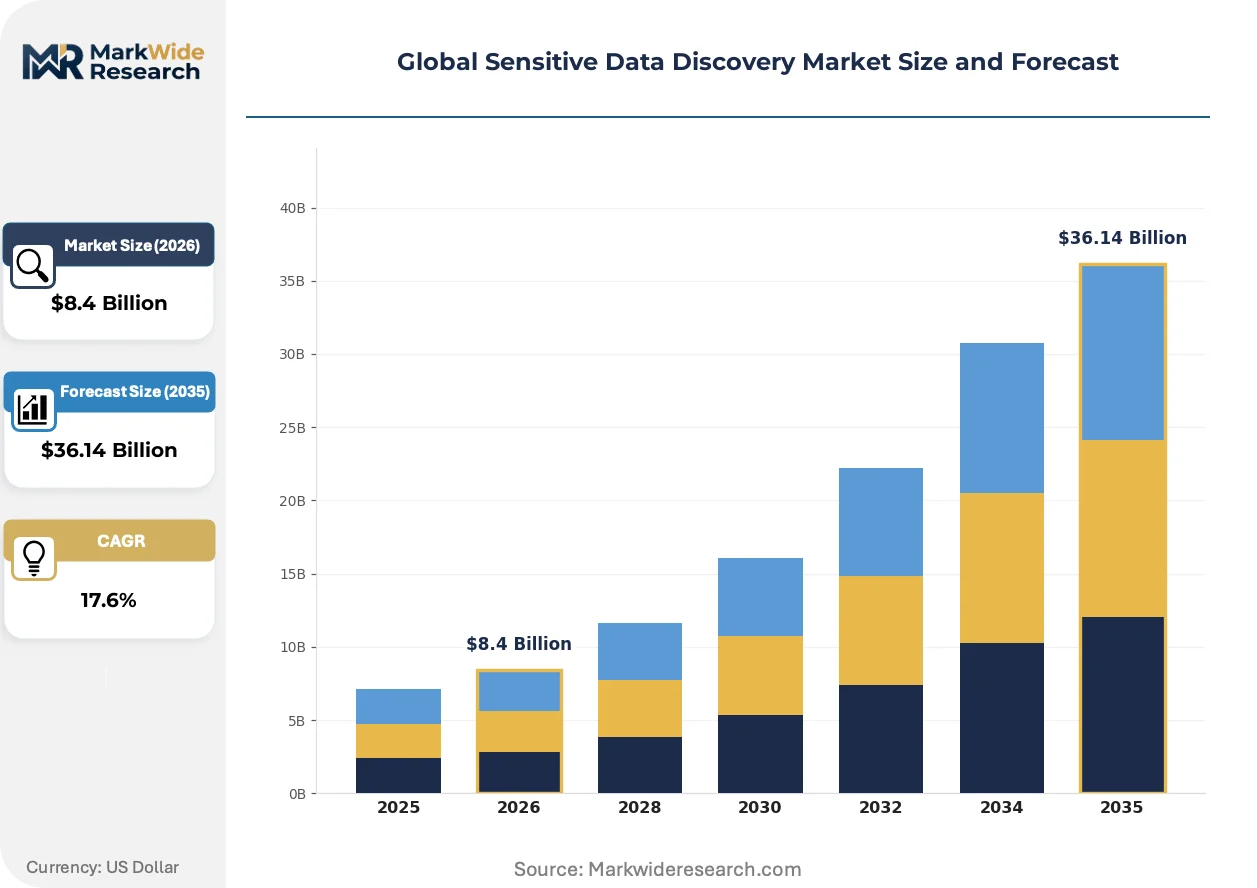
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Classification, Risk Analysis, Access Management, Anomaly Detection, Metadata Management Deployment Mode: On-Premises, Cloud-Based, Hybrid, Managed Services Application: Regulatory Compliance, Insider Threat Detection, Data Privacy, Intellectual Property Protection, Data Governance End User: Financial Institutions, Government Agencies, IT & Telecom, Education Providers, Energy Firms |
| Companies Covered | IBM Corporation, Microsoft Corporation, Varonis Systems, BigID, Amazon Web Services, Oracle Corporation, Proofpoint, Splunk Inc., Trend Micro Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sensitive Data Discovery Market Shifts & Advancements
Discovery architectures are pivoting from batch scanning to continuous real-time inference, driven by regulatory demands for instant breach detection and the operational impossibility of periodic audits in serverless environments.
Neural classification models trained on synthetic data are collapsing the latency gap between pattern-matching and contextual understanding. Financial services buyers in the United States are deploying these engines for real-time payment flow monitoring. The compression of false positive rates from double-digit to sub-5% levels is eliminating the manual review bottleneck that previously capped deployment scale.
The EU AI Act's training data documentation requirements are forcing discovery platforms to embed lineage tracking as a core module. Healthcare and insurance buyers must now demonstrate provenance for algorithmic decision inputs. German and French regulators are auditing these capabilities first, creating a compliance template that other EU member states are adopting verbatim.
Buyers are consolidating vendor relationships around platforms that span discovery, governance, and remediation. Healthcare systems previously procuring point solutions for HIPAA compliance now demand unified coverage of structured EHRs, unstructured clinical notes, and imaging archives. This preference shift favors vendors with native integration into existing cloud data lakes over standalone discovery tools.
Global Sensitive Data Discovery Market Segmentation
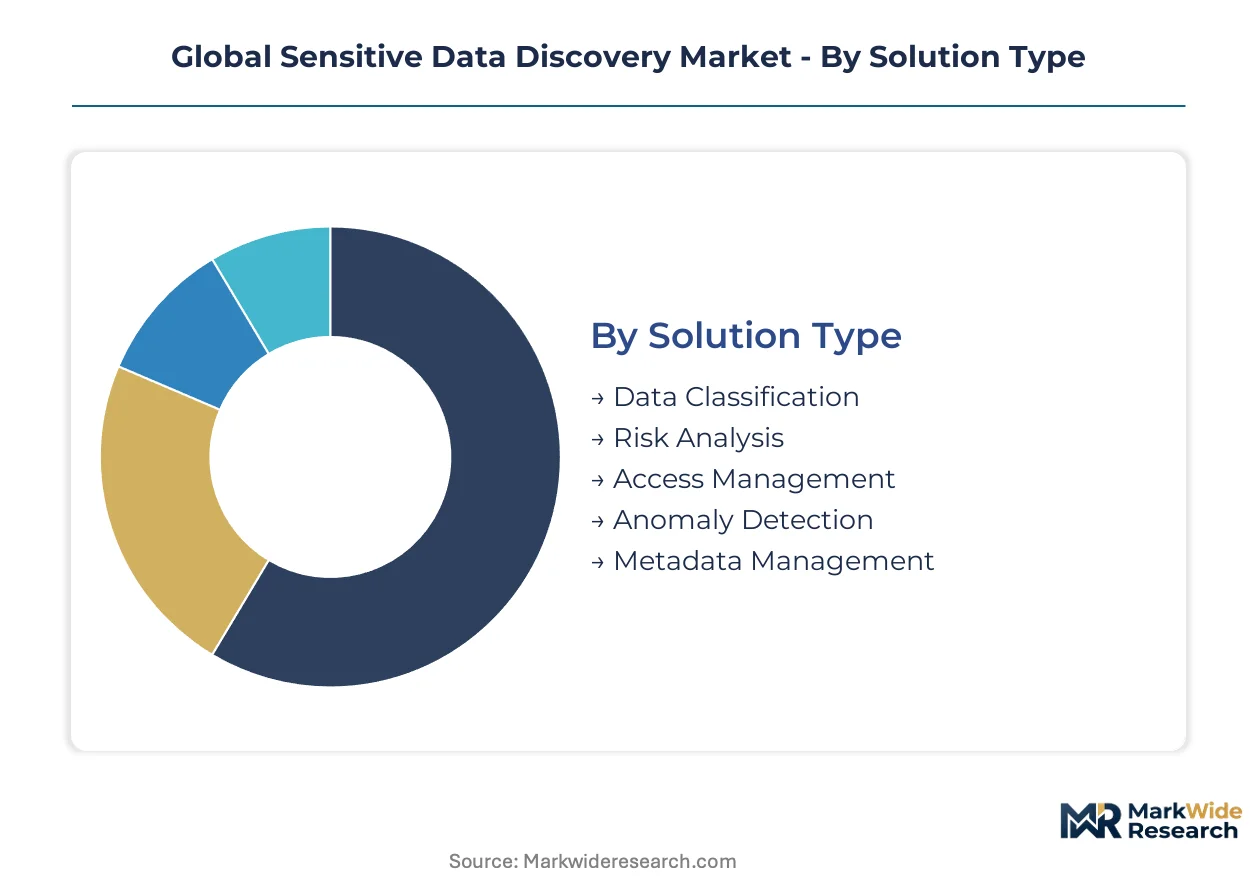
Segmentation in sensitive data discovery reveals how procurement cycles and technical requirements diverge across buyer profiles. Vendors must architect modular platforms that span legacy on-premises estates and serverless cloud workloads without forcing rip-and-replace decisions.
Solution Type:
Data classification engines refresh on 6-12 month cycles as regulatory definitions evolve, while metadata management infrastructure persists for 3-5 years once embedded in enterprise data lakes.
- Data Classification:Pattern-matching and ML inference engines scan structured and unstructured repositories to label regulated data types. Financial institutions in the United States deploy these for PCI-DSS audit trails, with refresh cycles accelerating under SEC cybersecurity disclosure rules.
- Risk Analysis:Quantitative scoring models aggregate exposure metrics across data stores, user permissions, and access patterns. German insurers prioritize these capabilities under GDPR Article 32 security requirements, driving integration with existing GRC platforms.
- Access Management:Permission mapping and least-privilege enforcement tools.
- Anomaly Detection:Behavioral analytics identifying deviations from baseline access patterns.
- Metadata Management:Cataloging engines that maintain lineage and provenance records for audit trails.
Data Classification dominates installed base. Risk Analysis is where expansion concentrates.
Deployment Mode:
Cost tiering separates capital-intensive on-premises builds from operational expenditure cloud models, with hybrid architectures commanding premium pricing for orchestration complexity.
- Cloud-Based:API-first discovery platforms integrate with AWS, Azure, and GCP native services for serverless workload scanning. India's DPDP Act and BIS cloud guidelines are forcing localization of processing nodes, fragmenting vendor infrastructure economics.
- On-Premises:Agent-based scanning appliances for air-gapped environments and legacy data centers. German automotive and industrial buyers retain these for trade secret protection under strict facility access controls.
- Hybrid:Unified control planes spanning private data centers and public cloud tenants.
- Managed Services:Outsourced discovery operations with SLA-guaranteed classification accuracy.
On-Premises retains the deepest revenue per account. Cloud-Based is climbing the fastest.
Application:
Volume concentration tracks regulatory enforcement intensity, with compliance applications absorbing the largest procurement budgets due to mandatory breach notification statutes.
- Regulatory Compliance:Automated inventory and classification for GDPR, HIPAA, PCI-DSS, and sector-specific retention mandates. EU AI Act training data documentation requirements are merging this category with AI governance procurement.
- Insider Threat Detection:User behavior analytics and access pattern monitoring for malicious or negligent data exfiltration. United States healthcare systems deploy these for HIPAA breach prevention, with clinical data monetization expanding budgets.
- Data Privacy:Consent management and subject rights request fulfillment automation.
- Intellectual Property Protection:Trade secret and patent documentation scanning for R&D environments.
- Data Governance:Enterprise-wide policy enforcement and data quality stewardship.
Regulatory Compliance commands margin pools. Insider Threat Detection is gaining share fastest.
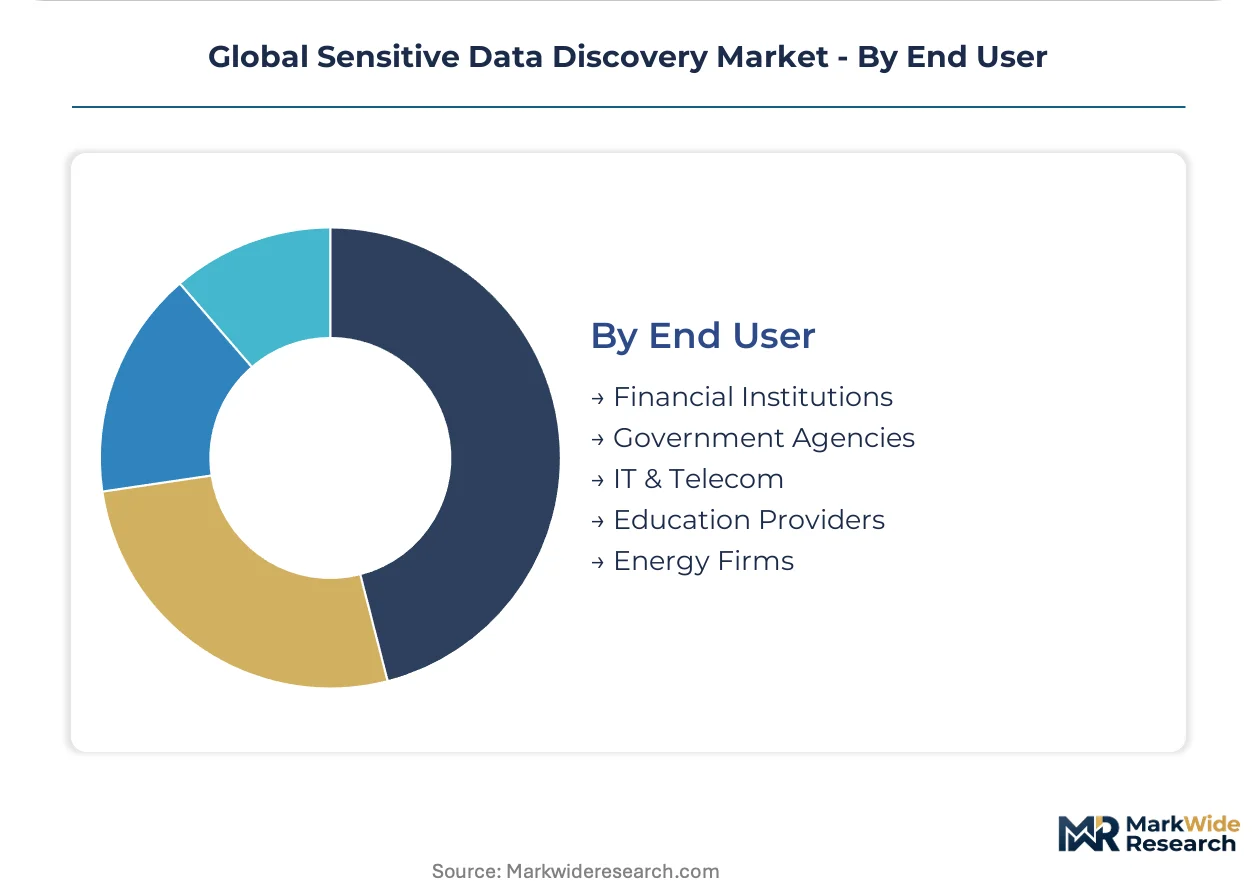
End User:
Customer type determines sales cycle length and integration complexity, with financial institutions demanding the most extensive proof-of-concept phases for real-time transaction monitoring.
- Financial Institutions:Banks, payment processors, and capital markets firms with PCI-DSS and cross-border transaction monitoring obligations. Continuous audit requirements sustain procurement of real-time scanning infrastructure with sub-second latency specifications.
- Government Agencies:National and sub-national entities with classified and citizen data protection mandates. India's DPDP Act implementation is accelerating sovereign-compliant discovery deployments across central and state government data centers.
- IT & Telecom:Service providers managing subscriber and network data across distributed infrastructure.
- Education Providers:Universities and research institutions with FERPA and grant-funded data stewardship requirements.
- Energy Firms:Utilities and oil and gas operators with OT/IT convergence and critical infrastructure protection needs.
Financial Institutions anchor enterprise deal flow. Government Agencies represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Financial institutions in the United States deploy real-time scanning for payment card protection, while German industrial buyers prioritize air-gapped on-premises solutions for trade secret defense. India's sovereign data mandates are forcing infrastructure localization that fragments vendor economics.
United States
Healthcare systems and capital markets firms anchor procurement intensity. SEC cybersecurity disclosure rules and HIPAA breach notification statutes compel continuous discovery coverage. The Boston-Washington corridor concentrates vendor deployment engineering for real-time transaction monitoring.
Germany
Automotive and industrial conglomerates sustain premium pricing for hybrid architectures. GDPR Article 32 security requirements and BSI technical guidelines mandate demonstrable data inventory controls. The Stuttgart-Munich industrial belt hosts the densest concentration of air-gapped discovery deployments.
India
Central and state government data centers are accelerating sovereign-compliant procurement. The DPDP Act and BIS cloud security guidelines force multinational vendors to localize processing nodes. Bengaluru and Hyderabad clusters host captive development centers for API-first discovery platforms.
United Kingdom
Financial services and legal sectors drive demand for unstructured file analytics. FCA operational resilience requirements and post-Brexit data adequacy negotiations complicate cross-border discovery architectures. The City of London maintains the highest density of real-time scanning deployments for transaction surveillance.
Israel
Cybersecurity specialists reconfigure scanning engines for cloud-native environments. Military technology transfer programs and Unit 8200 alumni networks seed venture capital flows into discovery startups. Tel Aviv's cybersecurity cluster produces low-latency classification models deployed by multinational vendors.
Global Sensitive Data Discovery Market Competitive Landscape
Capability concentration sits with specialized classification engine developers; scale advantage sits with cloud platform incumbents with native integration paths. The vendor base stratifies across three tiers: full-stack governance platforms, point-solution specialists, and hyperscale cloud services. Dominant competitive moves include strategic partnerships for connector ecosystems and geographic expansion through localized infrastructure deployment.
Within the full-stack governance tier, IBM Corporation and Microsoft Corporation anchor enterprise deployments across regulated industries. Varonis Systems occupies a specialist position in file analytics and permissions mapping for on-premises estates. These three exemplify the competitive tension between native cloud integration and legacy infrastructure coverage that defines vendor positioning.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Varonis Systems |
| BigID |
| Amazon Web Services |
| Oracle Corporation |
| Proofpoint |
| Splunk Inc. |
| Trend Micro Inc. |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber-optic cable capacity costs directly shape how discovery vendors price real-time scanning tiers, with latency-sensitive financial services buyers absorbing premium markups while mid-market healthcare adopters face compressed entry-level SaaS rates.
Pricing Analysis
Long-term enterprise offtake contracts dominate procurement above five thousand seats, while project-based engagements capture initial pilot deployments. Three-tier pricing structure across premium, standard, and economy levels separates GPU-accelerated real-time inference from batch-processed classification and basic pattern-matching tiers. Cost compression in the economy tier is intensifying because hyperscaler cloud marketplaces commoditize baseline discovery APIs. Healthcare systems demonstrate highest price sensitivity due to constrained IT budgets, whereas capital markets firms prioritize sub-second latency over per-seat cost.
Supply Chain Analysis
US Commerce Department export controls on advanced GPU clusters limit how Israeli and Indian engineering centers access training infrastructure for neural classification models. GPU silicon supply concentrates in Taiwan, South Korea, and the United States, while specialized inference hardware fabrication rests on TSMC's advanced nodes. Supply chain risk centers on single-source vulnerability for sub-5 nanometer foundry capacity. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with managed security service providers capturing growing indirect share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough driven by post-pandemic cloud migration completion and entering expansion as regulatory enforcement tightens discovery mandates.
For Market Incumbents: Pre-empt margin erosion from hyperscaler-native discovery tools by deepening API ecosystem partnerships and accelerating on-premises-to-hybrid migration services. Invest in automated remediation workflows to differentiate beyond classification-only offerings. Counter emerging API-first entrants by embedding discovery into existing governance platform renewals. For New Entrants and Emerging Players: Build out sovereign-compliant localized processing nodes for Indian and German government verticals where multinational incumbents face data localization friction. Target mid-market healthcare systems in the United States with HIPAA-specific pre-configured classification templates and managed service bundling. Pursue channel-centric go-to-market through MSSP partnerships rather than direct enterprise sales. For Investors and Strategic Acquirers: Specialized classification engine developers with proven sub-5% false positive rates in healthcare and financial services document repositories offer the strongest acquisition rationale. Long-term viability hinges on convergence with AI governance platforms rather than standalone discovery positioning. Watch for EU AI Act enforcement actions against training data documentation gaps as the signal indicating accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding discovery into Microsoft Azure Purview and IBM Watson governance stacks captures enterprise renewal cycles. |
| Geographic Expansion | Localized processing nodes in Bengaluru and Hyderabad satisfy India's DPDP Act sovereign data requirements. |
| Acquisition of Specialist Firm | Purchasing low-latency classification engine developers addresses ML engineering scarcity in cloud-native environments. |
| Strategic Partnership | Alliances with managed security service providers create indirect routes to mid-market healthcare buyers. |
| Product Launch | Real-time inference engines for serverless architectures displace batch scanning in financial transaction monitoring. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with CISOs, data protection officers, cloud architects, and MSSP portfolio managers across financial services, healthcare, and government verticals; and secondary validation against SEC cybersecurity disclosure filings, HIPAA breach notification databases, EU AI Act implementation guidance, and hyperscaler capex allocation reports. Bottom-up segment sizing triangulated against top-down regulatory spend estimates.
Forecast inputs span deployment mode, organization size, vertical industry, integration complexity with legacy ERP systems, and regional regulatory enforcement intensity. Modeled segmentation dimensions include solution type, deployment architecture, application use case, and end-user industry across the analysis window. CAGRs derive from regression against historical procurement cycle data and regulatory mandate implementation timelines, with cloud-native workload expansion and AI governance convergence as primary demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by hyperscaler-native discovery tools or accelerated EU AI Act enforcement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cyber Deception Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Endpoint Protection Platforms (EPP) Market
Cybersecurity
Information Security Products and Services Market
Cybersecurity
Saas-Based IT Security Market
Cybersecurity
Network Traffic Analysis Solutions Market
Cybersecurity
Peru Cybersecurity Market
Cybersecurity
Cloud Network Security Market
Cybersecurity
Firewall-As-A-Service (Fwaas) Market
Cybersecurity
Global Data Exfiltration Market
Cybersecurity
5G Security Market
Cybersecurity
Global Zero-Trust Security Market
Cybersecurity
Indonesia Cybersecurity Market
Cybersecurity
Endpoint Security Market
Cybersecurity
United States Virtualization Security Market
Cybersecurity
Europe Cloud DLP Market