
 Thailand IT and Security Market | 2026-2036
Thailand IT and Security Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand IT and Security Market Analytics
Subscription-based financing and managed security service leasing is reshaping competitive access for mid-tier Thai enterprises previously priced out of enterprise-grade protection. Palo Alto Networks leverages channel partnerships with local systems integrators to sustain footholds in government verticals. Fortinet anchors its position through appliance-heavy deployments that dominate manufacturing and logistics campuses across Eastern Economic Corridor provinces. Fujitsu Thailand Co. Ltd. competes by bundling domestic data residency compliance with hybrid cloud security architectures favored by regulated industries.
Thailand IT and Security encompasses hardware, software, and service layers designed to protect digital infrastructure from unauthorized access, data exfiltration, and operational disruption, with next-generation firewalls processing traffic at throughput rates exceeding 100 Gbps in carrier-grade deployments. The primary commercial purpose centers on maintaining business continuity, regulatory compliance, and customer trust across digitally transformed operations. AI-Powered Security segments lead R&D allocation as Thai enterprises confront automated threat campaigns, while Cloud-Based deployment captures the fastest expansion trajectory driven by Ministry of Digital Economy and Society cloud-first directives. Zero Trust Architecture segments concentrate margin pools in financial services and critical infrastructure where lateral movement prevention commands premium pricing.
Thailand's national cybersecurity regulator and the Bank of Thailand's technology risk supervision framework mandate baseline encryption standards and incident reporting protocols that elevate procurement specifications across banking and telecommunications sectors. The National Cyber Security Agency enforces critical information infrastructure protection requirements that restrict vendor selection to certified domestic and international providers. Stakeholders must monitor evolving data localization requirements and cross-border transfer restrictions that will determine architecture choices and partnership strategies for platform delivery.
Market Dynamics
The Bank of Thailand's operational risk guidelines are compressing procurement cycles across Thai financial institutions, forcing accelerated replacement of legacy perimeter defenses with zero-trust architectures that demand continuous verification of every access request.
Growth Catalysts
- Cloud-First Directives:The Ministry of Digital Economy and Society mandates cloud migration for state agencies, expanding addressable market for cloud-native security platforms.
- Eastern Economic Corridor:Manufacturing and logistics investments across Chonburi, Rayong, and Chachoengsao provinces generate demand for industrial control system protection.
- AI-Powered Threat Detection:Automated threat campaigns from regional actors drive Thai enterprises toward machine-learning-based anomaly detection systems.
Market Restraints
- Certified Vendor Concentration:National Cyber Security Agency critical infrastructure restrictions limit procurement to pre-approved domestic and international providers, reducing competitive pressure.
- Data Localization Costs:Evolving cross-border transfer restrictions force architecture duplication, raising total cost of ownership for multinational deployments.
- Skills Pipeline Gap:Domestic cybersecurity workforce development lags deployment timelines, extending implementation cycles for complex zero-trust rollouts.
Strategic Opportunities
- Mid-Tier Enterprise Access:Subscription-based managed security services unlock segments previously excluded from enterprise-grade protection through capital expenditure avoidance.
- Regulatory Tailwind:Bank of Thailand technology risk supervision framework mandates baseline encryption standards that elevate minimum procurement specifications across banking.
- Hybrid Cloud Convergence:Integration of on-premises appliance deployments with cloud-native security fabrics addresses regulated industries requiring data residency compliance.
Industry Challenges
- Integration Complexity:Legacy firewall architectures in Thai manufacturing campuses resist seamless incorporation with cloud-delivered security service edges.
- Certification Timelines:National Cyber Security Agency vendor approval processes extend sales cycles for new market entrants seeking critical infrastructure access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand IT and Security Market |
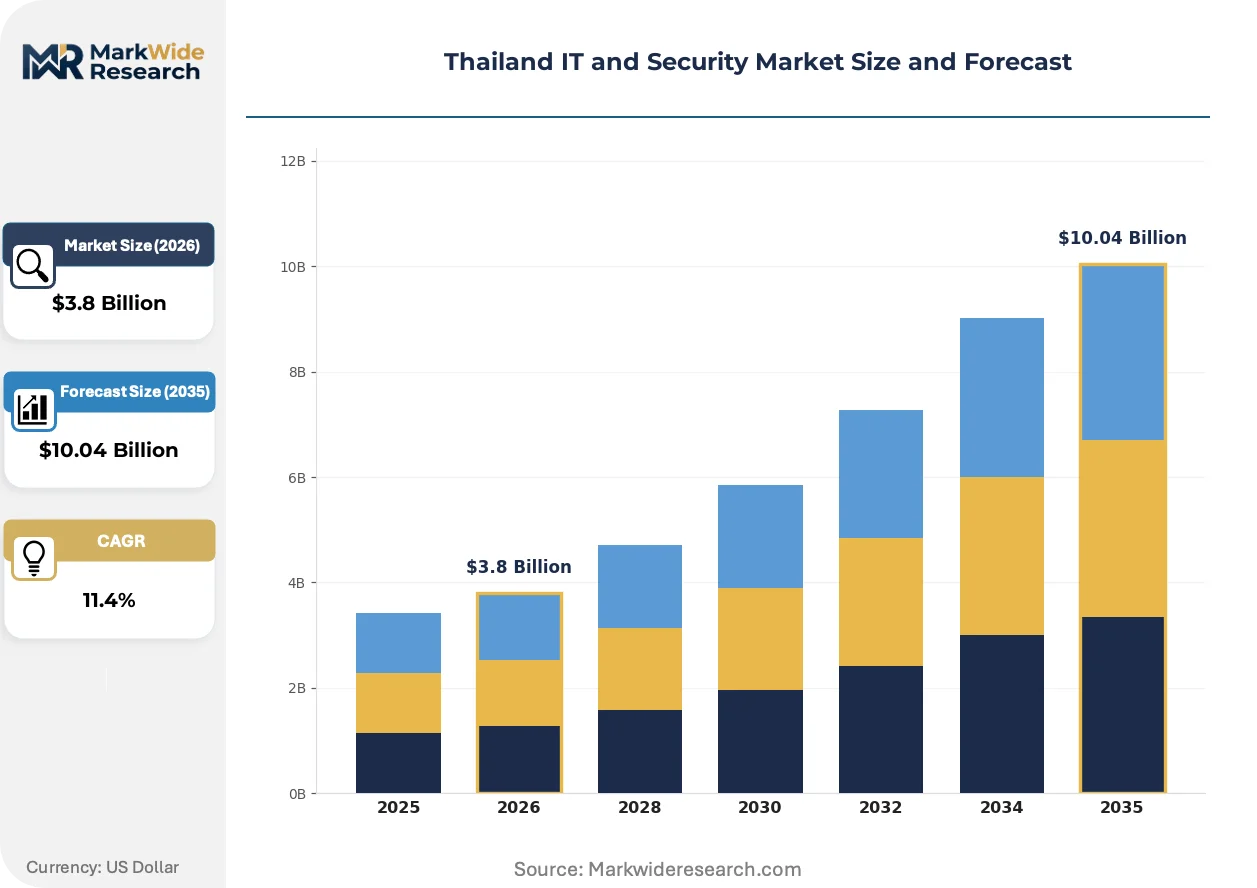
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firewalls, Antivirus Software, Intrusion Detection Systems, Encryption Tools Customer Type: SMEs, Government Agencies, Large Enterprises, Educational Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: AI-Powered Security, Blockchain Security, Zero Trust Architecture, Endpoint Protection |
| Companies Covered | Check Point Software Technologies Ltd., Palo Alto Networks Inc., IBM Corporation, CrowdStrike Holdings Inc., Trend Micro Incorporated, Cisco Systems Inc, Fortinet Inc., Microsoft Corporation, Fujitsu Thailand Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand IT and Security Market Evolving Landscape
Security delivery models across Thailand are fragmenting between appliance-heavy industrial deployments and cloud-native financial services architectures, with procurement authority shifting from IT departments to risk committees.
Secure access service edge technology is virtualizing network security functions that previously required dedicated hardware appliances. Thai banks and telecommunications operators are adopting SASE at accelerated pace to support distributed workforces. This consolidation of networking and security stacks is virtualizing traditional value chain boundaries between carriers and security vendors.
The National Cyber Security Agency enforces critical information infrastructure protection requirements that restrict vendor selection to certified providers. Thai banking and telecommunications sectors face elevated compliance thresholds with mandatory incident reporting protocols. Financial institutions are responding by consolidating procurement around pre-approved vendor lists that satisfy both domestic certification and international standards.
Mid-tier Thai enterprises are abandoning perpetual license purchases in favor of subscription-based managed security service arrangements. Systems integrators and channel partners capture expanded margin pools by bundling deployment, monitoring, and response capabilities. This transformation is most visible in Bangkok's enterprise corridor and emerging digital industrial zones where capital constraints meet regulatory pressure.
Thailand IT and Security Market Segmentation
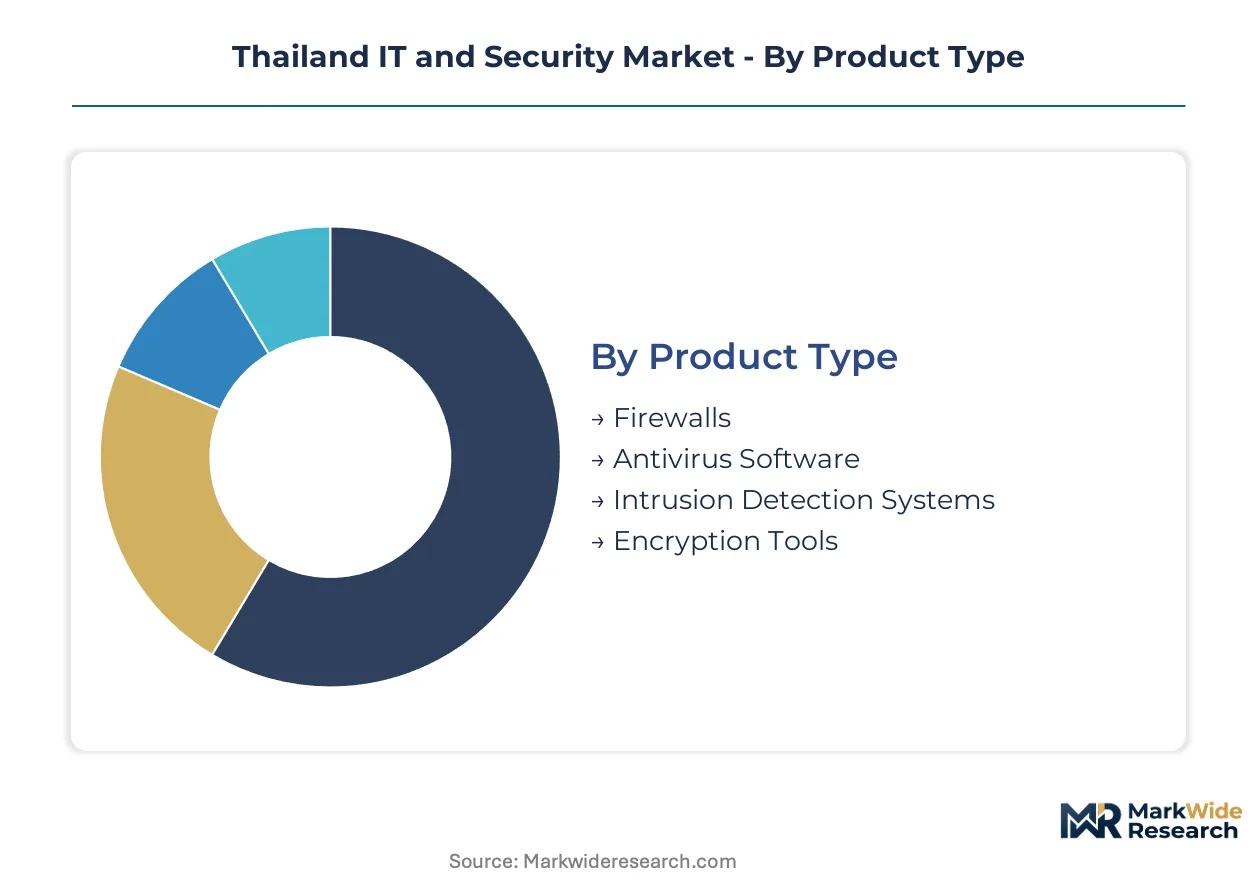
Thailand's IT and security procurement patterns fragment sharply across deployment architectures and customer sophistication levels. Vendors must calibrate service intensity, pricing tiers, and compliance packaging to match divergent technical capabilities and regulatory exposure across these segments.
Product Type:
After-sales service intensity varies dramatically by product category, with hardware-centric segments demanding on-site technical support while software layers shift toward remote monitoring and automated patch management.
- Firewalls:Next-generation appliances process carrier-grade traffic exceeding 100 Gbps in Bangkok's telecommunications hubs. Manufacturing campuses across Chonburi and Rayong provinces drive demand for industrial control system gateways that segment operational technology networks from corporate IT.
- Antivirus Software:Endpoint protection platforms deploy via centralized policy engines across distributed Thai enterprise networks. Educational institutions in Bangkok and Chiang Mai represent high-volume, price-sensitive procurement with limited internal security operations capacity.
- Intrusion Detection Systems:Network behavior analytics platforms monitor east-west traffic flows in financial services data centers.
- Encryption Tools:Data-at-rest and data-in-transit protection satisfies Bank of Thailand baseline standards for classified financial transactions.
By volume, Firewalls leads. By growth pace, Encryption Tools is ahead.
Customer Type:
Cost tier stratification separates capital-constrained buyers seeking subscription flexibility from institutions with dedicated procurement committees and multi-year security roadmaps.
- SMEs:Mid-tier enterprises across Bangkok's enterprise corridor lease managed security services to avoid upfront capital expenditure. Subscription-based financing unlocks enterprise-grade protection previously inaccessible to firms with limited security operations staffing.
- Government Agencies:Ministry of Digital Economy and Society cloud-first directives mandate standardized procurement across state agencies. Certified vendor restrictions from the National Cyber Security Agency compress supplier lists to pre-approved domestic and international providers.
- Large Enterprises:Banking and telecommunications operators maintain dedicated security operations centers with 24/7 monitoring capabilities.
- Educational Institutions:Universities and technical colleges face ransomware exposure from open network architectures serving heterogeneous device populations.
By revenue concentration, Government Agencies leads. By expansion trajectory, SMEs is climbing the fastest.
Deployment:
Application context determines architecture selection, with regulated industries requiring data residency compliance while distributed workforces favor cloud-native delivery models.
- Cloud-Based:Native security fabrics scale elastically to protect Ministry of Digital Economy and Society cloud migrations. Thai banks adopt secure access service edge architectures to consolidate networking and security stacks for branchless operations.
- Hybrid:Fujitsu Thailand bundles domestic data residency with cloud elasticity for regulated industries. Manufacturing firms across Eastern Economic Corridor provinces maintain on-premises appliances for operational technology segmentation while leveraging cloud analytics for threat intelligence.
- On-Premises:Legacy firewall architectures persist in industrial campuses with air-gapped operational networks.
- Managed Services:Systems integrators capture expanded margins by bundling deployment, monitoring, and incident response.
By installed base, On-Premises leads. By adoption momentum, Cloud-Based is gaining share fastest.
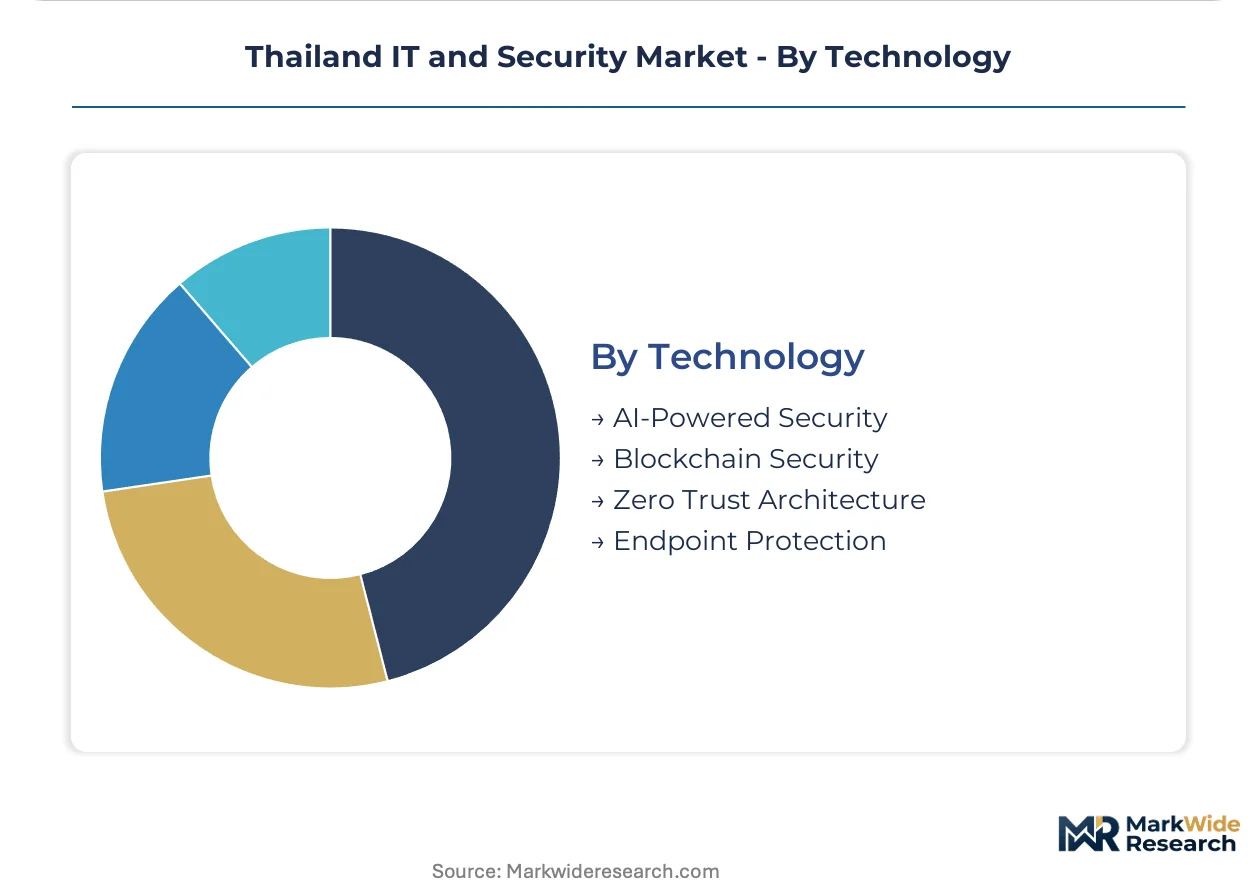
Technology:
Maturity curves separate proven defensive layers from emerging architectures commanding premium pricing through scarcity of implementation expertise.
- AI-Powered Security:Machine learning platforms detect anomalous patterns in network traffic and endpoint behavior. Thai enterprises confront automated threat campaigns from regional actors, elevating procurement priority for self-learning detection systems.
- Zero Trust Architecture:Continuous verification frameworks prevent lateral movement in financial services and critical infrastructure. Bank of Thailand operational risk guidelines compress procurement cycles, accelerating replacement of legacy perimeter defenses.
- Endpoint Protection:Unified endpoint detection and response platforms consolidate antivirus, device control, and forensic capabilities.
- Blockchain Security:Distributed ledger protection addresses supply chain traceability requirements in logistics and customs applications.
By deployment scale, Endpoint Protection leads. By investment growth, Zero Trust Architecture is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's IT and security sector runs a structural trade deficit in specialized hardware, importing carrier-grade appliances while exporting managed security services to neighboring Mekong economies. Cross-border data flows through Bangkok's internet exchange points generate demand for sovereign cloud architectures that satisfy emerging localization requirements.
Bangkok Metropolitan Region
Thailand's capital corridor concentrates banking headquarters and telecommunications infrastructure demanding zero-trust architectures. The Bank of Thailand's technology risk supervision framework mandates baseline encryption standards that elevate procurement specifications across financial institutions. Sathorn and Silom districts host security operations centers processing threat intelligence for regional financial networks.
Eastern Economic Corridor
Manufacturing campuses across Chonburi, Rayong, and Chachoengsao provinces generate demand for industrial control system protection. The National Cyber Security Agency enforces critical information infrastructure requirements that restrict vendor selection to certified providers. Amata City and Map Ta Phut industrial zones deploy operational technology segmentation gateways to isolate production networks from corporate IT.
Chiang Mai-Lamphun Digital Corridor
Startup ecosystems and digital nomad infrastructure create demand for cloud-native security platforms. Ministry of Digital Economy and Society cloud-first directives accelerate migration timelines for state-supported innovation hubs. Maejo University and Chiang Mai University research clusters drive procurement of endpoint protection for heterogeneous device populations.
Phuket-Krabi Tourism Technology Belt
Hospitality payment systems and guest data management require PCI-DSS compliant security architectures. The Personal Data Protection Act enforcement raises compliance thresholds for cross-border customer data handling. Patong and Ao Nang hospitality clusters adopt managed security services to address ransomware exposure without dedicated internal operations staff.
Thailand IT and Security Market Competitive Landscape
On the supply side, the industry is bifurcated between appliance-heavy industrial deployments and cloud-native service delivery. Hardware-centric specialists dominate manufacturing corridor procurement through localized technical support networks. Software-defined security vendors capture financial services verticals via subscription financing. The dominant competitive moves involve channel partnership expansion with Thai systems integrators and certification acquisition for National Cyber Security Agency critical infrastructure approval.
Within the multinational platform tier, Palo Alto Networks and Fortinet occupy positions reflecting divergent deployment philosophies. Palo Alto Networks exemplifies cloud-native expansion through local systems integrator relationships. Fortinet anchors the appliance-centric vector with manufacturing and logistics campus penetration. Fujitsu Thailand Co. Ltd. represents hybrid convergence, bundling domestic data residency compliance with managed service delivery for regulated industries.
| Leading Market Players |
|---|
| Check Point Software Technologies Ltd. |
| Palo Alto Networks Inc. |
| IBM Corporation |
| CrowdStrike Holdings Inc. |
| Trend Micro Incorporated |
| Cisco Systems Inc |
| Fortinet Inc. |
| Microsoft Corporation |
| Fujitsu Thailand Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Bangkok's enterprise corridor concentrates certified security appliance distribution capacity, channeling pricing power toward systems integrators who bundle deployment with recurring managed services. National Cyber Security Agency certification requirements restrict vendor eligibility, compressing competitive pressure on pre-approved hardware tiers while subscription-based SaaS models erode traditional perpetual license premiums.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy certification levels, with Bank of Thailand encryption mandates elevating baseline procurement specifications. Price differentiation hinges on domestic data residency compliance and post-deployment technical support intensity. Cost compression in mid-tier managed services is intensifying because channel partners compete on bundled monitoring margins. Educational institutions exhibit highest price sensitivity, while financial institutions with dedicated risk committees demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing for carrier-grade appliances concentrates among Taiwanese and South Korean EMS providers, with software-defined security components sourcing from US and Israeli development centers. Raw material dependencies span specialized semiconductors, cryptographic processors, and industrial-grade chassis materials. Single-source vulnerability in certified firmware modules creates supply chain risk for critical infrastructure deployments. Distribution runs through Bangkok-based systems integrators who maintain localized technical support networks across Eastern Economic Corridor provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward risk committees and procurement consolidation among banking consortiums, fragmenting vendor influence and elevating compliance-driven specification rigidity.
For Market Incumbents: Insulate market position through accelerated National Cyber Security Agency certification renewal and captive development of Thai-language security operations interfaces. Threat substitution from cloud-native SASE platforms demands channel control reinforcement. Vertical integration into localized threat intelligence feeds represents the critical lever for margin defense. For New Entrants and Emerging Players: Pursue white-space capture in Chiang Mai-Lamphun Digital Corridor startup ecosystems and Phuket-Krabi hospitality technology clusters, where compliance pressure meets capital constraints. Mid-tier manufacturing SMEs across Rayong province present the most penetrable segment. Go-to-market execution should anchor on subscription financing partnerships with domestic systems integrators. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-tailwind infrastructure play because data localization mandates and critical infrastructure protection requirements create durable competitive moats. Acquisition targets should display hybrid cloud security architectures with pre-existing Bank of Thailand compliance validation. Monitor National Cyber Security Agency vendor list expansion announcements as inflection signal for competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| National Cyber Security Agency Certification Acquisition | Unlocks critical infrastructure procurement access restricted to pre-approved vendor lists. |
| Managed Security Service Partnership | Captures recurring revenue from mid-tier enterprises avoiding capital expenditure. |
| Hybrid Cloud Architecture Development | Addresses Bank of Thailand data residency requirements with elastic scaling capacity. |
| Thai Systems Integrator Channel Expansion | Penetrates government verticals through localized deployment and support capabilities. |
| Zero Trust Platform Localization | Aligns with Bank of Thailand operational risk guidelines mandating continuous verification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of National Cyber Security Agency certification registries, Bank of Thailand technology risk supervision circulars, and Ministry of Digital Economy and Society cloud migration directives. Primary interviews engaged chief information security officers at financial institutions, procurement leads at Eastern Economic Corridor manufacturing campuses, systems integrator channel managers, and National Cyber Security Agency compliance officers. Secondary validation drew from customs import data for security appliances, hyperscaler capex disclosures for cloud infrastructure, and enterprise software licensing databases. Bottom-up segment sizing triangulates against top-down macroeconomic anchors.
Forecast inputs incorporate deployment model adoption curves, regulatory compliance timeline acceleration, and customer type migration patterns across the projection horizon. Segmentation dimensions span product type, customer sophistication tier, deployment architecture, and technology maturity curve. CAGRs derive from logistic diffusion modeling of security technology substitution rates, calibrated against historical procurement cycle data. Industry-specific inputs include Bank of Thailand operational risk guideline implementation velocity and Ministry of Digital Economy and Society cloud-first directive enforcement cadence.
Macroeconomic conditions sit as an overlay; deviation in Thai Baht exchange rate volatility, sovereign debt servicing capacity, or foreign direct investment flows into Eastern Economic Corridor manufacturing would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity and certification timeline stability. Quarterly review of National Cyber Security Agency vendor list updates and Bank of Thailand technology risk supervision circular releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cryptojacking Solution Market
Cybersecurity
Data Security Market
Cybersecurity
Thailand Cybersecurity Market
Cybersecurity
Artificial Intelligence in Cybersecurity Market
Cybersecurity
Deception Technology Market
Cybersecurity
Penetration Testing Market
Cybersecurity
IT and Telecom Cyber Security Market
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
Big Data Security Market
Cybersecurity
Enterprise Firewall Market
Cybersecurity
Global Sandboxing Market
Cybersecurity
Cyber Warfare Market
Cybersecurity
Portugal Cybersecurity Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
North America Digital Forensics Market