
 Concrete Canvas Market | 2026-2036
Concrete Canvas Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Canvas Market Intelligence
Qualification against the ASTM D8364 standard for Geosynthetic Cementitious Composite Mats is reorganizing the competitive landscape. This specification sets performance benchmarks for durability and strength. Concrete Canvas Ltd leverages its first-mover advantage and extensive project portfolio. Sika AG competes by integrating these materials into its broader construction chemical systems, while HUESKER Synthetic GmbH specializes in advanced geosynthetic solutions for civil engineering.
Concrete Canvas is a flexible, cement-impregnated fabric that hardens upon hydration to form a thin, durable concrete layer, typically with a compressive strength over 50 MPa. This Geosynthetic Cementitious Composite Mat provides a rapidly deployable alternative to traditional poured concrete. Among applications, erosion control and trench lining represent the largest share of deployments. Civil contractors and infrastructure developers are the primary end users, procuring material for large-scale public and private works.
Regulations from the US EPA concerning stormwater pollution prevention plans directly influence material selection for erosion control projects. In Europe, CE marking under the Construction Products Regulation mandates verified performance and safety standards for market access. Similarly, national standards bodies like the British Standards Institution provide guidance on application. Future market development hinges on demonstrating long-term durability versus conventional cast-in-place concrete.
Market Dynamics
The push for standardized, verifiable performance in geosynthetics is the central force shaping the market. The establishment of formal specifications like ASTM D8364 is moving the material from a novel solution to a specified component in civil engineering.
Growth Catalysts
- Regulatory Mandates:Regulations from the US EPA concerning stormwater pollution prevention plans drive the use of effective erosion control materials, creating a direct demand pull for certified GCCMs.
- Infrastructure Investment:Large-scale public works and transportation projects, particularly across India and Brazil, require rapid, durable solutions for slope stabilization and channel lining, boosting material consumption.
- Rapid Deployment:The technology's ability to be installed quickly with less equipment than traditional concrete reduces project timelines and labor costs, a significant catalyst for civil contractors.
Market Restraints
- Initial Material Cost:The upfront purchase price of Geosynthetic Cementitious Composite Mats is higher than that of conventional materials like poured concrete or riprap, creating a barrier for cost-sensitive projects.
- Durability Perception:End users require more long-term performance data to fully trust the material's durability and lifespan compared to the decades of field history for traditional cast-in-place concrete.
- Substitution by Concrete:Poured concrete remains a deeply entrenched, low-cost incumbent for many structural and lining applications, representing a significant and readily available substitute material.
Strategic Opportunities
- Application Diversification:There is significant potential in developing specialized product variants for niche uses such as containment berms in the energy sector or rapidly deployable shelters for disaster relief operations.
- Emerging Market Penetration:Beyond India and Brazil, infrastructure development in Southeast Asian and African nations presents untapped geographic markets for erosion control and water management projects.
- Hybrid System Development:Integrating GCCMs with other geosynthetic products, like geogrids or geomembranes, offers an opportunity to create advanced, multi-functional systems for complex geotechnical challenges.
Industry Challenges
- Installer Training Gap:Ensuring proper on-site hydration and installation techniques is critical to performance, and a shortage of certified, experienced installers can lead to inconsistent outcomes and project failures.
- Logistical Complexity:Transporting and handling large, heavy rolls of the material, especially in remote or difficult-to-access project sites, presents considerable logistical and planning challenges for contractors.
- Certification Timelines:Achieving compliance with evolving standards like ASTM D8364 or specific national codes is a time-consuming and resource-intensive process for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Canvas Market |
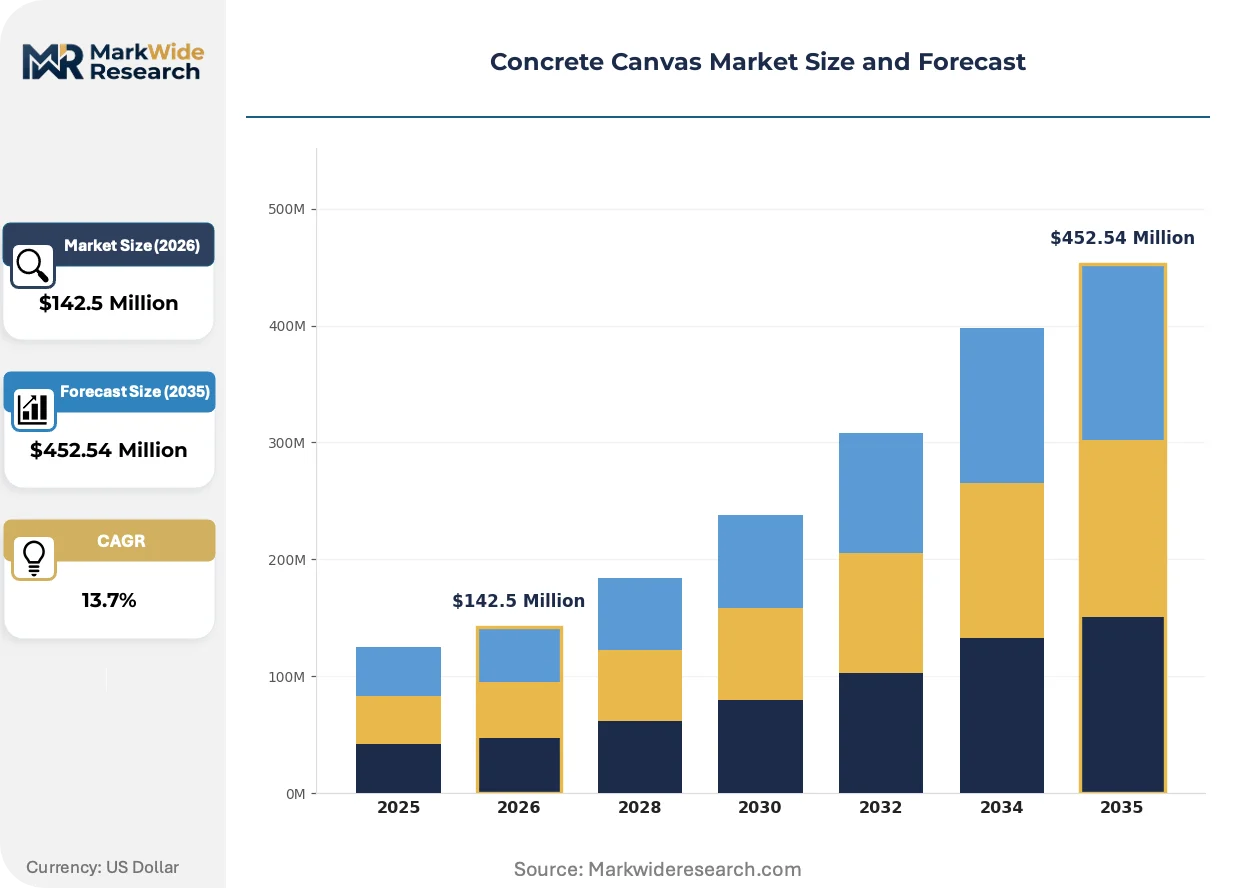
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Canvas Standard, Concrete Canvas Flexible, Concrete Canvas Fast Set, Concrete Canvas Waterproof, Concrete Canvas High Strength Application: Erosion Control, Retaining Walls, Slope Stabilization, Trench Lining, Flood Protection End User: Civil Contractors, Environmental Agencies, Defense Organizations, Infrastructure Developers, Agricultural Sector Deployment Method: Manual Installation, Mechanical Installation, Robotic Placement, Spray Application |
| Companies Covered | Sika AG, Nycon, Concrete Canvas Ltd, Titan Environmental Containment, GEOFABRICS AUSTRALASIA PTY LTD, Milliken & Company, The Euclid Chemical Company, HUESKER Synthetic GmbH, Bekaert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Canvas Market Strategic Shifts & Innovations
The market is transitioning from niche applications toward mainstream specification, driven by a convergence of material science advancements and formalized performance standards. This evolution prioritizes verifiable durability and installation efficiency over traditional construction methods.
Geosynthetic Cementitious Composite Mats provide a flexible, cement-impregnated fabric that hardens upon hydration. Civil contractors are increasingly adopting the material for large-scale erosion control and trench lining projects due to its speed. This rapid deployment capability is decomposing the traditional project timelines and cost structures associated with cast-in-place concrete.
Formalization of performance criteria through standards like ASTM D8364 for GCCMs is a critical trend. This standard provides a clear framework for evaluating durability, strength, and other key metrics, removing ambiguity for specifiers. The civil engineering sector is most affected, as procurement for public works now aligns with these verifiable benchmarks.
Specification behavior is shifting from focusing solely on initial material price to a total lifecycle cost analysis. This change disrupts the conventional bidding process where low-cost, traditional materials often held an advantage. This trend is most prominent in regulated infrastructure markets like North America and Europe, where long-term performance and maintenance are key considerations.
Concrete Canvas Market Segmentation
Understanding the varied requirements across different product types, applications, end-users, and deployment methods is crucial for market participants. This segmentation analysis provides a granular view of demand patterns and technological adoption within the Concrete Canvas market. It highlights where specific material properties and installation efficiencies create distinct value propositions for civil engineering projects.
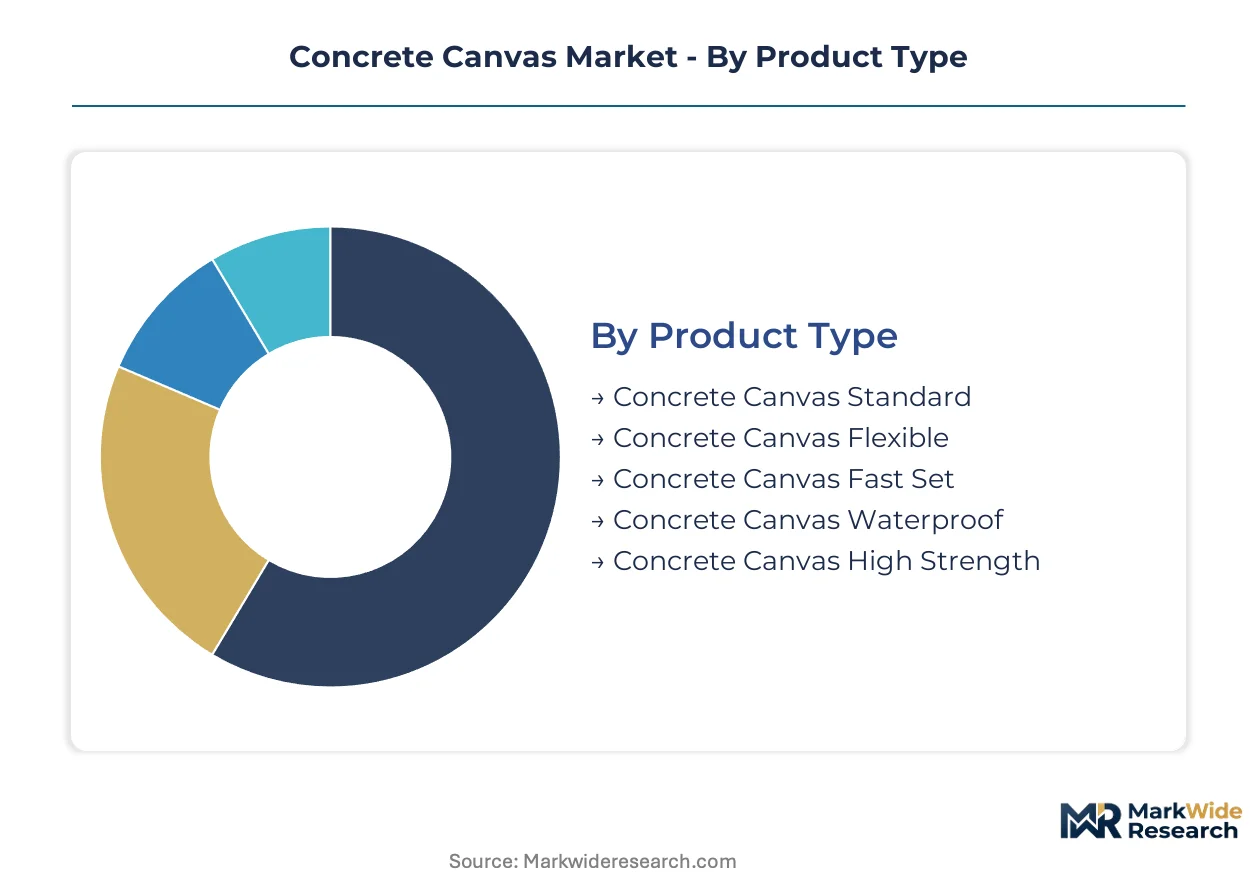
Product Type:
Product differentiation often dictates a material's suitability for specific climatic conditions, influencing its domestic versus export market potential.
- Concrete Canvas Standard:This foundational product offers a flexible, cement-impregnated fabric that hardens to a durable concrete layer upon hydration. Demand concentrates in large-scale infrastructure projects across India and Brazil, driven by its balance of performance and rapid deployment capabilities.
- Concrete Canvas High Strength:Engineered for enhanced load-bearing capacity and impact resistance, this variant provides superior structural integrity in demanding environments. Infrastructure developers for critical public works, such as railway embankments and bridge scour protection, prioritize its long-term durability.
- Concrete Canvas Flexible:Designed for applications requiring greater conformability to irregular surfaces, this type adapts to complex geometries.
- Concrete Canvas Fast Set:This formulation accelerates hardening times, enabling quicker project completion in time-sensitive construction schedules.
- Concrete Canvas Waterproof:Incorporating properties to resist water ingress, this product is specified for lining applications where impermeability is critical.
Concrete Canvas Standard commands the established base. The steepest expansion runs through Concrete Canvas High Strength.
Application:
Application segments delineate where Concrete Canvas materials solve distinct engineering challenges, from protecting environmental assets to securing critical infrastructure.
- Erosion Control:This application involves stabilizing soil and preventing material loss on slopes, channels, and embankments. Civil contractors extensively use it for stormwater management in the US, driven by EPA regulations concerning pollution prevention plans.
- Trench Lining:Used to protect and stabilize excavation trenches for pipelines and cables, this application benefits from rapid installation and minimal equipment needs. Infrastructure developers in Europe frequently specify it for utility projects, valuing its speed over traditional concrete.
- Retaining Walls:Concrete Canvas can form part of composite retaining structures or provide surface protection for earth-retaining systems.
- Slope Stabilization:This involves securing unstable ground to prevent landslides and improve geotechnical integrity, often in challenging terrains.
- Flood Protection:Deployments include creating temporary or permanent barriers and reinforcing existing defenses against water inundation.
Erosion Control generates the most volume. Trench Lining exhibits the most dynamic growth.
End User:
The end-user landscape reflects the diverse organizational needs and procurement processes, ranging from public sector entities to private commercial enterprises.
- Civil Contractors:These entities are the primary purchasers, integrating Concrete Canvas into their broader construction projects for public and private infrastructure. They prioritize materials offering efficiency gains and labor cost reductions for large-scale works.
- Infrastructure Developers:Responsible for planning, funding, and executing large-scale public and private works, these developers specify materials based on long-term performance and project lifecycle costs. They drive demand for durable solutions in transportation and utilities.
- Environmental Agencies:These governmental or non-governmental bodies utilize the material for ecological restoration, pollution control, and habitat protection initiatives.
- Defense Organizations:Military and security forces deploy Concrete Canvas for rapidly constructible shelters, fortifications, and logistical support structures.
- Agricultural Sector:Farmers and agribusinesses use the material for irrigation ditch lining, erosion control on farmland, and water containment solutions.
Civil Contractors represent the largest customer group. Infrastructure Developers show the most significant procurement shift towards these materials.
Deployment Method:
Deployment methods highlight the varying levels of mechanization and labor intensity involved in installation, impacting project timelines and overall cost efficiency.
- Manual Installation:This method relies on human labor for placement and hydration, suitable for smaller projects, remote sites, or areas with limited access for heavy machinery. It offers flexibility in diverse topographical conditions.
- Mechanical Installation:Utilizing excavators, cranes, or specialized laying equipment, this method enhances efficiency and speed for large-scale, linear projects. Civil contractors adopt this for extensive trench lining and erosion control works, reducing labor requirements.
- Robotic Placement:Emerging technologies in automation are being explored for precision placement in hazardous or difficult-to-access environments.
- Spray Application:This method involves applying the material in a liquid or semi-liquid form, suitable for complex geometries or repair work.
Manual Installation remains widely accessible. Mechanical Installation offers superior economies of scale for major projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Civil contractors and infrastructure developers represent significant procurement power across diverse geographies. These end-users prioritize efficient, durable solutions for large-scale public and private works. Demand for Concrete Canvas materials concentrates where infrastructure investment and stringent environmental regulations intersect.
United States
Demand for erosion control materials and trench lining drives consumption within the United States. US EPA regulations concerning stormwater pollution prevention plans mandate effective material selection for construction sites. Infrastructure projects across the Northeast Corridor, particularly in states like New York and Pennsylvania, require rapid deployment solutions for aging utility networks.
Germany
German infrastructure modernization and flood protection initiatives create demand for geosynthetic solutions. CE marking under the Construction Products Regulation ensures verified performance for construction materials seeking market access. Civil engineering firms in the Rhine-Ruhr region utilize these materials for canal reinforcement and embankment stabilization projects.
India
Large-scale public works and transportation projects, including national highway expansions, require rapid and durable solutions across India. The Ministry of Road Transport and Highways promotes sustainable construction practices in infrastructure development. Major infrastructure corridors like the Delhi-Mumbai Industrial Corridor are significant deployment sites for slope stabilization and channel lining.
Brazil
Brazilian infrastructure development in urban centers and for resource extraction projects generates demand for advanced construction materials. ANVISA provides regulatory oversight for construction materials used in public works, influencing material specification. Civil contractors in the São Paulo metropolitan area leverage rapid deployment for new utility installations and erosion control.
Australia
Australian mining sector infrastructure and coastal erosion management projects drive material specification for durable geosynthetics. Environmental protection agencies in states like Queensland enforce strict regulations for land rehabilitation and erosion prevention. Large-scale civil works in Western Australia, especially around Perth, adopt GCCMs for rapid trench lining and slope stabilization.
Concrete Canvas Market Key Industry Players
Player mix skews toward specialized geosynthetic manufacturers and diversified construction material suppliers. The market structure exhibits a blend of established incumbents leveraging broad distribution and agile niche players focusing on material innovation. Strategic archetypes include material innovators driving product development, integrated solution providers offering comprehensive construction systems, and regional specialists adapting products to local market needs. Competitive moves center on portfolio diversification to capture new applications, geographic expansion into emerging infrastructure markets, and securing product certifications to meet stringent engineering standards.
The competitive landscape features companies with deep expertise in construction chemicals and advanced textiles. Sika AG, for instance, represents a diversified construction materials giant, integrating geosynthetic cementitious composite mats into broader construction chemical systems. HUESKER Synthetic GmbH exemplifies a specialist in high-performance geosynthetic solutions, catering to complex civil engineering challenges with advanced materials. Concrete Canvas Ltd anchors the market as a first-mover, leveraging its proprietary technology and extensive project portfolio to maintain a strong market presence. These entities compete on material performance, installation efficiency, and compliance with evolving industry standards like ASTM D8364.
| Leading Market Players |
|---|
| Sika AG |
| Nycon |
| Concrete Canvas Ltd |
| Titan Environmental Containment |
| GEOFABRICS AUSTRALASIA PTY LTD |
| Milliken & Company |
| The Euclid Chemical Company |
| HUESKER Synthetic GmbH |
| Bekaert |
Cost & Logistics Intelligence
Extended lead-times for specialized Concrete Canvas rolls, especially for large infrastructure projects, directly influence procurement planning and overall project pricing. This dynamic is shaped by the material's manufacturing complexity and the logistical challenges associated with transporting heavy, oversized products to diverse project sites.
Pricing Analysis
Cost-plus contract patterns, often indexed to a construction input index, dominate pricing for large-scale Concrete Canvas procurements. Price differentiation stems from the material's quality grade, such as Concrete Canvas High Strength, and its specific certification level, like ASTM D8364 compliance. Pricing softness emerges from the persistent substitution threat posed by traditional poured concrete, which remains a low-cost incumbent. Civil contractors often exhibit higher price sensitivity regarding initial material cost, while infrastructure developers prioritize long-term performance and lifecycle value.
Supply Chain Analysis
Germany and specialized manufacturing hubs in Asia anchor the production of advanced geosynthetic materials and cementitious components. The supply chain draws from key raw material dependencies including cement, specialized polymer fabrics, and various chemical additives. Logistical complexity, particularly transporting large, heavy rolls to remote project sites, presents a structural supply chain risk. Distribution runs through a network of specialized construction material distributors and direct sales channels to large infrastructure developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Concrete Canvas market faces a capability scarcity concerning specialized installer training and widespread product certification, which limits broader adoption beyond early adopters.
For Market Incumbents:
Compound existing first-mover advantages by investing heavily in long-term durability studies to counteract the perception threat from conventional concrete. Diversify the application portfolio into niche uses such as containment berms in the energy sector to capture new revenue streams. Leverage extensive project portfolios to secure further ASTM D8364 certifications, reinforcing performance benchmarks.
For New Entrants and Emerging Players:
A certification fast-track for regional standards provides a viable entry point, allowing new players to penetrate local markets efficiently. Target application diversification in rapidly deployable shelters for disaster relief, where speed outweighs initial material cost concerns. Focus on emerging markets like Southeast Asia, offering rapid installation and labor cost savings as a primary go-to-market angle.
For Investors and Strategic Acquirers:
Long-term, this sits as a specialized material innovation play because regulatory mandates and infrastructure investment drive demand for verifiable performance. Target acquisition profiles include niche technology developers with proprietary product variants or regional distributors possessing strong installer training capabilities. Increased integration of GCCMs into large-scale public works projects, beyond erosion control, signals a market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Application Diversification | Expanding product use into new sectors like energy or disaster relief creates new revenue streams. |
| Certification Investment | Securing ASTM D8364 compliance validates performance and unlocks market access in regulated sectors. |
| Installer Training Programs | Addressing the installer training gap ensures consistent application quality and reduces project failures. |
| Hybrid System Development | Integrating GCCMs with geogrids offers advanced, multi-functional solutions for complex geotechnical challenges. |
| Emerging Market Penetration | Targeting infrastructure development in Southeast Asian nations expands the geographic footprint and sales volume. |
Research Approach
Initial hypotheses were tested against primary input from civil contractors, infrastructure developers, environmental agency officials, and geosynthetic manufacturers, then refined through iterative analysis. This approach combined qualitative insights from expert interviews with quantitative validation from secondary sources. Secondary data included US EPA reports, CE marking documentation, national standards from the British Standards Institution, and global infrastructure project databases. Both bottom-up and top-down triangulation methods were employed to ensure data consistency and accuracy.
Variance decomposition formed the basis of the forecast framework, disaggregating market growth across the analysis window into its constituent drivers. The model incorporated segmentation dimensions including product type, application, end user, deployment method, and regional infrastructure investment. Compound Annual Growth Rates were derived from historical data trends and projected future demand scenarios. Key industry-specific forecast inputs included anticipated infrastructure spending patterns and the stringency of environmental regulatory enforcement.
The analysis sits within stated boundaries; outcomes outside significant shifts in long-term durability perception or material cost parity with conventional concrete would require recalibration. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Africa Pipeline Construction Market