
 Qatar Construction Market | 2026-2036
Qatar Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Construction Market Outlook
Hospitality and sports infrastructure is consolidating as the dominant demand vertical following Qatar's mega-event hosting cycle. McDermott leverages its offshore fabrication heritage to compete for energy-linked industrial builds. Qatari Diar Construction anchors the premium residential and mixed-use pipeline through state-backed master planning. HBK Contracting Company dominates road, bridge, and heavy civil packages through decades of local operational scale.
Qatar construction encompasses the engineering, procurement, and physical assembly of buildings and infrastructure using reinforced concrete with specified compressive strengths of 40-60 MPa for high-rise cores and structural steel grades S355 and above for long-span commercial roofs. The sector serves Qatar's sovereign wealth-funded urbanization, hydrocarbon-linked industrial capacity, and tourism positioning. Concrete remains the volume leader across residential and infrastructure verticals, though steel is capturing share in fast-track commercial towers seeking reduced floor-to-floor heights. Design-Build delivery is displacing traditional Design-Bid-Build in complex hospitality and healthcare projects where single-point accountability compresses schedules.
The Ministry of Municipality enforces QSAS sustainability ratings and mandatory solar reflectance index thresholds for roofing materials. The Gulf Organization for Research and Development publishes region-specific cooling load metrics that shape glazing and insulation specifications. Contractors and developers must track evolving energy tariff structures and local content mandates from Qatar Energy's In-Country Value program to align procurement decisions with long-term project economics.
Market Dynamics
Qatar's sovereign wealth-funded urbanization pipeline is compressing project delivery timelines, forcing adoption of Design-Build contracts that collapse traditional sequential phases into overlapping execution streams.
Growth Catalysts
- QSAS Green Building Code:Mandatory sustainability ratings from Qatar's Ministry of Municipality are redirecting procurement toward thermally efficient envelope systems and low-carbon concrete mixes.
- Lusail Smart City Corridor:Master-planned infrastructure zones are consolidating demand for integrated utility networks and district cooling systems across mixed-use developments.
- Education City Expansion:Knowledge-economy anchor institutions are driving specialized laboratory and research facility construction with stringent vibration and climate control specifications.
Market Restraints
- Steel Price Volatility:Structural steel grades S355 and above face input cost swings tied to regional mill capacity constraints and shipping lane disruptions through the Strait of Hormuz.
- Specialized Labor Concentration:Skilled concrete finishing and post-tensioning expertise clusters among a limited contractor pool, creating bidding bottlenecks for complex high-rise cores.
- Gulf Organization for Research and Development Cooling Load Metrics:Stringent thermal performance thresholds extend design review cycles and limit supplier qualification to pre-certified envelope manufacturers.
Strategic Opportunities
- Qatar Energy In-Country Value Program:Local content mandates are creating procurement preferences for domestic steel fabrication and ready-mix concrete batching capacity.
- Modular Prefabrication Convergence:Offshore fabrication heritage from energy sector contractors is crossing into hospitality and healthcare verticals with accelerated module-to-site assembly.
- West Bay Lagoon District:Underdeveloped waterfront zones offer contiguous land parcels for integrated resort and residential developments with marina infrastructure.
Industry Challenges
- BIM-to-Field Coordination:Design-Build compression leaves limited margin for clash detection resolution between MEP systems and structural concrete pour sequences.
- QSAS Certification Timeline:Third-party sustainability verification extends project closeout by 4-8 months, straining contractor retention bonds and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Construction Market |
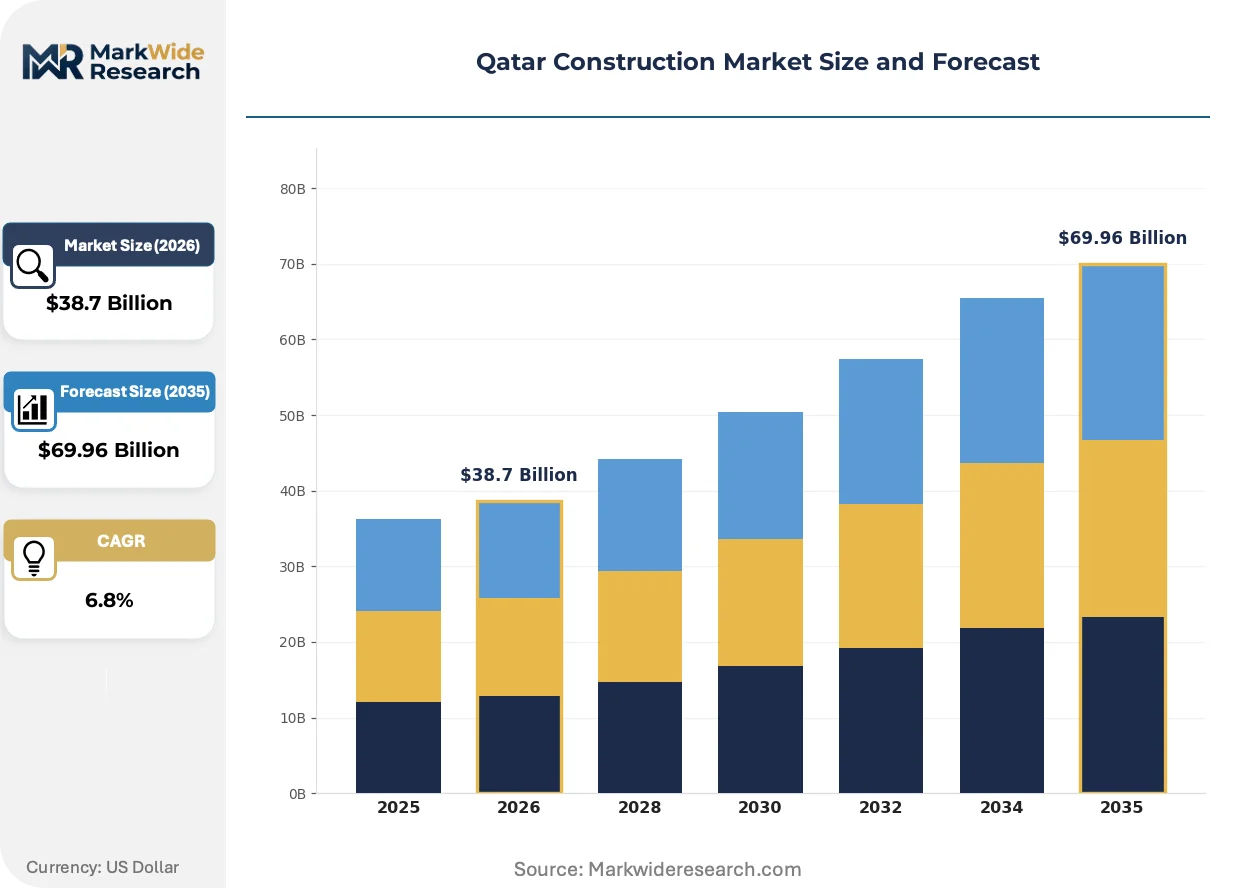
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material: Concrete, Steel, Wood, Glass Delivery Method: Design-Bid-Build, Design-Build, Construction Management, Integrated Project Delivery End User: Public Sector, Private Developers, Contractors, NGOs |
| Companies Covered | McDermott, Qatari Diar Construction, HBK Contracting Company, Al Ali Engineering Co. W.L.L, Consolidated Contractors Company, Larsen & Toubro, Technip Energies, Al Jaber Engineering, Saipem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Construction Market Strategic Shifts
Digital fabrication and regulatory tightening are converging to reshape how Qatar's construction sector sources materials, validates performance, and structures commercial risk across project lifecycles.
Modular bathroom pods and MEP riser assemblies are decentralizing on-site trade coordination for hospitality towers in Doha's central business district. Hotel operators facing compressed pre-opening schedules specify factory-integrated wet units to eliminate wet-work sequencing conflicts. This prefabrication shift is decentralizing final fit-out control from general contractors to specialized module suppliers with captive installation crews.
The Ministry of Municipality's phased QSAS enforcement is mandating whole-building energy modeling before construction permit issuance. Developers must demonstrate compliance with solar reflectance index thresholds and cooling load limits through third-party simulation. High-rise residential towers in Lusail are responding with high-performance glazing specifications and automated shading systems that exceed baseline code minimums.
Owner-operators in Qatar's healthcare and education verticals are consolidating vendor qualification around integrated facility management contracts. Single-source accountability for MEP maintenance and envelope performance is displacing traditional split warranties between construction and operations phases. This bundling trend is most visible in Education City research buildings where Qatar Foundation entities demand 10-year operational guarantees from design-build consortia.
Qatar Construction Market Segmentation
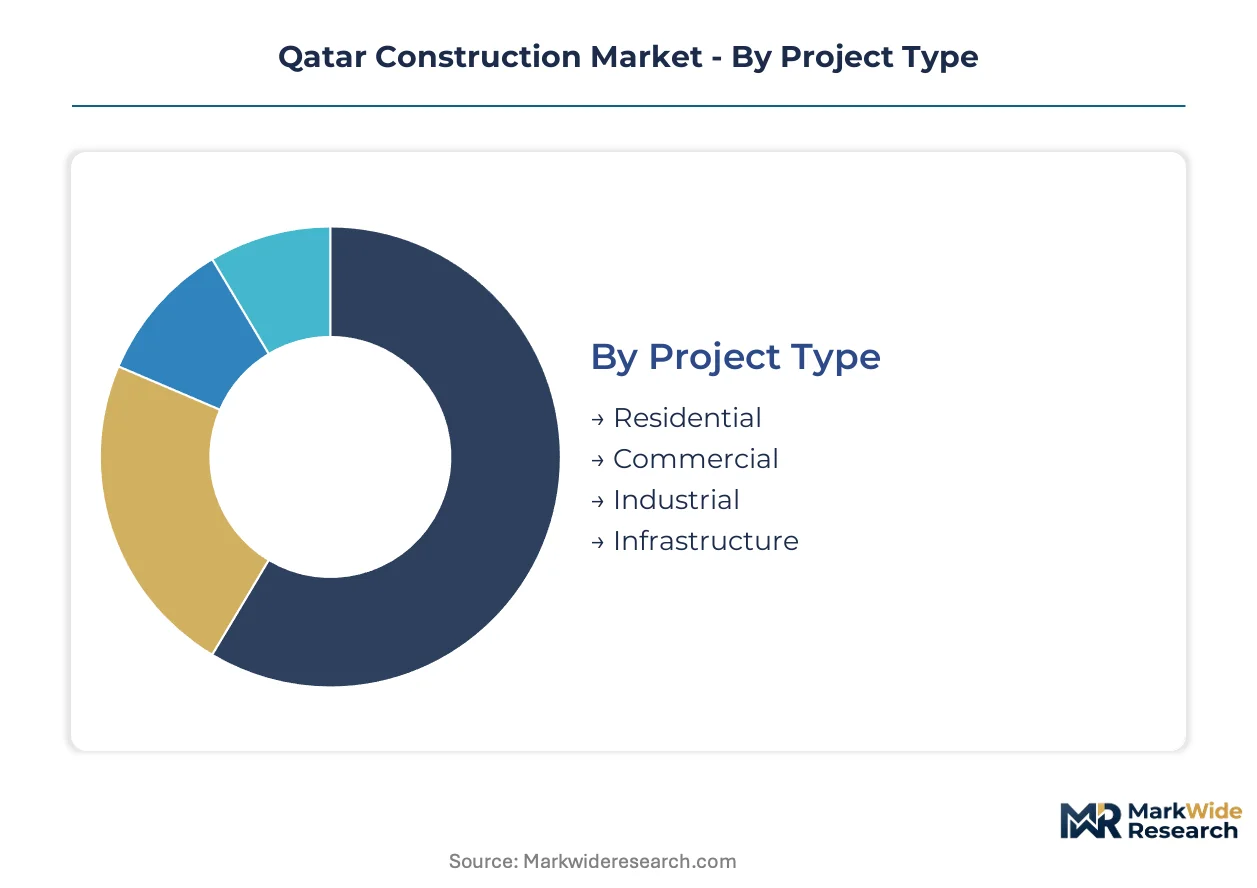
Qatar's construction pipeline fragments across project scale, material specification, and procurement risk allocation. Each segmentation axis reveals distinct contracting patterns tied to sovereign funding cycles, green code compliance, and labor specialization constraints.
Project Type:
Customization intensity rises with project complexity, from standardized residential repetition to bespoke industrial process integration.
- Residential:High-rise towers in Lusail and West Bay Lagoon deploy repetitive floor plates with QSAS-mandated envelope performance. Demand clusters in premium waterfront zones where Qatar Diar master plans dictate unit density and amenity integration.
- Commercial:Fast-track office and retail developments favor steel-framed long-span structures to compress floor-to-floor heights. HBK Contracting and specialized steel erectors capture packages in Doha's central business district where land values justify accelerated schedules.
- Industrial:Energy-linked process facilities require 40-60 MPa concrete for equipment foundations and S355+ steel for pipe rack structures. McDermott leverages offshore fabrication heritage for petrochemical and LNG-adjacent builds.
- Infrastructure:Road, bridge, and utility networks dominate public sector procurement through decades-long operational scale. Heavy civil packages concentrate with established local contractors possessing fleet capacity and Ministry of Municipality pre-qualification.
Most installed capacity flows through Infrastructure. Expansion is steepest in Commercial.
Material:
Cost tier stratification separates commodity volume plays from specification-driven premium sourcing.
- Concrete:Ready-mix batching with 40-60 MPa compressive strength dominates residential cores and infrastructure substructures. Qatar Energy In-Country Value mandates favor domestic batching capacity, concentrating supply among pre-qualified local producers.
- Steel:Structural grades S355 and above capture share in commercial towers seeking reduced structural depths. Regional mill capacity constraints through the Strait of Hormuz create input price volatility that shapes procurement timing.
- Wood:Engineered timber and treated lumber serve interior fit-out and temporary works. Limited regional supply chains restrict wood to secondary applications outside primary structural systems.
- Glass:High-performance glazing with low solar heat gain coefficients satisfies QSAS cooling load thresholds. Gulf Organization for Research and Development certification limits supplier qualification to pre-approved envelope manufacturers.
Concrete commands the greatest tonnage. Glass is gaining specification intensity fastest.
Delivery Method:
Maturity gradient runs from traditional sequential phases toward integrated risk transfer models.
- Design-Bid-Build:Sequential architect-then-contractor procurement persists in standardized public infrastructure. Ministry of Municipality tendering protocols favor this method for transparency in sovereign-funded road and utility packages.
- Design-Build:Single-point accountability compresses schedules for complex hospitality and healthcare projects. Education City research facilities and Lusail mixed-use towers specify this method to collapse design-review cycles.
- Construction Management:Owner-retained risk with fee-based contractor oversight suits phased master developments. West Bay Lagoon district planning employs CM to coordinate multiple prime contractors across contiguous parcels.
- Integrated Project Delivery:Shared risk pools and collaborative BIM workflows target technically complex builds. Healthcare verticals with stringent MEP coordination requirements pilot this method for clash reduction.
Design-Bid-Build retains the largest contract value. Design-Build is displacing traditional methods fastest.
End User:
Customer type determines funding source, timeline pressure, and sustainability mandate intensity.
- Public Sector:Sovereign wealth-funded ministries and Qatar Foundation entities drive master-planned developments. QSAS enforcement and In-Country Value procurement rules shape vendor selection and material specification.
- Private Developers:Mixed-use and hospitality sponsors in Lusail and Doha prioritize pre-opening schedules over first-cost minimization. Hotel operators specify modular bathroom pods to eliminate wet-work sequencing conflicts.
- Contractors:Self-performed industrial builds by energy sector contractors cross-utilize offshore fabrication yards. McDermott and similar entities integrate EPC capabilities for captive project delivery.
- NGOs:Limited construction activity; occasional educational or cultural facility sponsorship through international institutions. Qatar Foundation partnerships absorb most non-commercial development capacity.
Public Sector channels the dominant funding flow. Private Developers are expanding procurement discretion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in Gulf construction flows toward jurisdictions with streamlined permitting and sovereign-backed project pipelines. Qatar's QSAS green building code and In-Country Value procurement rules create compliance costs that reshape contractor qualification and material sourcing decisions.
Doha Metropolitan Zone
The capital corridor concentrates hospitality and commercial tower demand around West Bay and the central business district. The Ministry of Municipality enforces QSAS sustainability ratings and solar reflectance index thresholds for roofing materials. Lusail's smart city corridor anchors integrated utility networks and district cooling systems across mixed-use parcels.
Al Wakrah Industrial Corridor
Energy-linked process facilities drive heavy civil and industrial construction south of the capital. Qatar Energy's In-Country Value program mandates local content preferences for steel fabrication and ready-mix concrete batching. The Mesaieed industrial zone hosts petrochemical and LNG-adjacent builds where contractors cross-utilize offshore fabrication heritage.
Education City Cluster
Knowledge-economy anchor institutions in Al Rayyan municipality drive specialized laboratory and research facility construction. Qatar Foundation entities demand 10-year operational guarantees from design-build consortia. The zone's stringent vibration and climate control specifications consolidate vendor qualification around integrated facility management contracts.
Northwestern Coastal Belt
Underdeveloped waterfront zones offer contiguous land parcels for integrated resort developments. The Gulf Organization for Research and Development cooling load metrics shape glazing and insulation specifications across hospitality projects. Al Khor and Ras Laffan municipalities host industrial capacity tied to hydrocarbon processing infrastructure.
Al Shamal Development Frontier
Northern municipalities present greenfield opportunities for residential master planning and tourism infrastructure. The Ministry of Municipality's phased QSAS enforcement extends design review cycles for envelope performance compliance. Low-density coastal areas attract marina-integrated developments seeking differentiation from Doha's saturated premium segment.
Qatar Construction Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with sovereign-funded master developments concentrating procurement among pre-qualified local entities. The vendor base stratifies into three tiers: state-backed conglomerates with operational scale, international EPC contractors with offshore fabrication heritage, and specialized subcontractors holding Ministry of Municipality pre-qualification. Design-Build compression favors single-point accountability models that collapse traditional sequential phases. Two dominant competitive moves reshape positioning: backward integration into captive steel fabrication and modular prefabrication convergence from energy sector capabilities.
Among state-backed developers, Qatari Diar Construction anchors premium residential and mixed-use pipelines through sovereign wealth-funded master planning. International contractors with offshore fabrication heritage include McDermott and Technip Energies, both occupying positions that cross-utilize energy sector capabilities for industrial and hospitality verticals. HBK Contracting Company exemplifies the heavy civil specialization archetype, dominating road, bridge, and infrastructure packages through decades of local operational scale and fleet capacity.
| Leading Market Players |
|---|
| McDermott |
| Qatari Diar Construction |
| HBK Contracting Company |
| Al Ali Engineering Co. W.L.L |
| Consolidated Contractors Company |
| Larsen & Toubro |
| Technip Energies |
| Al Jaber Engineering |
| Saipem |
| Others |
Value Chain & Pricing Dynamics
Steel price indices for structural grades S355 and above cascade through Qatar's construction value chain, compressing margins for contractors locked into fixed-price Design-Build contracts while amplifying pricing power for domestic batching operators favored by In-Country Value mandates.
Pricing Analysis
Contractor markup layers in Qatar's construction sector stratify across project delivery risk allocation, with Design-Build premiums capturing 15-25% above Design-Bid-Build baselines to account for single-point accountability and schedule compression. Price differentiation separates QSAS-certified envelope systems from commodity-grade alternatives, with Gulf Organization for Research and Development pre-certification acting as a tier gate. Pricing pressure stems from steel input volatility through Strait of Hormuz shipping constraints, forcing procurement timing arbitrage. Public sector ministries exhibit lowest price sensitivity due to sovereign funding backstops, while private hospitality developers face acute cost discipline around pre-opening deadlines.
Supply Chain Analysis
Qatar Energy's In-Country Value program is redirecting material sourcing toward domestic steel fabrication and ready-mix concrete batching capacity, reshaping procurement patterns across the emirate. Supply concentration draws from Saudi Arabia for rebar and structural sections, the UAE for MEP components and glazing systems, and Oman for aggregate and cementitious materials. Raw material dependencies center on imported billets for rebar production, specialized low-E glass coatings from European suppliers, and post-tensioning strand from Asian mills. Single-source vulnerability concentrates in Gulf Organization for Research and Development-certified envelope manufacturers, where pre-qualification limits supplier pools. Distribution runs through Ministry of Municipality pre-qualified contractor tiers with bonded fleet capacity and sovereign project track records.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's construction market offers margin expansion pathways through modular prefabrication adoption and QSAS premium-tier positioning, as Design-Build compression rewards contractors with integrated fabrication capabilities over pure-play generalists.
For Market Incumbents: Lock in captive steel fabrication capacity to defend against regional mill price volatility and secure In-Country Value compliance advantages. Deepen backward integration into ready-mix batching to capture margin pools currently flowing to third-party suppliers. The priority lever sits with modular bathroom pod production for hospitality verticals, where factory-integrated wet units eliminate on-site trade coordination risks and compress pre-opening schedules.
For New Entrants and Emerging Players: Capture white-space in Al Shamal Development Frontier's greenfield residential master planning, where lower land costs and phased QSAS enforcement create entry runway absent in Doha's saturated premium segment. Target integrated facility management contracts in Education City research facilities, where Qatar Foundation entities demand decade-long operational guarantees that favor specialized service bundling over pure construction plays. The penetrable angle runs through BIM-to-field coordination software and clash-detection services for Design-Build consortia facing compressed review cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where Ministry of Municipality pre-qualification requirements and fleet scale thresholds create barriers for sub-scale contractors unable to bid sovereign-funded infrastructure packages. The acquisition target archetype combines heavy civil operational scale with modular fabrication capabilities, positioning for cross-vertical expansion from energy-linked industrial builds into hospitality and healthcare. Watch steel price volatility through Strait of Hormuz shipping lane disruptions as the dominant inflection signal, with sustained input cost spikes accelerating contractor distress and M&A window opening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Steel Fabrication | Qatar Energy In-Country Value mandates reward domestic production capacity with procurement preference points. |
| Modular Prefabrication Convergence | Offshore fabrication heritage from McDermott-class contractors crosses into hospitality verticals with accelerated assembly. |
| QSAS Premium Certification Investment | Third-party sustainability verification extends project closeout timelines but commands pricing premiums from sovereign funders. |
| Integrated Facility Management Bundling | Qatar Foundation's 10-year operational guarantee demands consolidate vendor qualification around single-source accountability models. |
| Al Shamal Geographic Expansion | Greenfield northern municipalities offer contiguous land parcels with lower compliance density than Doha's saturated corridor. |
Study Parameters
Bottom-up project pipeline modeling reconciled against top-down contractor capacity tracking forms the analytical core of this study. Primary interviews with project directors at Qatari Diar and HBK Contracting, procurement officers at Qatar Foundation entities, Ministry of Municipality planning officials, and steel fabrication plant managers informed demand segmentation and pricing dynamics. Secondary validation drew from Qatar Central Bank construction sector indices, Qatar Energy In-Country Value program disclosures, Gulf Organization for Research and Development technical standards, and QSAS certification registry data.
Historical trendline analysis across project type, material specification, and delivery method dimensions established baseline growth patterns. The projection framework models residential, commercial, industrial, and infrastructure verticals alongside concrete, steel, glass, and wood material tiers, with Design-Build, Design-Bid-Build, Construction Management, and Integrated Project Delivery methods tracked separately. CAGRs derive from regression-adjusted pipeline values against contractor capacity constraints and regulatory enforcement timelines, with cooling load metric compliance costs and local content mandate penetration as key forecast inputs.
Steel price volatility through Hormuz shipping disruptions, QSAS enforcement acceleration, and sovereign wealth fund allocation shifts are the dominant revision risks to the outlook. Forecasts embed assumptions around Design-Build adoption rates and In-Country Value compliance thresholds. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Japan Commercial Construction Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Malaysia Construction Market
Building Construction
Thailand Construction Market
Building Construction
North America Modular Construction Market
Building Construction
Modular and Portable Building Market
Building Construction
Prefabricated Construction Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
Turkey Construction Market
Building Construction
Global Dry Construction Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
UK Construction Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Prefabricated Buildings Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
China Construction Market