
 SAS Hard Disk Drives Market | 2026-2036
SAS Hard Disk Drives Market Size, Share, and Industry Trends Forecast 2026-2036
SAS Hard Disk Drives Market Analytics
Japanese component suppliers is pivoting toward higher-density platter technologies to preserve SAS HDD relevance against solid-state encroachment. Seagate Technology plc leverages its vertically integrated Thailand manufacturing base to control spindle motor costs. Western Digital Technologies Inc anchors its SAS portfolio on helium-sealed enterprise drives for cloud service operators. Toshiba Electronic Devices & Storage Corporation differentiates through dual-stage actuator designs that improve seek performance in financial trading environments.
A SAS hard disk drive constitutes a rotating magnetic storage device employing serial attached SCSI signaling protocol, typically operating at rotational speeds of 10,000 or 15,000 RPM with 512n, 512e, or 4Kn sector formats to deliver sustained throughput exceeding 200 MB/s for transactional workloads. Enterprise HDD configurations dominate installed base value due to their fault-tolerant firmware and sustained duty cycle ratings, while Nearline HDD variants represent the volume growth vector as warm-tier storage expands in cloud architectures. The 12 Gbps interface speed category captures the majority of current shipments, though 24 Gbps adoption accelerates among financial institutions running low-latency analytics clusters.
FCC equipment authorization requirements govern SAS HDD electromagnetic emissions in US-deployed storage systems, while EU RoHS and REACH directives restrict hazardous substances in drive substrates and lubricants. Japan's METI energy efficiency standards shape idle power specifications for enterprise drives sold into domestic data centers. Stakeholders must monitor interface speed migration timelines and regional certification divergence to optimize inventory positioning across enterprise and cloud segments.
Market Dynamics
Enterprise data centers face a structural tension between sustaining legacy SAS infrastructure and migrating to NVMe-over-Fabrics architectures, forcing HDD manufacturers to extract maximum performance from rotating media while preserving backward compatibility.
Growth Catalysts
- EU F-Gas Regulation:The directive mandates energy-efficient cooling for storage infrastructure, extending SAS HDD refresh cycles in Frankfurt and Amsterdam hyperscale facilities.
- Financial trading floors:Low-latency analytics clusters in London and Singapore sustain procurement of 15,000 RPM drives for transactional databases.
- Helium-sealed manufacturing:The process enables seven-platter densities that preserve SAS relevance against flash encroachment in warm-tier cloud storage.
Market Restraints
- Neodymium price volatility:Rare earth magnet costs fluctuate with Chinese export quotas, compressing spindle motor margins for drive assemblers.
- Single-source substrate dependency:Japanese glass-ceramic platter suppliers concentrate 70% of high-specification media output, creating geographic vulnerability.
- Solid-state substitution:QLC NAND price declines below $0.05 per gigabyte displace SAS HDDs in tier-one enterprise workloads.
Strategic Opportunities
- India's data localization mandate:The RBI and MeitY directives force global cloud operators to build domestic facilities, opening nearline HDD volume.
- 24 Gbps interface adoption:The protocol upgrade converges with computational storage controllers to enable in-drive analytics for edge deployments.
- Secondary market refurbishment:Certified pre-owned channels emerge for 12 Gbps drives retired from US financial services, extending asset lifecycles.
Industry Challenges
- Actuator servo firmware expertise:The talent pool for dual-stage positioning algorithms concentrates at Toshiba and legacy IBM sites, constraining new entrants.
- RoHS substance compliance:REACH restrictions on hexavalent chromium platings force substrate chemistry requalification timelines exceeding eighteen months.
- Legacy SAS-2 integration:Backward compatibility testing for 6 Gbps controllers in German automotive manufacturing extends product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SAS Hard Disk Drives Market |
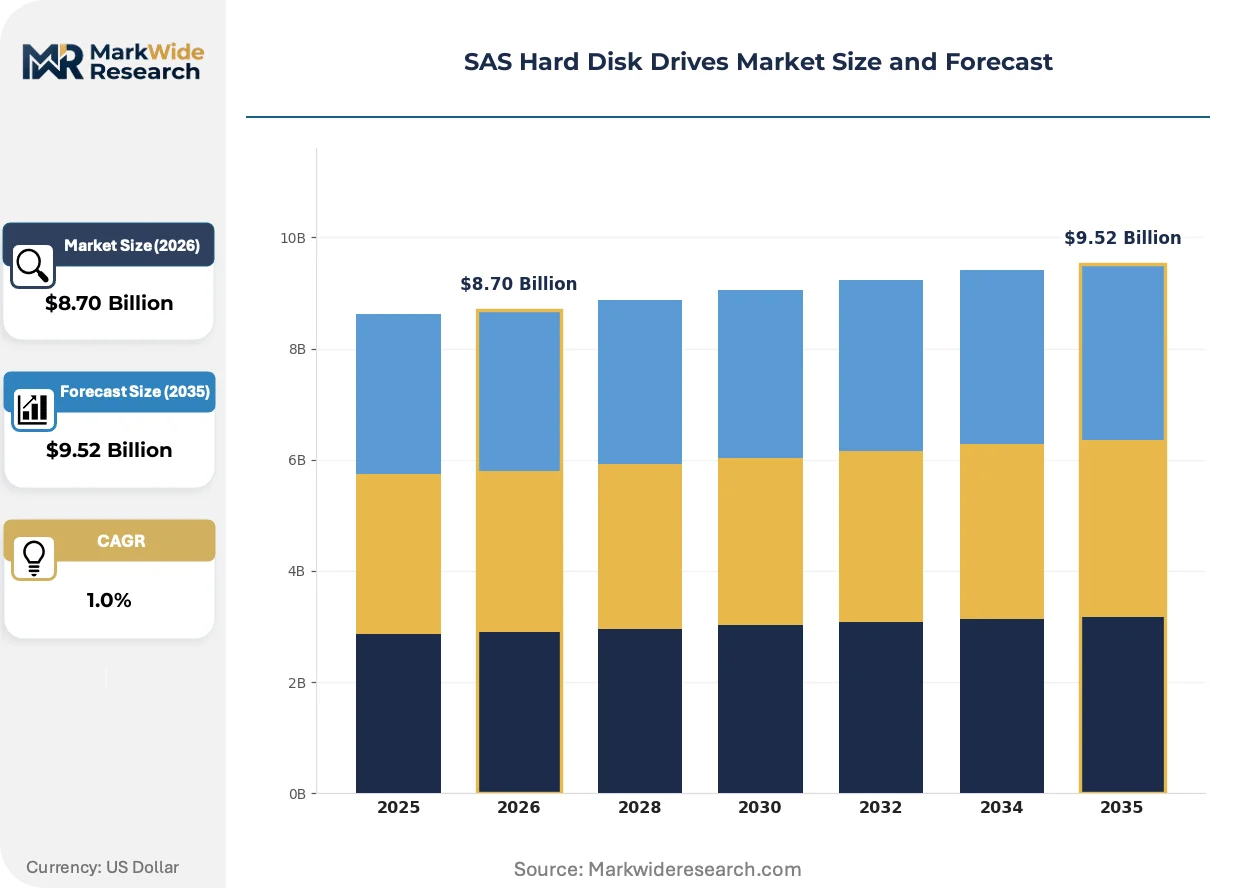
| Market Size in 2026 | $8.70 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise HDD, Nearline HDD, Archival HDD, Data Center HDD, High-Performance HDD Interface Speed: 6 Gbps, 12 Gbps, 24 Gbps, 48 Gbps, 60 Gbps Application: Data Storage Systems, Cloud Storage, Video Surveillance, Big Data Analytics, Backup & Recovery End User: Telecom Service Providers, Cloud Service Operators, Media & Entertainment, Financial Institutions, Government Agencies |
| Companies Covered | Toshiba Electronic Devices & Storage Corporation, Seagate Technology plc, Western Digital Technologies Inc, Fujitsu, Hitachi, HP, Dell, Quantum Corporation, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SAS Hard Disk Drives Market Evolving Landscape
Mechanical storage engineering is undergoing a precision manufacturing renaissance as vendors extract final performance increments from rotating media before physical limits intervene.
Dual-stage actuator architectures are decentralizing seek performance optimization across financial services and high-frequency trading environments. The technology splits head positioning into coarse and fine motion layers. Hedge funds in Chicago and proprietary trading desks in Hong Kong deploy these drives for microsecond-order latency advantages. The structural consequence is decentralizing performance differentiation away from interface bandwidth toward mechanical precision.
Japan's METI energy efficiency standards are tightening idle power specifications for enterprise drives sold into domestic data centers. The regulation mandates sub-7 watt idle consumption for 3.5-inch form factors. Domestic operators in Osaka and Tokyo retrofit existing arrays rather than full replacement, compressing near-term shipment volumes while extending service contract durations.
Hyperscale procurement patterns are consolidating around direct-to-manufacturer agreements that bypass traditional distribution. Cloud operators in Virginia and Texas negotiate multi-year volume commitments with Seagate and Western Digital. The channel compression is most visible in the United States, where distributor inventory for enterprise SKUs has declined sharply.
SAS Hard Disk Drives Market Segmentation
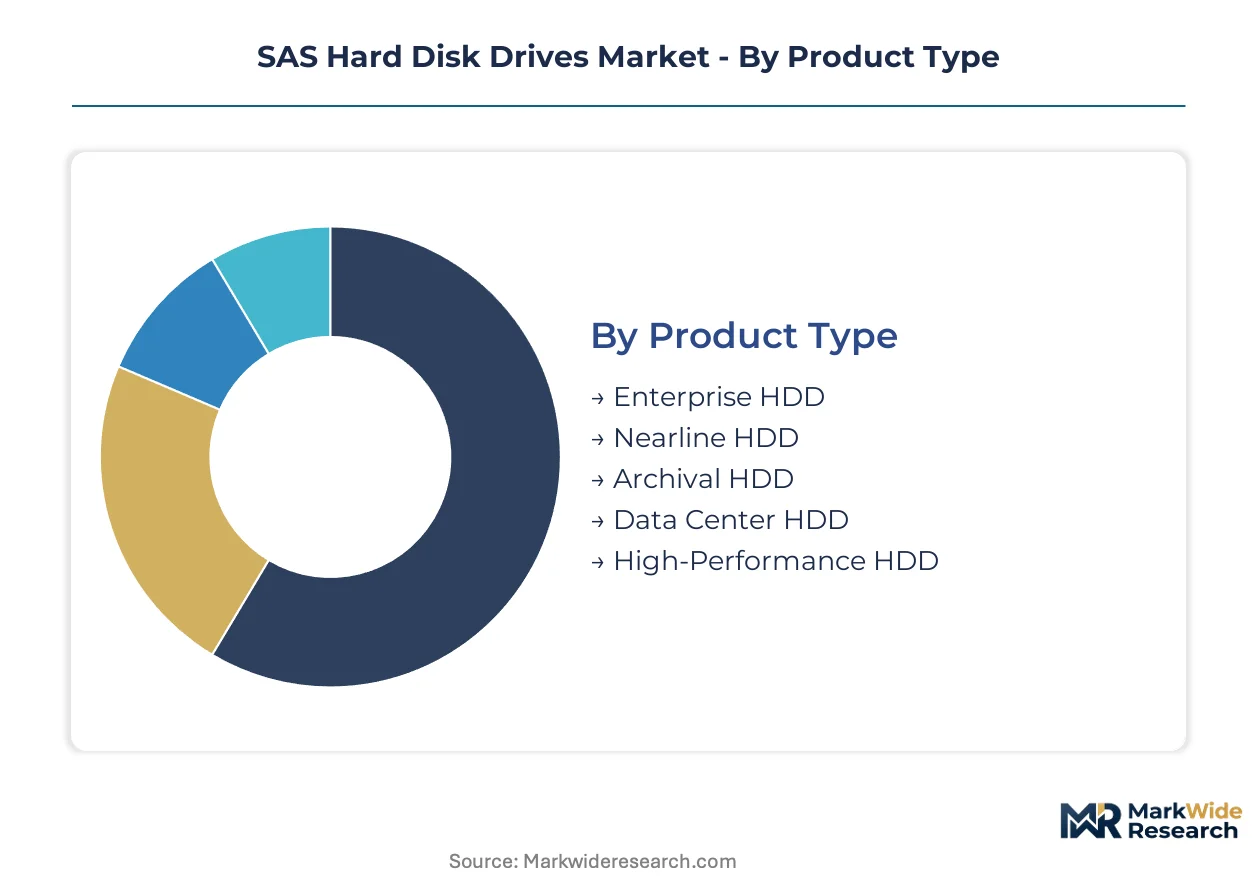
SAS HDD procurement patterns diverge sharply across workload intensity, interface maturity, and compliance requirements. Each segmentation axis reveals distinct buyer priorities that reshape supplier positioning and channel economics.
Product Type:
Buyers in this category separate by duty cycle demands and fault-tolerance requirements rather than unit price sensitivity.
- Enterprise HDD:Rotating magnetic storage rated for 24/7 operation with error-correction firmware optimized for transactional databases. Financial trading floors in Chicago and London sustain procurement of 15,000 RPM variants despite flash encroachment.
- Nearline HDD:Seven-platter helium-sealed designs delivering 7200 RPM operation with lower power envelopes for warm-tier cloud storage. Hyperscale facilities in Virginia and Texas anchor replacement cycles as these drives displace tape in secondary storage hierarchies.
- Archival HDD:Cold-storage-optimized firmware with aggressive spin-down protocols for compliance-mandated retention. Energy efficiency standards in Japan's Osaka data centers compress shipment volumes while extending service contracts.
- Data Center HDD:Standardized SKUs for multi-tenant colocation environments with uniform firmware stacks. India's RBI data localization mandates force domestic facility buildouts that open volume opportunities.
- High-Performance HDD:Dual-stage actuator variants targeting microsecond-order latency in high-frequency trading clusters. Singapore's proprietary trading desks sustain niche demand despite QLC NAND price pressure.
Volume sits with Nearline HDD; growth tilts toward Enterprise HDD as financial institutions delay full flash migration.
Interface Speed:
Migration timelines in this category track controller refresh cycles and backward compatibility testing burdens.
- 12 Gbps:Current shipment majority with mature controller ecosystems and broad SAS-3 ecosystem compatibility. German automotive manufacturing extends validation cycles for legacy integration requirements.
- 24 Gbps:Accelerating adoption among London and Singapore financial institutions running low-latency analytics clusters. Computational storage controllers converge with this protocol upgrade to enable in-drive edge analytics.
- 6 Gbps:Declining installed base in legacy enterprise arrays approaching end-of-service life. Refurbishment channels in US financial services extend asset lifecycles through certified pre-owned programs.
- 48 Gbps:Emerging specification targeting next-generation computational storage architectures with in-drive processing capabilities. Standards body activity concentrates in IEEE working groups.
- 60 Gbps:Laboratory-phase signaling protocol for future high-density platter technologies. Japanese component suppliers anchor R&D investment against solid-state substitution.
Deployment concentrates at 12 Gbps; steepest expansion trajectory belongs to 24 Gbps as financial workloads demand bandwidth headroom.
Application:
Workload characteristics determine capacity-per-spindle requirements and rotational speed tradeoffs.
- Data Storage Systems:General-purpose enterprise arrays with mixed workload support. Frankfurt hyperscale facilities extend refresh cycles under EU F-Gas Regulation cooling mandates.
- Cloud Storage:Warm-tier object and block storage with throughput-optimized sequential access patterns. Direct manufacturer agreements bypass traditional distribution channels in Texas and Virginia.
- Video Surveillance:Write-intensive continuous recording with high-capacity nearline drives. Compliance retention periods vary by municipal jurisdiction.
- Big Data Analytics:Sequential scan workloads favoring high-density helium-sealed architectures. Hadoop and Spark clusters in cloud environments drive petabyte-scale procurement.
- Backup & Recovery:Deduplication-optimized storage with idle power sensitivity. Japan's METI sub-7 watt specifications reshape domestic product qualifications.
Cloud Storage commands the largest addressable base; Backup & Recovery gains share fastest as ransomware protection mandates expand.
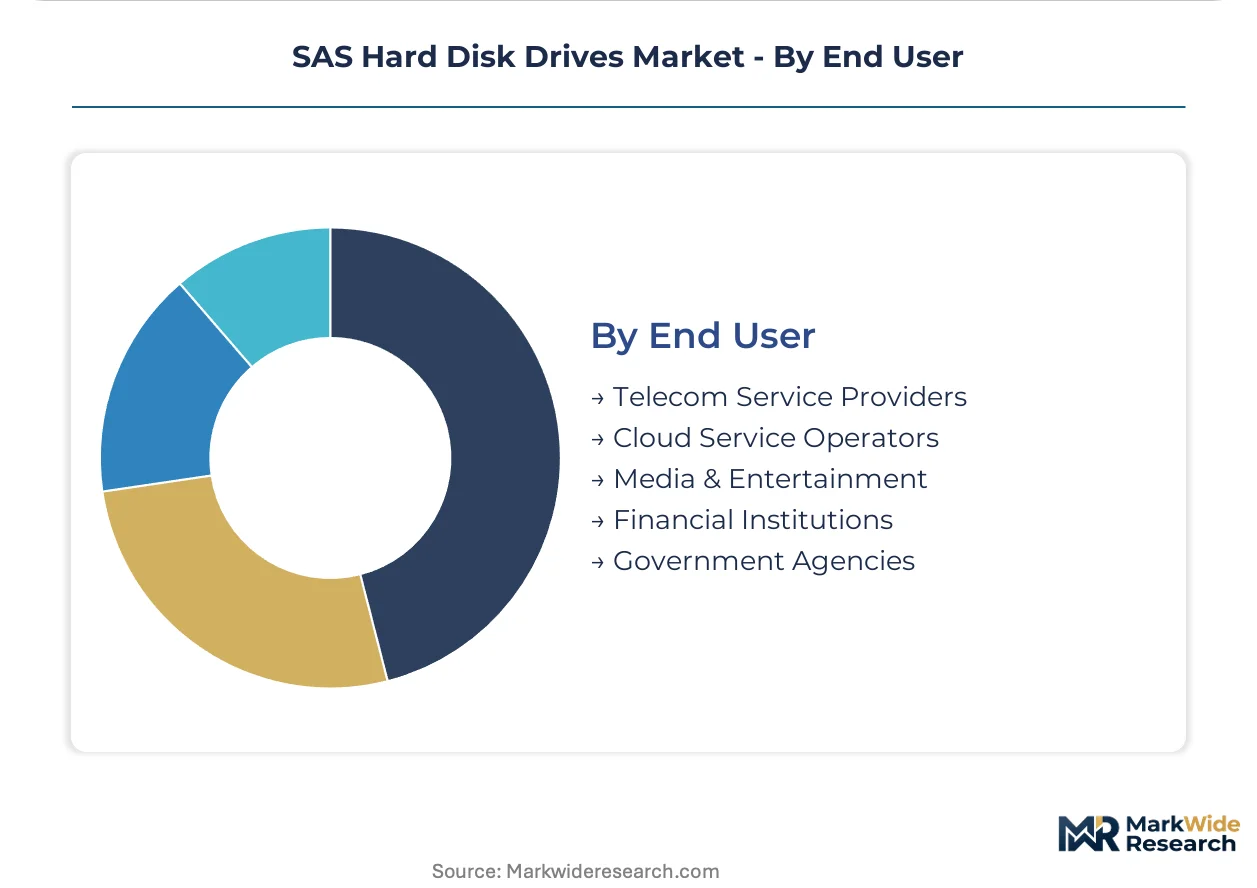
End User:
Budget authority and procurement sophistication separate buyers in this final segmentation axis.
- Cloud Service Operators:Volume purchasers negotiating multi-year supply agreements with direct manufacturer engagement. Hyperscale procurement consolidation compresses distributor inventory for enterprise SKUs.
- Financial Institutions:Latency-sensitive buyers prioritizing 15,000 RPM and dual-stage actuator technologies. Chicago hedge funds and Hong Kong trading desks sustain premium pricing for mechanical precision.
- Government Agencies:Compliance-driven procurement with domestic content requirements and extended validation timelines. US federal data centers anchor replacement cycles with security-hardened firmware specifications.
- Telecom Service Providers:Edge deployment specialists balancing capacity density with power envelope constraints. 5G infrastructure buildouts drive distributed storage node requirements.
- Media & Entertainment:Sequential throughput-dependent workflows for content rendering and distribution. Post-production facilities in Los Angeles and London concentrate demand for high-capacity nearline configurations.
Cloud Service Operators dominate procurement volume; Financial Institutions retain the highest willingness-to-pay for performance differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing in Chinese Inner Mongolia anchors spindle motor supply chains for SAS HDD assembly. Japanese glass-ceramic substrate manufacturing concentrates high-specification media output. German automotive and industrial automation clusters sustain legacy SAS-2 integration demand.
United States
Hyperscale cloud operators in Virginia and Texas negotiate multi-year volume commitments directly with manufacturers. FCC equipment authorization requirements govern electromagnetic emissions for storage systems deployed domestically. Government data centers in Maryland and Colorado anchor replacement cycles with security-hardened firmware specifications.
Japan
Domestic data center operators in Osaka and Tokyo retrofit existing arrays under METI energy efficiency mandates. Sub-7 watt idle consumption specifications for 3.5-inch form factors compress near-term shipment volumes. Component suppliers in the Chubu region pivot toward higher-density platter technologies.
Germany
Automotive manufacturing facilities in Bavaria extend validation cycles for backward compatibility with 6 Gbps SAS-2 controllers. EU F-Gas Regulation mandates energy-efficient cooling for Frankfurt hyperscale facilities. Industrial automation clusters in Baden-Württemberg sustain procurement of fault-tolerant enterprise configurations.
United Kingdom
Financial trading floors in London sustain procurement of 15,000 RPM drives for low-latency transactional databases. 24 Gbps interface adoption accelerates among analytics clusters serving hedge funds and proprietary trading desks. Compliance-driven procurement patterns favor established supplier relationships.
Singapore
Proprietary trading desks and regional financial institutions anchor demand for dual-stage actuator designs. Low-latency requirements in Southeast Asian financial hubs sustain premium positioning for mechanical precision. Regional data center buildouts serve as distribution nodes for Asia-Pacific cloud expansion.
SAS Hard Disk Drives Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and component specialization. The vendor base concentrates around vertically integrated platter fabricators and precision spindle motor assemblers. Three archetypes dominate: integrated storage technology conglomerates, precision component specialists, and legacy system integrators with captive drive programs. Competitive moves center on helium-sealed manufacturing process licensing and direct-to-hyperscale procurement channel compression.
Within the integrated technology tier, Seagate Technology plc, Western Digital Technologies Inc, and Toshiba Electronic Devices & Storage Corporation exemplify full-stack control from substrate chemistry to firmware development. These entities occupy positions defined by captive supply of critical components rather than external procurement dependence. Their geographic distribution spans North American and Asian manufacturing clusters, reflecting historical consolidation patterns in precision mechanical storage engineering.
| Leading Market Players |
|---|
| Toshiba Electronic Devices & Storage Corporation |
| Seagate Technology plc |
| Western Digital Technologies Inc |
| Fujitsu |
| Hitachi |
| HP |
| Dell |
| Quantum Corporation |
| IBM |
| Others |
Value Network & Pricing Analysis
Neodymium oxide price volatility in Chinese export markets cascades through spindle motor manufacturing into three distinct SAS HDD pricing tiers, with rare earth magnet cost fluctuations compressing margins for 15,000 RPM enterprise drives while helium-sealed nearline configurations absorb input pressure through volume scale.
Pricing Analysis
Warranty bundling separates premium enterprise SKUs from standard nearline and economy archival tiers, with five-year service contracts commanding substantial markups over bare-drive transactions. Price differentiation rests on rotational speed certification and dual-stage actuator precision, with financial trading floors in Chicago and Singapore exhibiting minimal price sensitivity compared to hyperscale cloud operators in Virginia and Texas. Cost compression in the nearline segment is intensifying because QLC NAND price erosion below flash crossover thresholds forces HDD vendors to defend warm-tier positioning through aggressive spindle density investments. Cloud Service Operators dominate procurement volume with extreme price sensitivity, while Financial Institutions retain the highest willingness-to-pay for mechanical latency advantages.
Supply Chain Analysis
India's data localization mandates and domestic-content requirements for government storage tenders are reshaping component sourcing patterns, forcing assembly partners to establish local spindle motor winding and substrate finishing capabilities. Manufacturing gravity centers on Thailand for vertically integrated drive assembly, Japan for glass-ceramic platter substrates and dual-stage actuator servo firmware, and Chinese Inner Mongolia for rare earth magnet processing. Raw material dependencies span neodymium-iron-boron magnet alloys, high-purity helium for seven-platter sealing, and aluminum-magnesium substrate alloys. Single-source vulnerability concentrates in Japanese glass-ceramic suppliers controlling high-specification media output. Distribution runs through direct manufacturer agreements with hyperscale operators, bypassing traditional channel inventory for enterprise SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAS HDD procurement sits at a technology-transition inflection point, with NVMe-over-Fabrics architectures displacing legacy rotating media in tier-one enterprise workloads and forcing incumbent vendors to extract final performance increments from mechanical engineering.
For Market Incumbents: To counter QLC NAND price erosion below flash substitution thresholds, Seagate and Western Digital should deepen captive supply of helium-sealed seven-platter substrates through backward integration into Thai manufacturing, while Toshiba must extend dual-stage actuator firmware licensing to preserve servo algorithm differentiation against computational storage controllers. For New Entrants and Emerging Players: Enter via India's data localization mandate, where RBI and MeitY directives force domestic facility buildouts without established supplier relationships, targeting Data Center HDD standardization for multi-tenant colocation operators lacking legacy array investments, with a go-to-market angle centered on certified pre-owned 12 Gbps channel partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision component specialists in Japan's Chubu region with captive platter substrate capabilities, as the long-term viability window for mechanical storage narrows toward archival and warm-tier niches; the signal to watch is 24 Gbps controller adoption velocity among London financial institutions as a proxy for interface refresh durability.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Sealed Manufacturing Scale-Up | Seven-platter densities preserve SAS relevance against flash encroachment in cloud warm tiers. |
| Dual-Stage Actuator Firmware Licensing | Toshiba's servo algorithms extend mechanical precision differentiation in high-frequency trading. |
| 24 Gbps Interface Controller Partnership | Protocol convergence with computational storage enables in-drive edge analytics for financial clusters. |
| Certified Pre-Owned Channel Development | Secondary market refurbishment extends 12 Gbps asset lifecycles in US financial services. |
| India Domestic Assembly Footprint | Data localization mandates force local spindle motor winding and substrate finishing capabilities. |
Research Methodology
Document review covered SEC 10-K filings from drive manufacturers, EU F-Gas Regulation implementation guidance, and Japan METI energy efficiency standards, complemented by interviews with data center infrastructure directors, enterprise storage procurement managers, hyperscale capacity planning officers, and precision component engineering leads. Secondary validation drew from customs trade data for rare earth magnet flows, FCC equipment authorization databases, and IEEE standards working group proceedings. Bottom-up shipment modeling triangulated against top-down enterprise storage capex disclosures.
Unit shipment and revenue estimates emerged from segment-level modeling across product type, interface speed, application workload, and end-user procurement sophistication dimensions throughout the projection horizon. CAGRs were derived from replacement cycle analysis weighted by installed base vintage and interface migration timelines. Industry-specific forecast inputs incorporated neodymium price elasticity assumptions and helium supply contract durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt QLC NAND price collapse or accelerated EU cooling efficiency mandates. Forecasts reflect documented assumptions regarding interface speed adoption curves and cloud procurement consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
External Storage Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
USB Key Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
Universal Flash Storage Market
Data Storage
NAND Flash Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Enterprise Storage System Market
Data Storage
Multiprotocol Storage Market
Data Storage
SSD Controller Market
Data Storage
Storage Class Memory Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Middle East Data Center Storage Market