
 Global Pin Fin Heat Sink for IGBT Market | 2026-2036
Global Pin Fin Heat Sink for IGBT Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pin Fin Heat Sink for IGBT Market Outlook
Distributor networks serving industrial semiconductor buyers is rewriting procurement geography across the thermal management sector. Boyd Corporation leverages captive extrusion capabilities to anchor North American supply chains for IGBT cooling assemblies. Wakefield-Vette competes through specialized aluminum forging operations that dominate mil-aerospace pin fin specifications. Advanced Thermal Solutions differentiates via computational fluid dynamics services bundled with custom heat sink design.
A pin fin heat sink for IGBT comprises an array of cylindrical or tapered protrusions machined or extruded from aluminum or copper substrates, engineered to maximize surface area-to-volume ratio for convective heat dissipation from insulated-gate bipolar transistor modules operating at junction temperatures exceeding 150°C. Passive heat sinks retain the largest installed base across motor control applications, while liquid cooling solutions capture expanding margin pools in high-frequency power inverter installations. Thermal interface materials represent the fastest-growing product category as silicone-based phase-change compounds displace traditional grease formulations in renewable energy systems.
REACH substance restrictions and RoHS compliance requirements in Europe constrain solder alloy selections and surface finish chemistries for heat sink assemblies. China's GB standards and MIIT energy efficiency directives mandate minimum thermal resistance benchmarks for industrial power electronics. EPA industrial emissions guidelines in the United States shape foundry sourcing decisions for aluminum extrusion feedstock. Stakeholders must monitor evolving semiconductor packaging form factors and corresponding pin fin array geometries to maintain design relevance.
Market Dynamics
Electric vehicle powertrain thermal density requirements are compressing design cycles for IGBT cooling assemblies, forcing heat sink suppliers to synchronize development timelines with semiconductor packaging roadmaps rather than traditional automotive tier schedules.
Growth Catalysts
- China MIIT energy efficiency mandates:Minimum thermal resistance benchmarks for industrial power electronics are accelerating aluminum alloy heat sink deployment across motor control installations.
- Silicone-based phase-change compounds:These materials are displacing traditional thermal grease formulations in renewable energy inverters, expanding the thermal interface materials category.
- Germany's automotive semiconductor corridor:Concentrated demand from powertrain manufacturers is scaling orders for high-density pin fin arrays serving traction inverter modules.
Market Restraints
- Aluminum extrusion feedstock volatility:EPA industrial emissions guidelines constrain foundry sourcing decisions in the United States, tightening primary metal supply channels.
- Copper-to-aluminum substitution ceiling:Junction temperatures exceeding 150°C in high-frequency applications preserve copper substrate requirements despite cost pressures.
- REACH substance restrictions:Solder alloy selections and surface finish chemistries face constrained formulation options across European assembly operations.
Strategic Opportunities
- Japan's precision manufacturing belt:Advanced machining capabilities for tapered pin geometries remain underexploited by foreign heat sink suppliers.
- Dual carbon goals compliance:China's national targets create procurement preference for low-carbon aluminum extrusion in state-backed renewable energy projects.
- Liquid cooling convergence:Integration of pin fin arrays with cold plate architectures opens margin pools in high-frequency power inverter installations.
Industry Challenges
- Computational fluid dynamics talent scarcity:Custom heat sink design services require specialized thermal simulation expertise that outpaces vocational training pipelines.
- Semiconductor packaging form factor volatility:Evolving IGBT module geometries force continuous retooling of pin fin array configurations without standardized interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pin Fin Heat Sink for IGBT Market |
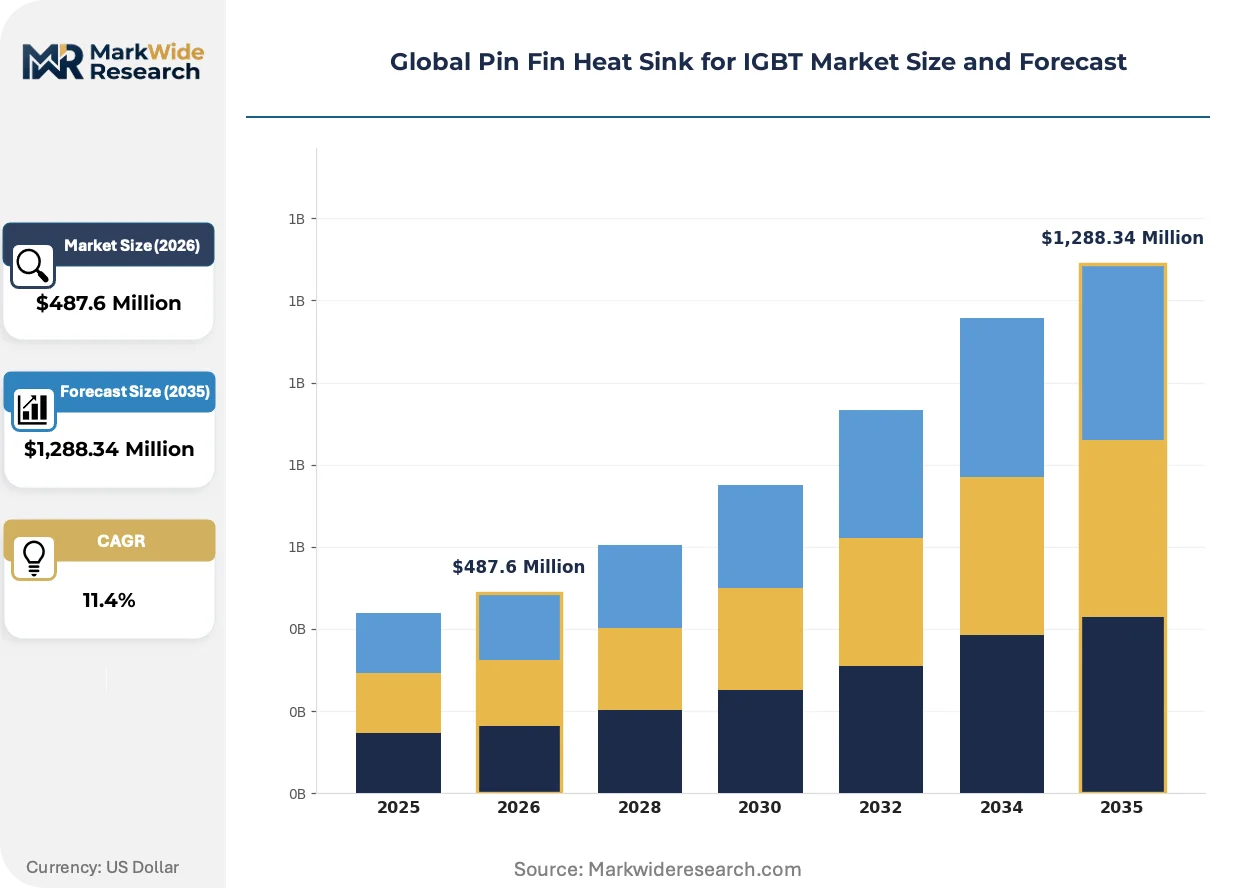
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Heat Sinks, Passive Heat Sinks, Liquid Cooling Solutions, Thermal Interface Materials Industry Vertical: Automotive, Aerospace, Industrial Equipment, Renewable Energy Application: Motor Control, Power Inverters, Welding Equipment, Renewable Energy Systems End User: Manufacturers, Distributors, Aftermarket Providers, OEMs |
| Companies Covered | Advanced Thermal Solutions, Aavid Thermalloy, Boyd Corporation, Apex Microtechnology, Honeywell International, Fischer Elektronik, Wakefield-Vette, CUI Devices, Kunshan Googe Metal Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pin Fin Heat Sink for IGBT Market Strategic Shifts
Thermal management architectures are bifurcating between passive air-cooled dominance in cost-sensitive motor control and liquid-cooled premiumization in power-dense electrification platforms. Three developments are reconfiguring competitive positioning.
Additive manufacturing of aluminum lattice structures is collapsing the tooling cost barrier for low-volume custom pin fin geometries. Aerospace and defense contractors in the United States are piloting electron beam melting for tapered fin arrays that conventional extrusion cannot achieve. This capability is collapsing minimum order quantity thresholds that previously excluded mid-tier industrial buyers from application-specific designs.
REACH authorization requirements for hexavalent chromium surface finishes are tightening compliance timelines for European heat sink suppliers. The restriction is redirecting plating chemistry investments toward trivalent alternatives and plasma electrolytic oxidation processes. German automotive semiconductor buyers are now mandating RoHS-compliant surface treatments in supplier qualification protocols.
Power electronics OEMs are consolidating vendor panels and demanding bundled thermal simulation services alongside physical heat sink supply. Japanese precision manufacturers are responding with captive CFD engineering teams that embed thermal modeling into early-stage customer co-development. This pattern is most visible in traction inverter programs where junction temperature guarantees carry warranty liability back to the heat sink supplier.
Global Pin Fin Heat Sink for IGBT Market Segmentation
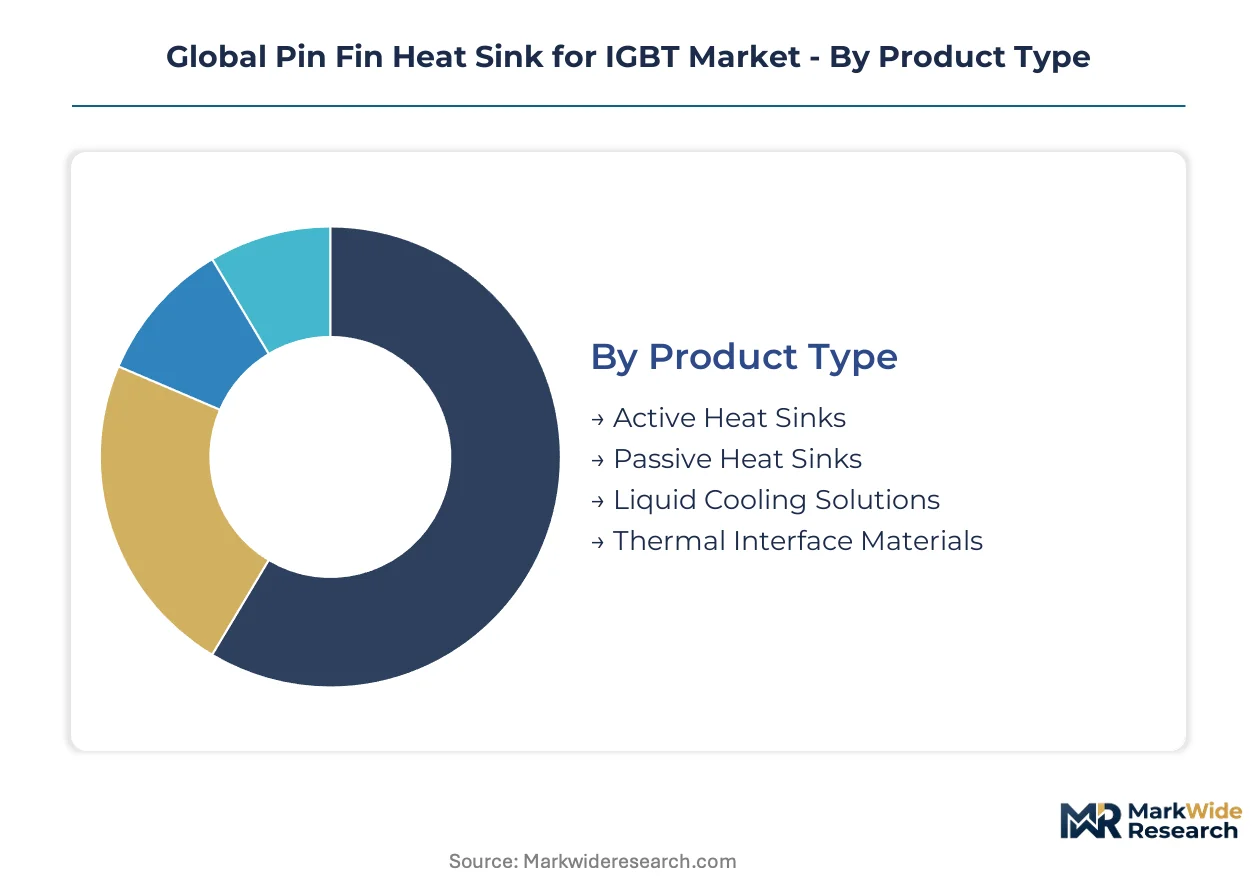
Pin fin heat sink procurement patterns diverge sharply across cooling architectures and end-use thermal densities. Semiconductor packaging roadmaps and electrification timelines reshape segment priorities faster than traditional industrial procurement cycles.
Product Type:
Mature passive configurations dominate installed base economics while emerging liquid architectures capture premium electrification applications.
- Passive Heat Sinks:Aluminum extruded arrays with cylindrical or tapered pin geometries maximize surface area-to-volume ratios for convective dissipation. Motor control installations across Germany's automotive semiconductor corridor sustain volume demand despite junction temperature limitations.
- Liquid Cooling Solutions:Cold plate-integrated pin fin architectures circulate dielectric fluid through precision-machined aluminum channels. High-frequency power inverter deployments in China's state-backed renewable energy projects are compressing design cycles for these assemblies.
- Thermal Interface Materials:Silicone-based phase-change compounds displace traditional grease formulations in traction inverter modules.
- Active Heat Sinks:Forced-air configurations with integrated blowers serve cost-sensitive industrial motor drives.
Passive Heat Sinks retain volume leadership; Liquid Cooling Solutions hold the steepest expansion curve.
Industry Vertical:
Cost tier stratification separates automotive electrification premiums from industrial equipment standardization.
- Automotive:Traction inverter thermal density requirements exceed 150°C junction temperatures, mandating high-conductivity aluminum alloys or copper substrates. Powertrain manufacturers in Japan's precision manufacturing belt are scaling orders for application-specific pin fin geometries.
- Renewable Energy:Utility-scale inverters and energy storage power conditioning systems demand scalable thermal architectures. China's MIIT energy efficiency mandates are accelerating aluminum alloy heat sink deployment across photovoltaic and wind installations.
- Industrial Equipment:Motor drives and welding power supplies prioritize cost-optimized extruded designs.
- Aerospace:Mil-aerospace specifications require specialized aluminum forging operations with tapered pin arrays.
Automotive commands premium pricing tiers; Renewable Energy is climbing fastest on policy-backed procurement.
Application:
Customer type bifurcation separates OEM co-development programs from aftermarket replacement economics.
- Power Inverters:DC-AC conversion modules in electric vehicle powertrains and renewable energy systems generate concentrated demand for liquid-cooled pin fin assemblies. German automotive semiconductor buyers now mandate bundled CFD thermal simulation services alongside physical supply.
- Motor Control:Variable frequency drives and servo systems sustain passive heat sink volumes through standardized extrusion platforms. Industrial equipment OEMs in the United States consolidate vendor panels to secure captive extrusion capabilities.
- Renewable Energy Systems:Photovoltaic inverters and battery energy storage thermal management require scalable modular designs.
- Welding Equipment:Resistance and arc welding power supplies utilize cost-optimized air-cooled configurations.
Motor Control sustains the broadest installed base; Power Inverters are gaining share fastest on electrification capex.
End User:
Supply concentration patterns favor direct OEM relationships over fragmented distribution channels.
- OEMs:Original equipment manufacturers in automotive and renewable energy verticals drive specification authority through early-stage thermal co-development. Japanese precision manufacturers embed captive CFD engineering teams to guarantee junction temperature performance.
- Manufacturers:Heat sink fabricators serving tier-two industrial buyers face compressed margins on standardized extrusion platforms.
- Distributors:Industrial semiconductor buyers in North America are rewriting procurement geography through consolidated distributor networks.
- Aftermarket Providers:Replacement thermal assemblies for legacy motor control installations compete on lead time and inventory depth.
OEMs control specification authority; Distributors are expanding fastest on procurement consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port complex underwrites China's dominance in aluminum extrusion feedstock logistics, anchoring Asia-Pacific supply chains for IGBT thermal management components. Germany's Rhine-Main corridor channels precision-machined heat sink assemblies across European automotive networks. Japan's Nagoya manufacturing belt concentrates high-tolerance pin fin fabrication for traction inverter programs.
China
MIIT energy efficiency mandates and dual carbon goals are accelerating aluminum alloy heat sink deployment across photovoltaic and wind installations. GB standards establish minimum thermal resistance benchmarks for industrial power electronics. The Yangtze River Delta concentrates extrusion capacity serving state-backed renewable energy procurement.
Germany
Automotive powertrain thermal density requirements are scaling orders for high-density pin fin arrays in traction inverter modules. REACH substance restrictions and RoHS compliance constrain solder alloy selections and surface finish chemistries. The automotive semiconductor corridor between Stuttgart and Munich anchors specification authority for European IGBT cooling assemblies.
Japan
Precision manufacturing capabilities for tapered pin geometries remain concentrated in industrial clusters serving electrification platforms. METI industrial efficiency directives shape procurement standards for high-frequency power electronics. The Chubu region around Nagoya embeds captive CFD engineering teams into early-stage customer co-development programs.
United States
EPA industrial emissions guidelines constrain foundry sourcing decisions for aluminum extrusion feedstock, tightening primary metal supply channels. The Inflation Reduction Act provisions accelerate domestic content requirements for renewable energy thermal management components. Aerospace and defense contractors in the Southwest are piloting additive manufacturing for lattice structures that conventional extrusion cannot achieve.
South Korea
Power electronics OEMs are consolidating vendor panels for bundled thermal simulation services alongside physical heat sink supply. MFDS-equivalent industrial standards govern semiconductor packaging thermal performance specifications. The Seoul Capital Area concentrates design engineering for liquid-cooled pin fin architectures in high-frequency inverter installations.
Global Pin Fin Heat Sink for IGBT Market Competitive Environment
On the supply side, the industry is tiered between captive extrusion operators, specialized forging houses, and design-engineering specialists. The vendor base separates into three strategic archetypes: aluminum alloy fabricators with backward integration into extrusion feedstock, precision machining specialists serving mil-aerospace specifications, and CFD-enabled engineering houses bundling simulation with physical supply. Dominant competitive moves include geographic expansion through distributor network consolidation and technology licensing for additive manufacturing capabilities.
Among North American fabricators, Boyd Corporation and Wakefield-Vette occupy positions across different competitive vectors. Boyd Corporation exemplifies the captive extrusion archetype with in-house aluminum feedstock control. Wakefield-Vette represents specialized forging operations serving precision specifications. Advanced Thermal Solutions anchors the engineering-services tier, differentiating through bundled computational fluid dynamics capabilities. These three companies collectively illustrate the strategic segmentation governing procurement decisions across automotive, renewable energy, and aerospace verticals.
| Leading Market Players |
|---|
| Advanced Thermal Solutions |
| Aavid Thermalloy |
| Boyd Corporation |
| Apex Microtechnology |
| Honeywell International |
| Fischer Elektronik |
| Wakefield-Vette |
| CUI Devices |
| Kunshan Googe Metal Products |
| Others |
Value Chain & Pricing Dynamics
The Qingdao port complex freight corridors channel aluminum extrusion feedstock cost volatility directly into downstream pricing power for heat sink fabricators, compressing margins for distributors serving fragmented industrial buyers while amplifying negotiation leverage for OEMs consolidating vendor panels.
Pricing Analysis
Volume-discount tiering structures stratify across premium liquid-cooled assemblies, standard passive extruded arrays, and economy-grade motor control configurations. Price differentiation hinges on REACH-compliant surface finish certification and captive extrusion capability, with automotive powertrain OEMs exhibiting lowest sensitivity due to junction temperature warranty liabilities. Cost compression in standard passive tiers is intensifying as Chinese aluminum alloy producers expand Yangtze River Delta capacity. Industrial equipment distributors face acute price sensitivity amid vendor panel consolidation.
Supply Chain Analysis
Upstream aluminum billet and copper cathode feedstock sourcing draws from China, Germany, and the United States, with secondary machining concentrated in Japan's Nagoya belt and South Korea's Seoul Capital Area. Raw material dependencies span 6061-T6 aluminum alloy, C11000 copper substrate, and silicone-based thermal interface compounds. Single-source vulnerability persists in precision-machined cold plate channels for liquid cooling architectures. Distribution runs through captive OEM direct relationships and consolidated North American distributor networks serving tier-two industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
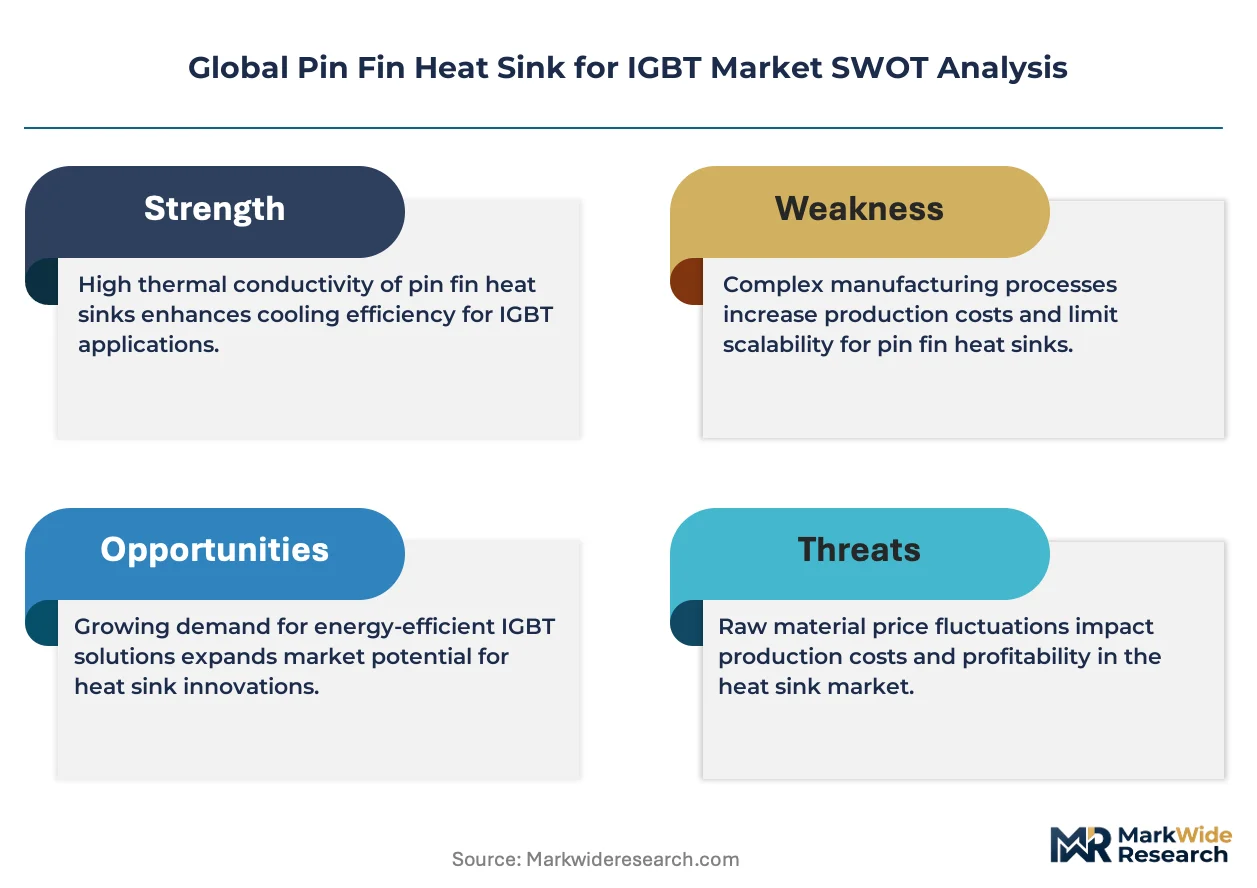
Incumbents face substitution defense imperatives as additive manufacturing of aluminum lattice structures threatens conventional extrusion economics for low-volume custom geometries.
For Market Incumbents: Pre-empt additive manufacturing disruption by licensing electron beam melting capabilities from Southwest US aerospace contractors or acquiring distressed precision forging assets. Deepen backward integration into low-carbon aluminum extrusion to secure China's state-backed renewable energy procurement preference. Defensive patent filings around tapered pin array geometries should accelerate before Japanese precision manufacturers consolidate CFD-enabled design services.
For New Entrants and Emerging Players: South Korea's liquid-cooled pin fin architectures remain underpenetrated by foreign suppliers despite power electronics OEM vendor panel consolidation. White-space targets include bundled thermal simulation services for traction inverter programs and REACH-compliant surface finish plating for German automotive semiconductor buyers. A go-to-market angle anchored in METI-aligned industrial efficiency certifications unlocks Japanese precision manufacturing belt access.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive heat sink divisions lacking CFD engineering scale. Long-term viability centers on suppliers controlling both aluminum extrusion feedstock and computational fluid dynamics talent pipelines. The inflection signal to watch is IGBT packaging form factor standardization that collapses retooling frequency for pin fin array configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Aluminum Extrusion | Secures procurement preference under China's MIIT energy efficiency mandates and dual carbon compliance frameworks. |
| CFD Engineering Team Captive Buildout | Matches Japanese precision manufacturers embedding thermal simulation into early-stage OEM co-development programs. |
| REACH-Compliant Surface Finish Chemistry Investment | Qualifies supplier status for German automotive semiconductor buyers mandating RoHS-compliant plating protocols. |
| Additive Manufacturing Capability Licensing | Collapses minimum order quantity thresholds for aerospace and defense lattice structure pilots in Southwest US clusters. |
| Distributor Network Consolidation Partnerships | Rewrites procurement geography for North American industrial semiconductor buyers shifting toward bundled supply relationships. |
Study Parameters
A spread of perspectives from thermal management engineering directors, automotive powertrain procurement leads, aluminum extrusion plant managers, and renewable energy EPC contractors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, EPA industrial emissions guidelines, MIIT energy efficiency directives, and customs trade data for aluminum alloy feedstock flows. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Demand-supply-balance framing anchored the forecast framework, modeling pin fin heat sink absorption by cooling architecture, industry vertical, application type, and end-user procurement channel. CAGRs derived from segment-level growth rate convergence across the projection horizon, with specific inputs including semiconductor packaging roadmaps, electric vehicle powertrain thermal density trajectories, and aluminum extrusion capacity expansion schedules. Regional production cluster analysis incorporated freight corridor cost dynamics and foundry emissions compliance timelines.
Practitioners should monitor IGBT module geometry standardization efforts, REACH authorization timelines for hexavalent chromium alternatives, and Chinese GB standards revision cycles for early signals requiring forecast reassessment. Cross-checking against MIIT energy efficiency mandate enforcement intensity and German automotive semiconductor corridor procurement data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Series Reactor Market
Power Systems
Battery Cyclers Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Global Rectifier Market
Power Systems
Shunt Capacitor Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Smart Power Strips Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Power Integrated Modules Market
Power Systems
Medium Voltage Drives Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
HVDC Converters Market
Power Systems
Thyristor Market
Power Systems
Buck-Boost Controller Market
Power Systems
Power Inverter Market