
 LED Modules and Light Engines Market | 2026-2036
LED Modules and Light Engines Market Size, Share, and Industry Trends Forecast 2026-2036
LED Modules and Light Engines Market Foresight
Gallium nitride is pivoting from premium niche to mainstream economics in LED module fabrication, displacing legacy sapphire-substrate architectures across high-lumen applications. Signify Holding leverages vertical integration from chip to system to protect margin pools in professional channels. OSRAM GmbH anchors European automotive light-engine supply through its captive wafer capacity. Nichia Corporation dominates phosphor-converted white LED intellectual property, sustaining royalty-advantaged positioning in backlighting modules.
LED modules and light engines are integrated electroluminescent assemblies comprising packaged emitters mounted on metal-core printed circuit boards with thermal interface materials, typically operating at correlated color temperatures between 2700K and 6500K and system efficacies exceeding 150 lumens per watt for commercial-grade products. Their primary purpose is to deliver standardized, replaceable light sources that reduce luminaire design complexity and accelerate fixture manufacturer time-to-market. Linear modules command the largest revenue share within product-type segmentation due to ubiquity in troffer and suspended-luminaire formats across commercial retrofit. COB arrays represent the fastest-expanding product category as single-point-source architectures penetrate directional retail and museum accent applications where beam precision commands premium positioning.
The EU Green Deal and Ecodesign requirements, enforced by national market-surveillance authorities, mandate minimum luminous efficacy and service-life thresholds that de-list legacy module generations from European commerce. In the United States, DOE efficacy standards and California Title 24 building codes compel module upgrades in new construction and major renovation. China's GB standards for solid-state lighting, administered by SAMR, establish domestic certification barriers that favor local module suppliers for government-procured infrastructure projects. Stakeholders must monitor divergence between regional efficacy trajectories and thermal-management specifications when configuring global product platforms.
Market Dynamics
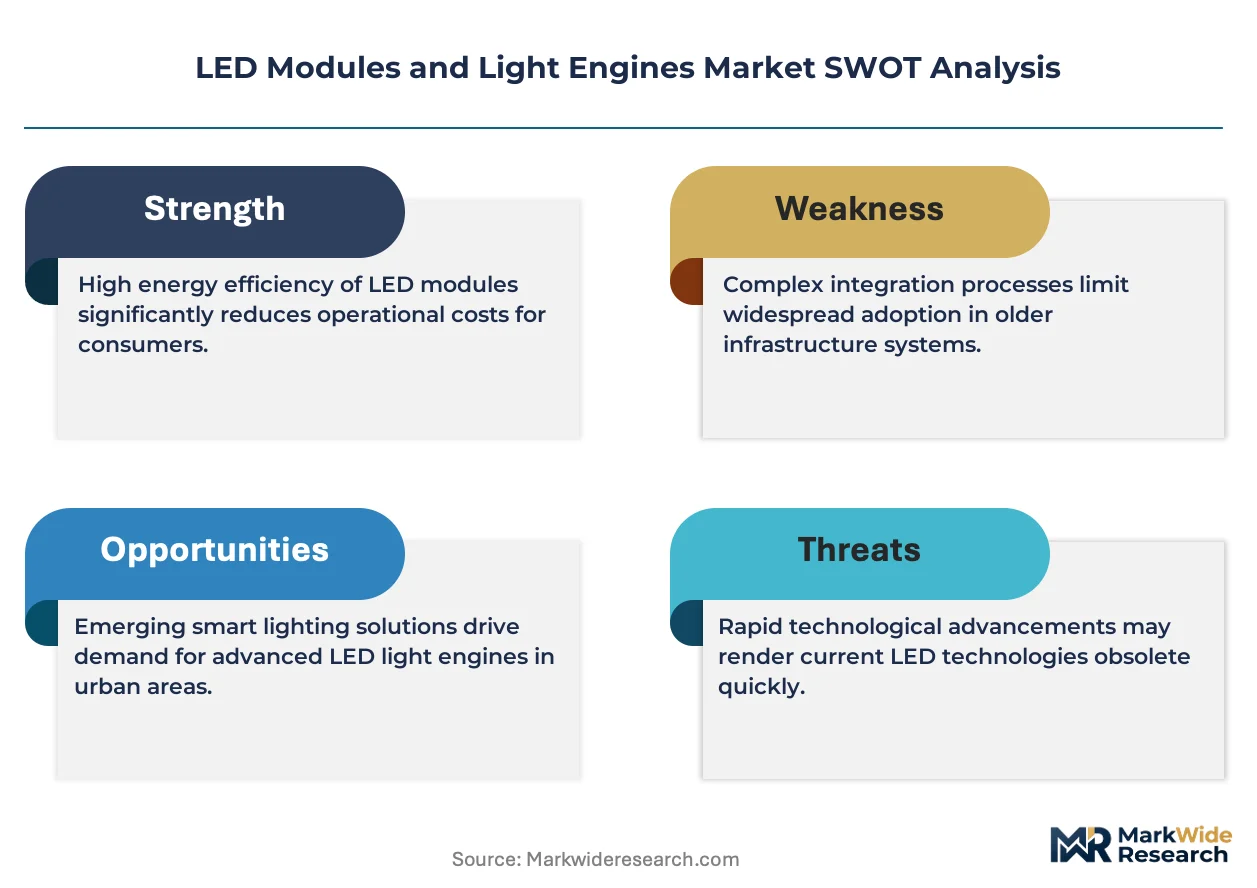
Gallium nitride substrate migration is compressing thermal management costs while EU Ecodesign mandates force simultaneous efficacy upgrades across installed commercial bases.
Growth Catalysts
- EU Green Deal enforcement:National market-surveillance authorities de-list legacy modules below luminous efficacy thresholds, compelling replacement cycles across German, French, and Italian commercial building stocks.
- Retrofit acceleration in hospitality:Hotel operators in the United States and China are standardizing on 4000K linear modules to reduce fixture redesign costs and accelerate renovation timelines.
- Chip-scale packaging:CSP architectures are reducing optical system height by 40% in downlight applications, enabling slimmer luminaire profiles for ceiling-constrained retrofits.
Market Restraints
- Phosphor supply concentration:Cerium-doped yttrium aluminum garnet phosphor production concentrates in Chinese rare-earth processing clusters, exposing module makers to export quota volatility.
- Substrate cost rigidity:Silicon carbide wafer prices remain elevated due to power electronics demand from electric vehicle inverters, limiting cost-down trajectories for premium LED modules.
- Legacy socket compatibility:Existing troffer infrastructures in North American office buildings constrain module form-factor innovation to 2x4 and 2x2 dimensional standards.
Strategic Opportunities
- Human-centric lighting protocols:Circadian-adjustable modules with tunable white from 2700K to 6500K are penetrating healthcare and education verticals where SAMR certification creates procurement preference for domestic suppliers.
- Direct-to-fixture digital channels:Alibaba and Amazon Business platforms are disintermediating traditional electrical distributors for sub-1000 unit module orders from small commercial contractors.
- IRA efficiency incentives:US commercial building owners accessing Inflation Reduction Act tax credits are bundling LED module upgrades with HVAC electrification projects.
Industry Challenges
- Thermal simulation talent scarcity:Computational fluid dynamics expertise for junction temperature prediction in compact COB arrays commands premium compensation and extended hiring cycles.
- Multi-certification sequencing:Module makers targeting simultaneous UL, CE, and CCC marks face 14-18 month validation timelines that delay product launches behind regional competitors.
- Legacy DALI integration complexity:Addressable modules must maintain backward compatibility with 1.0 and 2.0 control protocols across mixed-vintage European commercial installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Modules and Light Engines Market |
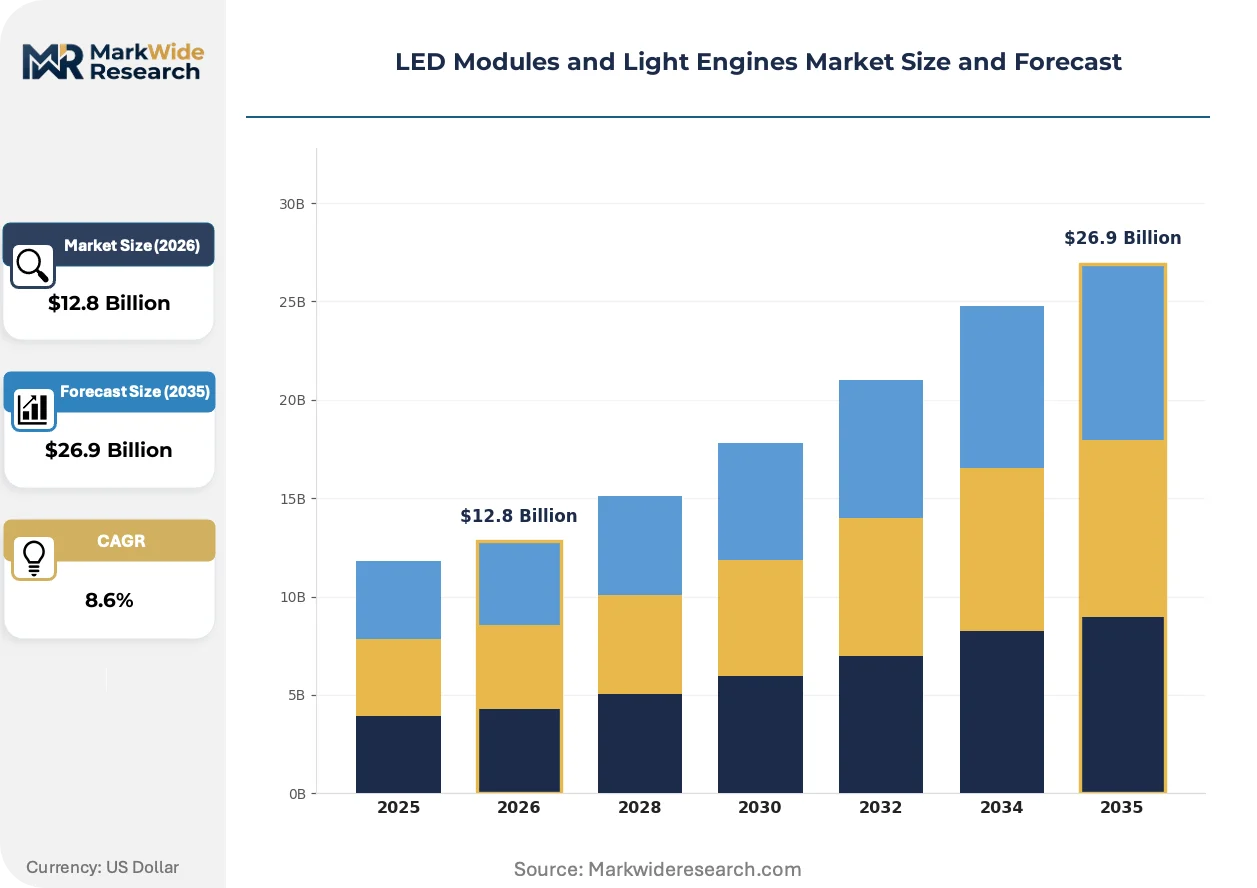
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Modules, High Power LEDs, COBs, Light Engines Application: Indoor Lighting, Outdoor Lighting, Automotive Lighting, Backlighting End User: Residential, Commercial, Industrial, Retail Technology: Smart Lighting, Dimmable LEDs, RGB LEDs, Solar LEDs |
| Companies Covered | Signify Holding, OSRAM GmbH, Acuity Brands Inc., Lumileds Holding B.V., Cree LED, Nichia Corporation, Bridgelux Inc., Tridonic, Everlight Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Modules and Light Engines Market Shifts & Advancements
Module-level intelligence and substrate material transitions are reconfiguring value capture points between semiconductor foundries and luminaire assemblers.
Chip-on-board architectures with integrated driver ICs are automating optical alignment steps previously requiring manual lens placement. Museum and gallery lighting specifiers in Germany and the Netherlands are specifying these single-point-source modules for 15-degree beam precision. The technology is automating fixture assembly labor out of high-cost manufacturing locations.
REACH substance restrictions on cadmium-containing quantum dots are redirecting phosphor formulation R&D toward perovskite alternatives with lower toxicity profiles. European module suppliers are accelerating perovskite stability testing to maintain color-rendering index performance above 90. Display backlighting applications face the tightest compliance timelines under the 2025 restriction schedules.
Specification-grade buyers are unbundling module procurement from luminaire sourcing, establishing direct relationships with Seoul Semiconductor and Lumileds for volume commitments. Large US retail chains and German automotive showrooms now issue module-only tenders with performance guarantees separate from fixture warranties. This pattern concentrates in projects exceeding 10,000 socket replacements where standardization yields measurable procurement savings.
LED Modules and Light Engines Market Segmentation

LED module procurement decisions hinge on thermal performance specifications, form-factor constraints, and control protocol compatibility. Segmentation reveals how fixture manufacturers prioritize replaceability and efficacy thresholds across divergent application environments.
Product Type:
Buyers select module architectures based on lumen density requirements and optical system complexity rather than unit cost alone.
- Linear Modules:Elongated emitter arrays mounted on metal-core PCBs deliver uniform flux distribution across troffer and suspended-luminaire formats. German and French office retrofit projects specify these for 2x4 and 2x2 ceiling grids where standardized dimensions reduce fixture redesign costs. Linear modules lead on scale; COBs lead on momentum.
- COBs:Chip-on-board configurations integrate multiple emitters on a single ceramic substrate with integrated phosphor layers, creating single-point-source architectures. Museum lighting specifiers in the Netherlands and Germany specify COB modules for 15-degree beam precision in accent applications where color consistency commands premium positioning.
- High Power LEDs:Discrete packaged emitters exceeding 1W nominal drive current serve floodlighting and high-bay industrial applications requiring punch-through illumination in Shenzhen port terminals and Houston petrochemical facilities.
- Light Engines:Fully integrated assemblies combining emitters, drivers, and thermal management into drop-in replacement units accelerate luminaire manufacturer time-to-market for California Title 24 compliance projects.
Linear modules dominate retrofit volume; COBs capture the steepest expansion trajectory in specification-grade channels.
Application:
Installation environment determines ingress protection ratings, thermal operating windows, and spectral power distribution requirements.
- Indoor Lighting:Commercial-grade modules operating at 4000K correlated color temperature with system efficacies exceeding 150 lumens per watt serve US hospitality renovation projects where hotel operators standardize on tunable white for guest room flexibility.
- Outdoor Lighting:Modules with IP66 enclosures and enhanced thermal cycling resistance illuminate German Autobahn maintenance depots and Chinese municipal road networks where SAMR certification creates procurement preference for domestic suppliers.
- Automotive Lighting:AEC-Q102 qualified modules with junction temperature stability below 125°C supply European OEM headlamp programs where OSRAM's captive wafer capacity anchors regional supply security.
- Backlighting:Phosphor-converted white LED modules with narrow binning tolerances serve display panel manufacturers in South Korea and Taiwan where Nichia's intellectual property portfolio sustains royalty-advantaged positioning.
Indoor lighting commands the largest installed base; outdoor lighting is climbing the fastest on infrastructure electrification mandates.
End User:
Procurement scale and technical specification authority separate volume buyers from price-sensitive specifiers.
- Commercial:Office landlords and facility managers issue module-only tenders exceeding 10,000 socket replacements where standardization yields measurable procurement savings across German automotive showrooms and US retail chains.
- Industrial:Manufacturing operators prioritize 24/7 operational reliability and five-year warranty terms in heavy-process environments from Houston refineries to Shenzhen electronics assembly plants.
- Retail:Brand-conscious merchants specify circadian-adjustable modules with CRI above 90 to enhance merchandise presentation in flagship locations where human-centric lighting protocols differentiate customer experience.
- Residential:Homeowners and small contractors source sub-1000 unit orders through Alibaba and Amazon Business platforms that disintermediate traditional electrical distributors on cost and delivery speed.
Commercial end users dominate aggregate demand; retail channels are gaining share fastest on experience-driven specification upgrades.
Technology:
Control integration and spectral tunability separate premium module tiers from commodity replacements.
- Smart Lighting:Addressable modules with embedded microcontrollers and wireless connectivity enable centralized energy management in Singapore commercial towers and Dubai hospitality complexes where building automation integration justifies hardware premiums.
- Dimmable LEDs:Phase-cut and 0-10V compatible modules maintain backward compatibility with legacy control infrastructure across mixed-vintage European installations where DALI 1.0 and 2.0 protocol support remains mandatory.
- RGB LEDs:Multi-channel emitter configurations with independent red, green, and blue die enable dynamic color mixing for architectural accent and entertainment venue applications in Las Vegas and Macau.
- Solar LEDs:Low-voltage DC modules with integrated charge controllers serve off-grid rural electrification projects in India and sub-Saharan Africa where national grid extension remains economically unviable.
Smart lighting leads on technology premium capture; solar LEDs expand most quickly on decentralized energy access programs.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's LED module manufacturing cluster anchors global supply capacity for commercial retrofit and automotive light-engine programs. National efficiency mandates in Germany, China, and the United States concentrate replacement demand. Regulatory divergence across these markets forces manufacturers to maintain parallel certification tracks for thermal management and efficacy thresholds.
United States
Commercial building owners accelerate LED module replacement cycles through Inflation Reduction Act tax credit bundling with HVAC electrification projects. DOE efficacy standards and California Title 24 building codes compel upgrades in new construction and major renovation across office and hospitality sectors. Texas and California industrial zones host specification-grade procurement clusters where retail chains issue module-only tenders exceeding 10,000 socket replacements.
Germany
Automotive OEM headlamp programs and commercial office retrofit projects drive demand for high-efficacy linear modules and COB arrays. EU Green Deal enforcement through national market-surveillance authorities de-lists legacy modules below luminous efficacy thresholds, compelling replacement across German, French, and Italian building stocks. Bavaria's industrial corridor concentrates automotive light-engine qualification facilities serving European OEM supply chains.
China
Shenzhen and Dongguan manufacturing clusters supply global module demand while domestic infrastructure electrification accelerates local consumption. SAMR-administered GB standards for solid-state lighting establish certification barriers favoring local suppliers for government-procured projects. Yangtze River Delta municipalities specify 4000K linear modules for smart city streetlighting retrofits under dual carbon goals implementation.
Japan
Display backlighting and precision industrial applications sustain demand for phosphor-converted white modules with narrow binning tolerances. METI energy efficiency standards and JIS certification requirements maintain technical barriers for imported modules in premium commercial segments. Osaka-Kyoto industrial zones concentrate phosphor formulation R&D facilities advancing perovskite alternatives to cadmium-containing quantum dots.
South Korea
Seoul Capital Area display panel manufacturers anchor demand for high-CRI backlighting modules serving global electronics brands. MFDS-equivalent standards for solid-state lighting components align with export market requirements in North America and Europe. Busan-Ulsan automotive manufacturing corridors specify AEC-Q102 qualified modules for domestic OEM headlamp and interior lighting programs.
LED Modules and Light Engines Market Competitive Landscape
Backward integration into captive wafer capacity dominates the current landscape as manufacturers secure gallium nitride substrate supply against power electronics competition. The vendor base separates into three functional tiers: semiconductor foundries controlling epitaxial growth, integrated module assemblers with in-house thermal management, and specification-grade specialists serving automotive and museum channels. Strategic differentiation concentrates on M&A activity targeting phosphor intellectual property and capacity expansion in ceramic substrate fabrication.
Among European-anchored suppliers, OSRAM GmbH exemplifies the captive-wafer archetype securing automotive program supply security, while Signify Holding occupies a position spanning foundry-to-system integration for professional channel margin protection. Nichia Corporation represents the royalty-advantaged tier leveraging phosphor-converted white LED patent portfolios in display backlighting procurement. These three anchors illustrate how intellectual property control, vertical manufacturing scope, and regional certification proximity separate premium positioning from commodity module supply.
| Leading Market Players |
|---|
| Signify Holding |
| OSRAM GmbH |
| Acuity Brands Inc. |
| Lumileds Holding B.V. |
| Cree LED |
| Nichia Corporation |
| Bridgelux Inc. |
| Tridonic |
| Everlight Electronics Co. Ltd. |
| Others |
Supply & Pricing Matrix
EU Ecodesign efficacy mandates compelling wholesale module replacement across German and French commercial building stocks force supply chains to absorb gallium nitride substrate cost premiums while fixture manufacturers pass thermal-management investments downstream.
Pricing Analysis
Input-cost pass-through from silicon carbide wafer markets feeds directly into premium LED module pricing tiers. Three-tier pricing structure across AEC-Q102 automotive, commercial specification-grade, and economy retrofit levels separates buyers by certification burden and thermal performance guarantees. Pricing pressure stems from Chinese rare-earth phosphor export quota volatility exposing module makers to margin compression. Commercial retrofit contractors exhibit highest price sensitivity, while automotive OEM programs accept hardware premiums for junction-temperature stability below 125°C.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Dongguan, and the Yangtze River Delta anchor hub-and-spoke fulfillment patterns for global module demand. Manufacturing concentration in China, South Korea, and Japan draws from gallium nitride epitaxial wafers, cerium-doped yttrium aluminum garnet phosphors, and metal-core printed circuit board substrates. Single-source vulnerability concentrates in Chinese rare-earth processing clusters for phosphor supply. Distribution runs through Alibaba and Amazon Business platforms disintermediating traditional electrical distributors on sub-1000 unit orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification-grade buyers unbundling module procurement from luminaire sourcing signal durable demand for premium thermal performance and narrow binning tolerances.
For Market Incumbents: Extend captive wafer capacity investments to secure gallium nitride substrate supply against power electronics competition from electric vehicle inverters. Deepen backward integration into phosphor intellectual property to defend royalty-advantaged positioning as REACH restrictions redirect R&D toward perovskite alternatives. For New Entrants and Emerging Players: Begin with human-centric lighting protocols in healthcare and education verticals where SAMR certification creates procurement preference for domestic Chinese suppliers. Target circadian-adjustable modules with tunable white from 2700K to 6500K as the most penetrable specification-grade segment, leveraging direct-to-fixture digital channels on Alibaba and Amazon Business platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with ceramic substrate fabrication specialists and phosphor formulation R&D facilities advancing perovskite stability testing. Long-term viability centers on module-level intelligence integration and substrate material transitions reconfiguring value capture points between semiconductor foundries and luminaire assemblers. Watch for divergence between regional efficacy trajectories forcing parallel certification tracks as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Wafer Capacity Expansion | Secures gallium nitride substrate supply against power electronics demand from automotive inverters. |
| Phosphor Intellectual Property Acquisition | Defends royalty positioning as REACH restrictions accelerate perovskite R&D investment cycles. |
| Human-Centric Lighting Module Launch | Captures healthcare and education verticals where tunable white commands specification premiums. |
| Direct-to-Fixture Digital Channel Buildout | Disintermediates electrical distributors on sub-1000 unit orders from small commercial contractors. |
| Multi-Certification Sequencing Investment | Compresses UL, CE, and CCC validation timelines that currently delay product launches 14-18 months. |
Research Methodology
Bottom-up commercial retrofit and automotive light-engine modeling reconciled against top-down gallium nitride substrate supply tracking forms the analytical core of this study. Primary interviews with LED module procurement managers at US retail chains, German automotive showroom operators, Chinese SAMR certification specialists, and museum lighting specifiers in the Netherlands triangulate demand-side validation. Secondary sources include EU Ecodesign regulatory filings, DOE efficacy standard publications, SAMR GB standard databases, SEC 10-K disclosures from listed lighting manufacturers, and customs trade data on phosphor and wafer imports.
Historical trendline analysis across efficacy threshold escalations, substrate cost trajectories, and module replacement cycle frequencies informs the projection framework. Segmentation dimensions span product type, application environment, end-user procurement scale, and control protocol integration complexity. CAGRs derive from curve-fitting installed base turnover rates against regulatory mandate enforcement timelines, with specific inputs from thermal management cost compression curves and chip-scale packaging adoption patterns.
Caveats apply where gallium nitride substrate allocation shifts toward power electronics, phosphor export quota volatility, or divergence between regional efficacy trajectories could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Asia Pacific LED Lighting Market
LED
UK LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
China Indoor LED Lighting Market
LED
LED Downlight Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Micro LED Display Market
LED
China LED Market
LED
High-Brightness LED Market
LED
Japan Indoor LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
Mini LED Market
LED
South America LED Lighting Market
LED
Germany Automotive LED Lighting Market
LED
Africa LED Lighting Market