
 Marine Variable Frequency Drives Market | 2026-2036
Marine Variable Frequency Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Variable Frequency Drives Market Foresight
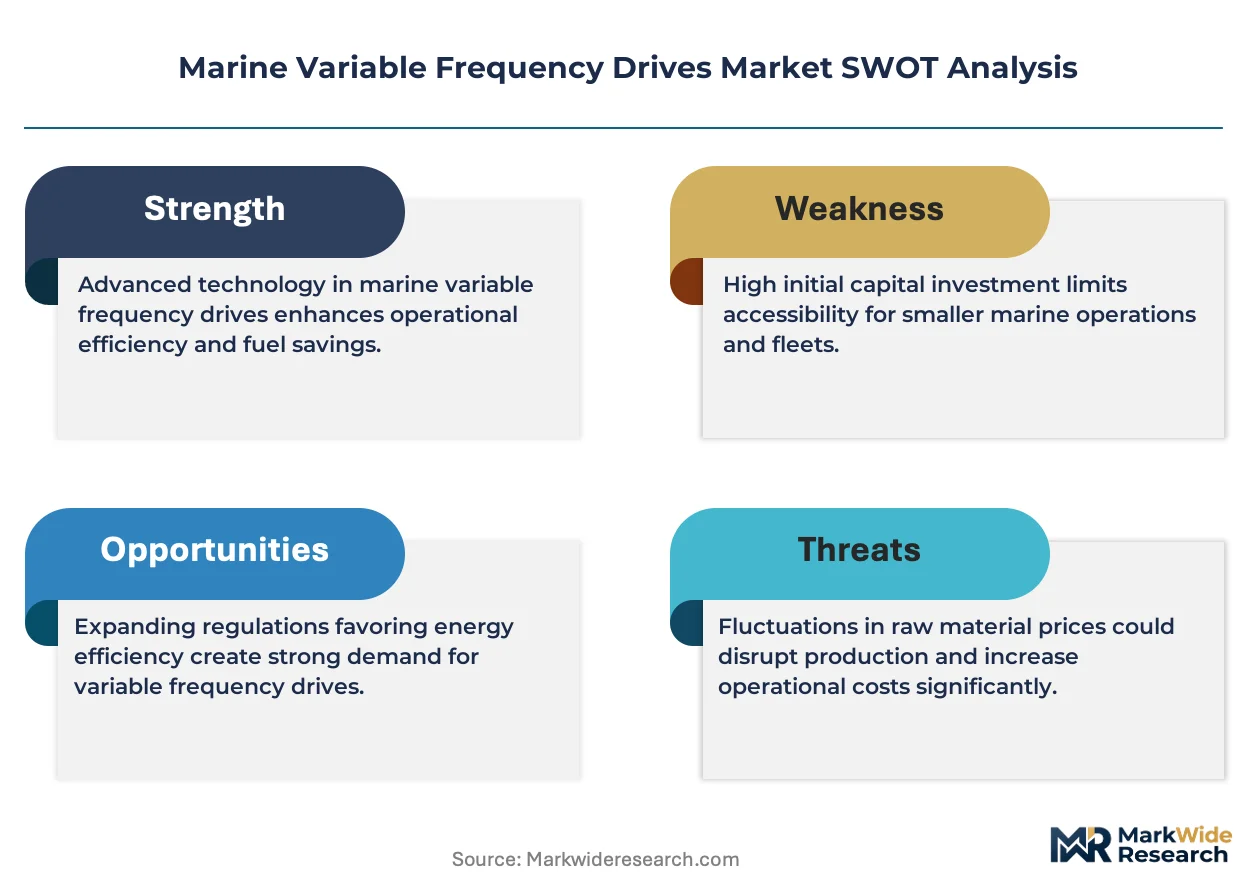
IEC 61800 marine certification is bifurcating the competitive landscape into qualified system integrators and excluded generalists. ABB leverages its propulsion automation heritage to anchor high-power contracts for offshore supply vessels. Siemens competes through integrated shipboard power platforms that bundle VFDs with switchgear and energy management systems. Danfoss specializes in compact low-voltage drives for auxiliary pump and fan applications where space constraints dominate specification.
Marine variable frequency drives are solid-state motor control systems that convert fixed-frequency shipboard power to variable voltage and frequency output, typically operating at 400-690 VAC with IP54 or higher enclosure ratings to withstand salt-laden atmospheres. Their primary purpose is optimizing propulsion motor speed and reducing fuel consumption across operating profiles from harbor maneuvering to open-sea transit. Pulse Width Modulation technology leads installed base due to proven harmonic performance and compatibility with existing induction motors, while Direct Torque Control gains share in dynamic positioning thrusters where sub-second torque response prevents station-keeping drift. Low Power drives dominate unit volume in HVAC and auxiliary pumping retrofits, though Very High Power systems above 1000 kW capture disproportionate value in cruise ship and LNG carrier propulsion upgrades.
The International Maritime Organization enforces Carbon Intensity Indicator metrics that directly reward vessels with VFD-controlled propulsion through reduced fuel consumption reporting. Classification societies including DNV and Lloyd's Register mandate type-approved drives for critical systems, creating compliance barriers for uncertified suppliers. The EU MRV Regulation and impending FuelEU Maritime standards extend monitoring requirements to auxiliary power systems, broadening addressable scope beyond main propulsion. Stakeholders must monitor classification rule evolution around cybersecurity for networked drive systems, as remote diagnostics capabilities become standard specification requirements.
Market Dynamics
The Energy Efficiency Existing Ship Index is compressing vessel upgrade cycles, forcing shipowners to retrofit propulsion systems with certified variable frequency drives ahead of regulatory deadlines rather than at natural replacement intervals.
Growth Catalysts
- IMO Carbon Intensity Indicator:The mandatory CII grading system rewards vessels with VFD-controlled propulsion through superior fuel efficiency scores, creating direct financial incentives for retrofits across cargo and passenger fleets.
- Offshore vessel electrification:Norway's North Sea cluster is accelerating platform supply vessel hybridization programs that require dynamic positioning thrusters with sub-second torque response.
- Direct Torque Control advancement:This control topology enables precise station-keeping for offshore construction vessels operating in harsh North Sea conditions where induction motor alternatives fail.
Market Restraints
- IEC 61800-9-2 compliance costs:Marine-specific certification requires extensive electromagnetic compatibility testing and vibration qualification that excludes generalist drive manufacturers from tender participation.
- Copper and silicon carbide supply concentration:Power module substrates depend on concentrated East Asian foundry capacity, exposing lead times to geopolitical friction.
- Harmonic filtering requirements:Pulse Width Modulation drives generate conducted emissions that demand costly line reactors and active front-end rectifiers on older vessel electrical architectures.
Strategic Opportunities
- FuelEU Maritime preparation:The 2025 implementation timeline creates retrofit demand for auxiliary power system VFDs beyond main propulsion, broadening addressable scope to HVAC and pumping loads.
- Autonomous vessel development:Unmanned surface vessel programs require fully integrated electric propulsion with networked drive diagnostics that enable shore-based predictive maintenance.
- India port infrastructure expansion:The country's shipbuilding subsidy schemes and Sagarmala port modernization are generating tugboat and pilot vessel orders specifying compact low-voltage drives.
Industry Challenges
- Marine electrical engineer scarcity:Vessel operators struggle to recruit technicians qualified in both medium-voltage drive commissioning and classification society inspection protocols.
- Legacy DC system integration:Retrofit projects on 1980s-era vessels require custom interface engineering between modern AC drives and existing DC distribution buses.
- Cybersecurity certification timelines:DNV and Lloyd's Register are evolving rules for networked drive remote access that delay type approval for diagnostic-enabled products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Variable Frequency Drives Market |
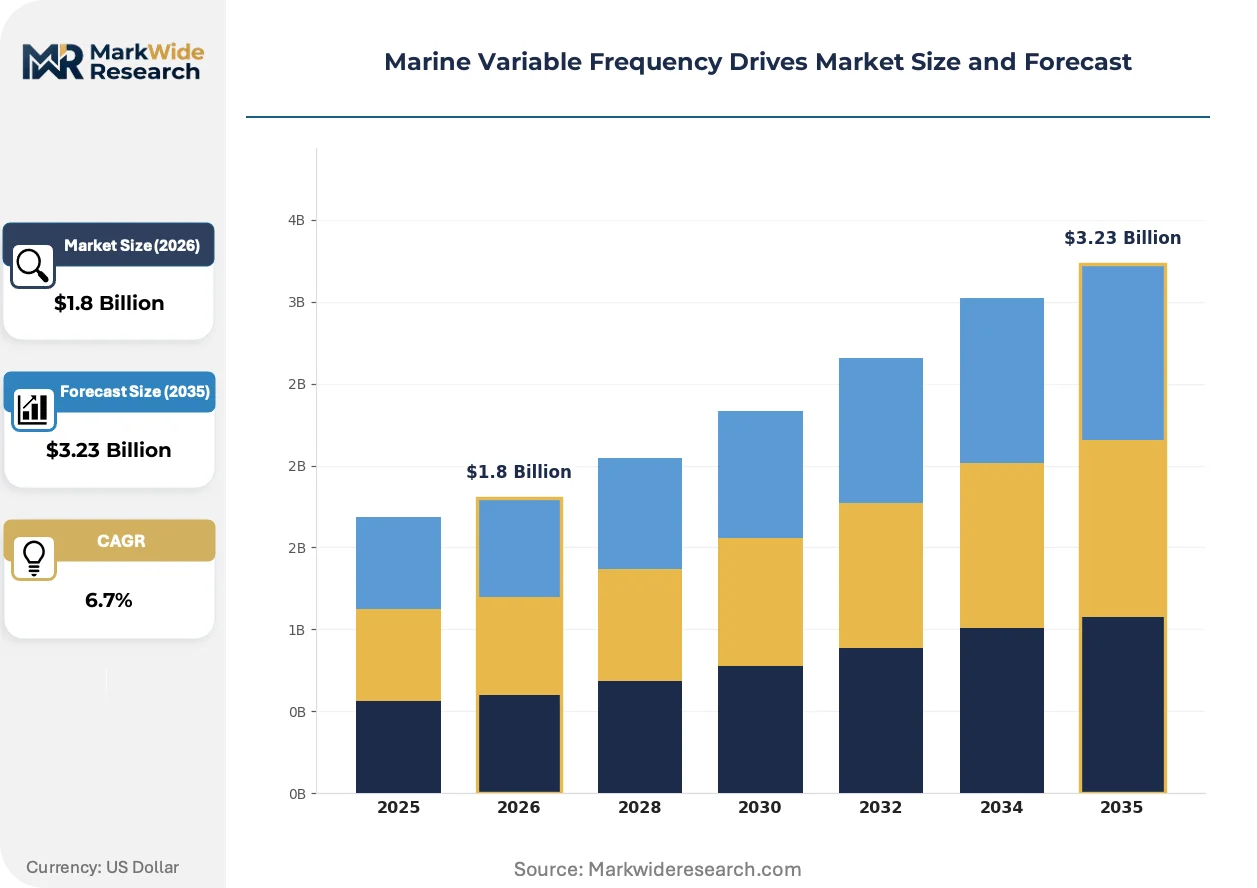
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pulse Width Modulation, Direct Torque Control, Vector Control, V/f Control Application: Propulsion, Pumping, HVAC, Auxiliary Systems End User: Shipping Companies, Offshore Platforms, Shipyards, Marine Equipment Manufacturers Power Rating: Low Power (Up to 30 kW), Medium Power (30-200 kW), High Power (200-1000 kW), Very High Power (Above 1000 kW) |
| Companies Covered | Rockwell Automation, WEG, ABB, Eaton, Yaskawa, Siemens, Mitsubishi Electric, Schneider Electric, Danfoss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Variable Frequency Drives Market Shifts & Advancements
Modular power electronics architectures are displacing monolithic drive designs, enabling vessel operators to replace individual power stages at sea rather than dry-docking for complete system swaps.
Silicon carbide MOSFET technology is decomposing the traditional voltage-current tradeoff in marine drives. Cruise ship operators are adopting 690V systems with reduced cooling requirements. This semiconductor transition is compressing physical envelope sizes by forty percent versus silicon IGBT equivalents.
The EU F-Gas Regulation is restricting sulfur hexafluoride use in medium-voltage switchgear that traditionally accompanied VFD installations. Shipyards are redesigning electrical rooms with air-insulated alternatives. Norwegian offshore vessel constructors face the tightest compliance timelines due to early national implementation.
Service contract unbundling is fragmenting traditional propulsion system procurement. Charter operators now source drives, commissioning, and predictive maintenance from separate vendors rather than single-source integrators. This pattern is most pronounced in Singapore's bunkering and short-sea shipping segments where vessel utilization rates demand rapid technician dispatch.
Marine Variable Frequency Drives Market Segmentation
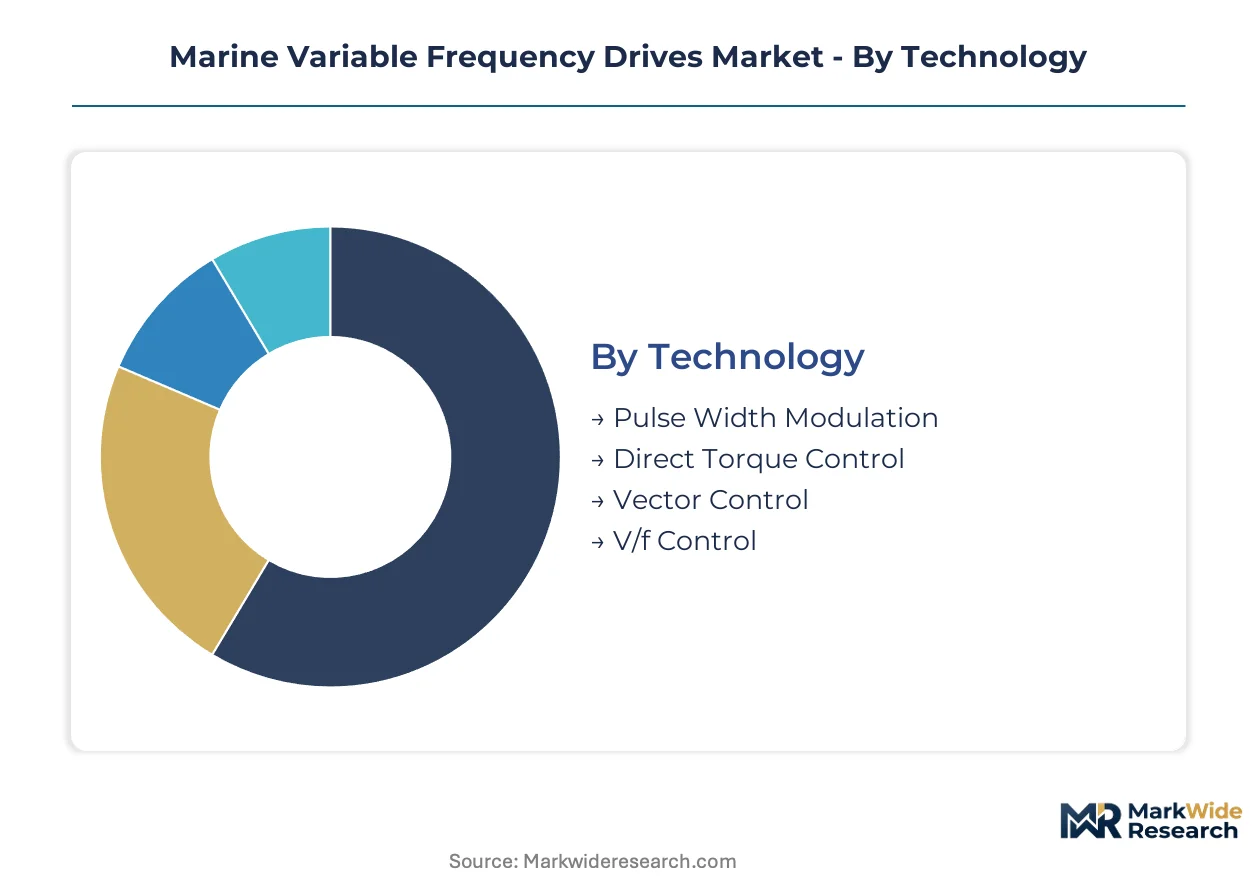
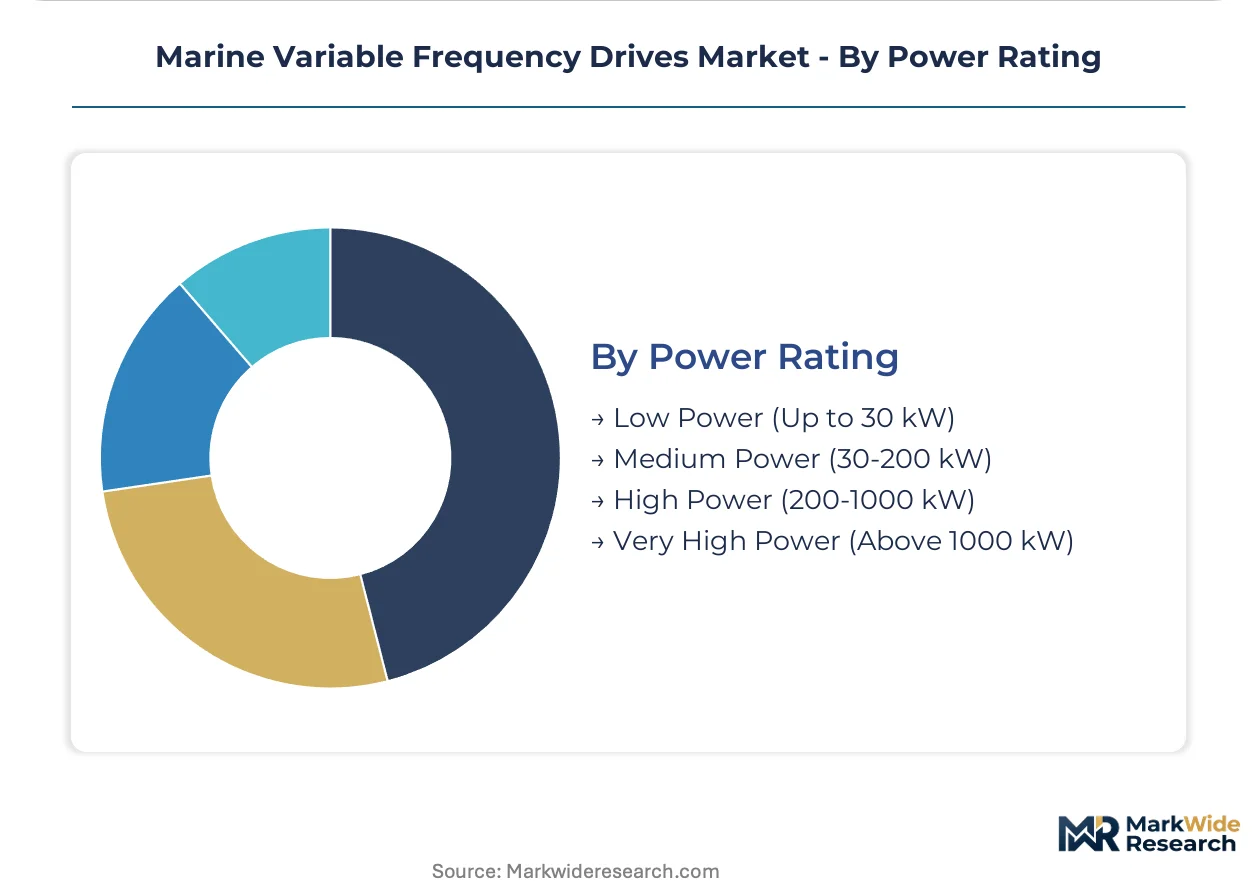
Technology and power rating divisions determine procurement economics for marine VFD systems. Certification requirements and semiconductor material choices create divergent margin structures across each category.
Technology:
Pulse Width Modulation commands the widest margin pool due to its established certification pathway and retrofit compatibility.
- Pulse Width Modulation:Converts DC to variable-frequency AC through high-speed switching at carrier frequencies typically 2-15 kHz. Norwegian offshore supply vessel operators specify PWM drives for hybrid propulsion retrofits where harmonic compatibility with existing switchgear limits alternatives. IEC 61800-9-2 electromagnetic qualification adds 15-20% certification cost premium versus industrial equivalents.
- Direct Torque Control:Eliminates modulator stage by directly controlling motor flux and torque through inverter switching states. Dynamic positioning thrusters on North Sea construction vessels demand sub-100 millisecond torque response that DTC topology delivers without encoder feedback. ABB and Siemens anchor high-power contracts through proprietary DTC algorithms.
- Vector Control:Field-oriented algorithms decouple torque and flux components for precise speed regulation across four-quadrant operation.
- V/f Control:Simpler scalar methodology maintains constant volts-per-hertz ratio for basic pump and fan applications where dynamic response requirements are minimal.
Pulse Width Modulation holds installed capacity. Direct Torque Control is rotating up the share rankings in offshore electrification programs.
Application:
Propulsion systems concentrate value capture due to fuel efficiency verification requirements under IMO Carbon Intensity Indicator rules.
- Propulsion:Main drive applications span diesel-electric, hybrid, and fully electric architectures from harbor tugs to cruise liners. Cruise ship operators in Mediterranean and Baltic routes retrofit fixed-pitch propellers with VFD-controlled variable-speed systems to achieve CII grade improvements. Classification societies mandate type-approved drives with active front-end rectifiers for harmonic mitigation on vessels above 500 gross tonnage.
- Pumping:Ballast, cargo, and fire-fighting pumps operate across intermittent duty cycles where VFD speed matching eliminates throttle valve losses. LNG carrier operators specify redundant pump drives with SIL 2 safety integrity for cargo handling systems.
- HVAC:Chiller and ventilation motor control dominates unit volume in passenger vessel retrofits where auxiliary load reduction supports overall efficiency metrics.
- Auxiliary Systems:Winches, cranes, and deck machinery require torque-controlled acceleration profiles for load handling safety.
Propulsion retains value concentration. HVAC is climbing fastest as FuelEU Maritime broadens monitoring scope beyond main engines.
End User:
Offshore platforms generate premium pricing through dynamic positioning redundancy requirements and harsh-environment specifications.
- Shipping Companies:Container lines and bulk operators drive retrofit demand as CII compliance deadlines compress vessel upgrade cycles. Maersk and MSC specify integrated power management platforms that bundle VFDs with energy storage interfaces.
- Offshore Platforms:Drillships and floating production units require thruster drives with 100% redundancy and sub-second torque response for station-keeping in North Sea and Gulf of Mexico conditions.
- Shipyards:Korean and Chinese builders source drives through system integrators for newbuild LNG carriers and container vessels.
- Marine Equipment Manufacturers:Thruster OEMs and pump suppliers integrate compact low-voltage drives into packaged skid systems for tugboat and pilot vessel applications.
Shipping Companies anchor procurement volume. Offshore Platforms is expanding most quickly on electrification investment cycles.
Power Rating:
Very High Power systems above 1000 kW concentrate margin through custom engineering and medium-voltage insulation requirements.
- Low Power (Up to 30 kW):Compact drives for auxiliary pumps, fans, and small winches where IP54 enclosure ratings and marine-grade conformal coating suffice. Danfoss specializes in this tier for space-constrained engine room retrofits on 1980s-era vessels.
- Medium Power (30-200 kW):Thruster and large pump applications dominate this range, with silicon carbide MOSFET adoption reducing cooling system footprint by 40% versus silicon IGBT equivalents.
- High Power (200-1000 kW):Diesel-electric propulsion generators and large cargo pumps require active front-end rectifiers for harmonic compliance with IEEE 519 and IEC 61000 standards.
- Very High Power (Above 1000 kW):Cruise ship and LNG carrier main propulsion demands liquid-cooled multilevel converters with cell-based redundancy for continued operation during single-point failures.
Very High Power dominates value capture. Medium Power is gaining share fastest on silicon carbide technology transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipowners in Norway's North Sea cluster drive premium-tier procurement for dynamic positioning systems. Container lines in Singapore and South Korea anchor volume demand for propulsion retrofits. Classification society offices in Hamburg and London influence specification standards across multiple flag states.
Norway
Offshore supply vessel operators in Stavanger and Bergen specify IEC 61800-9-2 certified drives for hybrid electrification programs. The Norwegian Maritime Authority enforces early implementation of sulfur emission controls that accelerate propulsion system upgrades. Kongsberg Maritime anchors thruster integration activity in the Oslofjord corridor.
Singapore
Bunkering operators and short-sea shipping fleets drive demand for compact low-voltage drives in auxiliary pumping retrofits. The Maritime and Port Authority mandates port facility standards that include shore power compatibility requirements for vessel electrical systems. Tuas Port expansion concentrates newbuild tugboat orders specifying space-constrained drive packages.
Germany
Cruise ship operators in Hamburg and Rostock retrofit fixed-pitch propellers with variable-speed systems to achieve Carbon Intensity Indicator grade improvements. Lloyd's Register and DNV classification offices in Hamburg shape cybersecurity certification timelines for networked drive diagnostics. Meyer Werft in Papenburg anchors high-power propulsion system integration for LNG carrier newbuilds.
South Korea
DSME and Hyundai Heavy Industries in Ulsan and Geoje source medium-voltage drives through system integrators for container vessel construction. The Korea Register of Shipping mandates type-approved equipment for vessels above 500 gross tonnage. Busan port electrification programs generate demand for harbor tugboat propulsion upgrades.
United States
Gulf of Mexico drillship operators specify thruster drives with 100% redundancy for station-keeping in harsh weather conditions. The Coast Guard enforces electrical safety standards for passenger vessels under 46 CFR regulations. Houma and Fourchon in Louisiana concentrate offshore vessel retrofit activity for dynamic positioning system compliance.
Marine Variable Frequency Drives Market Competitive Landscape
Player mix skews toward diversified electrical equipment conglomerates with marine certification heritage. The vendor base concentrates around propulsion automation specialists and power electronics generalists with type-approved product lines. Two strategic archetypes dominate: integrated platform providers bundling drives with switchgear, and compact drive specialists targeting auxiliary retrofits. Competitive moves center on silicon carbide technology transitions and service contract unbundling to capture predictive maintenance revenue.
Within the integrated platform tier, ABB and Siemens occupy positions exemplifying high-power contract anchoring through propulsion automation heritage and bundled shipboard power platforms. Danfoss represents the compact specialist archetype, with its low-voltage drive focus aligning with space-constrained engine room specifications. These three companies illustrate the certification bifurcation between qualified system integrators and excluded generalists that IEC 61800 marine standards enforce.
| Leading Market Players |
|---|
| Rockwell Automation |
| WEG |
| ABB |
| Eaton |
| Yaskawa |
| Siemens |
| Mitsubishi Electric |
| Schneider Electric |
| Danfoss |
| Others |
Supply & Pricing Matrix
Silicon carbide MOSFET substitution for silicon IGBTs is redrawing procurement geography toward East Asian foundry clusters while compressing price premiums for medium-voltage drives by forty percent against legacy equivalents. This semiconductor transition simultaneously concentrates supply leverage among integrated device manufacturers and erodes margin buffers for system integrators lacking captive wafer access.
Pricing Analysis
Cost-plus contracts with copper and silicon carbide indexation dominate procurement for very high power systems above 1000 kW. Three-tier pricing structure across IEC 61800 certified, industrial-grade, and uncertified economy drives separates qualified system integrators from excluded generalists. Pricing pressure stems from Norwegian offshore vessel electrification programs demanding volume discounts for fleet-wide retrofits. Charter operators in Singapore exhibit highest price sensitivity due to fragmented ownership structures, while cruise lines in Germany accept premium positioning for CII compliance verification.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standard low-voltage drives, whereas strategic stockpiling of silicon carbide wafers and copper busbars buffers against foundry lead time volatility. Power module substrates draw from concentrated capacity in Japan, South Korea, and Taiwan, with epoxy molding compounds and ceramic substrates feeding from specialized chemical suppliers. Single-source vulnerability in 6-inch silicon carbide wafer production exposes lead times to geopolitical friction. Distribution runs through marine system integrators in Norway, Germany, and South Korea rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat where IEC 61800 marine certification creates switching costs that lock shipowners into qualified supplier relationships for vessel upgrade cycles.
For Market Incumbents: Compound certification entrenchment by accelerating cybersecurity type approval for networked drive diagnostics ahead of evolving DNV and Lloyd's Register rules. Deepen backward integration into silicon carbide module packaging to capture margin compression from semiconductor transitions. Defend against emerging Chinese drive manufacturers by anchoring service contract unbundling capabilities in Singapore and South Korea port clusters. For New Entrants and Emerging Players: Anchor in India's port infrastructure expansion under Sagarmala modernization, where shipbuilding subsidy schemes generate tugboat and pilot vessel orders with less stringent certification barriers. Target compact low-voltage auxiliary retrofits for 1980s-era vessels where space constraints exclude incumbent bulk. Pursue white-label partnerships with European thruster OEMs seeking second-source drive suppliers for FuelEU Maritime preparation timelines. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement phase that favors vertically integrated platform providers with captive certification expertise over component specialists. Five-to-ten year viability hinges on silicon carbide technology transitions and autonomous vessel development programs. Acquisition candidates with proprietary DTC algorithms and established Lloyd's Register type approvals warrant premium positioning. Watch for inflection when cybersecurity certification timelines compress from eighteen months to six months, signaling regulatory maturation that enables new entrant scale.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61800-9-2 Certification Acceleration | DNV and Lloyd's Register type approval unlocks tender participation for offshore platform contracts. |
| Silicon Carbide Module Integration | Reduces cooling footprint by forty percent for cruise ship electrical room redesigns. |
| Cybersecurity Type Approval Investment | Remote diagnostic capabilities become standard specification under evolving classification rules. |
| Service Contract Unbundling | Captures predictive maintenance revenue from Singapore bunkering and short-sea shipping segments. |
| India Market Localization | Sagarmala port modernization generates tugboat orders specifying compact low-voltage drives. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with marine electrical engineers, shipyard procurement directors, classification society surveyors, and offshore vessel operators, combined with secondary validation against Lloyd's Register type approval databases, DNV certification registries, IMO Carbon Intensity Indicator vessel tracking, and customs trade records for power electronics imports. Bottom-up vessel fleet analysis and top-down OEM revenue triangulation anchored market sizing across the projection horizon.
Across the modeling period, forecasts integrate technology substitution curves for silicon carbide adoption, regulatory deadline clustering for EEXI and CII compliance, and power rating segmentation spanning low voltage auxiliary through very high power propulsion systems. CAGRs derive from regression against historical retrofit penetration rates and newbuild specification trends. Industry-specific inputs include Norwegian offshore electrification investment cycles and FuelEU Maritime auxiliary system monitoring scope expansion.
Material uncertainties — copper and silicon carbide supply disruptions, cybersecurity certification timeline extensions, and autonomous vessel program funding shifts — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement consistency and semiconductor foundry capacity expansion. Revision becomes warranted when IEC 61800 marine certification requirements expand beyond current electromagnetic compatibility and vibration qualification scopes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Semiconductor Rectifier Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Vehicle Inverter Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Low Voltage AC Drive Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Global Gan Power Device Market
Power Systems
Shunt Voltage References Market
Power Systems
Converter Modules Market
Power Systems
PV Micro Inverters Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market