
 Battery Module Sensors Market | 2026-2036
Battery Module Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Module Sensors Market Insights
Multi-source procurement for sensing elements is hardening across tier-one battery pack assemblers. Robert Bosch GmbH leverages its Stuttgart engineering base to dominate temperature sensor calibration for European EV platforms. Continental AG anchors its position through in-house MEMS fabrication, while NXP Semiconductors competes on automotive-grade ASIL-D functional safety certification.
Battery module sensors are electromechanical devices that monitor thermal, electrical, and mechanical states within lithium-ion cell arrays, typically operating across voltage ranges of 0–5 V with ±0.5 °C accuracy to prevent catastrophic failure. Their primary purpose is to feed real-time telemetry into battery management systems that govern charging protocols and cell balancing. Temperature sensors occupy the largest revenue pool given their critical role in thermal runaway mitigation, while wireless monitoring technology is expanding fastest as OEMs eliminate wiring harness weight from pack architectures. Automotive OEMs concentrate the highest absolute demand, though renewable energy storage deployments are widening the addressable base for voltage and current sensing arrays.
EU Battery Regulation and REACH compliance are mandating embedded cell-level monitoring traceability across European production lines, while China's GB/T standards enforce uniform sensor placement in domestic NEV battery packs. The US NHTSA and EPA are jointly elevating failure-reporting thresholds that require granular module-level telemetry. Stakeholders must calibrate their sensor portfolios against diverging regional certification timelines rather than pursuing universal platform designs.
Market Dynamics
Thermal runaway prevention mandates are compressing sensor integration timelines across EV battery pack architectures, forcing assemblers to embed multi-parameter monitoring at every cell junction rather than module-level aggregation.
Growth Catalysts
- EU Battery Regulation traceability mandates:Embedded cell-level monitoring is now compulsory across European production lines, requiring discrete sensor nodes at each lithium-ion cell interface.
- Wireless telemetry adoption:OEMs eliminate wiring harness weight through RF-based sensor networks, reducing pack mass while expanding data granularity for battery management systems.
- Renewable energy storage deployments:Utility-scale battery installations in Germany and China are widening demand for voltage and current sensing arrays beyond automotive applications.
Market Restraints
- MEMS fabrication concentration:Foundry capacity for automotive-grade pressure and gas sensors concentrates in Taiwan and South Korea, exposing supply chains to single-source fragility.
- Raw material cost volatility:Platinum-group metal prices for high-temperature thermistor elements fluctuate with mining output from South Africa and Russia, compressing sensor margin structures.
- ASIL-D certification friction:Functional safety qualification under ISO 26262 extends development cycles by 18-24 months for new sensor designs targeting EV platforms.
Strategic Opportunities
- Solid-state battery transition:Next-generation cell chemistries require redesigned thermal monitoring architectures, opening sensor specification windows before designs lock.
- India PLI scheme for NEV manufacturing:Domestic battery pack assembly incentives are creating fresh demand for localized sensor calibration and testing infrastructure.
- Second-life battery monitoring:Stationary storage repurposing of retired EV modules needs retrofit sensor kits for degradation tracking in non-automotive duty cycles.
Industry Challenges
- Multi-physics simulation talent scarcity:Battery thermal-electrical-mechanical modeling requires rare cross-trained engineers, slowing sensor placement optimization for new pack geometries.
- Legacy BMS integration complexity:Retrofitting wireless sensor networks into existing battery management architectures demands protocol translation layers that introduce latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Module Sensors Market |
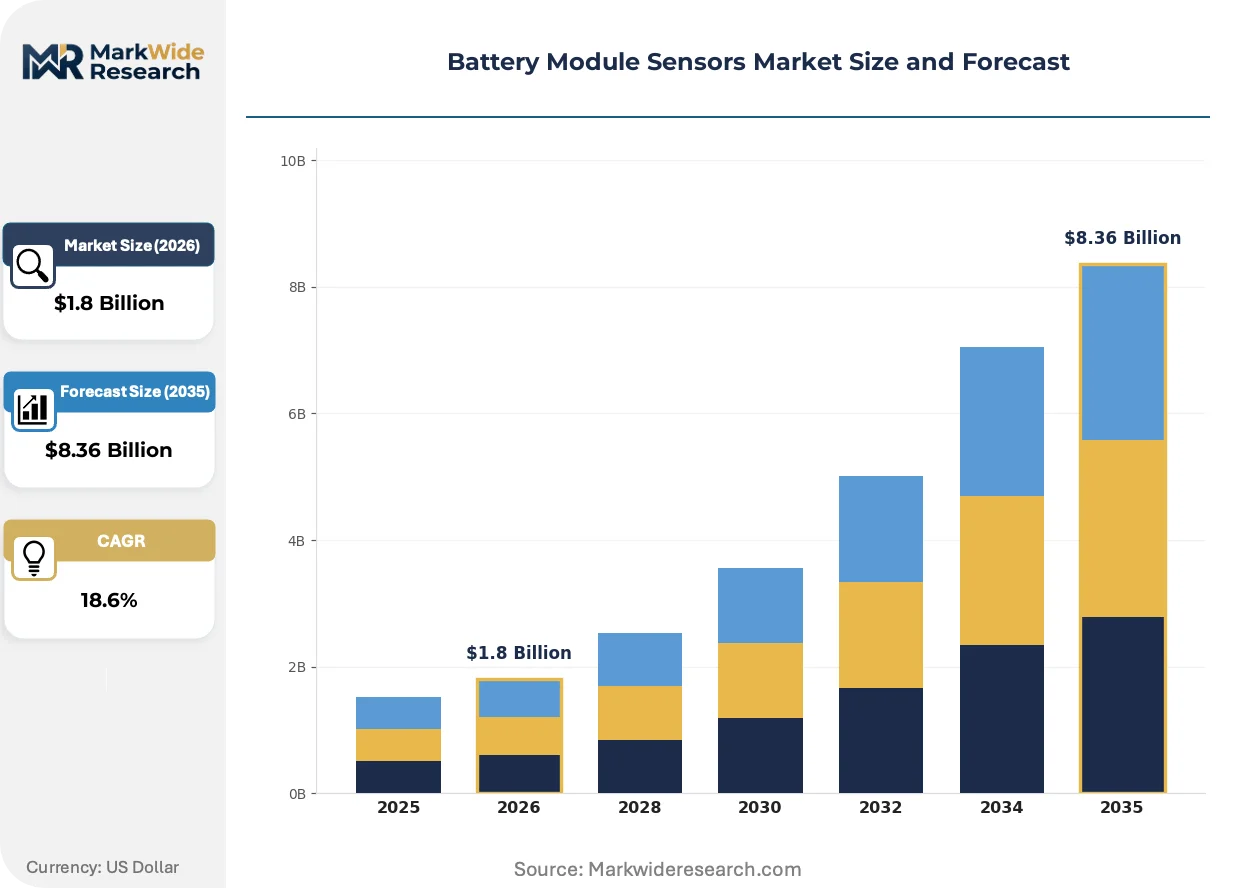
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Voltage Sensors, Current Sensors, Pressure Sensors Technology: Thermal Imaging, MEMS, RFID, Wireless Monitoring End User: Automotive OEMs, Consumer Electronics, Renewable Energy, Industrial Applications Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Robert Bosch GmbH, Continental AG, NXP Semiconductors, Texas Instruments, Infineon Technologies, TE Connectivity, DENSO Corporation, Analog Devices, Sensata Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Module Sensors Market Trends and Innovations
Sensor fusion architectures are collapsing discrete temperature, voltage, and gas detection into single-package units, eliminating redundant harnessing while complicating calibration workflows. This integration wave is redrawing competitive boundaries between specialized and diversified suppliers.
Silicon carbide-based temperature sensing is consolidating high-voltage isolation and rapid thermal response into unified probe designs. EV manufacturers in Germany and China are adopting these devices for 800-volt architectures. The technology is consolidating previously separate isolation barrier and sensing element supply chains into unified procurement categories.
China's GB/T standards now enforce uniform sensor placement density across domestic NEV battery packs, eliminating assembler discretion in thermal monitoring topology. The regulation is forcing foreign sensor suppliers to redesign packaging for Chinese-specific cell form factors. Domestic pack assemblers are responding by qualifying second-source local sensor vendors to meet compliance timelines.
Long-term service contracts now bundle sensor replacement and recalibration into battery pack lifecycle agreements, displacing spot procurement of discrete components. Fleet operators and energy storage developers are driving this shift to guarantee uptime metrics. The model is most visible in German utility-scale storage deployments where availability guarantees dominate vendor selection.
Battery Module Sensors Market Segmentation
Sensor specification windows vary sharply across battery pack architectures. Procurement teams must align technical requirements with deployment scale and certification timelines to avoid stranded inventory.
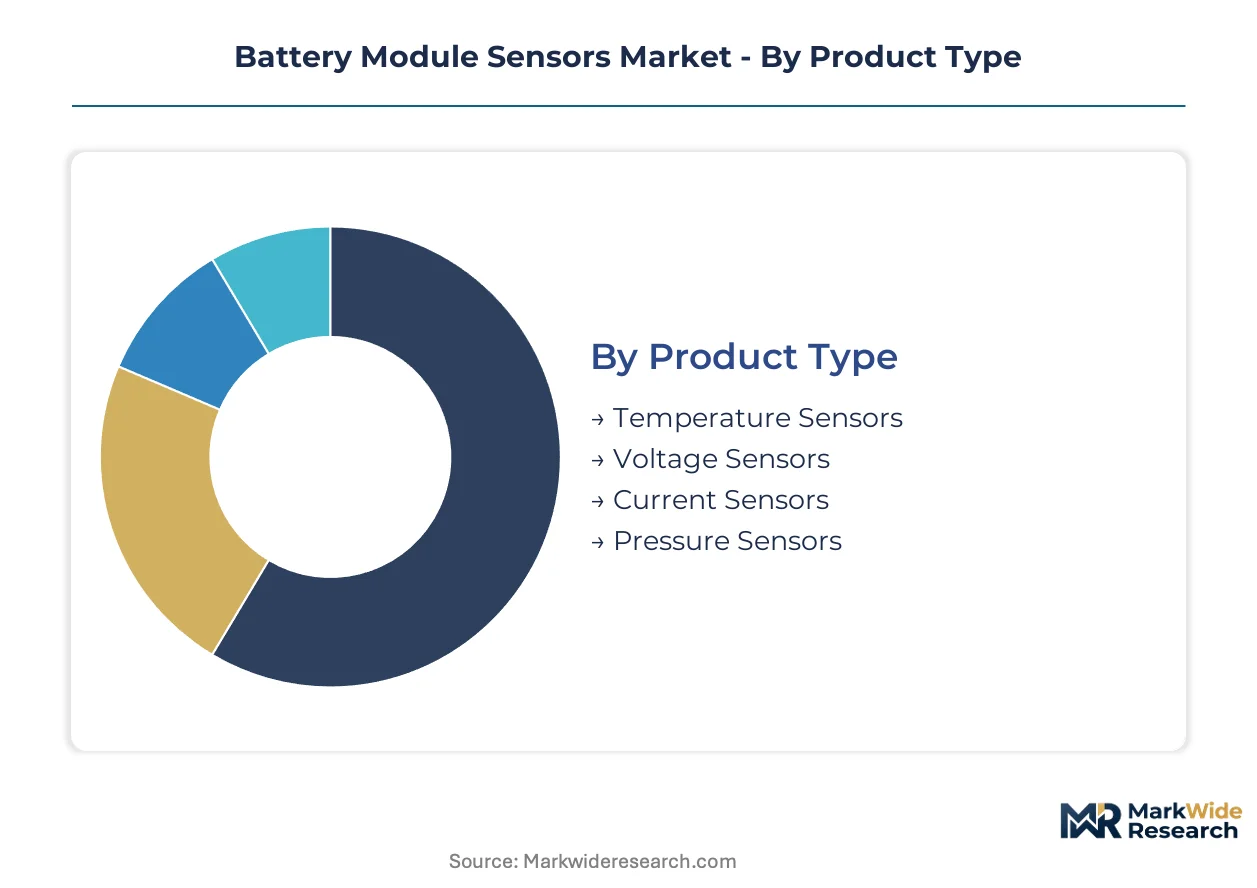
Product Type:
Supply concentration for sensing elements tracks directly to foundry capacity and raw material sourcing.
- Temperature Sensors:Platinum-group thermistors and NTC ceramics dominate automotive-grade specifications. Bosch and Continental in Germany calibrate these for 800-volt architectures under tightening EU Battery Regulation traceability mandates.
- Voltage Sensors:Precision resistor networks with ASIL-D functional safety certification feed real-time telemetry into battery management systems. Demand concentrates in German EV platforms and Chinese NEV production lines where GB/T standards enforce uniform placement density.
- Current Sensors:Hall-effect and shunt-based designs monitor cell-level charge flow.
- Pressure Sensors:MEMS-based gas detection for thermal runaway early warning.
Today's leader: Temperature Sensors. Tomorrow's challenger: Voltage Sensors.
Technology:
Cost tier differentiation separates premium certified solutions from commodity alternatives.
- MEMS:Micro-electromechanical systems consolidate pressure, gas, and thermal detection into single-package units. Foundry capacity concentrates in Taiwan and South Korea, exposing supply chains to geographic concentration risk.
- Wireless Monitoring:RF-based sensor networks eliminate wiring harness weight from pack architectures. OEMs in Germany and China adopt these fastest as 800-volt platforms demand reduced mass.
- Thermal Imaging:Infrared arrays for distributed temperature mapping.
- RFID:Passive identification tags for cell-level traceability compliance.
Volume concentration favors MEMS today. Wireless Monitoring is climbing the fastest as pack architectures evolve.
End User:
Application maturity determines margin structure and contract duration.
- Automotive OEMs:Long-term service contracts bundle sensor replacement and recalibration into battery pack lifecycle agreements. German fleet operators and utility-scale storage developers drive availability-guarantee procurement models.
- Renewable Energy:Utility-scale battery installations in Germany and China widen demand for voltage and current sensing arrays. Stationary storage duty cycles differ from automotive profiles, requiring recalibrated accuracy specifications.
- Consumer Electronics:Portable device battery modules with lower voltage ranges.
- Industrial Applications:Forklift and material handling equipment battery monitoring.
Margin stability sits with Automotive OEMs. Renewable Energy offers the steepest expansion trajectory.
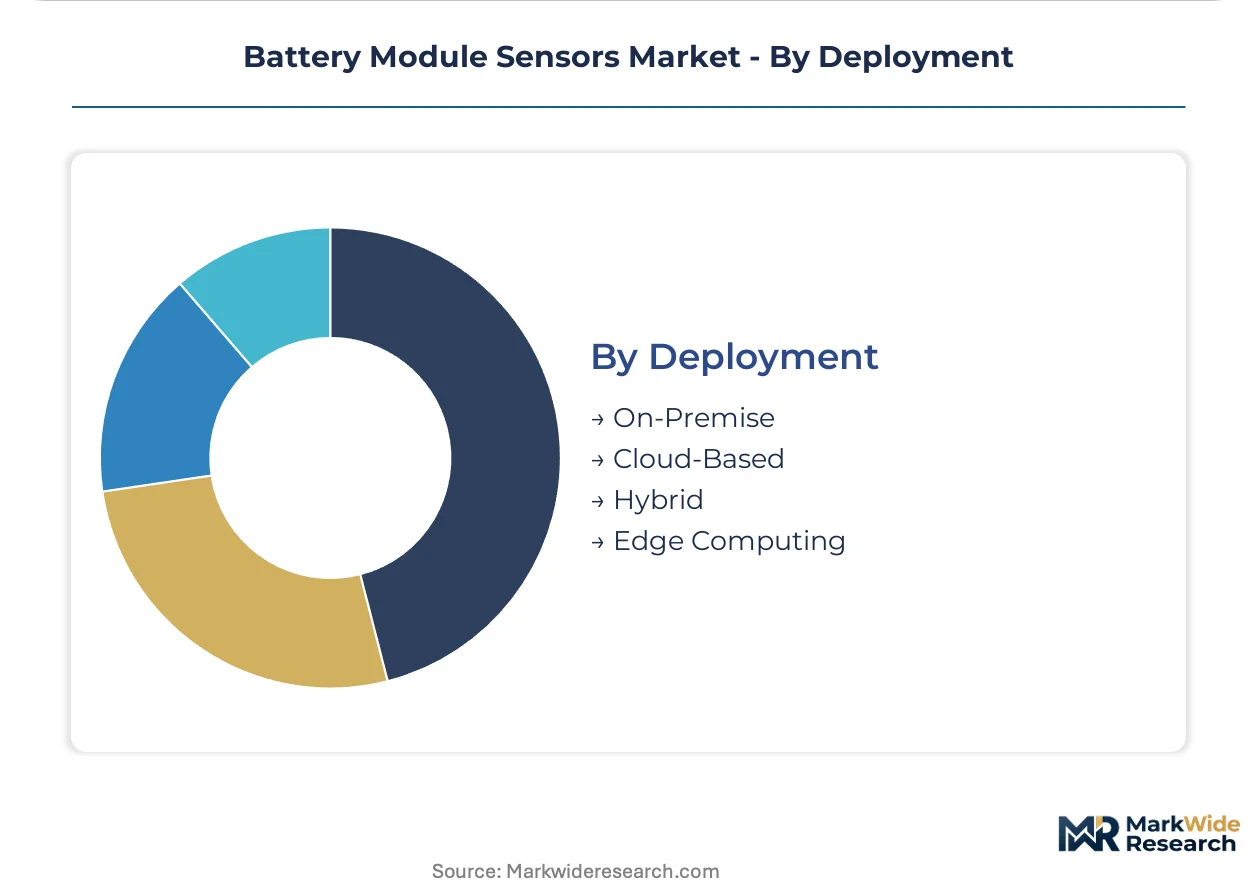
Deployment:
Customer type preferences split between real-time edge processing and centralized analytics.
- Edge Computing:Localized processing reduces latency for thermal runaway intervention. EV manufacturers embed these architectures directly into battery management systems to meet NHTSA failure-reporting thresholds.
- Cloud-Based:Centralized telemetry aggregation supports fleet-wide degradation modeling. Energy storage developers favor this for second-life battery monitoring across dispersed installations.
- Hybrid:Tiered processing with local alerts and cloud analytics.
- On-Premise:Air-gapped systems for sensitive industrial environments.
Edge Computing dominates new EV platforms. Cloud-Based deployment is gaining share fastest in stationary storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling battery module sensor production toward jurisdictions with calibrated compliance costs. Germany and China maintain the steepest technical mandates, while India and Southeast Asia offer assembly cost advantages for less certification-intensive specifications.
Germany
EU Battery Regulation traceability mandates and REACH compliance are forcing embedded cell-level monitoring across Stuttgart and Munich engineering corridors. The KBA enforces uniform thermal monitoring density for domestic EV platforms. Bosch and Continental anchor sensor R&D clusters in Baden-Württemberg, calibrating platinum-group thermistors for 800-volt architectures.
China
GB/T standards now mandate uniform sensor placement density across NEV battery packs, eliminating assembler discretion in thermal topology. MIIT oversees compliance timelines that force foreign suppliers to redesign packaging for Chinese-specific cell form factors. Yangtze River Delta pack assemblers are qualifying second-source local vendors to meet accelerated certification schedules.
United States
NHTSA and EPA joint failure-reporting thresholds are elevating granular module-level telemetry requirements for Detroit and Austin EV manufacturing hubs. The Inflation Reduction Act's domestic content provisions are reshaping procurement patterns for automotive-grade sensing arrays. Michigan and California engineering centers are adapting ASIL-D certification workflows for next-generation lithium-ion monitoring.
India
PLI scheme incentives for NEV manufacturing are creating fresh demand for localized sensor calibration infrastructure across Tamil Nadu and Gujarat battery assembly corridors. The Bureau of Indian Standards is developing harmonized testing protocols for imported sensing elements. Domestic pack integrators in Pune and Chennai are building captive testing capacity to reduce certification cycle times.
South Korea
MEMS foundry concentration in Gyeonggi and Chungnam provinces supplies automotive-grade pressure and gas sensing elements to global tier-one assemblers. MFDS oversees quality frameworks for exported components. Seoul-based engineering houses are expanding wireless telemetry R&D to capture OEM demand for harness-weight reduction in 800-volt platforms.
Battery Module Sensors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless telemetry and solid-state battery monitoring architectures. The vendor base clusters around three strategic archetypes: diversified automotive electronics conglomerates with captive MEMS fabrication, specialized sensing element suppliers with ASIL-D certification depth, and semiconductor firms leveraging functional safety IP. Competitive moves center on backward integration into MEMS foundry capacity and strategic partnerships with solid-state battery developers to secure specification windows before designs lock.
Among Germany-based diversified suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated archetype, combining Stuttgart engineering density with in-house calibration infrastructure. NXP Semiconductors represents the semiconductor-centric positioning, leveraging automotive-grade functional safety certification to anchor premium-tier procurement decisions. These three entities collectively illustrate how geographic proximity to OEM engineering centers and regulatory expertise are consolidating competitive position in a compliance-intensive segment.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| NXP Semiconductors |
| Texas Instruments |
| Infineon Technologies |
| TE Connectivity |
| DENSO Corporation |
| Analog Devices |
| Sensata Technologies |
| Others |
Pricing and Supply Chain Analysis
Captive MEMS fabrication in Taiwan and South Korea anchors both supply security and pricing power for tier-one sensor suppliers serving European and Chinese EV platforms. Bosch and Continental leverage in-house calibration infrastructure to command premium positioning against fabless competitors dependent on foundry spot pricing.
Pricing Analysis
Distributor margins compress ASIL-D certified sensor pricing by 12-18 points before reaching automotive OEM procurement desks. Three-tier pricing structure across premium, standard, and economy levels separates platinum-group thermistor assemblies from ceramic NTC alternatives and commodity Hall-effect designs. Cost compression in the economy tier intensifies because Chinese pack assemblers qualify second-source local vendors under GB/T compliance timelines. Fleet operators and utility-scale storage developers show least price sensitivity given uptime guarantee requirements, while consumer electronics battery module buyers drive spot-market volatility.
Supply Chain Analysis
Dual-sourcing requirements from German OEMs and Chinese NEV manufacturers force tier-one pack assemblers to qualify redundant sensor vendors across each specification window. Foundry capacity for automotive-grade MEMS concentrates in Taiwan, South Korea, and Japan, while platinum-group metal feedstocks draw from South African and Russian mining output. Single-source vulnerability runs through Taiwan Strait logistics chokepoints connecting MEMS wafer output to Stuttgart and Shanghai assembly corridors. Distribution runs through authorized distributor networks serving tier-one battery pack integrators with direct OEM qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Thermal runaway prevention mandates under EU Battery Regulation and China's GB standards are forcing demand-shift toward ASIL-D certified sensor specifications with embedded traceability.
For Market Incumbents: Hedge MEMS foundry exposure by qualifying secondary wafer sources in Japan and Southeast Asia before Taiwan Strait disruption scenarios materialize. Lock long-term offtake agreements with platinum-group metal suppliers to defend margin position against South African mining volatility. Reinforce calibration infrastructure in Stuttgart and Shanghai engineering corridors to maintain specification-setting authority as solid-state battery architectures open new design windows.
For New Entrants and Emerging Players: Capture second-life battery monitoring retrofit kits for stationary storage repurposing of retired EV modules, where incumbent service contracts have not yet penetrated. Target India's Tamil Nadu and Gujarat battery assembly corridors under PLI scheme incentives, where localized calibration infrastructure remains underdeveloped. Lead with wireless telemetry architectures to bypass incumbent harness-integration expertise and reduce customer switching costs.
For Investors and Strategic Acquirers: Roll-up economics work for specialized sensing element suppliers with ASIL-D certification depth because automotive OEM procurement committees prioritize pre-qualified vendor lists over price competition in thermal runaway-critical applications. Five-to-ten year viability hinges on solid-state battery specification capture before designs lock. Watch for MIIT acceleration of GB/T compliance timelines as the inflection indicator signaling Chinese market access tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Taiwan and South Korea foundry additions reduce single-source exposure for automotive-grade pressure sensing elements. |
| ASIL-D Certification Investment | ISO 26262 functional safety qualification opens procurement access to German OEM platform engineering teams. |
| Wireless Telemetry Platform Launch | RF-based sensor networks eliminate wiring harness weight for 800-volt architectures in Stuttgart and Shanghai. |
| Platinum-Group Metal Supply Agreement | Long-term offtake contracts with South African miners stabilize thermistor input costs against spot volatility. |
| Solid-State Battery Partnership | Early specification engagement with next-generation cell developers secures thermal monitoring architecture windows. |
Research Methodology
Coverage spans Germany, China, the United States, India, and South Korea, with primary inputs from each market cluster. The analysis combines structured interviews with battery pack procurement managers, OEM platform engineers, MEMS foundry operations directors, and tier-one supplier quality assurance leads with secondary validation. Regulatory filings from KBA, MIIT, NHTSA, and BIS anchor compliance timeline assessments. Vehicle production databases, customs trade records, and semiconductor capex disclosures support volume and value triangulation through bottom-up sensor unit estimates and top-down battery pack production forecasts.
Granularity-level modeling disaggregates the analysis window across product type, technology, end user, and deployment architecture dimensions. Automotive propulsion architecture splits further by voltage class and cell form factor to capture 800-volt platform sensor content differentiation. CAGRs derive from segmented volume trajectories weighted by regional production mix and certification tier pricing. Solid-state battery transition timelines and wireless telemetry adoption curves constitute industry-specific forecast inputs.
Platinum-group metal price shocks, Taiwan Strait logistics disruption, and MIIT acceleration of GB/T compliance deadlines are the dominant revision risks to the projection horizon. Deviation in any trigger would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Thermistor Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Seismic Monitoring Equipment Market