
 Power Supply and Charger Market | 2026-2036
Power Supply and Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Power Supply and Charger Market Analytics
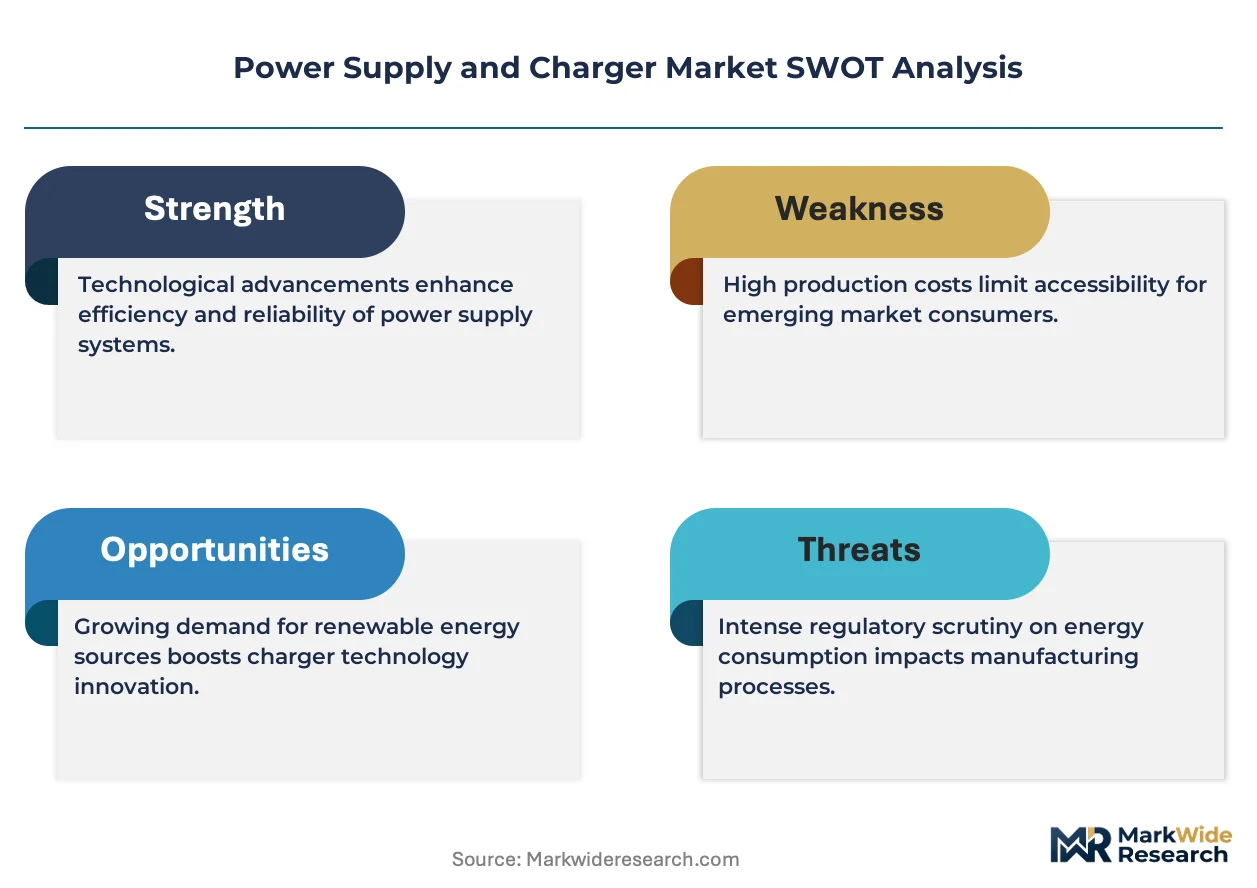
The capital-intensity divergence between integrated semiconductor fabricators and outsourced power assembly houses is bifurcating competitive returns across the industry. Delta Electronics leverages captive MOSFET sourcing and in-house magnetic component production to sustain margin control across industrial tiers. MEAN WELL Enterprises anchors its position through dedicated DIN-rail and LED driver specialization, while Phoenix Contact competes via ruggedized terminal-block-integrated supply designs for factory automation.
Power supply and charger equipment comprises electrical conversion and conditioning apparatus that transforms grid or stored energy into stable DC or AC output at specified voltage, current, and ripple parameters for downstream device operation. Switching-mode topologies dominate volume production due to efficiency advantages above 85 percent and reduced ferrite core mass compared to linear alternatives. AC/DC wall adapters and USB-C PD modules capture expanding consumer electronics attachment, while resonant and magnetic technologies occupy premium niches in telecom base stations and medical-grade isolation applications where thermal density constraints apply.
The EU Ecodesign Directive and USB-C harmonization mandate from the European Commission constrain standby power draw and connector interoperability, forcing redesign cycles across OEM portfolios. China's GB standards and NMPA certification requirements for medical power supplies create parallel compliance tracks for exporters. India's BIS compulsory registration order for electronics adds a third regulatory gate. Stakeholders must monitor harmonization gaps between regional efficiency tiers to avoid stranded inventory or duplicate certification spend.
Market Dynamics
Silicon carbide MOSFET adoption is compressing switching losses and thermal budgets, forcing incumbent silicon-based supply chains into accelerated redesign cycles across industrial and automotive tiers.
Growth Catalysts
- EU Ecodesign Directive:Standby power limits below 0.5 watts for external power supplies are mandating topology upgrades and eliminating linear transformer architectures from EU-bound portfolios.
- Electric vehicle fleet electrification:Commercial operators in logistics and public transit are specifying onboard chargers above 11 kW, pulling high-voltage DC/DC converter demand through OEM supply agreements.
- GaN-on-silicon epitaxy maturation:Foundry capacity expansion at TSMC and X-FAB is reducing cost premiums for high-frequency switching applications below 100W.
Market Restraints
- Rare earth magnet dependency:Neodymium and dysprosium price volatility from Chinese export quota adjustments directly impacts ferrite core and inductor input costs.
- Single-source semiconductor concentration:High-voltage superjunction MOSFET fabrication remains concentrated among three IDM houses, creating allocation risk during capacity tightness.
- Electrolytic capacitor lifespan limits:Aluminum electrolytic technology caps reliable operation at 10,000-15,000 hours at rated temperature, constraining maintenance-free designs for remote infrastructure.
Strategic Opportunities
- India BIS compulsory registration:Local testing infrastructure expansion creates first-mover advantage for certified suppliers targeting smartphone charger and IT adapter replacement cycles.
- Wireless power transfer convergence:Qi2 magnetic alignment standard integration with USB-C PD controllers opens unified accessory ecosystems for automotive and furniture embedding.
- Medical isolation grade expansion:2xMOPP (means of patient protection) certification for home healthcare devices addresses aging demographics in Japan and Germany.
Industry Challenges
- Magnetics design talent scarcity:Finite element simulation expertise for planar transformer optimization resides with a narrow cohort of senior engineers approaching retirement.
- Multi-jurisdiction certification stacking:Simultaneous UL, TÜV, and CCC timelines for a single SKU extend time-to-revenue by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Supply and Charger Market |
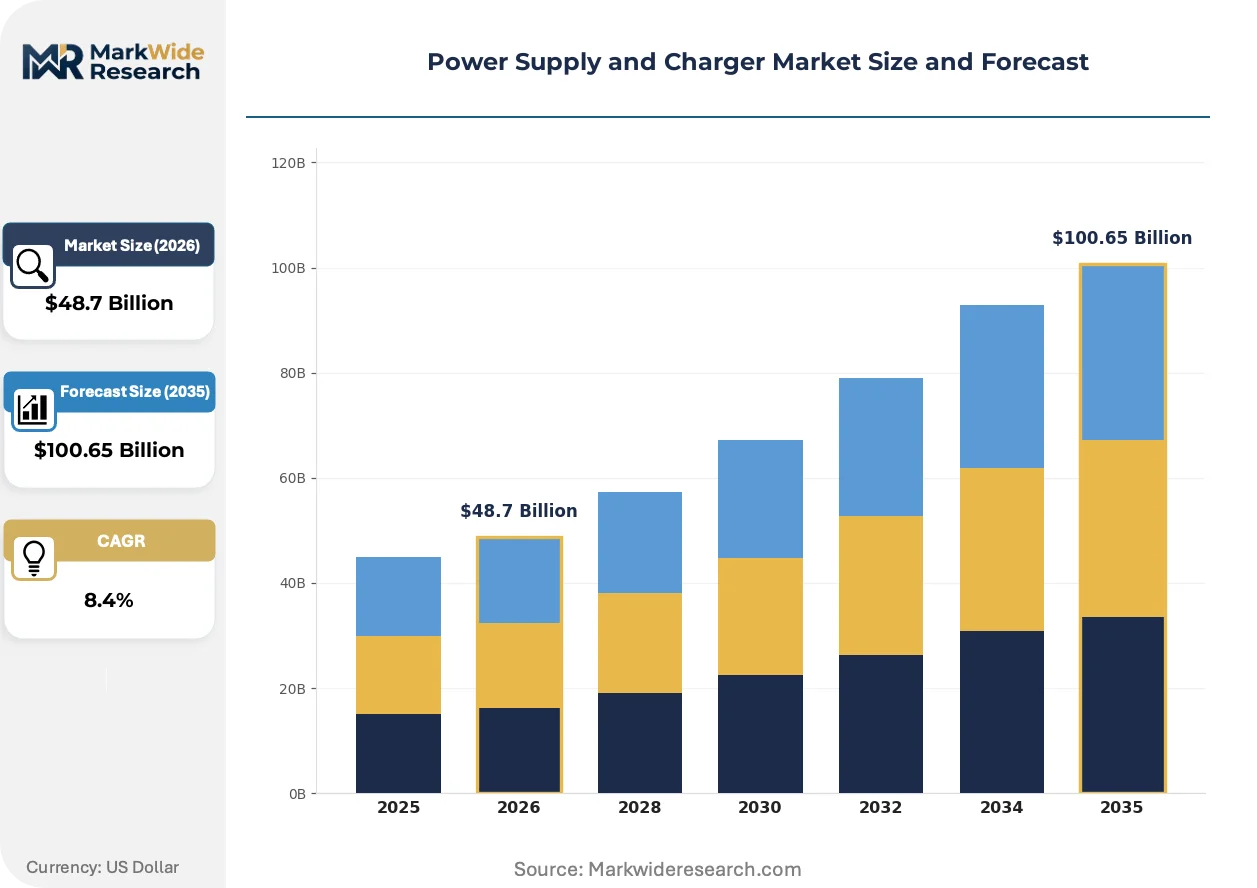
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: AC/DC, USB-C, Quick Charge, Wireless Application: Consumer Electronics, Automotive, Industrial Equipment, Telecom Technology: Switching, Linear, Resonant, Magnetic End User: Retail, OEMs, Distributors, Aftermarket Providers |
| Companies Covered | Delta Electronics, Schneider Electric, Siemens, ABB, TDK Corporation, MEAN WELL Enterprises, Emerson Electric, Phoenix Contact, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Supply and Charger Market Evolving Landscape
Topology innovation and wide-bandgap semiconductor maturation are redrawing efficiency frontiers while regulatory mandates force interoperability standardization across connector and standby power domains.
Resonant LLC and active-clamp flyback architectures are fragmenting the mid-power adapter landscape below 300W. Consumer electronics OEMs are adopting these topologies for gaming laptops and high-end smartphones. The shift is fragmenting procurement patterns as tier-one brands bypass legacy ODMs lacking magnetics simulation capabilities.
The EU USB-C harmonization mandate under the Radio Equipment Directive is eliminating proprietary fast-charging connectors from smartphones, tablets, and cameras by 2024. Manufacturers must redesign power delivery controllers and cable assemblies to meet 100W minimum capability. Southeast Asian contract manufacturers are absorbing the largest compliance burden as EU-bound production shifts from legacy micro-USB inventories.
Fleet operators are consolidating supplier relationships around lifecycle cost metrics rather than unit pricing. Data center and telecom infrastructure buyers now specify 10-year mean time between failures guarantees with penalty clauses. This behavioral pivot is most pronounced in Germany and the Netherlands, where energy-as-a-service contracts bundle power supply maintenance with renewable generation assets.
Power Supply and Charger Market Segmentation
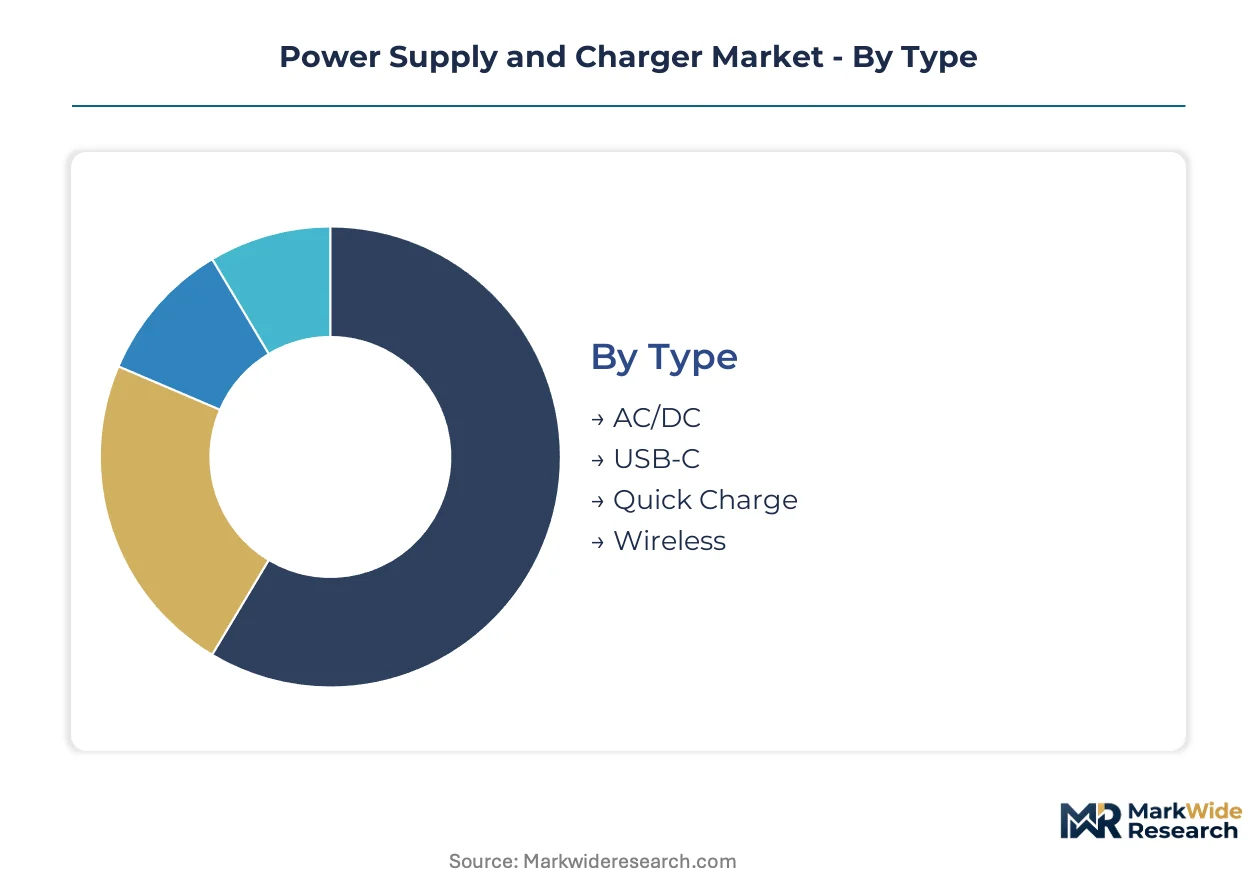
Power supply and charger segmentation reveals how topology choices, connector standards, and thermal architectures fragment procurement patterns across end-use verticals. Substitution pressure from wide-bandgap semiconductors and harmonized connector mandates is compressing legacy segment margins while elevating premium tiers.
Type:
USB-C and wireless formats are displacing proprietary connectors fastest, forcing AC/DC and Quick Charge incumbents into defensive redesign cycles.
- AC/DC:Wall-mounted and desktop adapters using flyback or forward converter topologies dominate legacy IT and small appliance attachment. Demand concentrates in India's BIS-registered aftermarket channels as smartphone penetration drives replacement cycles. Efficiency regulations from the EU Ecodesign Directive are eliminating linear transformer variants from export-bound portfolios.
- USB-C:Power Delivery controllers supporting 100W+ profiles with programmable voltage rails are capturing laptop and tablet procurement. Fleet operators in Germany and the Netherlands specify USB-C PD for unified cable ecosystems across mobile workstations. The EU Radio Equipment Directive harmonization mandate is accelerating OEM transitions from micro-USB by eliminating proprietary fast-charging connectors.
- Quick Charge:Qualcomm-licensed protocols with variable voltage negotiation remain entrenched in mid-tier smartphone ODM supply chains.
- Wireless:Qi2 magnetic alignment coils integrated with furniture and automotive surfaces address convenience-driven consumer segments.
AC/DC anchors the volume base while USB-C gains share at the steepest rate.
Application:
Automotive and industrial specifications are diverging from consumer electronics on thermal density and reliability metrics, fragmenting supplier qualification requirements.
- Consumer Electronics:Smartphone, tablet, and wearable adapters below 65W prioritize miniaturization and GaN-on-silicon integration. Procurement concentrates in China's Guangdong province contract manufacturers serving Apple, Samsung, and Xiaomi ecosystems. The EU USB-C mandate is forcing redesign of legacy micro-USB inventories ahead of regulatory deadlines.
- Automotive:Onboard chargers above 11 kW and DC/DC converters for electric vehicle powertrains specify AEC-Q100 qualified components. Logistics fleet operators in California and the Netherlands are consolidating supplier relationships around lifecycle cost metrics with 10-year mean time between failures guarantees.
- Industrial Equipment:DIN-rail supplies and motor drives require IP65 ingress protection and extended temperature operation.
- Telecom:Base station rectifiers and backup power systems demand N+1 redundancy with hot-swappable module architectures.
Consumer electronics maintains the broadest supplier base while automotive climbs fastest on electrification pull-through.
Technology:
Silicon carbide and GaN devices are compressing switching losses, concentrating growth in resonant and switching architectures while linear alternatives retreat to cost-sensitive niches.
- Switching:PWM-controlled MOSFET or IGBT topologies above 85% efficiency dominate volume production across adapter and industrial tiers. China's GB standards and India's BIS registration are creating parallel compliance tracks for exporters targeting Asian replacement markets. GaN-on-silicon foundry expansion at TSMC is reducing cost premiums below 100W.
- Resonant:LLC and ZVS architectures eliminate switching losses in telecom base stations and medical-grade isolation applications where thermal density constraints apply. Japanese and German healthcare device manufacturers specify 2xMOPP certification for home monitoring equipment addressing aging demographics.
- Linear:Transformer-based supplies with minimal ripple persist in audiophile and laboratory instrumentation segments.
- Magnetic:Inductive and resonant coupling for wireless power transfer enables sealed, connector-free designs.
Switching technology commands the installed base while resonant architectures expand most quickly in premium thermal-constrained applications.
End User:
OEM direct procurement is consolidating around captive magnetics and semiconductor sourcing, squeezing distributor and aftermarket margins on standard products.
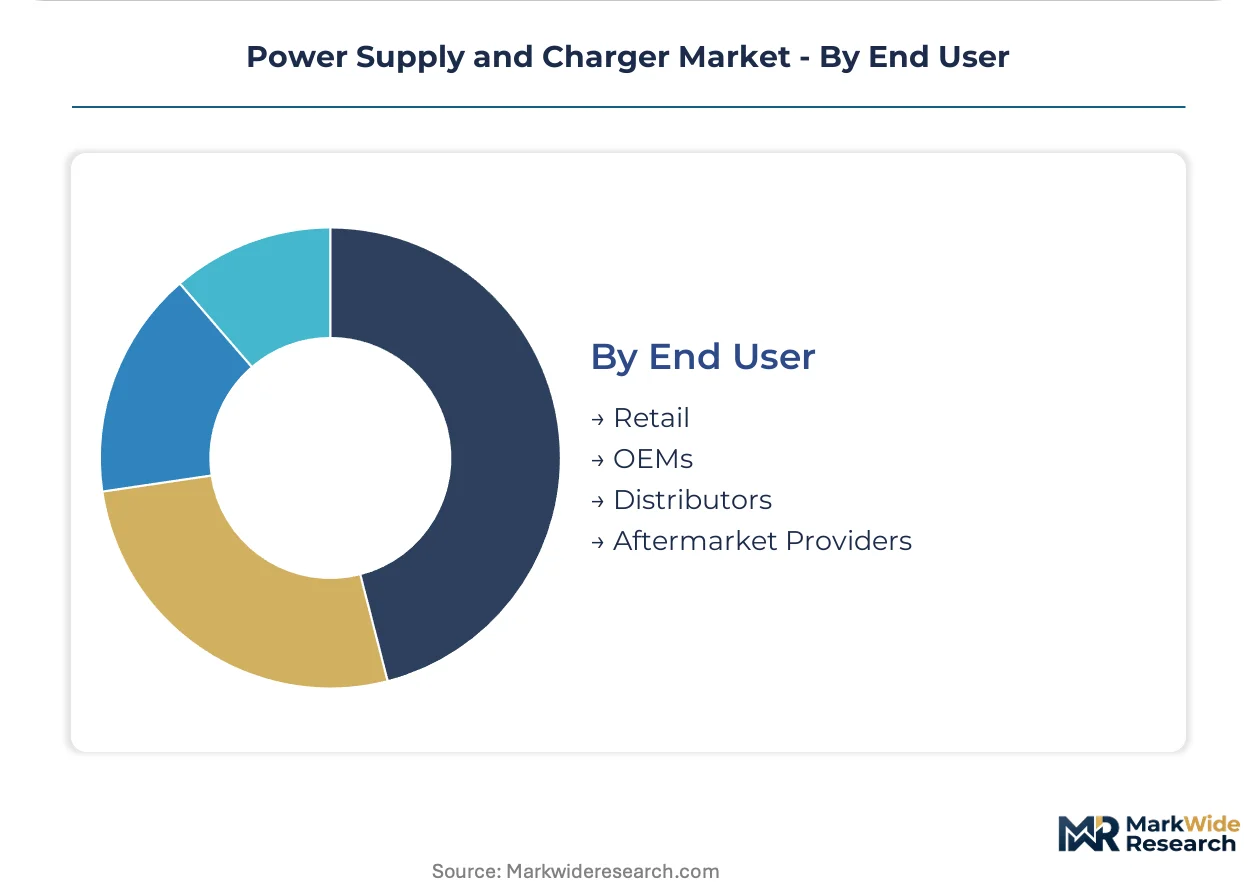
- OEMs:Tier-one electronics and automotive manufacturers specify custom power modules with integrated magnetic components and firmware-programmable output profiles. Delta Electronics leverages captive MOSFET sourcing to sustain margin control across industrial tiers. Multi-jurisdiction certification stacking extends time-to-revenue by 8-14 months for new SKU introductions.
- Distributors:Arrow, Avnet, and regional catalog houses stock standard DIN-rail and LED driver portfolios for maintenance and small-batch industrial procurement. MEAN WELL Enterprises anchors position through dedicated specialization and rapid fulfillment from Taiwan and China distribution centers.
- Retail:Consumer electronics aftermarket channels in India and Southeast Asia absorb compliance burden for BIS-registered smartphone chargers.
- Aftermarket Providers:Independent service organizations for telecom and data center infrastructure specify refurbished or third-party compatible modules.
OEMs anchor procurement value while distributors defend position through standard product availability and technical support services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: fleet operators in Germany and the Netherlands prioritize lifecycle cost guarantees, while India's aftermarket channels absorb compliance burdens for smartphone charger replacement cycles. China's contract manufacturers drive volume through Guangdong province clustering.
China
Electric vehicle fleet electrification and consumer electronics manufacturing anchor demand. GB standards from SAMR and NMPA certification requirements create parallel compliance tracks for medical power supply exporters. Contract manufacturers cluster around Shenzhen's electronics corridor, serving Apple, Samsung, and Xiaomi ecosystems with high-volume adapter production.
Germany
Data center infrastructure buyers and automotive OEMs specify 10-year mean time between failures guarantees with penalty clauses. The EU Ecodesign Directive and REACH regulations mandate standby power limits below 0.5 watts. Industrial automation corridors in Bavaria and Baden-Württemberg drive demand for ruggedized DIN-rail supplies.
United States
Logistics fleet operators in California specify onboard chargers above 11 kW with lifecycle cost metrics. FCC and EPA regulations constrain electromagnetic interference and standby power draw. The Pacific Northwest and Texas host data center expansions pulling high-efficiency rectifier demand through utility-scale procurement.
India
Smartphone penetration drives replacement cycle demand through BIS-registered aftermarket channels. The BIS compulsory registration order for electronics adds regulatory gates for smartphone charger and IT adapter imports. Manufacturing concentrates in Maharashtra and Tamil Nadu as contract manufacturers absorb EU-bound compliance burdens from legacy micro-USB inventories.
Japan
Aging demographics drive home healthcare device demand requiring 2xMOPP medical isolation certification. METI efficiency standards and JIS specifications constrain product design parameters. Kanto and Kansai regions host precision magnetics fabrication for planar transformer optimization serving telecom and medical tiers.
Power Supply and Charger Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor sourcing and in-house magnetic production separating margin performance. The vendor base spans three strategic archetypes: diversified industrial conglomerates with captive component arms, pure-play power specialists with dedicated topology expertise, and regional contract manufacturers serving branded OEMs. Competitive moves concentrate on foundry partnerships for wide-bandgap semiconductor access and magnetics simulation capability acquisition.
Within the integrated tier, Delta Electronics and Schneider Electric exemplify archetypes combining captive MOSFET sourcing with multi-jurisdiction certification infrastructure. MEAN WELL Enterprises occupies a position among dedicated power specialists, anchoring distribution-centric positioning through Taiwan and China fulfillment networks.
| Leading Market Players |
|---|
| Delta Electronics |
| Schneider Electric |
| Siemens |
| ABB |
| TDK Corporation |
| MEAN WELL Enterprises |
| Emerson Electric |
| Phoenix Contact |
| General Electric |
| Others |
Value Network & Pricing Analysis
GaN-on-silicon epitaxy maturation is displacing silicon MOSFET cost structures while simultaneously pulling foundry capacity toward Taiwan and reshaping procurement economics for sub-100W adapter tiers. This substitution dynamic compresses bill-of-materials differentials between premium and standard product lines, forcing contract manufacturers in Guangdong province to absorb margin compression or accelerate captive GaN sourcing.
Pricing Analysis
After-sales service contracts and extended warranty bundles now drive lifetime value capture for industrial and automotive power supply tiers. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 certified automotive modules from consumer-grade adapters, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from rare earth magnet volatility and foundry allocation tightness for high-voltage superjunction MOSFETs. Fleet operators in Germany and the Netherlands exhibit lowest price sensitivity due to lifecycle cost contracting, while Indian aftermarket smartphone charger channels face acute margin compression from BIS compliance overhead.
Supply Chain Analysis
China and Taiwan anchor ferrite core fabrication and power semiconductor packaging, with South Korea contributing high-purity silicon wafer supply. The supply chain draws from neodymium and dysprosium deposits subject to Chinese export quota adjustments, aluminum electrolytic capacitor foils, and epoxy molding compounds for semiconductor encapsulation. Single-source concentration for high-voltage superjunction MOSFET fabrication among three IDM houses creates allocation vulnerability during capacity tightness. Distribution runs through Arrow and Avnet for standard industrial portfolios, while OEM direct procurement dominates automotive and medical tiers with captive magnetics integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power supply and charger market functions as a defensive-moat arena where regulatory entrenchment through multi-jurisdiction certification stacking creates switching costs that lock in incumbent supplier relationships.
For Market Incumbents: Secure captive sourcing of wide-bandgap semiconductors through foundry partnerships at TSMC or X-FAB to defend against GaN cost compression eroding silicon-based margins. Expand in-house planar transformer simulation capabilities to address magnetics design talent scarcity approaching retirement cohorts. Reinforce certification infrastructure for simultaneous UL, TÜV, and CCC timelines to compress 8-14 month time-to-revenue windows. For New Entrants and Emerging Players: Differentiate on medical isolation grade specialization targeting 2xMOPP certification for home healthcare devices in Japan and Germany, where aging demographics outpace incumbent capacity expansion. Target India's BIS-registered aftermarket channels for smartphone charger replacement cycles, leveraging local testing infrastructure buildout as a compliance-first entry wedge. Pursue white-label partnerships with Southeast Asian contract manufacturers absorbing EU USB-C harmonization mandate redesign burdens. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed power electronics specialists holding stranded micro-USB inventories and legacy linear transformer capabilities requiring topology overhaul. Long-term viability over a 5-10 year horizon hinges on wide-bandgap semiconductor access and magnetics simulation talent retention. Watch GaN-on-silicon cost parity milestones below 65W as the inflection signal for commoditization acceleration in consumer adapter tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for Wide-Bandgap Access | TSMC GaN-on-silicon capacity locks in cost-competitive positioning for sub-100W adapter tiers. |
| Magnetics Simulation Capability Acquisition | Planar transformer optimization expertise addresses finite element talent scarcity in aging engineer cohorts. |
| Multi-Jurisdiction Certification Infrastructure | Simultaneous UL, TÜV, and CCC pipelines compress 8-14 month SKU introduction timelines for OEM direct procurement. |
| Medical Isolation Grade Expansion | 2xMOPP certification captures home healthcare device demand from Japan and Germany aging demographics. |
| Wireless Power Transfer Controller Integration | Qi2 magnetic alignment with USB-C PD enables unified automotive and furniture embedding ecosystems. |
Research Methodology
Desk research of SEC 10-K filings, customs trade databases, and IEC standard documentation preceded structured interviews with power supply procurement managers at data center operators, magnetics design engineers at tier-one automotive suppliers, and regulatory affairs leads at medical device OEMs. Primary fieldwork with distribution channel partners at Arrow and Avnet validated secondary estimates of DIN-rail and LED driver inventory turns. Bottom-up unit shipment modeling across adapter, industrial, and automotive tiers was cross-checked against top-down semiconductor wafer consumption data from foundry disclosures.
Variance decomposition across the projection horizon isolates volume drivers by application segment, technology substitution rates, and regional regulatory enforcement intensity. The analytical framework models switching versus resonant topology adoption, USB-C PD penetration by wattage tier, and fleet electrification pull-through for onboard chargers. CAGRs were derived from segment-level unit economics and input cost trajectory assumptions, with GaN-on-silicon foundry expansion curves and rare earth magnet price volatility as key sensitivity inputs.
Material uncertainties — Chinese export quota adjustments for rare earth elements, foundry allocation tightness for high-voltage superjunction MOSFETs, and harmonization gaps between EU Ecodesign tiers and India's BIS efficiency standards — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding wide-bandgap semiconductor cost reduction curves and regulatory deadline adherence. Recalibration cycles align with material shifts in foundry capacity announcements, export policy changes, and harmonized standard adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Chip Power Inductor Market
Power Systems
Global Flexible Batteries Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Voltage Regulators Market
Power Systems
Shunt Reactor Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Battery Balancer Market
Power Systems
Thermal Management Systems Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Global Inverter Market